
 Clothing Recycling Market | 2026-2036
Clothing Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Clothing Recycling Market Analysis
Buyer concentration among large apparel retailers is hardening as Zara, H&M, and Inditex-scale buyers mandate recycled content quotas across supplier networks. Lenzing AG leverages its TENCEL Lyocell technology to anchor premium fiber supply from post-consumer cotton waste. Unifi Inc. sustains geographic dominance through its REPREVE platform, converting plastic bottles and textile scrap into performance yarns. Renewcell specializes in chemical recycling, operating one of Europe's few commercial-scale textile pulp facilities.
Clothing recycling encompasses the collection, sorting, and reprocessing of post-consumer and post-industrial garments into reusable fibers, yarns, or raw chemical inputs through mechanical shredding, chemical depolymerization, or thermomechanical methods. Mechanical recycling preserves fiber length but degrades quality through repeated processing, while chemical routes break polymers into virgin-equivalent monomers suitable for high-grade textile applications. Chemical recycling currently occupies the fastest-expanding margin pool as brands seek fiber quality indistinguishable from virgin material. Mechanical recycling dominates volume throughput due to lower capital requirements and established sorting infrastructure. End-user concentration among retailers is deepening as take-back programs and resale platforms integrate directly with supply chains.
The EU Green Deal and REACH frameworks mandate extended producer responsibility for textile waste across member states, forcing brands to fund collection and recycling infrastructure or face market exclusion. The EPA and state-level waste hierarchies in California and New York impose landfill diversion targets that accelerate domestic sorting investments. China's MEE dual carbon goals and GB standards for recycled textile labeling reshape export compliance requirements for international suppliers. Stakeholders must monitor regulatory fragmentation between chemical recycling approval pathways in Europe and emerging state-level mandates in the United States.
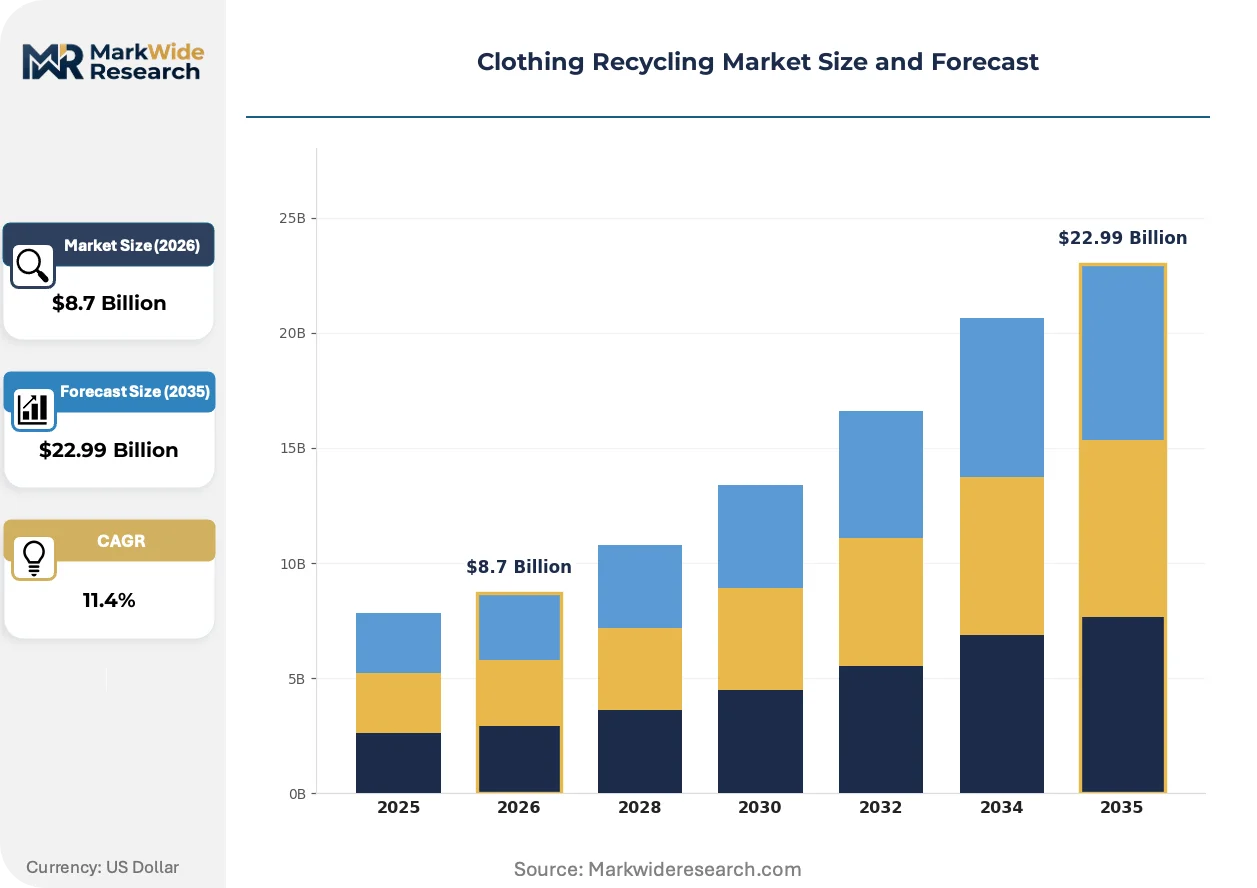
Market Dynamics
EU Green Deal mandates on extended producer responsibility are forcing apparel brands to internalize textile waste collection costs, fundamentally restructuring supplier economics across European supply chains.
Growth Catalysts
- REACH textile waste frameworks:Extended producer responsibility obligations in Europe mandate brand-funded recycling infrastructure, accelerating capital deployment into chemical recycling pilot facilities.
- Mechanical shredding scale-up:Established sorting infrastructure in Germany enables volume throughput that chemical processes cannot yet match, anchoring near-term fiber supply security.
- Post-industrial garment streams:Factory offcuts and production scrap provide consistent feedstock quality that reduces contamination risk versus post-consumer collection systems.
Market Restraints
- Cotton price volatility:Virgin cotton futures fluctuations compress recycled fiber premium tolerance, limiting margin expansion for mechanical recyclers dependent on cost parity positioning.
- Sorting infrastructure concentration:Automated fiber identification and separation capacity clusters in Germany and the Netherlands, creating feedstock access bottlenecks for peripheral European processors.
- Polymer degradation limits:Mechanical recycling shortens cotton fiber length through repeated processing, capping quality at mid-tier apparel applications and excluding premium fashion segments.
Strategic Opportunities
- Spain's underdeveloped collection networks:Southern European markets lack integrated take-back infrastructure, creating first-mover advantage for brands establishing direct consumer garment recovery systems.
- Chemical depolymerization convergence:Integration of enzymatic hydrolysis with conventional solvent-based methods promises quality parity with virgin viscose for luxury textile applications.
- Resale platform channel integration:ThredUp and Vinted logistics networks now feed unsold inventory directly into fiber recovery streams, bypassing traditional municipal waste intermediaries.
Industry Challenges
- Fiber identification automation:Near-infrared spectroscopy technicians and AI-trained sorting engineers remain scarce, slowing facility commissioning timelines across new plant deployments.
- Multi-fiber blend separation:Elastane-cotton-polyester combinations in athleisure garments resist mechanical and chemical separation, requiring pre-processing capex that strains project returns.
- Recycled content certification lag:GRS and RCS audit backlogs extend supplier qualification timelines, delaying contract execution for brands with mandatory recycled fiber quotas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothing Recycling Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Mechanical, Chemical, Textile-to-Textile, Upcycling End User: Retailers, NGOs, Manufacturers, Consumers Material Type: Cotton, Polyester, Wool, Blends Collection Method: Drop-off Centers, Pickup Services, Events, Textile Banks |
| Companies Covered | Lenzing AG, Birla Cellulose, Unifi Inc., Worn Again Technologies, HYOSUNG TNC, Renewcell, The Woolmark Company, The Boer Group, Martex Fibre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothing Recycling Market Emerging Trajectories
Technology convergence between chemical recycling and synthetic biology is compressing the cost-quality trade-off that has historically limited recycled fiber penetration in premium apparel segments.
Enzymatic textile depolymerization is electrifying competitive dynamics in fiber recovery. The technology uses engineered cellulase enzymes to break cotton polymers into dissolvable pulp without the harsh solvents of conventional chemical recycling. Luxury fashion houses in Italy and France are piloting enzymatic outputs for virgin-equivalent viscose replacement. This biological pathway is electrifying margin structures by eliminating hazardous chemical handling costs and enabling smaller-scale distributed processing facilities.
EU Green Deal implementation timelines are tightening compliance windows for extended producer responsibility. Member states must transpose textile waste directives into national law, forcing brands to pre-fund collection infrastructure or face market exclusion. German and French regulators are moving fastest on enforcement, while Southern European implementation lags create temporary competitive asymmetries for brands with centralized EU supply chains.
Certification-driven procurement criteria are displacing price-primary supplier selection. Large apparel retailers now mandate GRS or RCS chain-of-custody documentation as a contract precondition, not a preference. This behavioral shift compresses supplier pools to pre-certified processors, concentrating order flow toward established recyclers with audit infrastructure. The pattern is most visible in German retail procurement, where sustainability compliance teams have gained veto authority over fiber sourcing decisions.
Clothing Recycling Market Segmentation
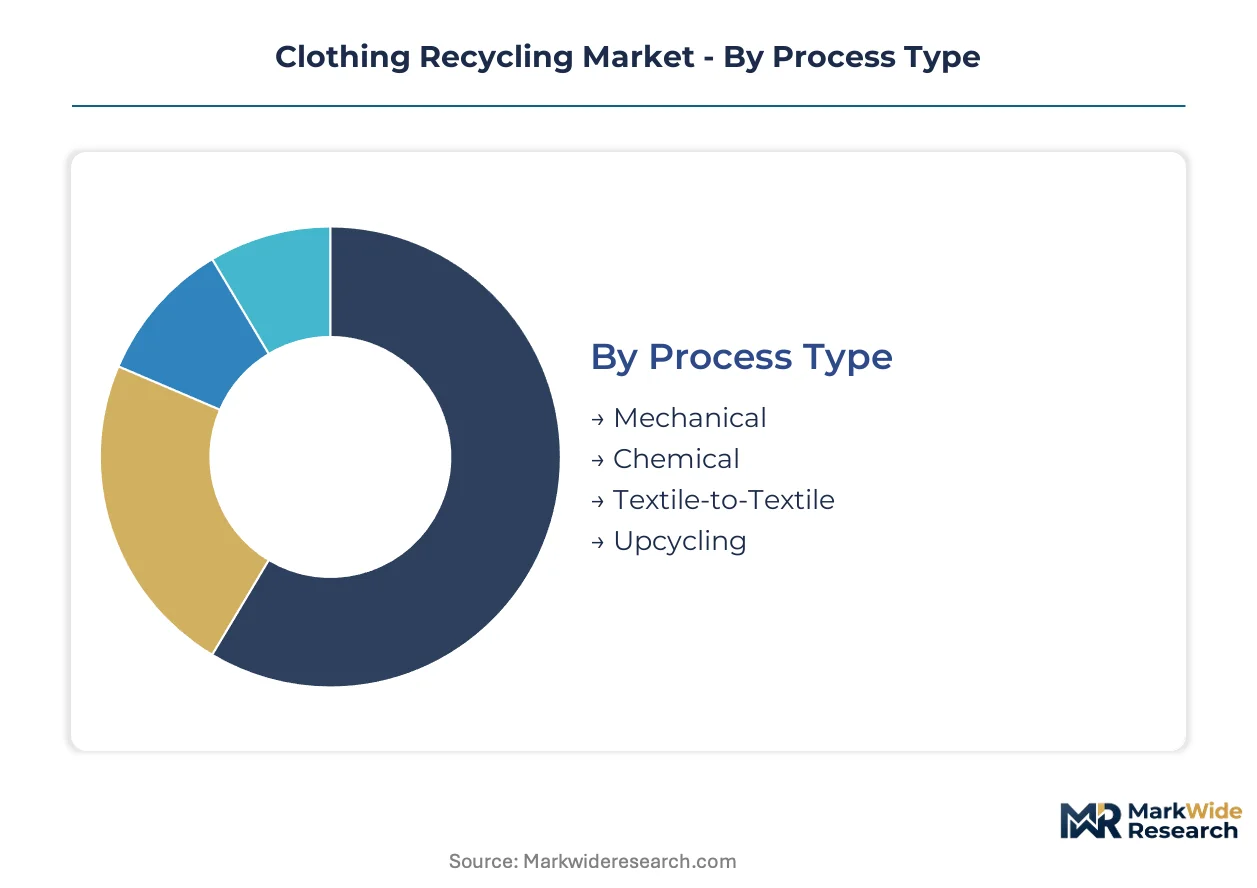
Segmentation in clothing recycling reveals how capital flows diverge between volume-driven mechanical operations and premium chemical recovery. Process economics, feedstock quality requirements, and brand compliance mandates create distinct competitive arenas that shape supplier positioning.
Process Type:
Mechanical processes dominate current throughput volumes while chemical routes capture expanding margin pools as fiber quality standards tighten.
- Mechanical:Shredding and re-spinning of post-consumer garments preserves fiber structure with minimal capital outlay. German sorting infrastructure anchors European supply security for mid-tier apparel brands facing EU Green Deal compliance deadlines.
- Chemical:Depolymerization breaks cotton and polyester polymers into virgin-equivalent monomers through solvent or enzymatic methods. Luxury fashion houses in France and Italy pilot enzymatic outputs for viscose replacement where fiber quality must match virgin standards.
- Textile-to-Textile:Closed-loop systems recover fibers for direct re-weaving into new garments without downcycling into industrial applications.
- Upcycling:Design-led transformation of intact garments into higher-value products bypasses fiber destruction entirely.
Today's leader: Mechanical. Tomorrow's challenger: Chemical.
End User:
Procurement authority is consolidating among large-scale retail buyers with mandatory recycled content quotas.
- Retailers:Zara, H&M, and Inditex-scale buyers mandate supplier network compliance with GRS and RCS certification. Their volume commitments determine which recycling technologies achieve commercial scale.
- NGOs:Collection infrastructure operators in Germany and the Netherlands manage municipal partnerships that feed automated sorting facilities.
- Manufacturers:Factory offcuts provide consistent post-industrial feedstock that reduces contamination risk versus post-consumer streams.
- Consumers:Take-back program participation rates vary sharply by geography, with Northern European markets showing highest return rates.
Retail procurement teams now hold veto authority over fiber sourcing decisions.
Material Type:
Feedstock composition dictates processing technology selection and end-market value recovery.
- Cotton:Cellulosic fibers suit both mechanical shredding and chemical depolymerization into dissolvable pulp. Enzymatic hydrolysis pilots target cotton-rich streams for luxury textile applications.
- Polyester:Thermoplastic properties enable melt-reprocessing with quality degradation that limits reprocessing cycles. Bottle-to-textile and textile-to-textile routes compete for the same feedstock pools.
- Wool:Premium natural fiber commands highest resale values through upcycling channels rather than mechanical recycling.
- Blends:Elastane-cotton-polyester combinations in athleisure resist separation technologies, requiring pre-processing capex that strains project economics.
Single-fiber streams concentrate investment; blended streams remain stranded.
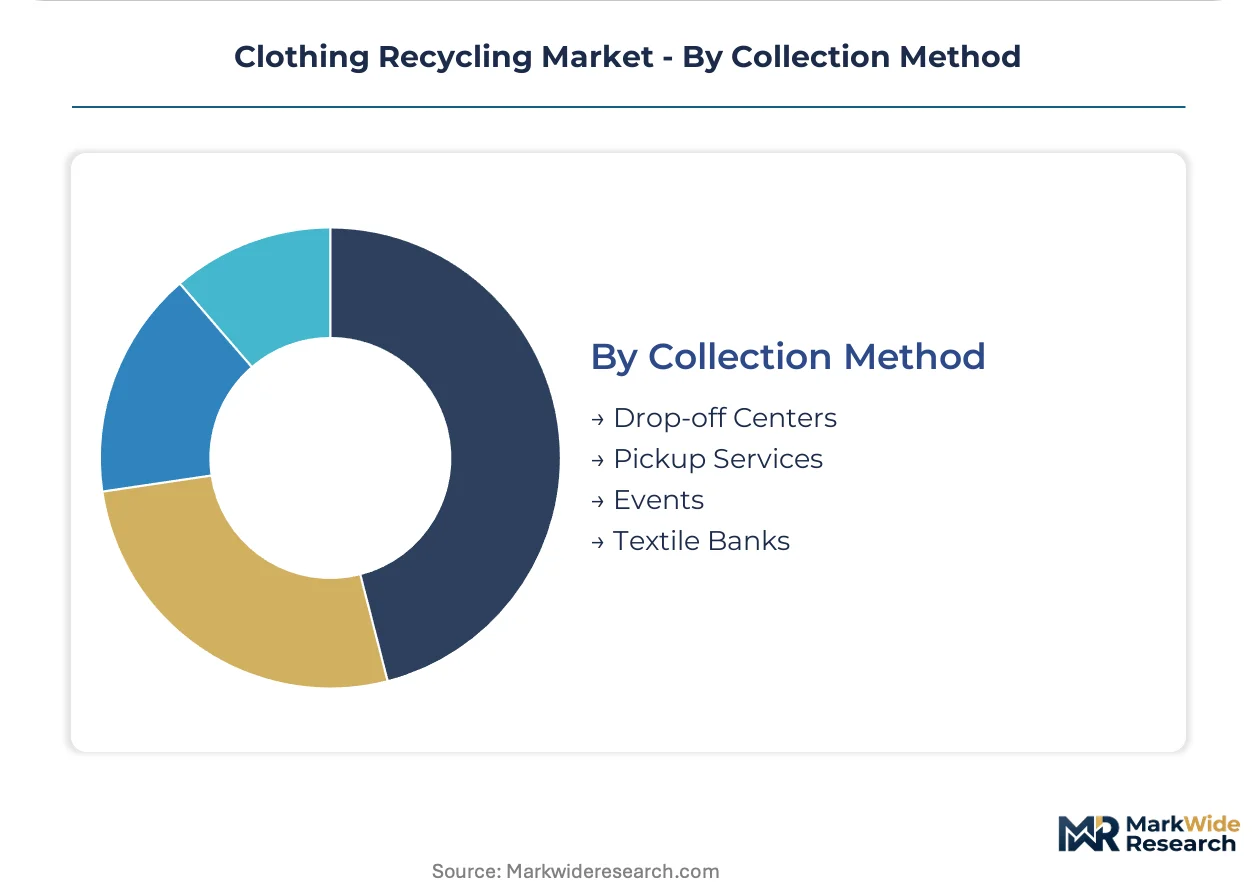
Collection Method:
Logistics configuration determines feedstock cost structure and contamination rates.
- Drop-off Centers:Municipal partnerships in Germany and the Netherlands anchor automated sorting capacity with predictable volume flows.
- Pickup Services:Direct-to-consumer collection models in urban France and Belgium reduce intermediaries but raise per-kilogram logistics costs.
- Events:Seasonal collection drives generate volume spikes that strain continuous-processing plant economics.
- Textile Banks:Unattended donation infrastructure dominates UK collection networks with lower labor costs but higher contamination incidence.
Integrated collection-sorting-recycling clusters outperform fragmented municipal systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled fiber sorting technicians and chemical process engineers concentrate in German industrial clusters, anchoring European recycling capacity. Their expertise underpins automated identification systems that feed both mechanical shredders and emerging chemical depolymerization plants.
Germany
Take-back program participation rates exceed any European comparator, generating predictable post-consumer feedstock volumes. The EU Green Deal implementation through national EPR frameworks forces brand-funded collection infrastructure. North Rhine-Westphalia hosts automated sorting facilities that supply mechanical recyclers across the Benelux corridor.
France
Luxury fashion houses in Paris and Lyon pilot enzymatic hydrolysis outputs for virgin-equivalent viscose replacement. ANSM and environmental regulators enforce REACH-aligned chemical handling standards that favor biological pathways over solvent-based methods. The Île-de-France region anchors pilot-scale chemical recycling investments from premium textile brands.
Netherlands
Municipal partnership models generate consistent volume flows to automated sorting infrastructure unmatched in feedstock predictability. ECHA compliance frameworks for chemical recycling approval accelerate facility commissioning timelines relative to Southern European jurisdictions. Rotterdam-Antwerp logistics corridors enable integrated collection-sorting-recycling clusters that outperform fragmented municipal systems.
Italy
Prato's historic textile district repurposes mechanical recycling capacity for post-industrial garment streams from nearby luxury production facilities. National transposition of EU textile waste directives lags German and French timelines, creating temporary competitive asymmetries. Lombardy-based brands face compressed compliance windows as enforcement tightens.
United States
California and New York state-level waste hierarchies impose landfill diversion targets that accelerate domestic sorting investments. EPA frameworks lack the binding force of European EPR mandates, producing regulatory fragmentation that complicates multi-state supply chain planning. The Southeast textile corridor experiments with post-industrial feedstock aggregation from residual apparel manufacturing.
Clothing Recycling Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists for procurement contracts from large apparel retailers. The supplier base organizes around three strategic archetypes: integrated fiber producers with captive recycling streams, independent mechanical recyclers scaling through municipal partnerships, and chemical technology licensors pursuing royalty-based expansion. Consolidation pressure intensifies as certification backlogs compress qualified supplier pools. Capacity expansion and strategic licensing agreements represent the dominant competitive moves as brands pre-fund dedicated recycling infrastructure.
Within the integrated fiber producer tier, Lenzing AG and Birla Cellulose exemplify conglomerate structures that anchor premium supply from post-consumer waste streams. Unifi Inc. occupies a position among North American specialists leveraging established collection networks. Renewcell represents the pure-play chemical recycling archetype, operating one of Europe's few commercial-scale textile pulp facilities. These three entities collectively illustrate the competitive tension between diversified scale and focused technology depth.
| Leading Market Players |
|---|
| Lenzing AG |
| Birla Cellulose |
| Unifi Inc. |
| Worn Again Technologies |
| HYOSUNG TNC |
| Renewcell |
| The Woolmark Company |
| The Boer Group |
| Martex Fibre |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up mechanical recyclers in Germany and the Netherlands anchor mid-tier fiber supply, compressing margins for independent operators while concentrating pricing power among integrated conglomerates with captive certification infrastructure.
Pricing Analysis
Bundle collection-sorting-recycling contracts dominate enterprise procurement from Zara-scale retailers, while unbundled spot transactions serve peripheral processors lacking GRS audit infrastructure. Price differentiation centers on certification tier and volume scale, with GRS-certified chemical pulp commanding premium positioning against mechanical outputs. Cost compression in mechanical shredding is intensifying because virgin cotton futures volatility narrows recycled fiber premium tolerance. Mid-tier apparel manufacturers show highest price sensitivity, while luxury fashion houses in France and Italy absorb premium enzymatic outputs with minimal procurement friction.
Supply Chain Analysis
Skilled fiber identification technicians and chemical process engineers concentrate in German industrial clusters, particularly North Rhine-Westphalia, anchoring European automated sorting capacity that feeds both mechanical and chemical recycling routes. Feedstock supply rests on post-consumer collection partnerships in Germany, France, and the Netherlands, drawing from municipal drop-off centers and direct-to-consumer pickup models. Single-source vulnerability concentrates in German sorting infrastructure, where automated near-infrared spectroscopy capacity clusters create feedstock access bottlenecks for peripheral processors. Distribution runs through integrated collection-sorting-recycling clusters along Rotterdam-Antwerp logistics corridors, outperforming fragmented municipal systems in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement criteria displace price-primary supplier selection, with large apparel retailers mandating GRS chain-of-custody documentation as a contract precondition rather than preference.
For Market Incumbents: Extend certification infrastructure backward into collection partnerships, locking in feedstock security before EU Green Deal enforcement tightens compliance windows across Southern Europe. Acquire automated sorting capacity in Spain and Italy to capture first-mover advantage in underdeveloped collection networks. Chemical recycling pilots face margin pressure from enzymatic hydrolysis entrants; defend position by scaling solvent-based depolymerization to cost parity before biological pathways achieve commercial scale. For New Entrants and Emerging Players: Launch via direct-to-consumer collection models in urban France and Belgium, bypassing municipal intermediaries that dominate German supply security. Target Spain's underdeveloped take-back infrastructure, where Southern European implementation lags create temporary competitive asymmetries for brands with centralized EU supply chains. White-space exists in enzymatic hydrolysis licensing for distributed processing facilities serving luxury fashion houses seeking virgin-equivalent viscose replacement. For Investors and Strategic Acquirers: Valuations sit cheapest among independent mechanical recyclers lacking GRS audit infrastructure, as certification backlogs compress qualified supplier pools and concentrate order flow toward pre-certified processors. Long-term viability favors chemical technology licensors with royalty-based expansion models over capital-intensive plant operators. Watch enzymatic hydrolysis cost curves as the inflection indicator for biological pathway displacement of conventional solvent-based methods.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Brand-funded take-back programs in Spain secure feedstock before EPR enforcement tightens. |
| Enzymatic Hydrolysis Scale-Up | Biological pathways eliminate hazardous chemical handling costs for French luxury textile brands. |
| GRS Certification Investment | Pre-certified processors capture concentrated order flow from German retail procurement teams. |
| Geographic Expansion to Southern Europe | Italy and Spain lag German EPR timelines, creating temporary competitive asymmetries. |
| Resale Platform Channel Integration | ThredUp and Vinted logistics networks bypass traditional municipal waste intermediaries. |
Methodological Framework
Bottom-up apparel retailer procurement modeling reconciled against top-down chemical recycling capacity tracking forms the analytical core of this study. Primary interviews with sustainability compliance directors at large apparel retailers, fiber procurement managers, chemical recycling plant engineers, and municipal waste partnership coordinators combined with secondary validation from EU textile waste directive filings, ECHA chemical approval databases, and national EPR implementation timelines. Trade data from German and Dutch customs authorities, SEC filings from listed fiber producers, and GRS certification registry records provided supply-side triangulation against demand signals from retail procurement patterns.
Input-output matrices map feedstock collection volumes through sorting infrastructure to fiber output capacity across mechanical shredding, chemical depolymerization, and emerging enzymatic hydrolysis routes. Segmentation dimensions include process type, material composition, end-user procurement tier, and collection method logistics configuration. CAGRs derive from regression analysis of historical capacity deployment against EU Green Deal implementation timelines, with enzymatic technology cost curves and virgin cotton futures volatility as key demand-side sensitivity inputs.
Several conditions sit outside the modeled scope, including potential REACH regulatory amendments affecting chemical recycling approval pathways, breakthrough separation technologies for elastane-cotton-polyester blends, and sovereign trade policy shifts impacting post-industrial garment stream flows. Forecasts reflect assumptions about EPR enforcement consistency across member states and enzymatic hydrolysis scale-up trajectories. Material deviation in EU directive transposition timelines or enzymatic cost compression rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
United States Textile Recycling Market