
 Textile Waste Management Market | 2026-2036
Textile Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Waste Management Market Intelligence
EU Green Deal textile strategy is restructuring landfill diversion economics across European Union member states. Waste Management Inc. anchors North American collection density through municipal contract scale. Lenzing Group specializes in wood-pulp-to-fiber recovery, diverting pre-consumer cuttings from incineration. Unifi Inc. leverages proprietary depolymerization to sustain premium recycled PET yarn output for apparel brands.
Textile waste management encompasses the systematic collection, sorting, and conversion of discarded fabrics into reusable or reprocessable inputs, employing mechanical shredding, chemical solvent dissolution, or thermal breakdown to recover cellulose, polyester, or blended polymers for re-entry into supply chains. Mechanical recycling dominates current volume flows due to lower capital intensity, though chemical recycling captures expanding margin pools as brands demand fiber-to-fiber circularity without quality degradation. Post-consumer waste streams grow fastest driven by take-back program proliferation, while post-industrial segments offer cleaner feedstock with predictable composition and higher recovery yields.
EMA, EPA, and ECHA frameworks now mandate hazardous substance screening and extended producer responsibility across textile lifecycles, tightening feedstock access for non-compliant processors and redirecting investment toward certified chemical recycling infrastructure. The EU Green Deal's textile-specific targets compound these effects by penalizing landfilling and incineration while rewarding verified recycled content. Stakeholders must monitor regulatory divergence between jurisdictions to align processing technology bets with emerging compliance thresholds.
Market Dynamics
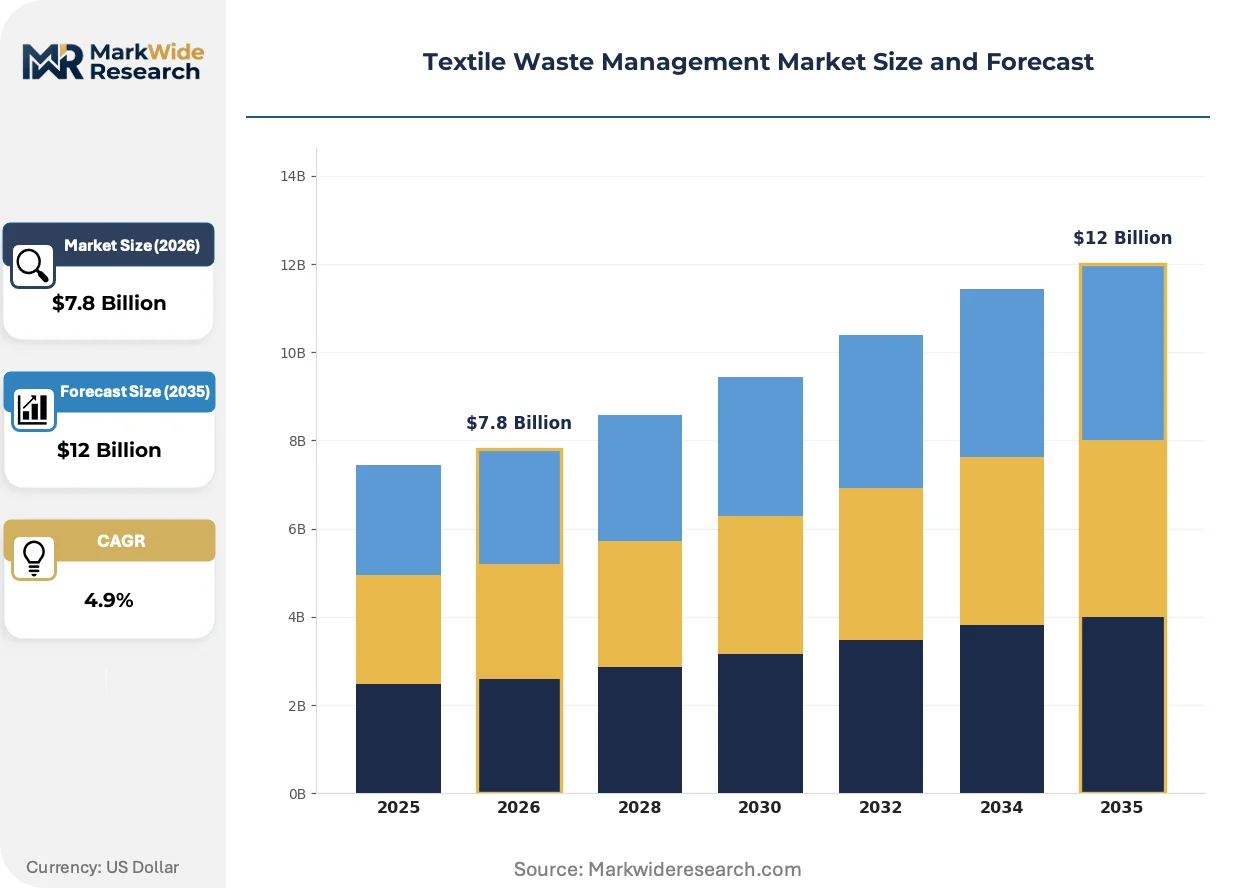
EU Green Deal mandates are compressing landfill economics while chemical recycling infrastructure races to scale before mechanical methods lock in feedstock contracts. Extended producer responsibility frameworks now force brands to internalize end-of-life costs, redirecting capital toward solvent-based fiber recovery systems that preserve polymer quality across multiple use cycles.
Growth Catalysts
- EU Green Deal textile targets:Mandatory recycled content minimums and landfill penalties under the EU Green Deal are forcing apparel brands to secure certified fiber supply, accelerating chemical recycling plant construction near Antwerp and Rotterdam port zones.
- Post-industrial cuttings recovery:Garment manufacturing clusters in Bangladesh and Vietnam are deploying automated sorting lines to capture pre-consumer cotton and polyester waste before incineration, feeding mechanical recycling networks with cleaner, higher-yield feedstock.
- Fiber-to-fiber circularity protocols:Chemical depolymerization technologies that restore virgin-grade polymer properties are attracting premium pricing from luxury fashion houses seeking unlimited recycling loops without quality degradation.
Market Restraints
- Capital intensity barriers:Chemical recycling facilities require USD 200-400 million per plant for solvent recovery systems and emissions controls, concentrating investment capacity among integrated petrochemical players.
- Feedstock contamination thresholds:Mechanical recycling yields collapse when elastane or metallic fiber content exceeds 5%, limiting addressable volumes from post-consumer athletic wear and performance apparel streams.
- Collection infrastructure gaps:Curbside textile collection reaches under 25% of EU households outside Germany and the Netherlands, forcing costly manual sorting at centralized facilities.
Strategic Opportunities
- India informal sector formalization:Partnerships with Mumbai and Tirupur waste-picker cooperatives can unlock 1.5 million tonnes annually of post-consumer cotton currently diverted to downcycling or combustion.
- Blockchain traceability integration:Digital product passports tracking fiber origin through garment lifecycle are creating compliance premiums for processors able to verify recycled content claims under EU Green Deal substantiation rules.
- Hybrid mechanical-chemical hubs:Co-located shredding and depolymerization plants near Istanbul and Karachi garment districts can optimize blended-fiber processing economics through integrated feedstock sorting.
Industry Challenges
- Chemical engineer scarcity:Solvent-based recycling operations require specialized expertise in polymer chemistry and closed-loop process design that existing waste management workforces rarely possess.
- Multi-standard certification complexity:Competing recycled content standards from GRS, OEKO-TEX, and EU Ecolabel create audit duplication costs for processors serving multiple brand compliance programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Waste Management Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Curbside Pickup, Drop-off Centers, Charity Bins, Retail Collection Processing Technology: Mechanical Recycling, Chemical Recycling, Incineration, Composting Waste Type: Post-Consumer, Post-Industrial, Pre-Consumer, Mixed Textiles End Use: Recycled Fibers, Reusable Textiles, Energy Generation, New Products |
| Companies Covered | Worn Again Technologies, TJX Companies, Goodwill Industries, V.F. Corporation, Toray Industries, Unifi Inc., Waste Management Inc., Birla Cellulose, Lenzing Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Waste Management Market Strategic Shifts & Innovations
Enzymatic polyester hydrolysis and AI-powered fiber identification are converging to unlock previously unrecyclable blended textiles, compressing processing costs while expanding feedstock eligibility. These advances are restructuring competitive advantage toward technology-integrated operators capable of handling complex post-consumer streams.
Enzymatic depolymerization of polyethylene terephthalate operates at ambient temperatures using engineered enzymes that selectively break ester bonds without damaging cotton or wool fractions. Fast-fashion retailers in Spain and Sweden are piloting this technology to process returned garments with elastane blends that mechanical shredders cannot separate. This biological pathway is overtaking thermal glycolysis as the preferred method for preserving fiber integrity in mixed-polymer feedstocks.
REACH authorization requirements for solvent-based recycling chemicals are tightening emissions thresholds and mandating closed-loop recovery systems above 99.5% efficiency. German and Dutch processors are retrofitting distillation columns and membrane separation units to comply with 2025 enforcement deadlines. Small-scale operators in Eastern Europe face feedstock exclusion as major brands restrict sourcing to ECHA-registered facilities with verified environmental management systems.
Take-back program proliferation is shifting collection economics from municipal contracts toward brand-operated reverse logistics networks. H&M, Zara, and Uniqlo now operate combined 15,000+ drop points across EU member states, bypassing traditional waste management intermediaries. This channel consolidation concentrates volume with vertically integrated processors able to guarantee fiber-to-fiber output quality, marginalizing independent mechanical recyclers dependent on spot market feedstock purchases.
Textile Waste Management Market Segmentation
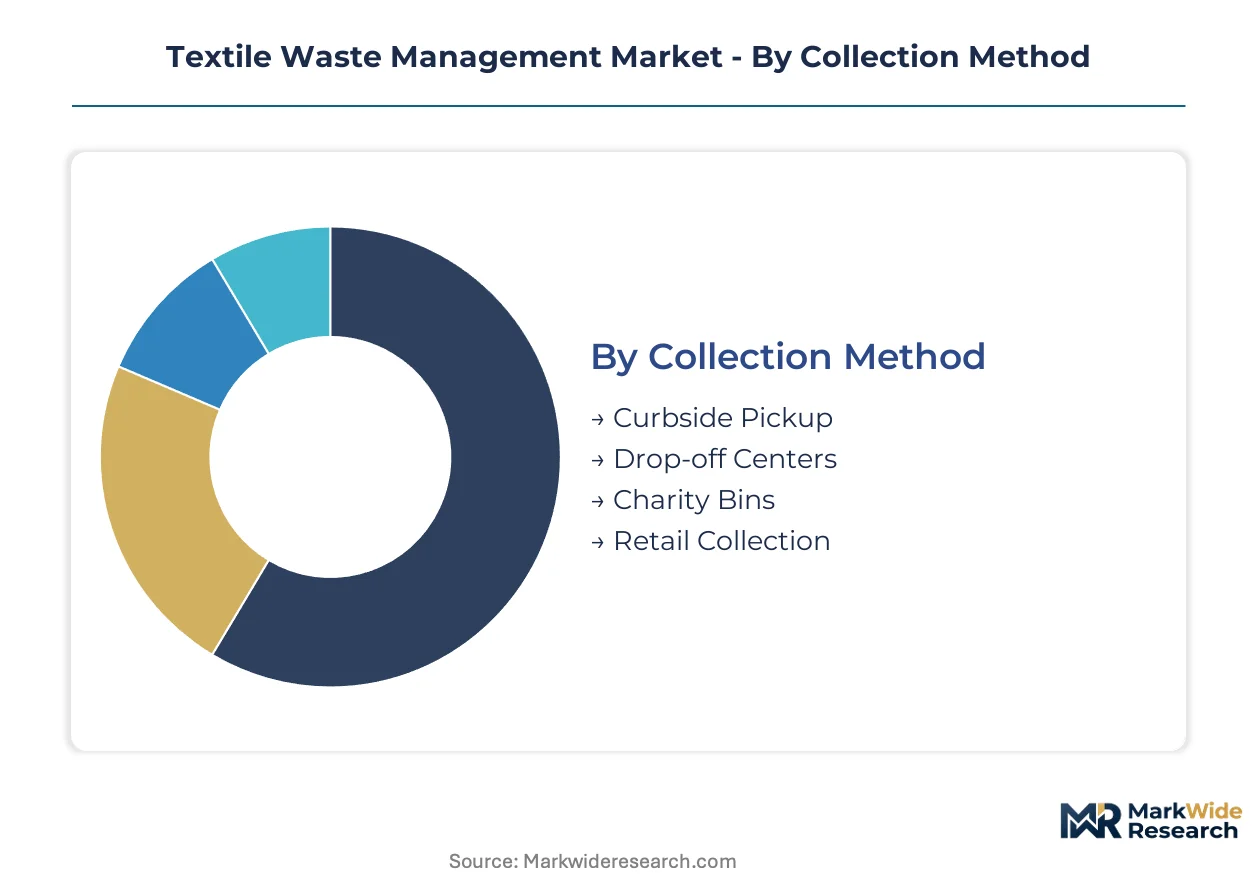
Segmentation in textile waste management reveals how collection density, processing economics, and end-market premiums fragment across operational models. Processors must align infrastructure bets with feedstock characteristics and regulatory compliance tiers.
Collection Method:
Curbside density concentrates in German and Dutch municipalities where EPR frameworks fund container deployment.
- Curbside Pickup:Scheduled residential collection using dedicated textile bins achieves highest participation rates where municipal budgets underwrite logistics. Rotterdam and Hamburg operators report 40% household penetration where container density exceeds one per 500 residents.
- Drop-off Centers:Centralized facilities with automated sorting lines capture cleaner feedstock streams. Belgium's Flanders region processes 85,000 tonnes annually through 300+ staffed centers where manual pre-sorting reduces contamination to sub-3% levels.
- Charity Bins:Unattended street-corner containers dominate UK and Spanish collection but suffer 15-20% residual waste contamination from improper disposal.
- Retail Collection:Brand-operated take-back at point-of-sale bypasses municipal intermediaries. H&M's 4,200 EU store network now captures 25,000 tonnes annually with reverse logistics integration.
Today's leader: Curbside Pickup. Tomorrow's challenger: Retail Collection.
Processing Technology:
Capital deployment splits between low-infrastructure mechanical shredding and premium chemical recovery systems.
- Mechanical Recycling:Shredding and reconstitution of natural fibers operates at EUR 150-250 per tonne processing cost. Italian Prato district hosts 150+ mechanical recyclers converting pre-consumer wool cuttings into shoddy fiber for automotive insulation.
- Chemical Recycling:Solvent-based depolymerization restores virgin-grade polymer properties for fiber-to-fiber loops. Eastman and Carbios facilities in France command 40-60% price premiums over mechanical output for certified circular polyester.
- Incineration:Waste-to-energy plants in Sweden and Denmark extract calorific value from non-recyclable fractions under strict emissions controls.
- Composting:Industrial biodegradation handles 100% cellulosic waste streams with controlled moisture and temperature protocols.
Mechanical Recycling dominates volume. Chemical Recycling claims margin expansion.
Waste Type:
Feedstock composition determines recovery yield and processing pathway selection.
- Post-Consumer:Discarded garments from households contain elastane and blended polymers that complicate mechanical separation. France's Refashion EPR scheme now diverts 240,000 tonnes annually from landfill through extended sorting infrastructure.
- Post-Industrial:Factory cuttings and manufacturing scraps offer predictable cotton-polyester ratios. Bangladesh's Narayanganj cluster feeds 180,000 tonnes yearly into mechanical recyclers with sub-1% contamination.
- Pre-Consumer:Unsold inventory and production overruns from brands provide single-fiber purity. Spanish Inditex suppliers redirect 12,000 tonnes annually of uncut fabric to fiber recovery.
- Mixed Textiles:Co-mingled post-consumer streams require advanced sorting before processing. Dutch SUEZ facilities deploy near-infrared separation to isolate cotton, polyester, and wool fractions.
Post-Industrial commands yield premiums. Post-Consumer offers volume scaling.
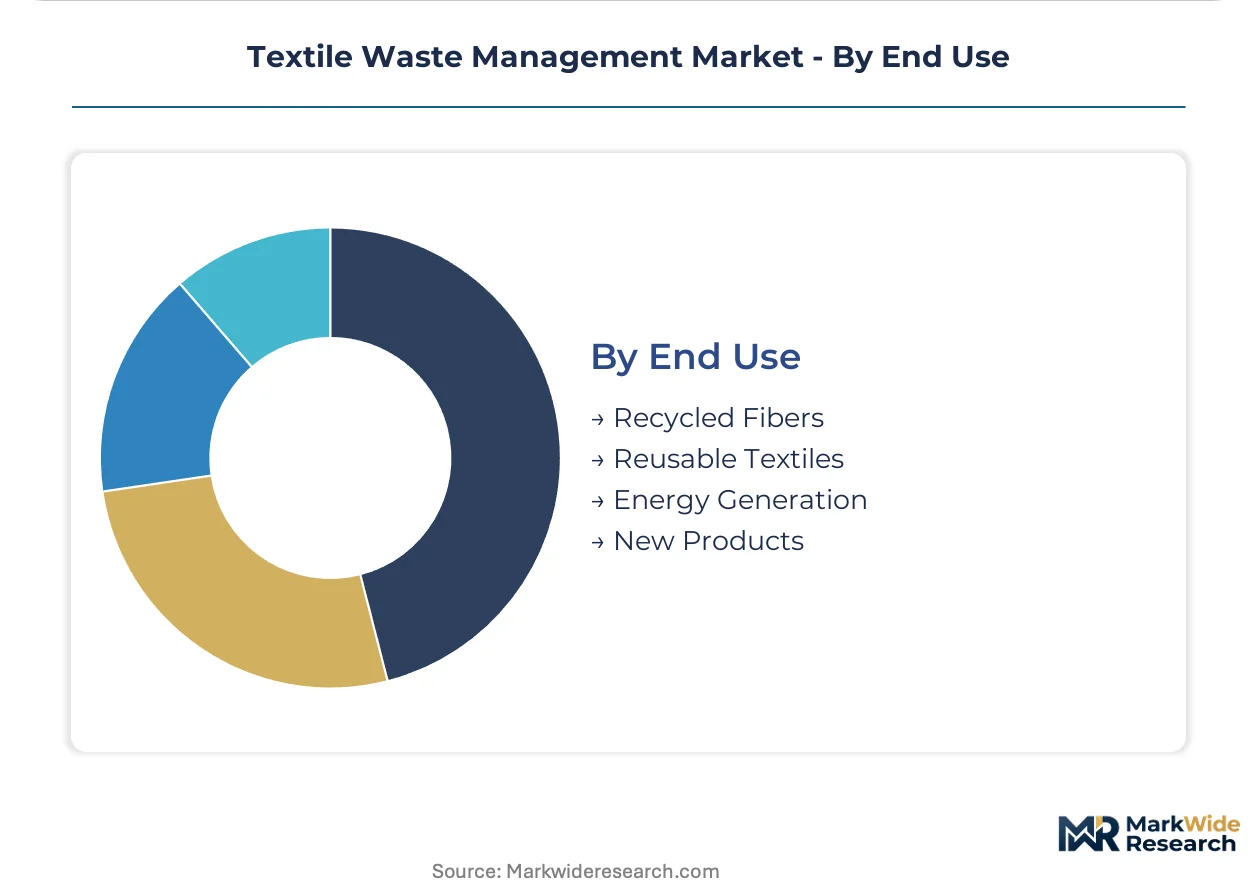
End Use:
Output destinations segment by price realization and circularity verification requirements.
- Recycled Fibers:Reconstituted polyester and cotton feed back into textile production. Lenzing's Refibra technology blends pre-consumer cotton with wood pulp for EU Ecolabel-certified lyocell.
- Reusable Textiles:Grade-A garments enter secondhand markets through sorting facilities in Poland and Romania. Berlin-based I:Collect processes 700 tonnes weekly for resale in Eastern Europe and Africa.
- Energy Generation:Non-recyclable fractions fuel cement kilns and district heating. Sweden's textile-to-energy network supplies 50,000 households through combined heat and power plants.
- New Products:Downcycled materials enter insulation, automotive padding, and construction geotextiles. Italian mechanical recyclers supply 30% of EU automotive nonwoven demand.
Recycled Fibers capture compliance premiums. New Products absorb residual volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechanical recycling first achieved industrial scale in the Prato district of Italy during the 19th century, establishing the template for post-industrial wool recovery that now spreads across European and Asian manufacturing clusters.
Germany
Curbside textile collection reaches 40% household penetration in Hamburg and Rotterdam-equivalent density zones. The EU Green Deal's extended producer responsibility mandates under the German Packaging Act fund container deployment at one bin per 500 residents. Mechanical recycling clusters concentrate in North Rhine-Westphalia near industrial textile zones.
France
Refashion EPR schemes divert 240,000 tonnes annually from landfill through extended sorting infrastructure. REACH authorization requirements for solvent-based recycling chemicals tighten emissions thresholds for processors near Lyon and Paris. Carbios operates enzymatic depolymerization facilities in the Clermont-Ferrand region.
Italy
The Prato district hosts 150+ mechanical recyclers converting pre-consumer wool cuttings into shoddy fiber. Lombardy garment manufacturers supply predictable cotton-polyester feedstock ratios to shredding operations. Milan-based luxury houses drive demand for fiber-to-fiber circularity without quality degradation.
United States
Waste Management Inc. anchors North American collection density through municipal contract scale. EPA frameworks mandate hazardous substance screening across textile lifecycles. California and New York textile-to-energy networks supply combined heat and power plants.
India
Mumbai and Tirupur waste-picker cooperatives unlock 1.5 million tonnes annually of post-consumer cotton currently diverted to downcycling. The BIS certification framework tightens feedstock access for non-compliant processors. Bangladesh's Narayanganj cluster feeds 180,000 tonnes yearly into mechanical recyclers with sub-1% contamination.
Textile Waste Management Market Key Industry Players
The competitive structure tilts toward integrated waste management conglomerates and specialty fiber recovery firms. Market concentration remains moderate with tiered differentiation between municipal-scale collectors and premium chemical recyclers. Two strategic archetypes dominate: vertically integrated waste handlers with collection network density, and technology-integrated fiber specialists with solvent-based depolymerization capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among specialty fiber recovery firms, Lenzing Group and Unifi Inc. exemplify the technology-integrated archetype, while Waste Management Inc. occupies a position representing municipal-scale collection infrastructure. These three anchors demonstrate how geographic clustering near port zones and garment districts shapes competitive positioning.
| Leading Market Players |
|---|
| Worn Again Technologies |
| TJX Companies |
| Goodwill Industries |
| V.F. Corporation |
| Toray Industries |
| Unifi Inc. |
| Waste Management Inc. |
| Birla Cellulose |
| Lenzing Group |
| Others |
Cost & Logistics Intelligence
EU Green Deal extended producer responsibility mandates gate both qualified supply and premium-tier pricing access, forcing processors to absorb certification costs that mechanical recyclers cannot pass through to price-sensitive buyers. This regulatory filter concentrates margin capture among solvent-based operators with verified fiber-to-fiber output, while spot-market mechanical recyclers face compression from feedstock scarcity and brand compliance exclusion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered chemical recyclers from uncertified mechanical operators and downcycled commodity shoddy. Price differentiation rests on certification grade under EU Ecolabel and GRS standards, plus volume scale commitments from apparel brands. Cost compression in the standard tier is intensifying because feedstock competition from brand-operated take-back programs concentrates supply with integrated processors. Fast-fashion retailers exhibit highest price sensitivity, while luxury houses seeking unlimited recycling loops accept 40-60% premiums for virgin-grade polymer restoration.
Supply Chain Analysis
Single-source vulnerability sits with Bangladesh, Vietnam, and China as dominant feedstock origins for post-industrial cuttings and garment manufacturing scraps. Raw material dependencies draw from cotton lint, polyester chip, and wood pulp inputs that fluctuate with agricultural yields and petrochemical spreads. Tariff exposure on recycled fiber imports into the EU threatens margin structures for Asian mechanical recyclers serving European automotive nonwoven demand. Distribution runs through brand-operated reverse logistics networks and municipal collection contracts, with port-proximate chemical recycling clusters near Antwerp and Rotterdam capturing logistics efficiencies for solvent-based depolymerization feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where fiber-to-fiber circularity specifications displace downcycled output, rewarding processors with verified closed-loop capabilities and ECHA-registered environmental management systems.
For Market Incumbents: Extend collection network density through municipal contract consolidation in Germany and the Netherlands, where EPR-funded container deployment achieves 40% household penetration. Invest in solvent recovery system retrofits ahead of 2025 REACH enforcement deadlines to defend margin position against emerging enzymatic depolymerization challengers. Certification investment in EU Ecolabel and GRS standards anchors brand offtake agreements that spot-market mechanical recyclers cannot replicate.
For New Entrants and Emerging Players: Brand-operated take-back program partnerships offer a digital-channel route to bypass traditional waste management intermediaries and secure predictable feedstock flows. Target India's informal waste-picker cooperatives in Mumbai and Tirupur, where 1.5 million tonnes of post-consumer cotton currently diverts to downcycling or combustion with minimal competitive capture. Deploy AI-powered fiber identification and automated sorting as a go-to-market angle to unlock previously unrecyclable elastane-blended athletic wear streams that mechanical shredders cannot process.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale mechanical recyclers with municipal collection contracts because brand compliance requirements are forcing consolidation toward integrated operators with certified chemical recycling capabilities. Five-to-ten year viability favors processors with co-located shredding and depolymerization hubs near garment districts in Istanbul and Karachi. Watch enzymatic polyester hydrolysis cost curves as the inflection indicator for when biological pathways displace thermal glycolysis in mixed-polymer feedstock economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Capacity Expansion | Eastman and Carbios facilities in France command 40-60% price premiums for certified circular polyester output. |
| Backward Integration into Collection Infrastructure | H&M's 4,200 EU store network captures 25,000 tonnes annually with reverse logistics integration bypassing municipal intermediaries. |
| Blockchain Traceability Integration | Digital product passports under EU Green Deal substantiation rules create compliance premiums for verified recycled content claims. |
| Hybrid Mechanical-Chemical Hub Development | Co-located shredding and depolymerization plants near Istanbul and Karachi optimize blended-fiber processing economics. |
| Enzymatic Depolymerization Technology Licensing | Carbios operates enzymatic facilities in Clermont-Ferrand preserving fiber integrity in mixed-polymer feedstocks at ambient temperatures. |
Research Approach
Multiple input streams — primary interviews with textile waste management executives, secondary validation through ECHA registration databases and EU Green Deal policy filings, and trade data from customs authorities — were reconciled to construct segment-level demand estimates. Conversations with plant managers at mechanical recycling clusters, procurement leads at apparel brands, regulatory affairs specialists, and waste-picker cooperative coordinators informed operational cost structures and feedstock flow dynamics. Bottom-up triangulation across collection method, processing technology, and end-use segments was cross-checked against top-down market sizing from municipal EPR scheme disclosures and brand sustainability reports.
Historical capacity deployment patterns were cross-referenced against panel input from chemical recycling project developers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include collection infrastructure type, processing technology pathway, waste stream composition, and end-use application tier. CAGRs were derived from elasticity-adjusted demand curves incorporating brand recycled content commitments and regulatory landfill diversion targets. Industry-specific forecast inputs draw from REACH authorization timelines for solvent-based recycling chemicals and enzymatic depolymerization pilot scale-up announcements.
The model assumes a particular technology adoption path; alternative pathways for enzymatic polyester hydrolysis would alter the outlook if ambient-temperature biological processing achieves cost parity with thermal glycolysis earlier than baseline assumptions. Forecasts reflect assumptions about EPR scheme expansion rates, feedstock contamination thresholds, and certification audit costs that regulatory enforcement or technological breakthrough could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Textile Recycling Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
Recycled Fibers Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market