
 Textile Recycling Market | 2026-2036
Textile Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Recycling Market Intelligence
The channel for unsorted post-consumer textile waste collection is narrowing as municipalities and brands establish more direct partnerships with specialized sorters. This shift favors firms with advanced sorting and processing technologies. Lenzing AG leverages its closed-loop TENCEL™ Lyocell process to handle pre-consumer cotton scraps. Renewcell specializes in chemical recycling of cellulose-based textiles into new pulp, while Unifi, Inc. dominates the polyester segment with its REPREVE® brand of recycled fibers.
Textile recycling encompasses processes that convert post-consumer or post-industrial textile waste into reusable fibers, yarns, or other materials. These methods involve sorting by material type, followed by mechanical shredding or chemical dissolution to break down fabrics into their constituent components. Mechanical recycling of cotton currently represents the largest volume, though chemical recycling of polyester is the fastest-growing method. Within end uses, demand from the apparel sector for recycled content is significant, but industrial textiles offer higher-margin opportunities.
Regulatory frameworks like the EU's Waste Framework Directive and state-level initiatives in the United States, such as California's textile recovery programs, mandate increased collection and recycling rates. In China, the 'dual carbon' goals and GB standards for recycled textiles create strong domestic policy support for the industry. Consequently, the key strategic decision for operators involves balancing investments in high-purity chemical recycling against scaling lower-cost mechanical processing for blended materials.
Market Dynamics
The central tension in textile recycling is the strategic choice between scaling lower-cost mechanical processing for blended materials and investing in high-purity, capital-intensive chemical recycling to meet brand demand for virgin-equivalent fibers and satisfy regulatory mandates.
Growth Catalysts
- Regulatory Mandates:The European Union's implementation of extended producer responsibility (EPR) schemes under its Waste Framework Directive creates a powerful incentive for increased collection, sorting, and processing of post-consumer textiles across member states.
- Automotive Sector Intake:Material demand from the automotive industry for recycled textiles is a significant driver, specifically for use in insulation, carpet backing, and other non-woven components where performance and sustainability are key purchasing criteria.
- National Sustainability Goals:China's 'dual carbon' policy and GB standards for recycled textiles are creating strong domestic policy support, encouraging investment in recycling infrastructure to manage textile waste and build a circular economy.
Market Restraints
- Feedstock Contamination:The prevalence of complex fiber blends, such as cotton-polyester or elastane mixes, in post-consumer garments contaminates recycling streams, making efficient and pure material separation technically difficult and costly.
- High Capital Costs:Advanced chemical recycling technologies require substantial capital expenditure for plant construction and have high operational costs, which can make recycled feedstock more expensive than virgin materials, dampening adoption.
- Collection Infrastructure Gaps:The inconsistent volume and quality of collected post-consumer textile waste creates significant feedstock volatility for recyclers, hindering their ability to operate at a consistent, efficient scale.
Strategic Opportunities
- High-Margin Industrial Applications:Developing recycled fibers for non-apparel end uses, such as geotextiles, building materials, and composites, offers higher-margin opportunities away from the competitive fashion sector.
- AI-Powered Sorting Technology:Integrating artificial intelligence and near-infrared (NIR) spectroscopy into automated sorting lines presents a major opportunity to improve the speed, accuracy, and purity of feedstock separation by material type and color.
- US State-Level Programs:Emerging textile recovery and recycling programs, such as those being established in California and other states, create new, mandated regional markets for collection and processing services.
Industry Challenges
- Harmonization of Standards:A lack of globally accepted standards for defining and verifying recycled content creates market confusion, complicates international trade, and opens the door for unsubstantiated greenwashing claims by brands.
- Scale-Up Capital for Chemical Recycling:Securing the significant long-term investment needed to build and scale chemical recycling facilities to an industrial level remains a primary operational hurdle for technology developers and operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Recycling Market |
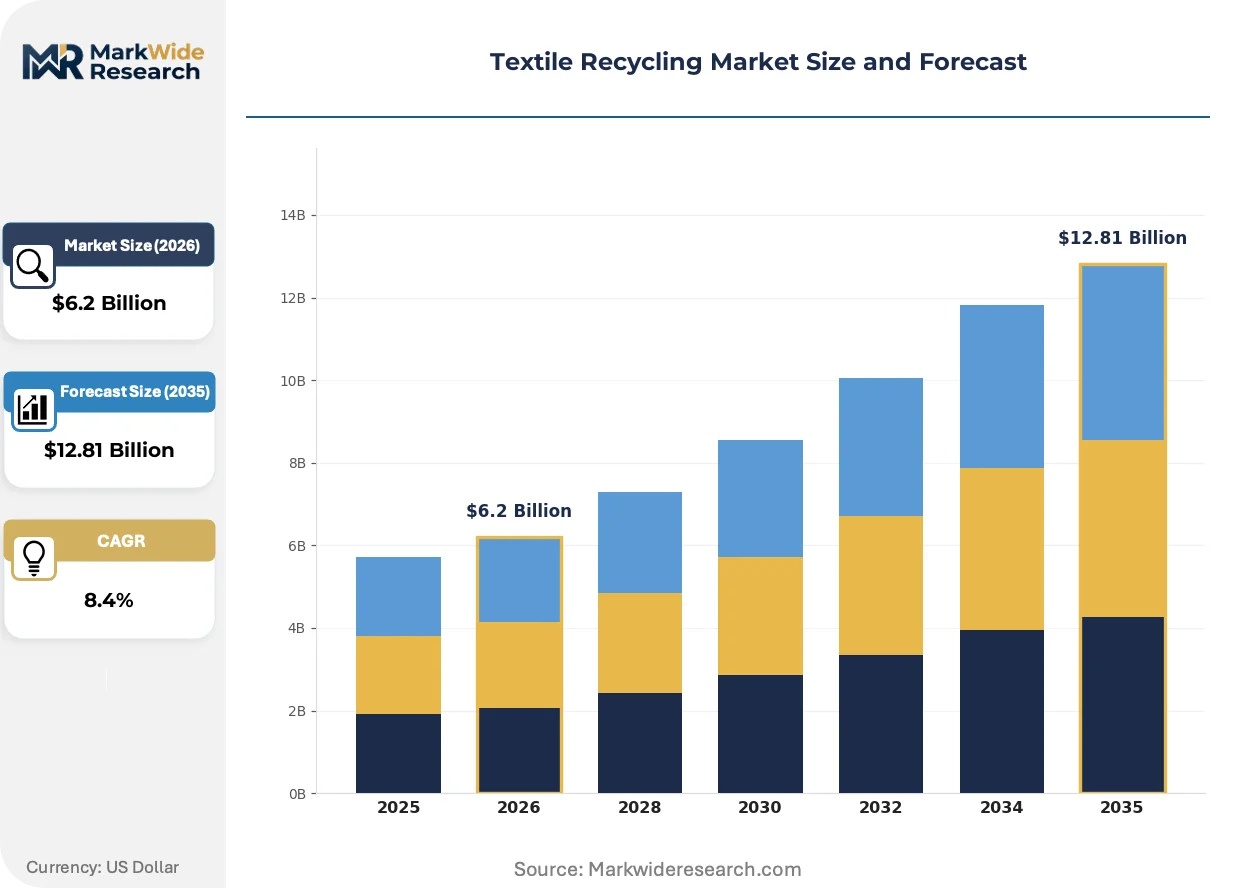
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Recycling Method: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Upcycling Material Type: Cotton, Polyester, Nylon, Wool End Use: Apparel, Home Textiles, Industrial Textiles, Automotive Distribution Channel: Online, Retail, Direct Sales, Partnerships |
| Companies Covered | Lenzing AG, Birla Cellulose, HYOSUNG TNC, Unifi, Inc., Renewcell, The Woolmark Company, Boer Group, Martex Fibre, REMONDIS SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Recycling Market Strategic Shifts & Innovations
The market is defined by a technological and logistical push to transform low-value textile waste into high-quality circular feedstocks. This evolution is supported by new policies and direct collaborations across the supply chain, moving beyond simple downcycling.
Chemical recycling technologies, including solvolysis and enzymatic digestion, break down polymers like polyester into their constituent monomers. Apparel and automotive brands are adopting fibers made from these processes to meet circularity and recycled-content targets. The technological focus is migrating from mechanical shredding, which degrades fiber quality, toward chemical methods that restore materials to a virgin-equivalent state for true circularity.
The European Union's Waste Framework Directive establishes a critical regulatory push by mandating separate collection for textiles. This policy compels member states to organize the necessary infrastructure, which in turn provides recyclers with a more consistent and predictable supply of post-consumer feedstock. The apparel retail sector within the EU is most affected, forcing brands to redesign products for recyclability and actively participate in take-back schemes.
A significant shift in supply chain behavior involves brands forming direct partnerships with specialized textile sorters and chemical recyclers. This model bypasses traditional, fragmented municipal or charitable collection channels, giving brands greater control over the quality and traceability of their recycled material inputs. This trend is most pronounced in North America and Europe, where brands seek to secure feedstock for closed-loop product lines.
Textile Recycling Market Segmentation
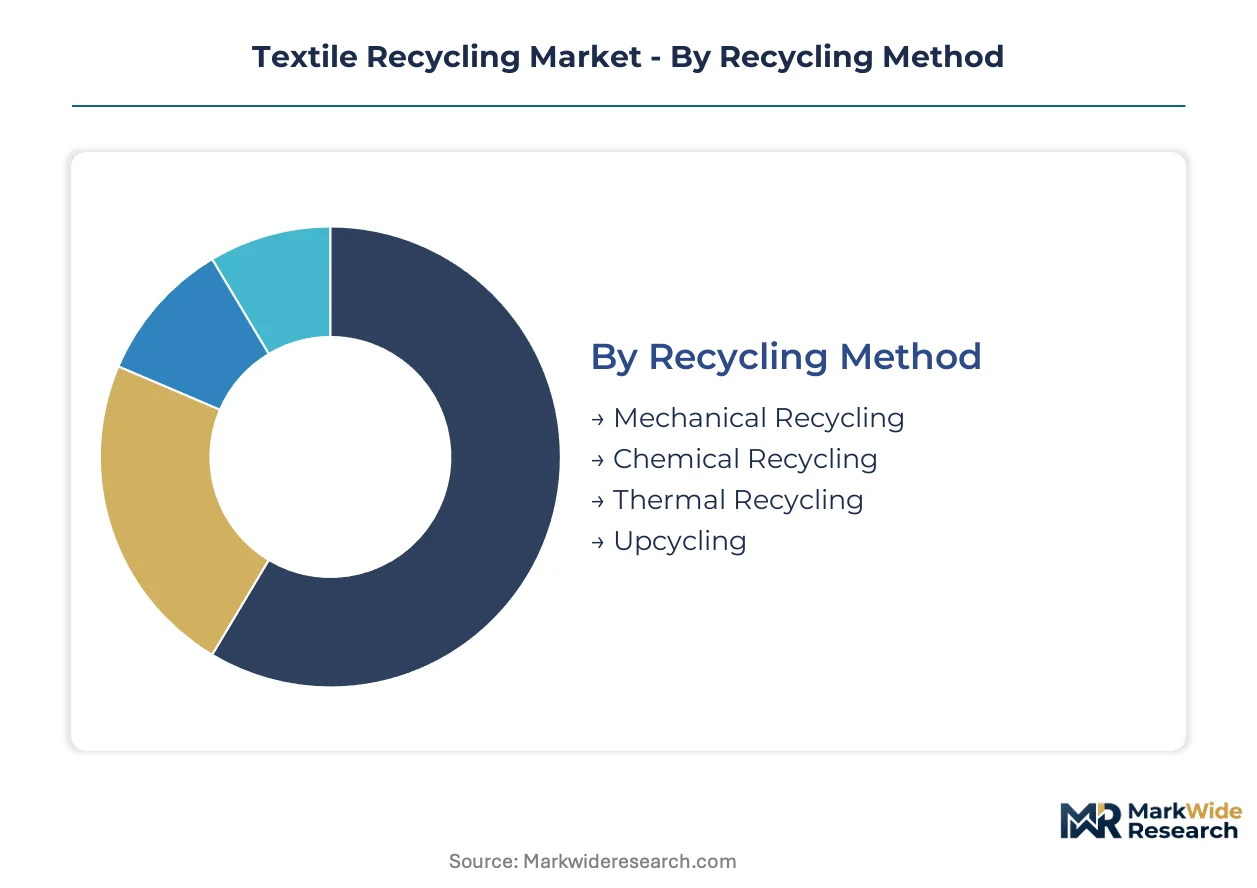
The segmentation of the textile recycling market illuminates the diverse pathways materials take from waste to new products. Understanding these distinct segments helps stakeholders identify optimal processing technologies and target high-value end-use applications. This detailed breakdown highlights areas of technological innovation and market concentration for specific material flows.
Recycling Method:
The use-case spectrum for textile recycling methods spans from mechanical processes handling mixed materials to advanced chemical techniques targeting virgin-equivalent outputs.
- Mechanical Recycling:This method physically breaks down textile waste through shredding and carding into shorter fibers, suitable for non-woven applications or lower-grade yarns. Demand concentrates in regions with established textile industries like India, driven by its cost-effectiveness for cotton and blended materials.
- Chemical Recycling:This advanced process dissolves or depolymerizes textile waste into its constituent monomers or polymers, allowing for the creation of new fibers with virgin-like properties. China's export-oriented textile production centers increasingly demand chemically recycled polyester to meet global brand sustainability targets.
- Thermal Recycling:This method involves incinerating textile waste to recover energy, often used for materials unsuitable for mechanical or chemical recycling due to contamination or complex blends. Municipal waste management systems in Europe utilize thermal recycling to reduce landfill volume.
- Upcycling:Upcycling repurposes textile waste into new products without breaking down the original fibers, such as converting old denim into bags or insulation. Small and medium-sized enterprises often engage in upcycling for niche consumer markets.
The dominant share belongs to Mechanical Recycling, while Chemical Recycling is closing the gap fastest.
Material Type:
Supply concentration across material types dictates the appropriate recycling technology and potential end-use applications, influencing processing infrastructure investments.
- Cotton:A natural cellulosic fiber, cotton is widely recycled mechanically into shoddy for insulation or non-woven fabrics, and increasingly chemically for regenerated cellulose fibers. Apparel manufacturers in Europe seek recycled cotton content to meet circularity goals.
- Polyester:This synthetic fiber is a primary target for chemical recycling, yielding virgin-equivalent PET for new textiles or bottles. The automotive sector in Germany utilizes recycled polyester extensively for interior components.
- Nylon:A synthetic polyamide, nylon recycling often involves depolymerization to recover caprolactam, which is then re-polymerized into new nylon. Specialized facilities in the United States process industrial nylon waste from fishing nets and carpets.
- Wool:This natural protein fiber is typically mechanically recycled into insulation, carpet underlay, or lower-grade yarns for blankets. Recycled wool finds application in cold-weather apparel in Scandinavian countries.
Polyester represents the largest volume processed for high-value applications, with Cotton expanding most quickly in mechanical recycling.
End Use:
Application diversity for recycled textiles spans from consumer goods to high-performance industrial products, each with distinct quality requirements and market dynamics.
- Apparel:Recycled fibers are incorporated into new clothing lines, driven by consumer demand for sustainable fashion and brand commitments to circularity. Brands in the United States increasingly feature garments made from recycled polyester and cotton.
- Industrial Textiles:This segment includes geotextiles, filtration media, and composites, valuing performance characteristics and cost-effectiveness from recycled materials. The construction industry in China uses recycled textiles for sound insulation and reinforcement.
- Home Textiles:Recycled fibers find application in bedding, upholstery, carpets, and towels, contributing to a more sustainable home goods market. European home furnishing brands are incorporating more recycled content into their product lines.
- Automotive:Recycled textiles are used for insulation, carpet backing, headliners, and other non-structural components in vehicles. Japanese automotive manufacturers are leaders in integrating recycled materials into their car interiors.
Apparel constitutes the largest segment by volume, while Industrial Textiles is gaining share fastest due to performance demands.
Distribution Channel:
Market access for recycled textile materials is increasingly defined by direct relationships and strategic collaborations, moving beyond traditional wholesale models.
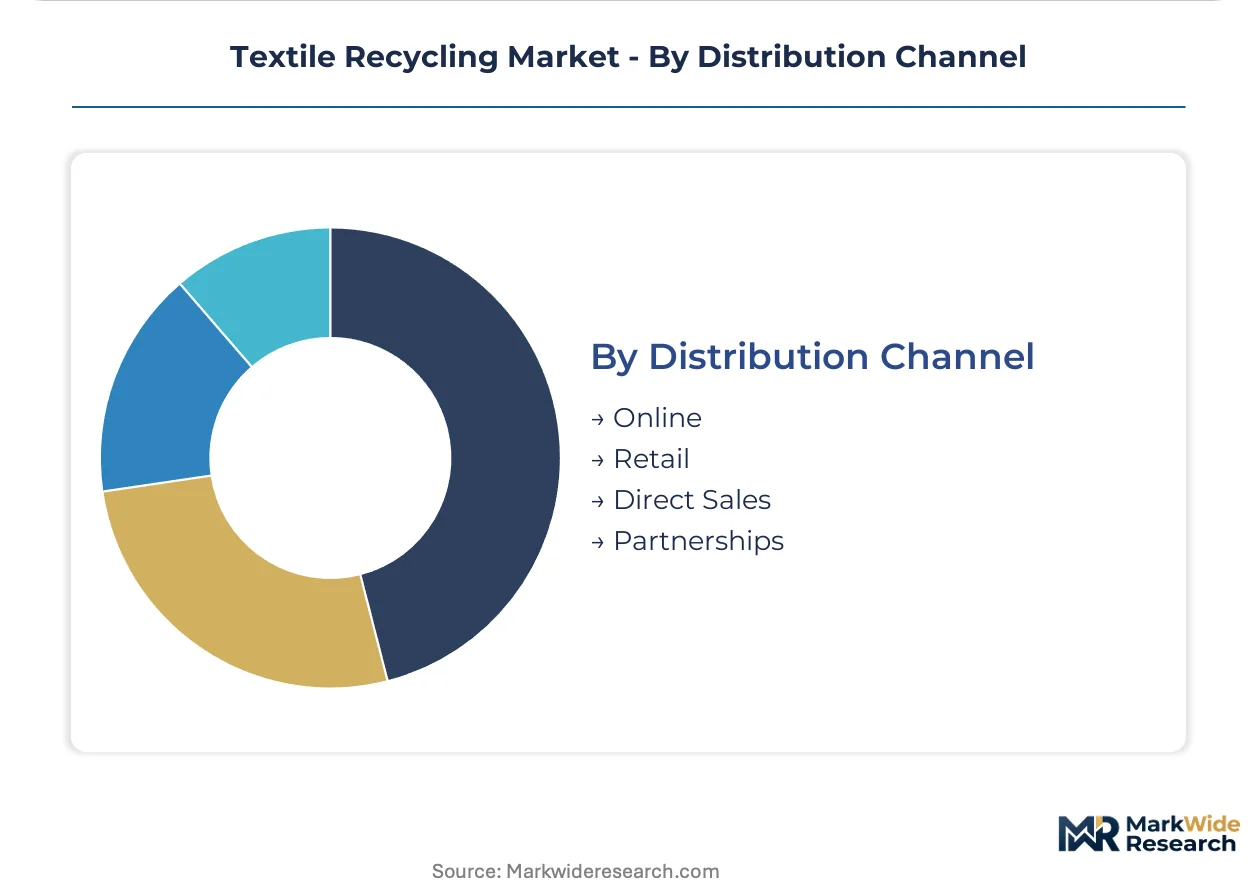
- Online:E-commerce platforms facilitate the trade of recycled fibers and textile waste, connecting suppliers with buyers globally and expanding market reach. Digital marketplaces in North America streamline transactions for specialized recycled materials.
- Retail:Retail channels include brand-led take-back programs and in-store collection points, serving as direct conduits for post-consumer textile waste collection. Major apparel retailers in the United Kingdom operate extensive garment collection initiatives.
- Direct Sales:Recyclers often engage in direct sales to manufacturers, ensuring consistent supply and tailored material specifications for specific production needs. Chemical recyclers in Europe directly supply polymer producers with recycled monomers.
- Partnerships:Strategic alliances between brands, recyclers, and waste management companies secure reliable feedstock supply and demand for recycled content. Collaborative ventures in Denmark ensure closed-loop systems for specific textile products.
Direct Sales maintains a significant volume, with Partnerships climbing fastest due to increasing supply chain integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam, as a major European logistics hub, underwrites the region's role in processing imported and domestically collected textile waste. This infrastructure facilitates the movement of post-consumer textiles for sorting and recycling across the continent. Such strategic assets are crucial for scaling circular economy initiatives globally.
United States
Emerging state-level textile recovery programs drive demand for collection and processing services across the United States. California's textile recovery initiatives mandate increased recycling rates, creating new regional markets. In Los Angeles, specialized sorters and recyclers are establishing facilities to process textile waste from the large urban population.
Germany
Automotive manufacturers in Germany generate significant demand for recycled polyester, particularly for interior components like insulation and carpet backing. The EU's Waste Framework Directive and extended producer responsibility schemes incentivize textile collection and processing. Bavaria's industrial clusters collaborate on research into advanced recycling technologies for high-performance automotive applications.
China
Domestic sustainability goals and export-oriented textile production centers concentrate demand for chemically recycled polyester within China. The nation's 'dual carbon' policy and GB standards for recycled textiles provide strong policy support for recycling infrastructure investment. The Yangtze River Delta region hosts numerous textile manufacturers integrating recycled content into their supply chains.
India
The textile industry in India drives substantial demand for mechanical recycling of cotton, utilizing cost-effective processing for lower-grade yarns and non-woven applications. National textile policies increasingly promote sustainable practices and waste management initiatives. Tiruppur, a major textile manufacturing hub, concentrates mechanical recycling operations to supply its apparel sector.
Japan
Japanese automotive manufacturers utilize recycled textiles extensively for interior components, valuing performance and sustainability in their material selection. The Ministry of Economy, Trade and Industry (METI) supports circular economy initiatives and waste reduction targets. Aichi Prefecture, a center for automotive production, fosters collaboration between recyclers and car makers for material innovation.
Textile Recycling Market Key Industry Players
On the supply side, the industry is fragmented, with a clear tiering between large-scale mechanical processors and capital-intensive chemical recycling innovators. This structure accommodates diverse feedstock types and end-use requirements across the market. Strategic archetypes include specialized sorters, mechanical recycling volume players, and advanced chemical recycling technology providers. Dominant competitive moves involve forming strategic partnerships with brands and expanding capacity for advanced recycling technologies.
Specialists in advanced fiber processing, such as Lenzing AG, exemplify the industry's push towards closed-loop systems for cellulosic materials. Renewcell, a Sweden-based technology developer, occupies a position at the forefront of chemical recycling for cellulose-based textiles, converting waste into new pulp. Unifi, Inc., a United States-based company, anchors the polyester segment with its REPREVE® brand, supplying recycled fibers for diverse applications including apparel and automotive components.
| Leading Market Players |
|---|
| Lenzing AG |
| Birla Cellulose |
| HYOSUNG TNC |
| Unifi, Inc. |
| Renewcell |
| The Woolmark Company |
| Boer Group |
| Martex Fibre |
| REMONDIS SE & Co. KG |
| Others |
Cost & Logistics Intelligence
Feedstock contamination, particularly from complex fiber blends, determines both pricing tier spreads and the fragmented supply chain shape within the textile recycling market. This challenge necessitates specialized sorting technologies, impacting overall cost structures.
Pricing Analysis
Volume-discount tiering structures characterize pricing for mechanically recycled fibers, while contract-based long-term offtake agreements define chemical recycling. Price differentiation arises from material purity (virgin-equivalent vs. downcycled), certification of recycled content, and volume scale. Upward pricing pressure stems from high capital expenditure for chemical recycling facilities. Apparel manufacturers exhibit higher price sensitivity compared to industrial textile buyers focused on performance characteristics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming more common for sourcing high-value chemically recycled materials. The supply of textile waste concentrates in Europe for collection, while processing and demand anchor in China and India. Raw material dependencies include post-consumer textile waste and specific chemical solvents for advanced processes. Inconsistent collection volume presents a structural supply chain risk for recyclers. Direct sales and strategic partnerships define the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textile recycling market faces a critical shortage of advanced sorting and processing capabilities for complex fiber blends. This scarcity limits the volume of high-purity recycled feedstock available for circular economy initiatives.
For Market Incumbents:Pre-empt competitive threats from specialized chemical recyclers by investing in AI-powered sorting technologies. Expand chemical recycling capacity, particularly for polyester and cellulosic blends, to meet rising demand for virgin-equivalent fibers. Form strategic partnerships with fashion brands to secure long-term feedstock supply. This approach mitigates the risk of being outmaneuvered by agile technology developers.
For New Entrants and Emerging Players:Build out specialized collection and sorting infrastructure in emerging US state-level markets. Target niche industrial applications, such as geotextiles or composites, where recycled content offers performance benefits and higher margins. Focus on developing innovative pre-treatment solutions for complex blended materials. Value-chain integration with specific brand partners provides a strong go-to-market angle.
For Investors and Strategic Acquirers:The EU's Waste Framework Directive reshapes the acquisition landscape, favoring firms with advanced processing capabilities. High-purity chemical recycling technology developers offer long-term value over the next decade. Seek out targets with proven intellectual property and established pilot-scale operations for cellulose or polyester. Commercialization of new chemical recycling plants signals market maturation and investment readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (Chemical Recycling) | Scales production of virgin-equivalent fibers, meeting brand demand for circularity. |
| AI-Powered Sorting Integration | Improves feedstock purity and efficiency, reducing processing costs for recyclers. |
| Direct Brand Partnerships | Secures consistent feedstock supply and guaranteed offtake for recycled materials. |
| New Product Development (Industrial) | Diversifies revenue streams into higher-margin, performance-driven end uses. |
| Regulatory Compliance Investment | Ensures market access and avoids penalties under evolving waste management mandates. |
Research Approach
A standing panel of textile manufacturers, chemical recyclers, waste management executives, and apparel brand sustainability leads provided ongoing calibration for primary insights. This involved combining qualitative interviews with industry stakeholders and rigorous secondary validation. Publicly available EU Waste Framework Directive documents, China's GB standards, US state-level program reports, and corporate sustainability disclosures informed the analysis. Bottom-up data collection and top-down market sizing ensured robust triangulation.
Scenario-bracketing provided a comprehensive range for market projections across the analysis window. The model integrated segmentation dimensions including recycling method, material type, end use, distribution channel, and regional policy impact. Compound annual growth rates were derived through regression analysis of historical data and projected growth drivers. Raw material availability, technological advancements in sorting, and regulatory compliance timelines served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by chemical recycling innovators or large-scale apparel brands would shift outcomes. This analysis reflects current market dynamics and known regulatory trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled and Circular Textiles
Clothing Recycling Market
Recycled and Circular Textiles
Post-Consumer Recycled Textiles Market
Recycled and Circular Textiles
Textile Waste Management Market
Recycled and Circular Textiles
Recycle Yarn Market
Recycled and Circular Textiles
United States Textile Recycling Market
Recycled and Circular Textiles
Europe Textile Recycling Market
Recycled and Circular Textiles
EU Outdoor and Sportswear Textile Returns Refurbishment and Recycling Market
Recycled and Circular Textiles
Reusable Period Panties Market
Recycled and Circular Textiles
Automotive Seat Cover and Interior Textile Recycling in Europe Market
Recycled and Circular Textiles
Global Recycled Textiles Market
Recycled and Circular Textiles
PET Microfiber Fleece Garment Recycling Streams in Europe Market
Recycled and Circular Textiles
Recycled Polyester (Rpet) Market
Recycled and Circular Textiles
Recycled Cotton Market
Recycled and Circular Textiles
Recycled Fibers Market