
 Global Thermal Analysis Software Market | 2026-2036
Global Thermal Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Analysis Software Market Foresight
Aftermarket service revenue is narrowing as vendors bundle predictive maintenance modules into core platform licenses. NETZSCH leverages its thermal instrument installed base to cross-sell integrated software workflows. TA Instruments sustains premium positioning through deep calibration protocols that lock in repeat analytical cycles. PerkinElmer anchors cloud migration roadmaps for enterprise laboratories seeking centralized data governance.
Thermal analysis software comprises computational platforms that model heat transfer, thermodynamic phase transitions, and thermal stability across materials using finite element methods and differential scanning calorimetry data inputs. These tools enable engineers to predict thermal behavior without physical prototyping, reducing development cycles for heat-sensitive components. Cloud-based deployment now captures the fastest expansion as semiconductor manufacturers demand elastic compute for transient thermal simulations of chip architectures. Academic institutions remain a mature, price-sensitive segment where open-source alternatives constrain vendor margins. Simulation software commands the deepest margin pools where multiphysics coupling commands annual subscription premiums.
FDA validation requirements for pharmaceutical thermal characterization shape product development priorities for software vendors serving drug stability analysis. EPA emissions testing protocols and REACH substance thermal hazard assessments in Europe compel chemical processors to maintain auditable simulation records. EMA guidelines on biologic storage thermal mapping further extend compliance-driven procurement across life sciences laboratories. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as instrument-hardware bundling tightens across major suppliers.
Market Dynamics
Cloud-based thermal simulation platforms are compressing hardware-software bundling power as semiconductor manufacturers demand elastic compute for transient chip thermal modeling, forcing legacy vendors to unbundle instrument-tied licenses.
Growth Catalysts
- Aerospace engine validation mandates:Commercial aviation OEMs in Toulouse and Seattle now require thermal simulation documentation for turbine blade certification, expanding software procurement cycles.
- EU F-Gas Regulation compliance:European chemical processors must submit thermal performance disclosures for fluorinated gas alternatives, creating audit-trail requirements that simulation software satisfies.
- Multiphysics coupling adoption:Automotive battery pack designers combine thermal, electrical, and mechanical solvers to predict thermal runaway propagation without physical crash testing.
Market Restraints
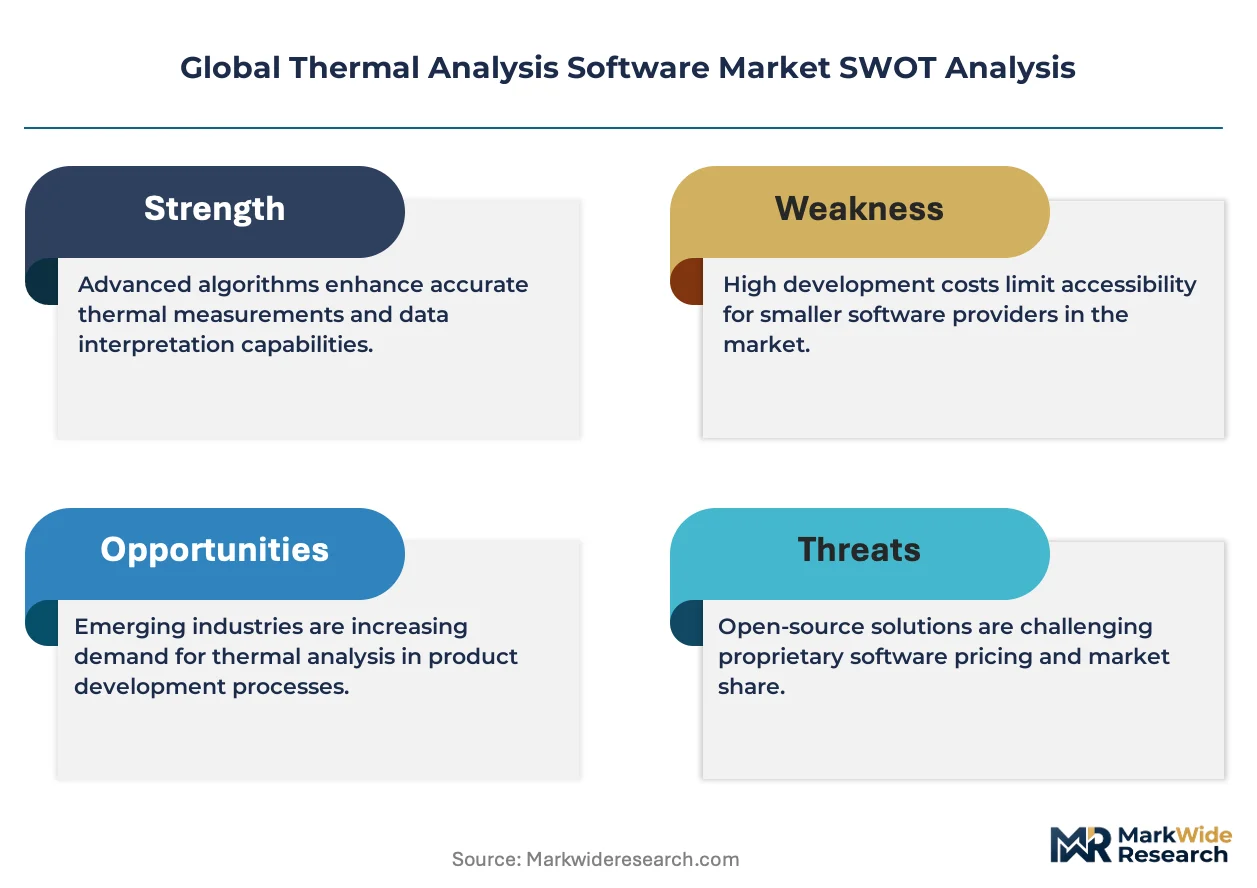
- High-performance computing infrastructure costs:Transient thermal simulations of 3D chip architectures require GPU clusters that mid-size engineering firms cannot justify.
- Open-source solver availability:Academic institutions and cost-conscious R&D labs migrate to free finite element frameworks like CalculiX and Elmer, constraining commercial vendor pricing power.
- Instrument-hardware bundling concentration:Major thermal instrument manufacturers in Germany and the US tie software licenses to hardware purchases, limiting pure-play software penetration.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO stability testing requirements for generic drug exports create demand for thermal characterization software in Hyderabad and Ahmedabad clusters.
- Predictive maintenance module unbundling:Vendors can extract standalone recurring revenue by decoupling AI-driven thermal degradation forecasting from core platform licenses.
- Digital twin integration:Convergence between thermal simulation and IoT sensor streams enables real-time asset monitoring for chemical plant heat exchangers.
Industry Challenges
- Multiphysics simulation expertise scarcity:Engineers capable of coupling thermal, fluid, and structural solvers command salary premiums that stretch mid-market vendor implementation teams.
- FDA validation timeline compression:Pharmaceutical software deployments require documented IQ/OQ/PQ protocols that extend sales-to-revenue recognition cycles by 8-14 months.
- Legacy LIMS integration complexity:Enterprise laboratories demand bidirectional data flows between thermal analysis platforms and decades-old laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Analysis Software Market |
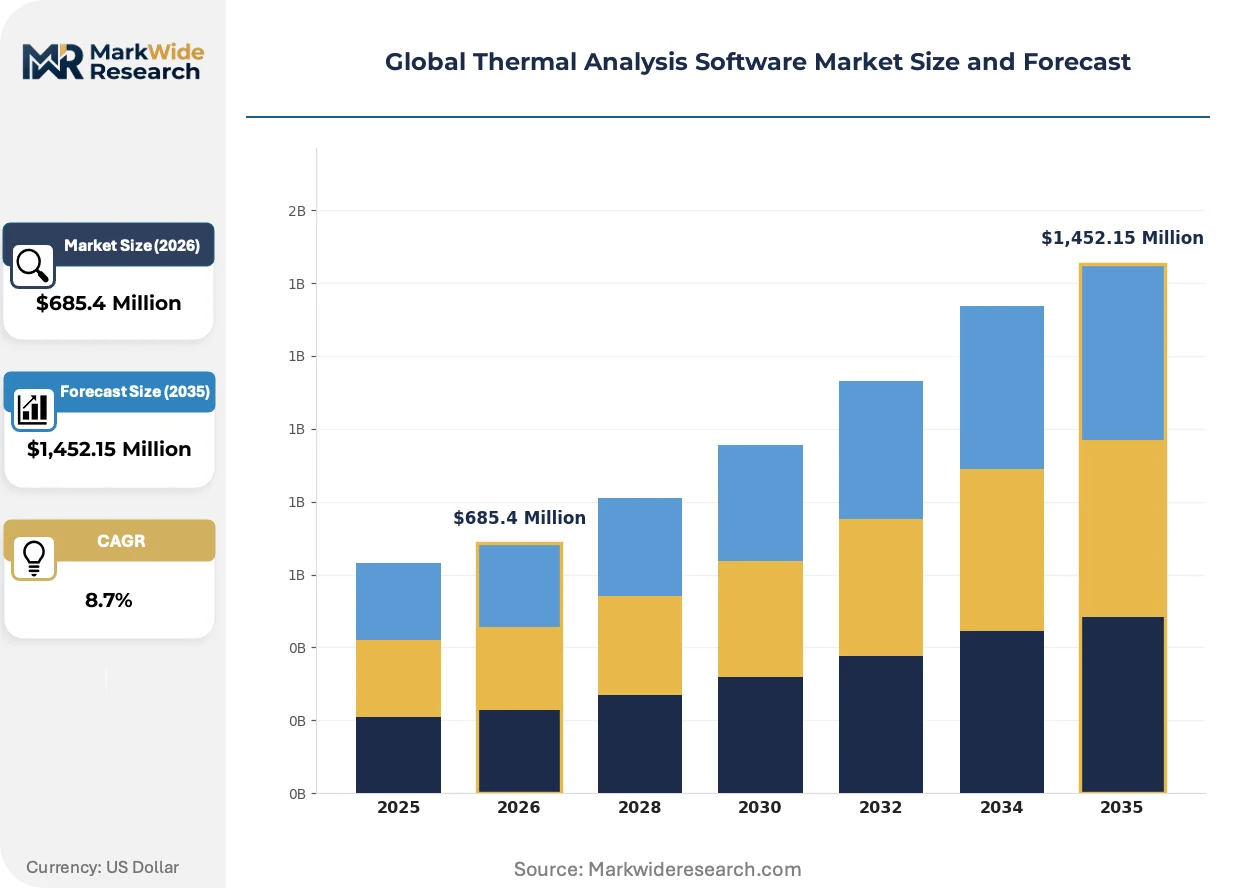
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Offering: Simulation Software, Data Analytics, Monitoring Tools, Visualization Platforms, Reporting Modules Application: Material Testing, Electronics Cooling, Chemical Process Analysis, Energy Systems, Aerospace Component Evaluation End User Industry: Semiconductor Manufacturers, Chemical Processors, Aerospace Fabricators, Academic Institutions, Power Generation Firms |
| Companies Covered | PerkinElmer, Linseis, NETZSCH, Rigaku, Setaram, TA Instruments, Shimadzu, Hitachi High-Tech, Mettler-Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Analysis Software Market Shifts & Advancements
Computational methods and deployment architectures are actively restructuring how thermal simulation capabilities reach end-users, with three convergent shifts altering vendor business models and buyer procurement patterns.
Finite element thermal solvers are migrating from on-premise workstation installations to containerized cloud instances. Semiconductor foundries in Taiwan and South Korea now spin up thousand-core clusters for hours-long transient simulations of advanced packaging architectures, then terminate instances. This consumption pattern compresses perpetual license revenue into usage-based streams that reward elastic infrastructure providers over traditional software vendors.
REACH substance thermal hazard assessments and EU Green Deal embodied carbon tracking requirements are forcing chemical processors to maintain auditable simulation records across material lifecycle stages. ECHA compliance deadlines in 2026 and 2027 are accelerating procurement of software with built-in regulatory reporting templates, particularly among German and Dutch specialty chemical manufacturers.
Enterprise laboratory buyers now unbundle validation and calibration services from core software subscriptions, treating these as separately negotiable line items. Large pharmaceutical and automotive R&D departments in New Jersey and Stuttgart demand itemized service catalogs with fixed-price validation scopes, compressing vendor service margins while extending procurement negotiation cycles.
Global Thermal Analysis Software Market Segmentation
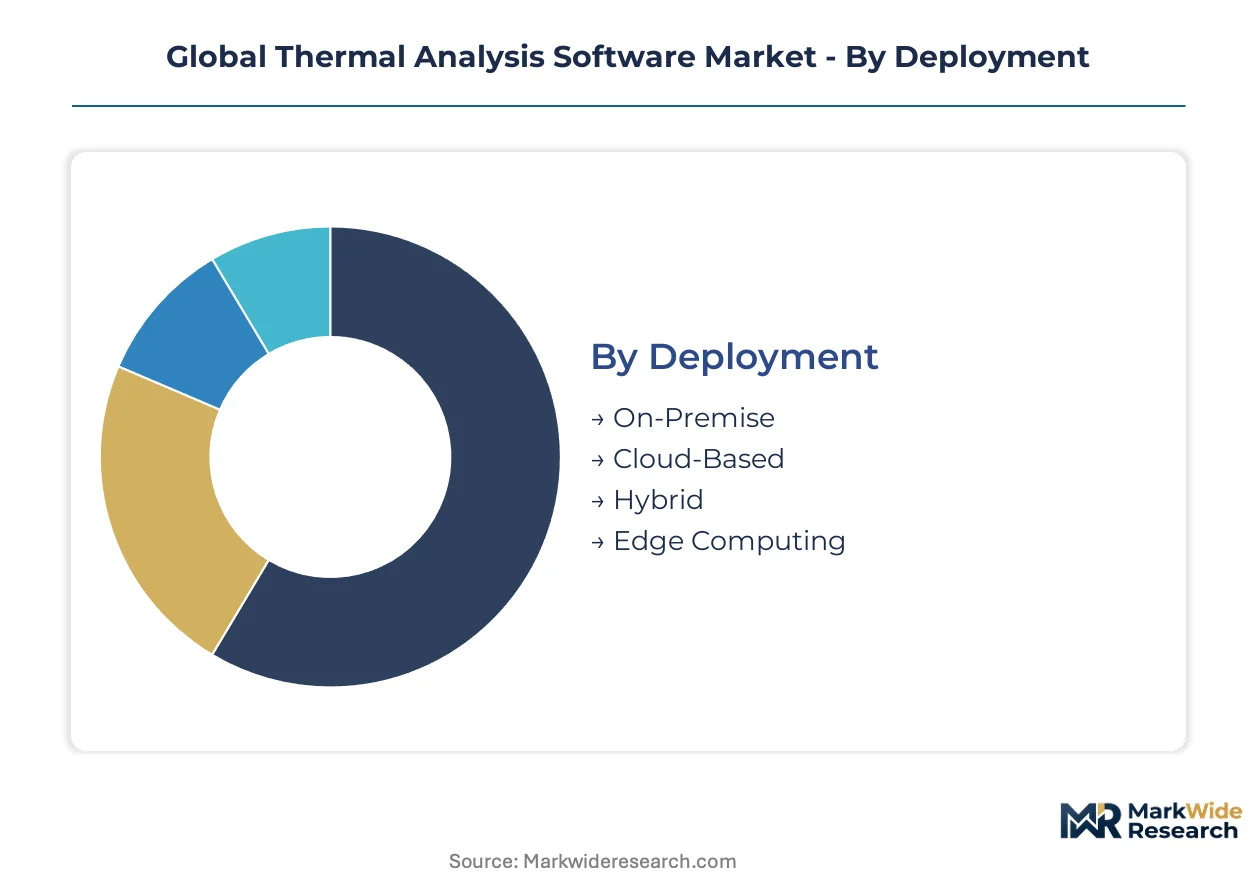
Thermal analysis software vendors structure product portfolios around distinct computational workloads and buyer infrastructure constraints. Deployment architecture, solution depth, and end-use intensity each create separate pricing corridors and competitive battlegrounds.
Deployment:
Engineering teams select infrastructure models based on simulation burst frequency and data sovereignty requirements.
- Cloud-Based:Containerized instances enable semiconductor foundries in Taiwan and South Korea to provision thousand-core clusters for transient chip thermal modeling, then terminate compute resources. Elastic consumption converts perpetual licenses into usage-based revenue streams that favor infrastructure providers over traditional software vendors.
- On-Premise:Perpetual workstation installations persist in defense contractors and pharmaceutical quality control labs where ITAR and FDA 21 CFR Part 11 requirements mandate air-gapped environments. German automotive R&D centers in Stuttgart maintain captive server farms for multiphysics coupling workflows.
- Hybrid:Split architectures allow preprocessing on local workstations with burst compute to cloud for mesh refinement. Chemical processors in Rotterdam deploy this model for REACH compliance simulations.
- Edge Computing:Distributed nodes process thermal sensor streams from chemical plant heat exchangers without round-trip latency to central servers. Power generation firms in Texas deploy edge nodes for real-time turbine monitoring.
The dominant share belongs to On-Premise, while Cloud-Based is closing the gap fastest.
Solution Offering:
Commercial depth determines margin capture and renewal elasticity across buyer segments.
- Simulation Software:Finite element and computational fluid dynamics solvers model heat transfer, phase transitions, and thermal stability. Automotive battery pack designers in Michigan combine thermal, electrical, and mechanical solvers to predict thermal runaway propagation without physical crash testing.
- Data Analytics:Platforms ingest DSC, TGA, and DMA instrument outputs for statistical process control. Academic institutions in Hyderabad leverage analytics modules for generic drug stability studies under CDSCO export requirements.
- Monitoring Tools:Real-time thermal degradation tracking for production line integration. Aerospace fabricators in Toulouse embed monitoring for turbine blade manufacturing qualification.
- Visualization Platforms:3D thermal mapping and immersive rendering for stakeholder communication. Energy systems engineers in Denmark use visualization for district heating network optimization.
- Reporting Modules:Automated documentation for regulatory submission. EMA thermal mapping guidelines drive procurement among Swiss biologics manufacturers.
Simulation Software commands the deepest margin pools, with Data Analytics expanding most quickly.
Application:
Industry-specific validation mandates dictate solver complexity and compliance feature requirements.
- Electronics Cooling:Transient thermal analysis of 3D chip architectures and advanced packaging. GPU cluster requirements constrain mid-size engineering firms from competing with semiconductor manufacturer simulation depth.
- Aerospace Component Evaluation:Turbine blade certification documentation for FAA and EASA submission. Commercial aviation OEMs in Seattle now require thermal simulation archives for new engine programs.
- Material Testing:Polymer and composite characterization for automotive lightweighting. German chemical clusters drive procurement of coupled thermal-mechanical solvers.
- Chemical Process Analysis:Reactor thermal hazard assessment and scale-up safety. EU F-Gas Regulation compliance creates audit-trail requirements for fluorinated gas alternative disclosures.
- Energy Systems:Battery thermal management and grid storage optimization. Power generation firms in Saudi Arabia deploy simulation for solar thermal plant design.
Electronics Cooling holds the largest installed base, though Aerospace Component Evaluation shows the steepest expansion trajectory.
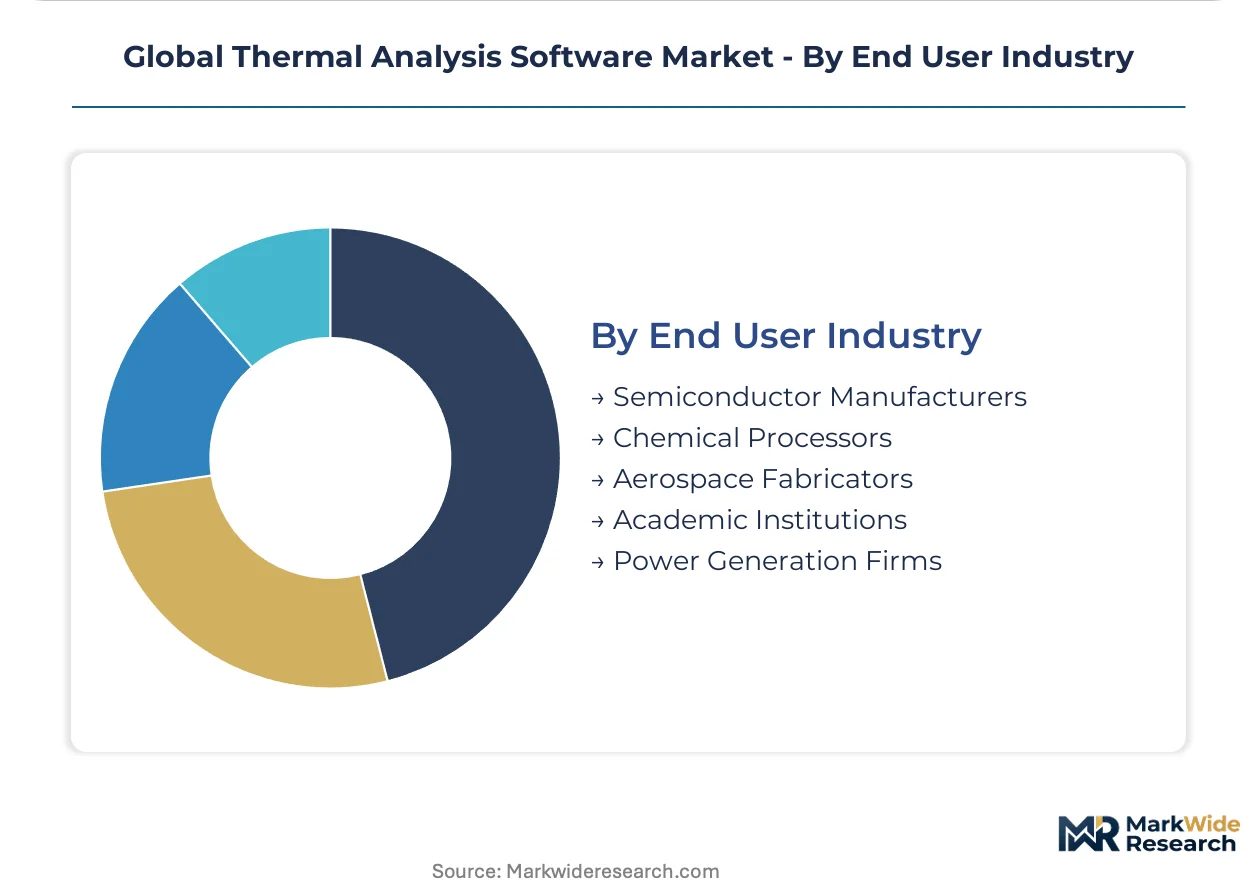
End User Industry:
Procurement sophistication and price sensitivity diverge sharply across buyer maturity.
- Semiconductor Manufacturers:Foundries and IDMs demand elastic compute for architecture-scale thermal verification. Open-source solver migration in academic spin-offs constrains vendor pricing power.
- Chemical Processors:Specialty and commodity chemical producers require REACH and EPA emissions testing protocol compliance. ECHA deadlines in 2026 and 2027 accelerate software procurement with built-in regulatory templates.
- Aerospace Fabricators:Engine OEMs and tier suppliers validate components against FAA and EASA thermal certification standards. Toulouse and Seattle clusters expand simulation documentation requirements.
- Academic Institutions:Universities and national labs train next-generation engineers on thermal characterization. Cost-conscious R&D labs migrate to free finite element frameworks like CalculiX and Elmer.
- Power Generation Firms:Utilities and independent producers optimize heat rate and equipment lifetime. Digital twin integration with IoT sensor streams enables real-time asset monitoring.
Semiconductor Manufacturers account for the dominant revenue share, while Chemical Processors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: semiconductor foundries in Taiwan and South Korea drive elastic cloud compute demand, while German automotive clusters favor perpetual on-premise licenses for multiphysics workflows. European chemical processors prioritize regulatory audit-trail features, whereas US aerospace fabricators emphasize FAA validation documentation.
United States
FDA validation requirements for pharmaceutical thermal characterization and FAA turbine blade certification documentation anchor software procurement. The EPA emissions testing protocols compel chemical processors to maintain auditable simulation records. Aerospace OEMs in Seattle now require thermal simulation archives for new engine programs, expanding enterprise license cycles.
Germany
Automotive battery pack designers and chemical clusters drive coupled thermal-mechanical solver adoption. The EU F-Gas Regulation mandates thermal performance disclosures for fluorinated gas alternatives, creating compliance-driven procurement. Stuttgart R&D centers maintain captive server farms for multiphysics workflows, resisting cloud migration.
China
Semiconductor foundries demand elastic compute for advanced packaging thermal verification. NMPA stability testing requirements for pharmaceutical exports create software demand in manufacturing clusters. Yangtze River Delta fabrication facilities provision thousand-core cloud instances for transient chip simulations.
Japan
Materials characterization laboratories and electronics manufacturers prioritize deep calibration protocols. METI industrial standards shape thermal simulation requirements for automotive lightweighting programs. Osaka-based polymer research institutes sustain demand for high-precision DSC data analytics modules.
South Korea
Memory and logic foundries drive consumption-based cloud simulation for 3D chip architectures. MFDS pharmaceutical export requirements expand thermal characterization software adoption. Samsung and SK Hynix supplier ecosystems in Suwon and Icheon spin up elastic compute clusters for hours-long transient analyses.
Global Thermal Analysis Software Market Competitive Landscape
Capability concentration sits with instrument-integrated specialists; scale advantage sits with diversified analytical platforms. The vendor base structures around three tiers: thermal instrument manufacturers bundling software licenses, pure-play simulation developers, and cloud-native multiphysics platforms. Dominant competitive moves include hardware-software unbundling responses and predictive maintenance module decoupling.
Within the instrument-integrated tier, NETZSCH, TA Instruments, and PerkinElmer exemplify divergent strategic postures. NETZSCH leverages its thermal instrument installed base to cross-sell integrated workflows. TA Instruments occupies a premium positioning through calibration protocol depth that locks in repeat analytical cycles. PerkinElmer anchors cloud migration roadmaps for enterprise laboratories seeking centralized data governance. These three represent how hardware origin shapes software monetization architecture.
| Leading Market Players |
|---|
| PerkinElmer |
| Linseis |
| NETZSCH |
| Rigaku |
| Setaram |
| TA Instruments |
| Shimadzu |
| Hitachi High-Tech |
| Mettler-Toledo |
| Others |
Supply & Pricing Matrix
Stuttgart's captive server farms for multiphysics thermal workflows anchor European pricing power, as German automotive R&D clusters resist cloud migration and sustain premium perpetual license structures that semiconductor foundries in Asia cannot command.
Pricing Analysis
Long-term enterprise contracts dominate procurement for pharmaceutical quality control labs bound by FDA 21 CFR Part 11 requirements, while spot consumption models capture semiconductor foundries spinning up thousand-core cloud clusters for transient chip simulations. Price differentiation rests on validation protocol depth and calibration certification tiers, with TA Instruments commanding premiums through locked analytical cycles. Pricing pressure intensifies as open-source solvers like CalculiX and Elmer constrain academic segment willingness-to-pay. Academic institutions exhibit highest price sensitivity; aerospace engine OEMs in Toulouse and Seattle demonstrate lowest sensitivity due to mandatory certification documentation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard as German instrument manufacturers and US analytical platform vendors manage working capital across bundled hardware-software transactions. Software development concentrates in Germany, the United States, and Japan, with thermal instrument manufacturing anchored in these same geographies. Raw material dependencies include GPU compute clusters for cloud-native solvers, precision sensor arrays for instrument integration, and specialized finite element meshing libraries. Single-source vulnerability runs through NVIDIA's dominance in GPU acceleration for transient thermal simulations. Distribution runs through direct enterprise sales teams for large pharmaceutical and automotive accounts, with channel partners serving mid-size chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: FDA validation timelines and EMA thermal mapping guidelines create 8-14 month switching costs that lock pharmaceutical laboratories into incumbent ecosystems.
For Market Incumbents: Insulate recurring revenue streams by decoupling predictive maintenance modules from core platform licenses, extracting standalone AI-driven thermal degradation forecasting subscriptions. Deepen calibration protocol investments to lock in repeat analytical cycles against open-source solver substitution. Prioritize cloud migration roadmaps for enterprise laboratories seeking centralized data governance, anchoring switching costs through integrated instrument-software workflows. For New Entrants and Emerging Players: Mid-market engineering firms in India unable to justify GPU cluster infrastructure for transient chip simulations represent the most penetrable entry point, particularly CDSCO compliance-driven generic drug manufacturers in Hyderabad and Ahmedabad. Cloud-native multiphysics platforms with usage-based pricing can displace perpetual license incumbents among cost-conscious R&D labs. Target pharmaceutical export manufacturers facing accelerated stability testing requirements with regulatory-reporting-automation as the primary go-to-market wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among instrument-integrated specialists with captive hardware installed bases enabling cross-sell workflows. Long-term viability favors vendors with regulatory validation depth across FDA, EMA, and EPA compliance frameworks. Acquisition targets should demonstrate established IQ/OQ/PQ protocol libraries and entrenched relationships with aerospace certification authorities. Monitor ECHA compliance deadline acceleration in 2026 and 2027 as inflection indicators for European chemical processor software procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Module Unbundling | AI-driven thermal degradation forecasting creates standalone recurring revenue streams from pharmaceutical QC labs. |
| Cloud-Native Multiphysics Platform Launch | Containerized elastic compute captures semiconductor foundry demand in Taiwan and South Korea. |
| Regulatory Validation Protocol Investment | FDA 21 CFR Part 11 and EMA thermal mapping compliance deepens switching costs for life sciences laboratories. |
| Digital Twin Integration Partnership | IoT sensor stream convergence enables real-time asset monitoring for chemical plant heat exchangers. |
| Academic Open-Source Migration Response | Freemium tier introduction constrains CalculiX and Elmer substitution among price-sensitive R&D institutions. |
Research Methodology
Initial hypotheses were tested against primary input from thermal instrument product managers, pharmaceutical regulatory affairs leads, aerospace engine certification engineers, and chemical process safety officers, and refined through secondary validation against SEC 10-K filings, EMA submission databases, EPA emissions testing protocols, and customs trade data for thermal analysis equipment. Bottom-up triangulation across deployment model adoption rates and top-down cross-check against end-user industry procurement patterns anchored market sizing.
Demand-supply-balance framing structured the analytical framework across the analysis window, with segmentation modeled across deployment architecture, solution depth, application intensity, and end-user industry maturity. CAGRs were derived from elasticity-adjusted adoption curves and regulatory deadline acceleration effects. Forecast inputs incorporated semiconductor foundry capex cycles for GPU cluster provisioning and pharmaceutical export compliance timeline compression under CDSCO and MFDS requirements.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, pharmaceutical R&D budget allocations, or chemical processing capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory deadline adherence and open-source solver substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Employee Wellness Software Market
Software & Services
Content Moderation Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Global Animation Software Market
Software & Services
Online Recruitment Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
MCAD Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Video Server Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Global Note Taking App Market
Software & Services
Global Linux Operating System Market
Software & Services
Compositing Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Deck Design Software Market