
 Global Space Planning Software Market | 2026-2036
Global Space Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Space Planning Software Market Foresight
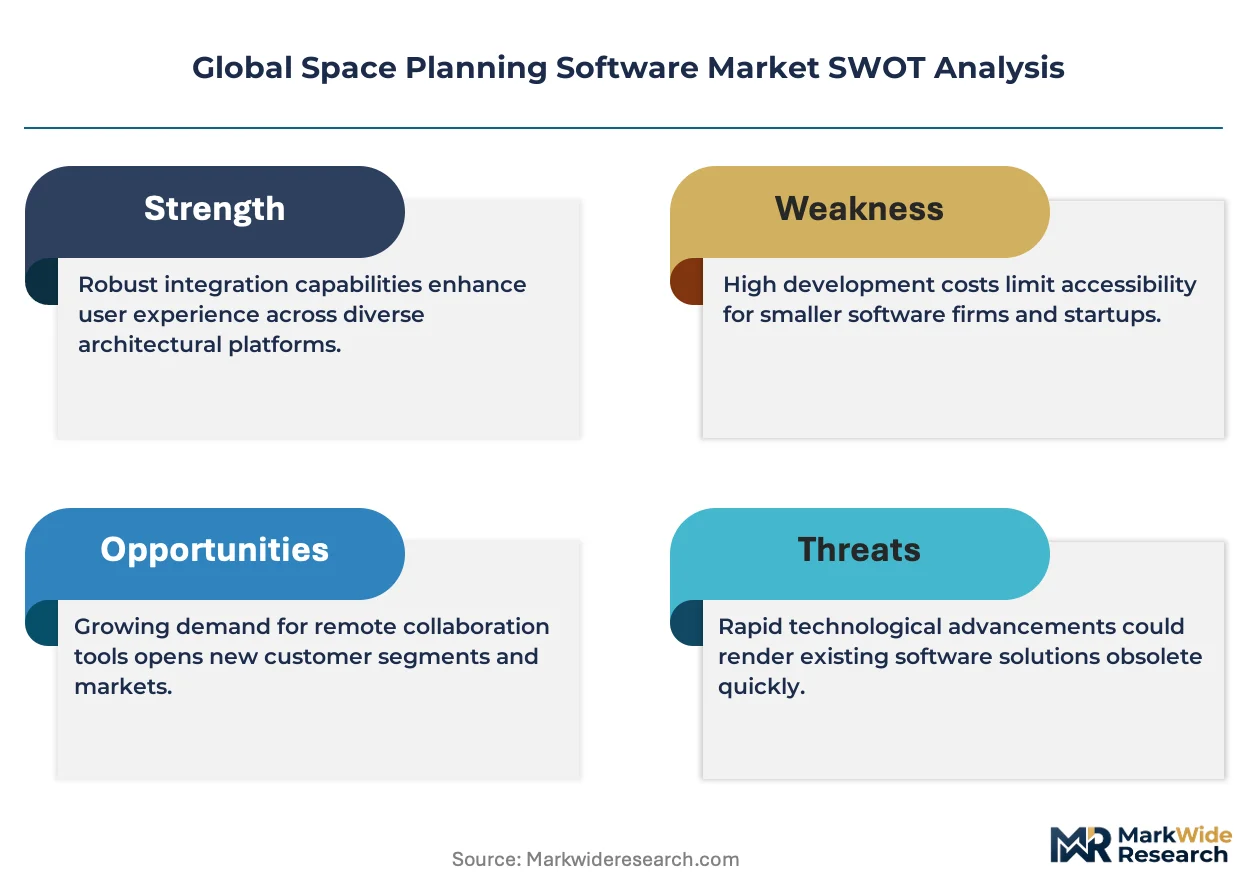
Enterprise-grade BIM compatibility is reorganizing competitive dynamics across the space planning software landscape. Trimble Inc. leverages its geospatial heritage to anchor positions in construction-adjacent facility workflows. IBM Corporation sustains relevance through ERP integration depth and hybrid cloud infrastructure. FM:Systems competes on pure-play specialization, dominating higher education and healthcare verticals with purpose-built asset tracking modules.
Space planning software encompasses digital tools that model, analyze, and optimize physical environments through parametric floor plan generation, occupancy sensor integration, and real-time square-footage allocation algorithms. These platforms serve commercial and institutional operators seeking to minimize wasted capacity, streamline move management, and satisfy sustainability reporting requirements. Cloud-based deployment now leads solution delivery, while BIM support commands premium pricing due to engineering-grade accuracy demands and cross-disciplinary coordination requirements. Facility management suites retain the largest installed base, though space utilization analyzer modules are expanding fastest as IoT sensor networks mature and occupancy analytics penetrate mid-market accounts.
ISO 19650 information management standards and the EU Green Deal building performance frameworks are elevating data interoperability and energy disclosure requirements across major construction and real estate markets. The EPA's ENERGY STAR certification pathways in the United States similarly tie software procurement to measurable efficiency outcomes. Stakeholders must evaluate integration roadmaps against evolving regulatory data standards rather than isolated feature comparisons.
Market Dynamics
Hybrid workplace permanence is forcing facility managers to abandon static floor plans for algorithmic space allocation that responds to real-time occupancy telemetry rather than fixed headcount assumptions.
Growth Catalysts
- EU Green Deal building mandates:Member states now require energy performance certification for commercial structures above specific thresholds, compelling property operators to deploy software that models thermal zones alongside spatial layouts.
- IoT sensor maturation:Bluetooth Low Energy and millimeter-wave occupancy detectors have reached cost parity with manual audit methods, enabling mid-market office portfolios to justify automated utilization tracking.
- Healthcare vertical expansion:Hospital systems in the United States are retrofitting aging campuses with modular room configurations that demand parametric planning tools to manage infection-control protocols and equipment density.
Market Restraints
- Data interoperability friction:ISO 19650 compliance requires costly middleware development to bridge legacy CAD formats with modern cloud-native platforms, extending implementation timelines.
- Concentrated cloud infrastructure:Three hyperscale providers dominate hosting for space planning SaaS, creating single-point-of-failure exposure for facility operators in regulated industries.
- Technical talent scarcity:BIM-certified space planners command premium compensation that mid-size architecture firms cannot absorb, constraining solution deployment velocity.
Strategic Opportunities
- Underpenetrated Indian commercial real estate:Mumbai and Bangalore office construction is accelerating without corresponding software adoption, presenting first-mover advantage for localized platform entrants.
- AI-assisted generative design:Machine learning algorithms that propose optimal furniture arrangements from natural language prompts are converging with traditional CAD engines, opening subscription tiers below enterprise price points.
- Japan's building efficiency subsidies:METI incentive programs for smart building retrofits explicitly cover software procurement costs, reducing customer acquisition friction for qualified vendors.
Industry Challenges
- Cross-functional workflow integration:Facility teams struggle to synchronize space planning data with HR systems managing hot-desking permissions and IT asset inventories, creating shadow spreadsheets that undermine platform value.
- Certification timeline compression:BREEAM and LEED version updates are accelerating faster than software certification cycles, leaving vendors perpetually behind current standard requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Space Planning Software Market |
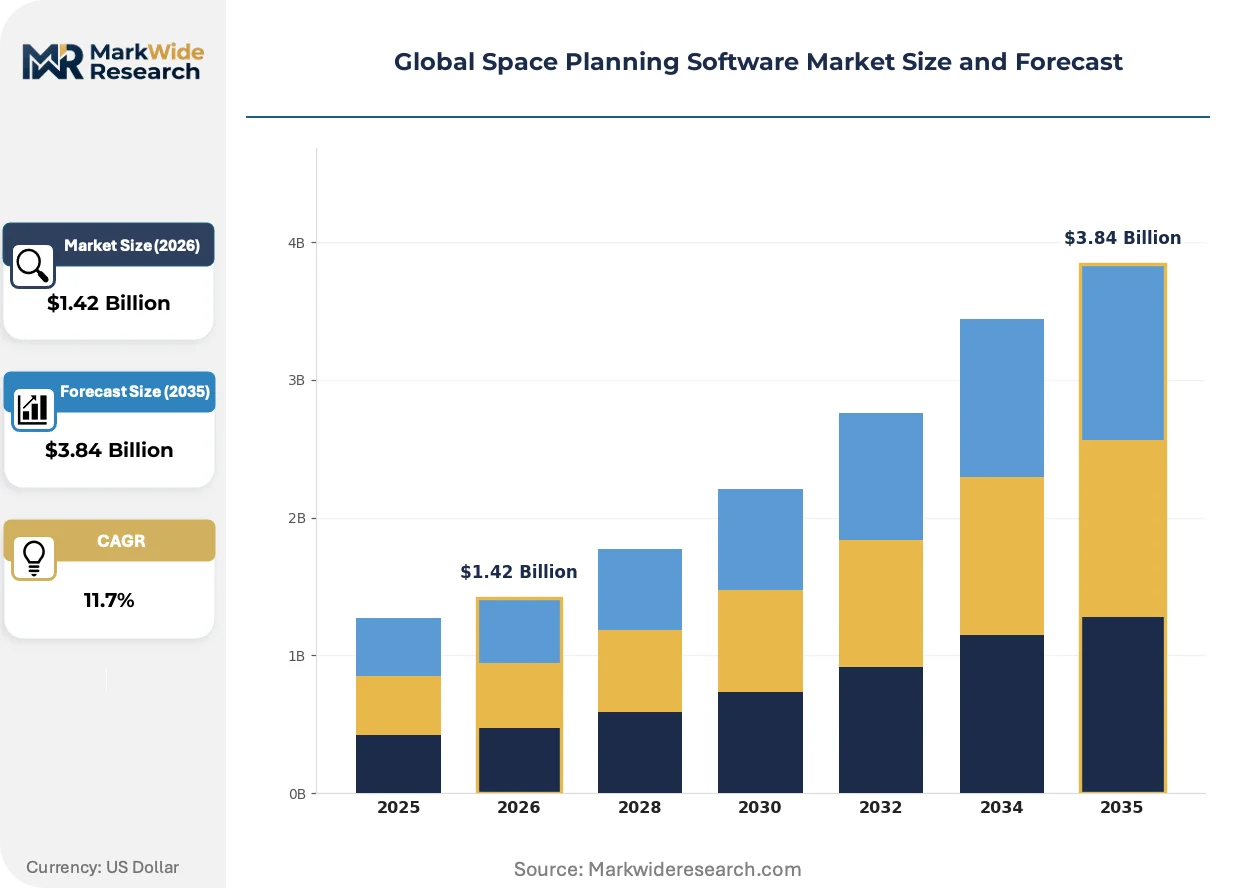
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Room Layout Planner, Facility Management, Asset Tracking, Workflow Optimization, Space Utilization Analyzer Deployment Mode: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Services End User Sector: Commercial Offices, Educational Institutes, Government Agencies, Event Venues, Co-Working Spaces Integration Capability: ERP Integration, CAD Compatibility, BIM Support, IoT Connectivity, Facility Security Systems |
| Companies Covered | IBM Corporation, Accruent, Trimble Inc., FM:Systems, Planon, Archibus, OfficeSpace Software, SpaceIQ, iOFFICE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Space Planning Software Market Shifts & Advancements
Computational design methods are displacing manual drafting across the facility lifecycle, with implications stretching from initial lease analysis through decommissioning workflows.
Digital twin technology is bifurcating the market between lightweight visualization tools for tenant experience and engineering-grade simulation platforms for MEP coordination. Corporate real estate teams in the United States are adopting the lighter variant for portfolio dashboards, while construction-adjacent facility managers demand physics-based thermal and airflow modeling. This divergence is compressing vendor R&D budgets as they attempt to serve incompatible accuracy requirements without dedicated product lines.
CSRD disclosure mandates in Europe are elevating embodied carbon tracking from voluntary feature to procurement prerequisite. Software platforms must now calculate and report whole-life carbon impacts of interior fit-outs and material selections. German and French commercial landlords are responding fastest, embedding these capabilities into standard lease negotiation workflows ahead of 2025 reporting deadlines.
Subscription fatigue among mid-market facility operators is fragmenting buying committees that previously consolidated software procurement under IT departments. Individual business units now pilot point solutions for specific use cases—move management, desk booking, or energy analytics—creating integration debt that central governance struggles to reverse. This pattern is most visible in United States healthcare systems where departmental autonomy resists standardization mandates from corporate real estate functions.
Global Space Planning Software Market Segmentation
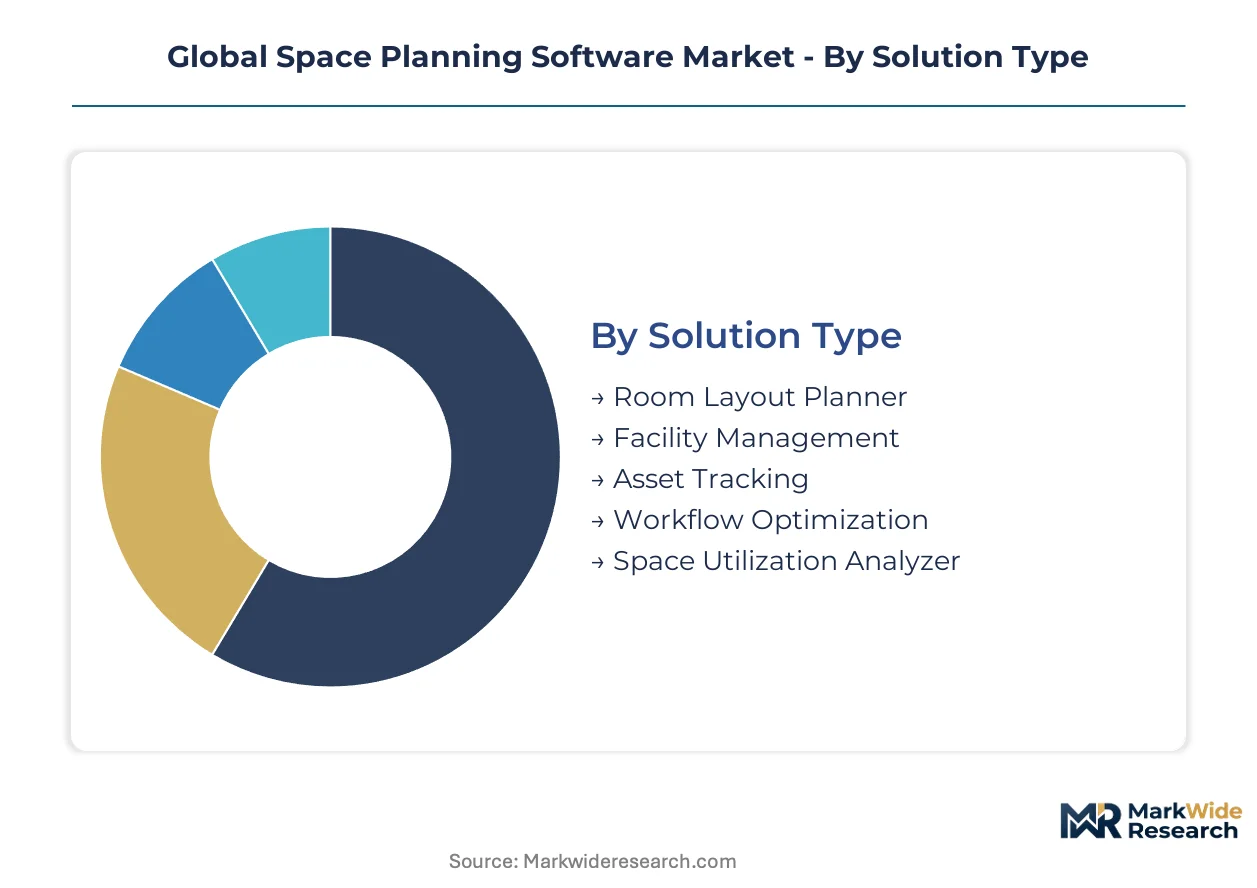
Segmentation in space planning software reveals how procurement decisions fragment across technical sophistication, infrastructure constraints, and regulatory exposure. Buyers prioritize different capability bundles depending on whether they manage single-tenant corporate portfolios or multi-use institutional campuses.
Solution Type:
Premium margin pools concentrate in modules that combine real-time sensor ingestion with predictive analytics, while commoditized floor-planning tools face pricing pressure from free CAD alternatives.
- Room Layout Planner:Parametric drafting tools generate 2D and 3D spatial configurations with furniture libraries and code-compliance checking. Demand clusters in United States architecture firms serving landlord rep assignments, where rapid test-fit turnaround wins competitive mandates.
- Facility Management:Integrated work order, lease administration, and capital planning modules anchor enterprise procurement decisions. German commercial landlords driving EU Green Deal compliance are expanding deployment fastest as energy performance certification deadlines approach.
- Asset Tracking:RFID and barcode-enabled inventory systems monitor movable equipment location and condition.
- Workflow Optimization:Move management and project coordination tools streamline churn scenarios.
- Space Utilization Analyzer:Occupancy sensor aggregation platforms deliver density heatmaps and peak-load forecasting.
The dominant share belongs to Facility Management, while Space Utilization Analyzer is closing the gap fastest.
Deployment Mode:
Customer infrastructure maturity and data sovereignty requirements split procurement between elastic cloud consumption and controlled on-premise environments.
- Cloud-Based:Multi-tenant SaaS architectures enable rapid scaling across distributed facility portfolios without capital expenditure. United States healthcare systems with departmental autonomy favor this model for pilot projects that bypass centralized IT procurement.
- On-Premise:Single-tenant installations behind customer firewalls satisfy national security and patient privacy mandates. Government agencies in France and Germany specify this deployment for classified or sensitive facility data under GDPR and national security frameworks.
- Hybrid:Split architectures keep sensitive core data local while pushing analytics to cloud tiers.
- SaaS:Subscription-native platforms with API-first design patterns dominate mid-market adoption.
- Hosted Services:Managed private cloud deployments offer dedicated infrastructure without operational burden.
Cloud-Based architectures command the largest installed base, though Hybrid configurations are expanding most quickly among regulated industries.
End User Sector:
Procurement sophistication varies sharply across sectors, with some buyers treating space planning as strategic infrastructure and others as administrative overhead.
- Commercial Offices:Corporate real estate teams optimize hybrid workplace ratios and desk-sharing coefficients. United States enterprise portfolios with 500,000+ square feet under management drive premium solution uptake as return-to-office policies stabilize.
- Educational Institutes:Universities and K-12 districts manage semesterly classroom scheduling and research lab allocation. FM:Systems dominates this vertical in North America with purpose-built academic calendaring modules that integrate with student information systems.
- Government Agencies:Public sector procurement emphasizes interoperability standards and accessibility compliance.
- Event Venues:Convention centers and stadiums require rapid reconfiguration tools for varying audience capacities.
- Co-Working Spaces:Flexible office operators need member-facing booking interfaces and dynamic pricing engines.
Commercial Offices retain the deepest penetration, while Co-Working Spaces are gaining share fastest as operator consolidation creates procurement scale.
Integration Capability:
Technical stickiness in this market derives from how effectively platforms bridge into adjacent enterprise systems rather than standalone feature depth.
- BIM Support:Engineering-grade building information modeling compatibility enables MEP coordination and clash detection. Construction-adjacent facility managers in Japan and Germany demand physics-based thermal simulation that lightweight visualization tools cannot deliver.
- ERP Integration:Financial system connectivity automates lease accounting, depreciation schedules, and capital project budgeting. IBM Corporation sustains competitive position through pre-built connectors to SAP and Oracle environments.
- CAD Compatibility:Legacy drawing format support preserves investment in historical documentation.
- IoT Connectivity:Sensor network ingestion protocols enable real-time occupancy analytics.
- Facility Security Systems:Access control and surveillance integration correlates physical presence with spatial authorization.
BIM Support commands the highest pricing premiums, though IoT Connectivity is climbing the fastest as sensor networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software procurement flows reveal a pronounced import dependency outside North America and Western Europe, where domestic development capabilities remain concentrated. The United States runs a substantial surplus in space planning software exports, while Asia-Pacific markets absorb foreign platforms with limited local alternatives.
United States
Enterprise facility portfolios exceeding 500,000 square feet drive premium solution uptake as return-to-office policies stabilize occupancy forecasting needs. The EPA's ENERGY STAR certification pathways tie software procurement to measurable efficiency outcomes, compelling vendors to embed carbon reporting modules. Corporate real estate teams in Manhattan and Chicago anchor demand for hybrid workplace optimization tools.
Germany
Commercial landlords retrofit aging portfolios to meet EU Green Deal building performance certification deadlines, accelerating facility management suite deployments. The country's federal building efficiency mandates require thermal zone modeling alongside spatial layouts, elevating BIM-compatible platforms. Berlin and Frankfurt property operators lead procurement velocity for whole-life carbon tracking capabilities.
Japan
METI incentive programs for smart building retrofits explicitly cover software procurement costs, reducing customer acquisition friction for qualified vendors. Physics-based thermal and airflow modeling demands from construction-adjacent facility managers command engineering-grade simulation accuracy. Osaka and Nagoya industrial districts concentrate deployment of MEP coordination platforms.
India
Mumbai and Bangalore office construction accelerates without corresponding software adoption, presenting first-mover advantage for localized platform entrants. The country's national building code modernization creates compliance windows that favor cloud-native deployment models. Hyderabad's technology park developers pilot sensor-integrated utilization analytics for speculative commercial projects.
United Kingdom
CSRD disclosure mandates elevate embodied carbon tracking from voluntary feature to procurement prerequisite for commercial landlords. London property operators embed whole-life carbon calculation capabilities into standard lease negotiation workflows ahead of reporting deadlines. The Southeast corridor concentrates demand for lightweight digital twin visualization tools serving tenant experience dashboards.
Global Space Planning Software Market Competitive Landscape
Listed leaders compete with private specialists across integration depth and vertical focus dimensions, producing a tiered structure where scale advantages clash with domain expertise. Publicly traded technology conglomerates leverage balance sheet capacity for platform consolidation, while venture-backed pure-plays capture narrow workflow segments. Three strategic archetypes dominate: ERP-anchored suites, BIM-native construction extenders, and vertical-specific facility specialists. Competitive moves concentrate on API ecosystem expansion and geographic localization partnerships rather than direct price confrontation.
Within the vertical specialist tier, FM:Systems exemplifies pure-play positioning through higher education and healthcare concentration, while Trimble Inc. anchors construction-adjacent workflows leveraging geospatial heritage. IBM Corporation occupies the integration-centric archetype, sustaining relevance through ERP connector depth and hybrid cloud infrastructure deployment. These three entities represent distinct competitive vectors rather than overlapping contestation, reducing direct rivalry intensity despite shared market participation.
| Leading Market Players |
|---|
| IBM Corporation |
| Accruent |
| Trimble Inc. |
| FM:Systems |
| Planon |
| Archibus |
| OfficeSpace Software |
| SpaceIQ |
| iOFFICE |
| Others |
Supply & Pricing Matrix
EU Green Deal building performance certification gates both vendor qualification and price differentiation simultaneously, as platforms lacking thermal zone modeling capabilities face exclusion from German and French procurement tenders while BIM-compatible modules command subscription premiums over visualization-only alternatives.
Pricing Analysis
Enterprise facility managers anchor pricing stratification across premium, standard, and economy tiers, with BIM-certified engineering modules fetching the highest rates due to ISO 19650 compliance requirements and physics-based simulation depth. Price differentiation hinges on sensor integration density and ERP connector breadth, particularly SAP and Oracle pre-built adapters. Cost compression in the mid-market SaaS tier intensifies as free CAD alternatives encroach on basic floor-planning functionality. Healthcare systems with departmental autonomy exhibit the sharpest price sensitivity, while construction-adjacent facility managers prioritize accuracy over cost.
Supply Chain Analysis
Inventory cycles for IoT sensor hardware stretch deployment timelines as Bluetooth Low Energy and millimeter-wave component availability fluctuates. Software development concentrates in the United States, Germany, and Japan, with cloud infrastructure drawing from hyperscale providers in Ireland, Singapore, and Virginia. Raw material dependencies span semiconductor foundry capacity, rare earth elements for sensor magnetics, and optical-grade glass for LiDAR modules. Single-source vulnerability in millimeter-wave chip fabrication creates supply chain risk. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The space planning software market sits in early-cycle expansion as hybrid workplace permanence forces facility managers to abandon static floor plans for algorithmic allocation systems.
For Market Incumbents: Shield installed base erosion by accelerating API ecosystem expansion to counter modular point solutions encroaching on move management and desk booking workflows. Deepen vertical integration into sensor hardware partnerships to secure data pipeline control. Invest in ISO 19650 certification maintenance ahead of BREEAM and LEED version updates that outpace vendor compliance cycles. For New Entrants and Emerging Players: Differentiate on AI-assisted generative design capabilities that propose optimal furniture arrangements from natural language prompts, opening subscription tiers below enterprise price points. Target Mumbai and Bangalore commercial real estate developers as first-mover opportunities where office construction accelerates without corresponding software adoption. Pursue METI-qualified vendor status to capture Japan's building efficiency subsidy coverage for software procurement costs. For Investors and Strategic Acquirers: Carve-out targets emerge from construction technology conglomerates divesting non-core facility management modules to refocus on core BIM authoring tools. Long-term viability favors platforms with demonstrated healthcare and higher education vertical penetration where switching costs accumulate through student information system and electronic health record integrations. Watch for inflection when Indian national building code modernization creates compliance windows favoring cloud-native deployment models.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures bridge space planning data with HR hot-desking permissions and IT asset inventories. |
| Acquisition of Specialist Firm | Pure-play sensor analytics vendors add real-time occupancy ingestion to legacy facility management suites. |
| Geographic Expansion | Localized platform entrants capture Mumbai and Bangalore commercial real estate construction acceleration. |
| Strategic Partnership | Hyperscaler alliances resolve single-point-of-failure exposure for regulated industry facility operators. |
| Product Launch | CSRD-compliant embodied carbon tracking modules satisfy German and French landlord lease negotiation workflows. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with corporate real estate directors, facility management VPs, BIM coordinators, and IoT systems integrators; and secondary validation against SEC filings of listed software vendors, EPA ENERGY STAR certification databases, EU Green Deal implementation guidance documents, and METI smart building retrofit program disclosures. Bottom-up sizing of sensor deployment volumes and top-down triangulation against facility management suite subscription revenues ensured cross-verification.
Across the projection horizon, the analytical framework modeled deployment mode, end-user sector verticality, integration complexity tier, and regional adoption pattern. CAGRs were derived from segment-level growth rate reconciliation against macro facility construction indicators and software penetration benchmarks. Forecast inputs included IoT sensor cost curves and hybrid workplace policy stability assumptions.
Forecasts assume regulatory continuity in EU Green Deal implementation, EPA ENERGY STAR pathways, and METI incentive programs; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
API Management Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Data Pipeline Tools Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Hiking Apps Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
India ICT Market
Digital Solutions
File Sharing Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Online Hyper-Local Services Market