
 Asia Pacific Content Services Platform Market | 2026-2036
Asia Pacific Content Services Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Content Services Platform Market Outlook
Platform licensing revenue is rewriting margin economics across the Asia Pacific Content Services Platform landscape as vendors shift from perpetual licenses to recurring subscription frameworks. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise deployments across Japan and South Korea. IBM Corporation sustains competitive positioning through hybrid cloud architectures that navigate stringent data residency requirements. OpenText Corporation specializes in document-intensive verticals, extending its footprint among Australian financial institutions.
A content services platform integrates document management, workflow orchestration, and digital asset repositories through API-first architectures that enable federated content access across distributed systems. The technology serves commercial and industrial users by unifying structured and unstructured data into searchable, governable information layers. Cloud-based deployment models are capturing the fastest expansion as SMEs across Indonesia and Vietnam bypass on-premises infrastructure investments. Workflow automation services concentrate margin pools in financial services and healthcare verticals where compliance audit trails command premium pricing. Document management remains the mature revenue base, though collaboration tools are displacing legacy file-sharing protocols in education and government sectors.
TRAI's data localization guidelines in India, Australia's Privacy Act amendments, and Japan's APPI cross-border transfer rules collectively reshape product architecture requirements for vendors operating across the region. The EU AI Act's extraterritorial reach further pressures platforms serving multinational enterprises with European operations to embed algorithmic transparency and consent management capabilities. Stakeholders must weigh sovereign cloud mandates against interoperability standards when selecting deployment architectures for multi-country operations.
Market Dynamics
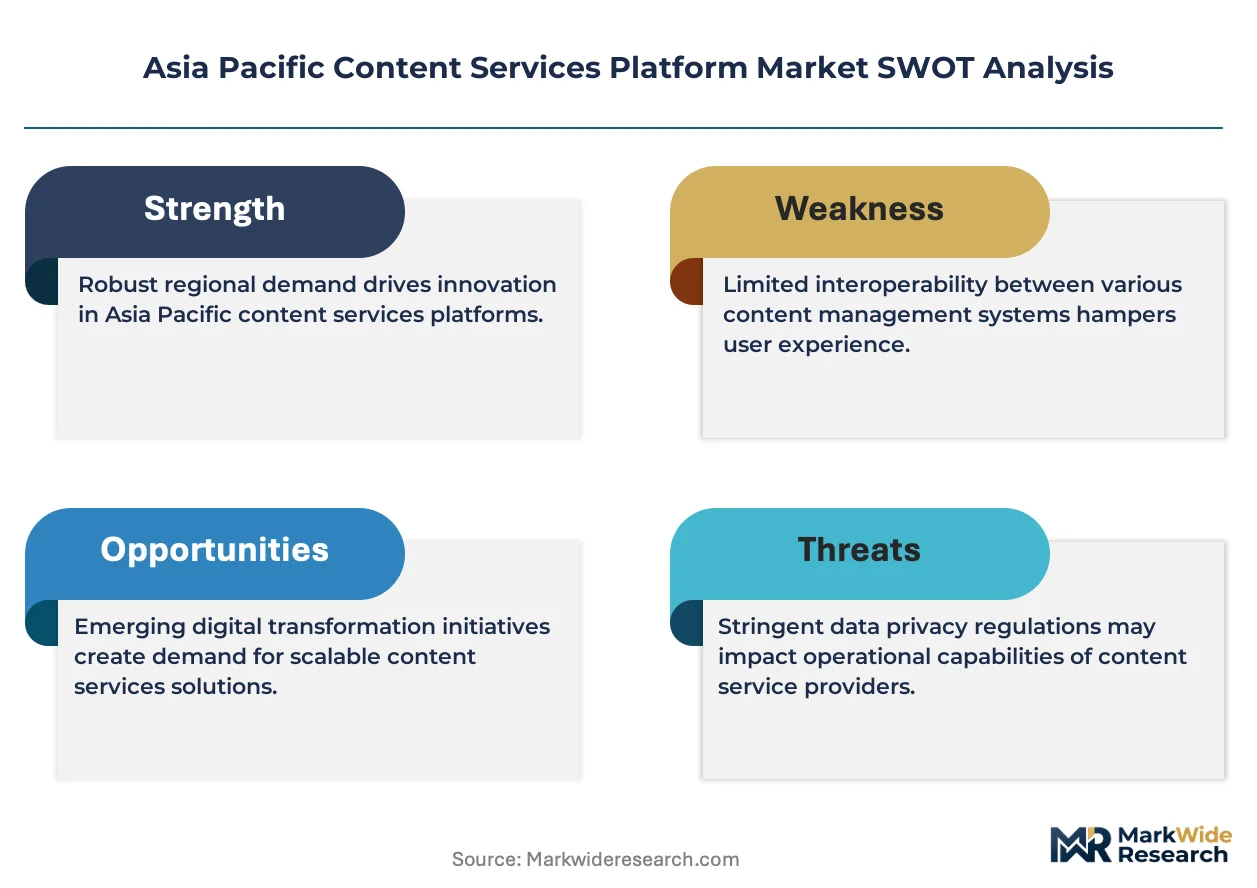
Platform vendors across Asia Pacific are restructuring product roadmaps around sovereign cloud mandates, forcing architectural pivots that privilege data residency compliance over interoperability optimization.
Growth Catalysts
- TRAI Localization Guidelines:India's data residency rules compel domestic enterprises to adopt compliant content repositories, expanding addressable market for certified platform providers.
- Financial Services Digitization:Southeast Asian banks are consolidating compliance documentation onto unified platforms to satisfy cross-border audit requirements.
- API-First Architecture:Federated content access protocols enable distributed system integration without wholesale infrastructure replacement.
Market Restraints
- Data Center Concentration:Cloud capacity bottlenecks in Indonesia and Vietnam limit deployment velocity for latency-sensitive workflows.
- Fragmented Standards:Incompatible national encryption protocols across Japan, Australia, and Singapore force redundant engineering effort.
- Legacy System Entrenchment:On-premises document management installations in Japanese manufacturing create switching friction.
Strategic Opportunities
- Vietnam SME Segment:Cloud-native bypass strategies among small enterprises avoid capital-intensive infrastructure buildouts entirely.
- Healthcare Workflow Automation:Diagnostic imaging archives and patient record interoperability present untapped vertical expansion.
- PLI Scheme Tailwinds:India's production-linked incentives for IT hardware manufacturing reduce cloud infrastructure costs for domestic platform operators.
Industry Challenges
- Cross-Border Transfer Complexity:Japan's APPI requirements and Australia's Privacy Act amendments impose conflicting technical specifications on multi-country deployments.
- Integration Talent Scarcity:Shortage of engineers fluent in both legacy ECM protocols and modern container orchestration constrains implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Content Services Platform Market |
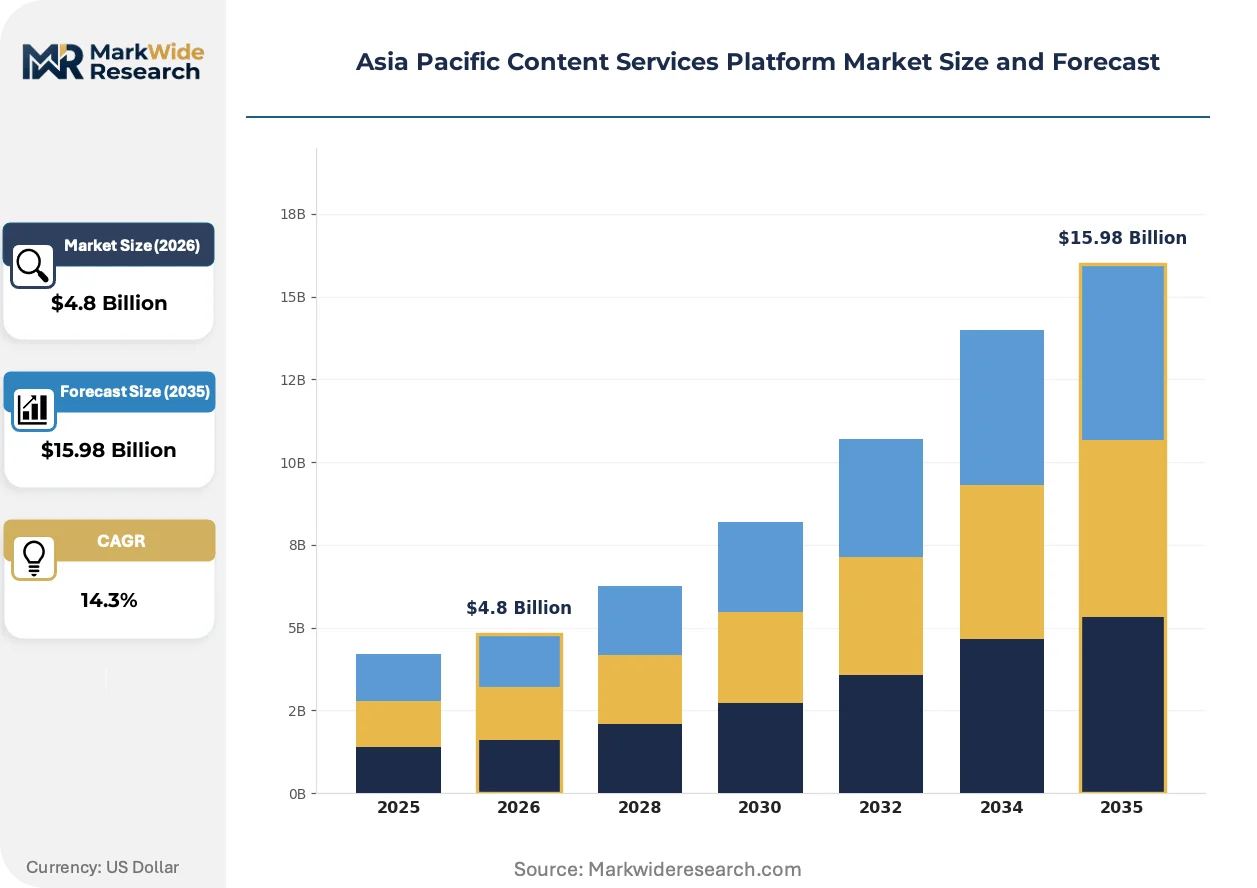
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.98 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Enterprises, SMEs, Government, Education Service Type: Document Management, Workflow Automation, Digital Asset Management, Collaboration Tools Industry Vertical: Healthcare, Financial Services, Retail, Media |
| Companies Covered | IBM Corporation, Microsoft Corporation, OpenText Corporation, Box Inc, Oracle Corporation, Hyland Software Inc, Laserfiche Inc, Adobe Systems Inc, M-Files Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Content Services Platform Market Strategic Shifts
Artificial intelligence capabilities are embedding into core platform functions, redefining competitive differentiation around automated content classification rather than storage economics.
Vector search and semantic indexing are migrating from experimental features to standard platform components. Australian government agencies and Singaporean ministries are deploying these capabilities for policy document discovery. The technology is migrating from niche legal research tools to mainstream enterprise search, compressing vendor differentiation cycles.
Australia's Privacy Act amendments and Japan's APPI cross-border transfer rules are tightening consent management requirements. Platform vendors must now embed granular audit trails and data lineage tracking by default. Financial services deployments across both jurisdictions are prioritizing these compliance modules over collaboration features.
Subscription pricing models are displacing perpetual licenses across mid-market buyers in Indonesia and the Philippines. Channel partners are repositioning from implementation services to ongoing managed platform operations. This shift concentrates margin pools with vendors demonstrating consistent uptime and security posture rather than upfront customization depth.
Asia Pacific Content Services Platform Market Segmentation
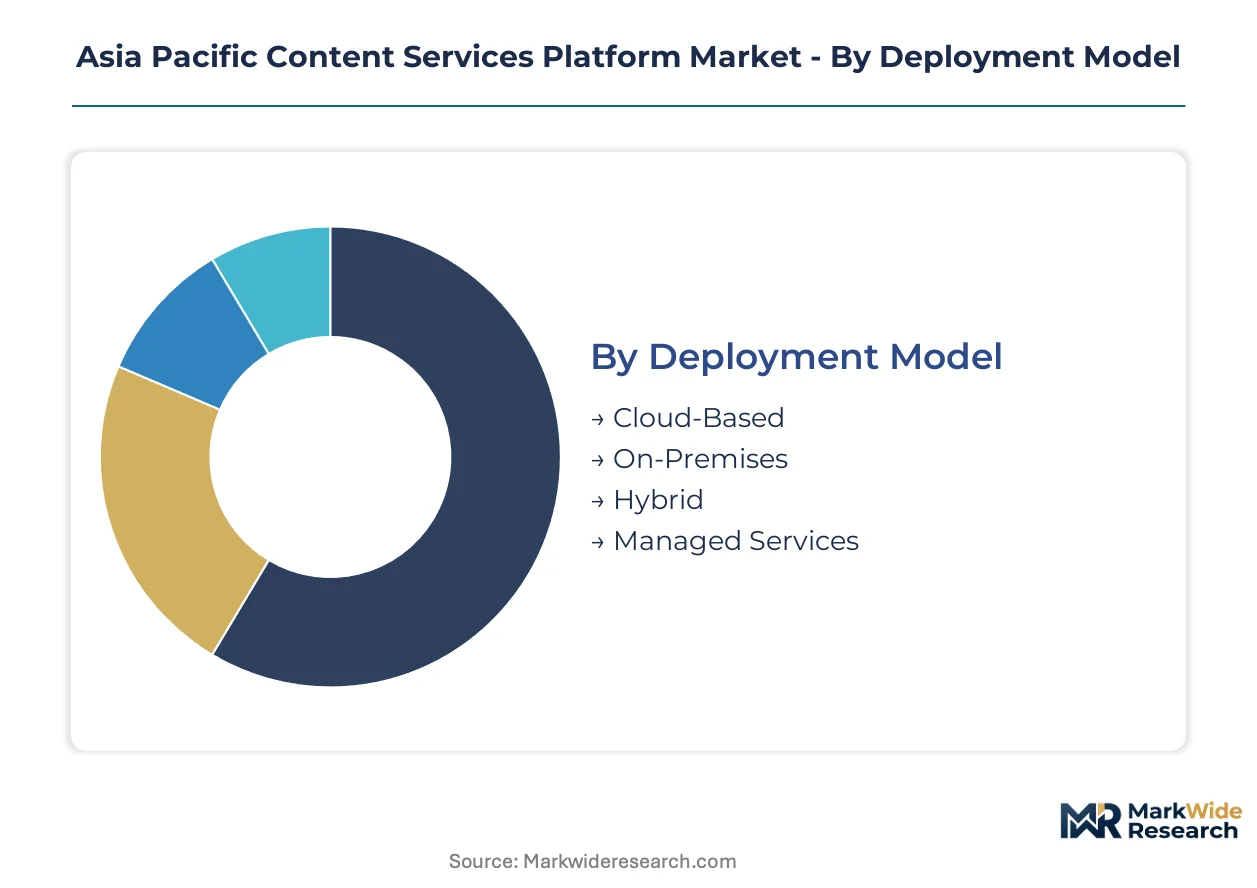
Content services platforms fragment across deployment architectures, buyer scales, functional modules, and sector-specific compliance requirements. Each segmentation dimension carries distinct margin profiles and vendor competitive dynamics across the Asia Pacific region.
Deployment Model:
Use-case spectrum spans latency-sensitive manufacturing workflows to elastic government service portals with variable citizen traffic.
- Cloud-Based:Multi-tenant architectures with API-first integration layers enable rapid provisioning without capital expenditure. Demand concentrates among Vietnamese and Indonesian SMEs bypassing on-premises infrastructure entirely; TRAI localization guidelines and Australia's Privacy Act amendments force regional data center investments by hyperscalers.
- On-Premises:Dedicated hardware installations with full administrative control over encryption keys and audit logs. Japanese manufacturing conglomerates retain these deployments for intellectual property protection; legacy system entrenchment creates substantial switching friction and elongated replacement cycles.
- Hybrid:Federated architectures partitioning sensitive records on-premises while leveraging cloud elasticity for collaboration workloads. Singaporean financial institutions favor this model for cross-border data governance.
- Managed Services:Third-party operational responsibility for platform maintenance, security patching, and compliance monitoring. Australian healthcare providers outsource diagnostic imaging archive management to specialized operators.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
End User:
Buyer sophistication and procurement authority reshape platform configuration requirements across the customer pyramid.
- Enterprises:Multi-department deployments with custom workflow orchestration and federated search across legacy repositories. Singapore's smart-nation government services and Australian enterprise digitization programs anchor regional demand; integration talent scarcity extends implementation timelines.
- SMEs:Standardized subscription tiers with pre-configured templates and limited customization scope. Cloud-native bypass strategies in Vietnam and Indonesia eliminate infrastructure capital requirements entirely.
- Government:Sovereign cloud mandates with mandatory data residency and algorithmic transparency for AI-enabled classification. Australia's Privacy Act amendments and Japan's APPI rules dictate procurement specifications.
- Education:Campus-wide collaboration tools displacing legacy file-sharing protocols with semantic search for research archives. Demand clusters in South Korean and Australian tertiary institutions.
Procurement scale concentrates with Enterprises; subscription velocity climbs fastest among SMEs.
Service Type:
Functional modules compete for platform budget allocation based on automation ROI and compliance utility.
- Document Management:Centralized repositories with version control, retention policies, and legal hold capabilities. Mature revenue base across Australian financial institutions; OpenText Corporation extends footprint through specialized compliance modules.
- Workflow Automation:Business process orchestration with audit trails and exception handling for regulatory examinations. Premium pricing commands in financial services and healthcare verticals where compliance documentation requires immutable lineage tracking.
- Digital Asset Management:Media file organization with metadata extraction and rights management for creative production. Media verticals in South Korea and Japan deploy these for content supply chain optimization.
- Collaboration Tools:Real-time co-authoring, annotation, and approval routing with granular permission architectures. Education and government sectors displace legacy protocols as remote service delivery becomes permanent.
Margin pools concentrate in Workflow Automation; Collaboration Tools gain share fastest as distributed work models institutionalize.
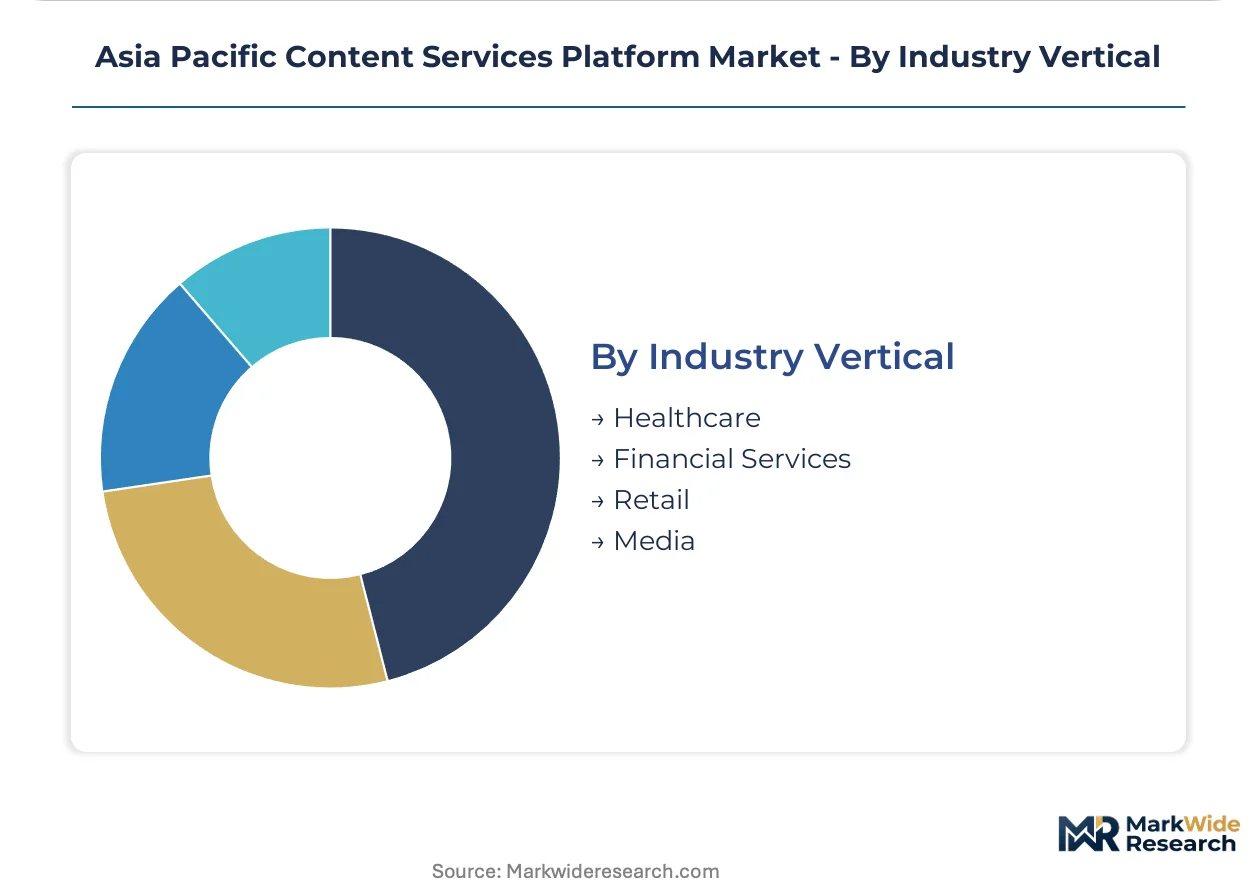
Industry Vertical:
Sector-specific regulatory density and documentation intensity determine platform customization depth and pricing power.
- Healthcare:Diagnostic imaging archives, patient record interoperability, and consent management with granular audit trails. Australia's Privacy Act amendments and Japan's APPI requirements reshape product architecture; untapped vertical expansion potential exists in cross-facility record sharing.
- Financial Services:Compliance documentation consolidation for cross-border audit requirements with algorithmic transparency for AI-enabled decisions. Southeast Asian banks accelerate adoption; EU AI Act extraterritorial reach pressures multinational deployments.
- Retail:Product information management and supplier document coordination across distributed sourcing networks. India's PLI scheme for IT hardware manufacturing strengthens underlying cloud infrastructure capacity for domestic operators.
- Media:Content supply chain orchestration from production through multi-channel distribution with rights and royalty tracking. South Korean entertainment conglomerates and Japanese publishers anchor regional demand.
Compliance premiums sustain Financial Services; Healthcare presents the steepest expansion trajectory as interoperability mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia Pacific Content Services Platform landscape. Vietnamese and Indonesian SMEs demand cloud-native bypass strategies with minimal upfront investment. Australian enterprises and Singaporean government agencies accept premium pricing for sovereign compliance and advanced workflow automation.
Japan
Japanese manufacturing conglomerates retain on-premises deployments for intellectual property protection. METI guidelines and APPI cross-border transfer rules mandate granular audit trails for multinational enterprises. Tokyo and Osaka industrial clusters drive demand for hybrid architectures that partition sensitive records locally while leveraging cloud elasticity.
Australia
Australian financial institutions and healthcare providers anchor enterprise digitization programs with compliance-heavy procurement. Privacy Act amendments force embedded consent management and data lineage tracking by default. Sydney and Melbourne enterprise clusters prioritize workflow automation modules over collaboration features.
India
Domestic enterprises expand cloud infrastructure capacity under TRAI data localization guidelines. The PLI scheme for IT hardware manufacturing reduces underlying infrastructure costs for platform operators. Bangalore and Hyderabad technology corridors concentrate demand among mid-market buyers adopting subscription frameworks.
Singapore
Singaporean financial institutions favor hybrid deployment models for cross-border data governance. Smart-nation government services mandate sovereign cloud architectures with algorithmic transparency. The city-state's regulatory clarity attracts multinational enterprises seeking compliant regional hubs.
Vietnam
Vietnamese SMEs bypass capital-intensive infrastructure through cloud-native adoption entirely. Data center capacity bottlenecks constrain latency-sensitive workflow deployments outside major urban centers. Ho Chi Minh City and Hanoi concentrate emerging demand for standardized subscription tiers with limited customization scope.
Asia Pacific Content Services Platform Market Competitive Environment
Capability concentration sits with specialized document-management vendors; scale advantage sits with hyperscale cloud providers. The Asia Pacific Content Services Platform landscape organizes around three strategic tiers: legacy enterprise software houses with hybrid cloud architectures, born-cloud specialists with API-first integration layers, and infrastructure providers leveraging captive cloud backbones. Dominant competitive moves include sovereign cloud partnerships with regional data center operators and vertical-specific compliance module development for financial services and healthcare.
Within the legacy enterprise tier, IBM Corporation and OpenText Corporation exemplify architectural approaches navigating stringent data residency requirements. Microsoft Corporation anchors the infrastructure-provider vector through Azure-backed deployments across Japan and South Korea. These three entities represent distinct competitive archetypes: hybrid-cloud navigators, document-intensive vertical specialists, and hyperscale platform anchors.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| OpenText Corporation |
| Box Inc |
| Oracle Corporation |
| Hyland Software Inc |
| Laserfiche Inc |
| Adobe Systems Inc |
| M-Files Inc |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian cloud data centers under the PLI scheme is compressing infrastructure costs and enabling aggressive subscription pricing from domestic platform operators while forcing multinational vendors to absorb margin compression or cede share.
Pricing Analysis
Managed services and extended support contracts drive lifetime value as vendors abandon perpetual licenses. Pricing stratifies across premium sovereign-cloud tiers for Australian financial institutions, standard multi-tenant subscriptions for Singaporean enterprises, and economy self-service tiers for Vietnamese SMEs. Cost compression in the economy tier is intensifying because Indonesian hyperscalers are racing to fill new data center capacity. Australian government buyers exhibit the lowest price sensitivity due to compliance mandates; Vietnamese SMEs demonstrate acute sensitivity to any upfront expenditure.
Supply Chain Analysis
Upstream compute and storage hardware feeds from Taiwan, South Korea, and China underpins platform delivery across the region. Specialized AI accelerators and high-density storage arrays rest on semiconductor fabrication concentrated in Taiwan and South Korea. Single-source vulnerability in advanced GPU supply creates deployment bottlenecks for AI-enabled classification features. Distribution runs through hyperscaler marketplaces and certified systems integrators with regional data center partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward procurement teams at Australian financial institutions and Singaporean government agencies as these segments consolidate vendor rosters around compliant sovereign-cloud providers.
For Market Incumbents: Pre-empt margin erosion in the mid-market by embedding workflow automation modules that raise switching costs. Acquire specialized healthcare compliance boutiques to defend against born-cloud challengers attacking diagnostic imaging archives. Channel control through exclusive systems integrator partnerships in Japan protects against IBM's hybrid-cloud expansion.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's SME segment through mobile-first, zero-infrastructure onboarding workflows. The Indonesian education vertical presents white-space opportunity as campuses displace legacy file-sharing protocols. A channel-native go-to-market through regional telecom carriers bypasses direct enterprise sales complexity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed services operators with healthcare compliance certifications. Long-term viability hinges on sovereign-cloud partnerships that lock in data residency premiums. Acquisition targets should demonstrate API-first architectures with proven TRAI or Australia's Privacy Act compliance. The signal to watch is hyperscaler marketplace traction as a leading indicator of scalable distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | TRAI and Australia's Privacy Act mandates require certified regional data center alliances. |
| Vertical Compliance Module | Healthcare workflow automation with Japan's APPI audit trails commands premium pricing. |
| API-First Platform Integration | Federated content access displaces wholesale infrastructure replacement in Japanese manufacturing. |
| Acquisition of Specialist Firm | Diagnostic imaging archive operators in Australia expand addressable market in patient record interoperability. |
| Geographic Expansion | Ho Chi Minh City and Hanoi SME clusters offer cloud-native bypass adoption without legacy drag. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at Australian financial institutions, compliance officers at Singaporean government agencies, platform engineers at Indian cloud operators, and integration specialists serving Japanese manufacturing conglomerates. Secondary validation drew from TRAI regulatory filings, Australia's Privacy Act amendment records, hyperscaler capex disclosures, and enterprise software SEC filings. Bottom-up deployment counts across cloud, on-premises, and hybrid architectures were triangulated against top-down vendor revenue estimates.
Calibration against historical subscription conversion rates and sovereign-cloud certification timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, functional module mix, and industry vertical regulatory density. CAGRs were derived from fitted adoption curves incorporating PLI scheme infrastructure cost reductions and data localization compliance deadlines. AI-enabled classification penetration and API integration complexity served as industry-specific forecast inputs.
Stress conditions across data center buildout delays, cross-border transfer rule tightening, and SME subscription churn were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and hyperscaler pricing discipline. Cross-checking against vendor-reported cloud marketplace transaction volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Human Capital Management Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
North America Equity Management Software Market
Software & Services
PCB CAD Software Market
Software & Services
Team Collaboration Software Market
Software & Services
Camp Management Software Market
Software & Services
Lead Mining Software Market
Software & Services
IT Services Market
Software & Services
HSM-As-A-Service Market
Software & Services
Predictive Dialer Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Telecom IT Services Market
Software & Services
Advanced Process Control Software Market
Software & Services
Online Recruitment Software Market
Software & Services
Global Contract Management Software Market