
 Clustering Software Market | 2026-2036
Clustering Software Market Size, Share, and Industry Trends Forecast 2026-2036
Clustering Software Market Intelligence
Data science talent scarcity is rotating enterprise purchasing patterns toward managed clustering services and pre-configured analytics platforms. Microsoft Corporation leverages its Azure cloud footprint to embed clustering tools within broader enterprise workflows. IBM Corporation sustains competitive relevance through specialized offerings in predictive analytics and anomaly detection for regulated industries. Amazon Web Services dominates cloud-native deployments with elastic compute integration that reduces infrastructure overhead for data-intensive clustering workloads.
Clustering software refers to algorithmic systems that group unlabeled datasets into coherent segments based on statistical similarity metrics such as Euclidean distance, cosine similarity, or density-based spatial thresholds, serving primarily to uncover hidden patterns in customer behavior, operational telemetry, and scientific observation. The deployment dimension shows cloud-based and SaaS configurations capturing expanding share as organizations prioritize elastic scalability over capital-intensive on-premises infrastructure. Within applications, anomaly detection and customer profiling represent the most dynamic margin pools, while image analysis retains specialized positioning in healthcare and autonomous systems verticals.
The EU AI Act imposes risk-tiered compliance obligations on clustering applications used for biometric categorization and predictive policing, compelling vendors to embed auditability and explainability features. In the United States, NIST AI Risk Management Framework and sector-specific HIPAA constraints shape how healthcare and finance end users evaluate clustering solutions for sensitive data environments. Stakeholders must monitor evolving cross-border data localization requirements and emerging algorithmic accountability standards that will determine market access conditions for platform providers.
Market Dynamics
Cloud migration mandates under the EU AI Act and parallel data governance frameworks in the United States are compressing procurement cycles while elevating explainability requirements as non-negotiable selection criteria for enterprise clustering deployments.
Growth Catalysts
- EU AI Act compliance deadlines:Risk-tiered obligations for biometric categorization systems are compelling healthcare and finance end users to accelerate replacement of legacy black-box clustering tools with auditable alternatives.
- Healthcare diagnostic imaging:Patient segmentation algorithms are penetrating radiology workflows in the United States, driven by HIPAA-constrained demand for privacy-preserving pattern recognition.
- Edge computing architectures:Federated clustering implementations are expanding in Germany and Japan as manufacturers deploy distributed inference nodes for real-time quality control.
Market Restraints
- GPU compute cost volatility:Training density-based spatial clustering models at scale requires sustained access to NVIDIA H100 or equivalent accelerators, creating input cost exposure for mid-tier SaaS vendors.
- Cross-border data localization:China's GB standards and India's draft data protection rules are fragmenting cloud deployment architectures, forcing redundant infrastructure provisioning.
- Substitution by foundation models:Large language models with embedded semantic clustering capabilities are displacing standalone algorithmic tools in customer profiling applications.
Strategic Opportunities
- Brazilian healthcare digitization:ANVISA's accelerated medical device software pathway is opening regulated market access for patient clustering tools in diagnostic workflows.
- Convergence with causal inference:Integration of clustering outputs with structural equation modeling is creating new pricing power in pharmaceutical patient stratification.
- Managed service channels:Systems integrators in France and the Netherlands are building recurring revenue streams by embedding clustering modules within broader enterprise analytics subscriptions.
Industry Challenges
- Interpretability engineering talent scarcity:The specialized skill set combining statistical learning with regulatory documentation is commanding premium compensation, constraining vendor scaling velocity.
- Legacy data warehouse integration:On-premises Teradata and Oracle installations in United States federal agencies require custom API development, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clustering Software Market |
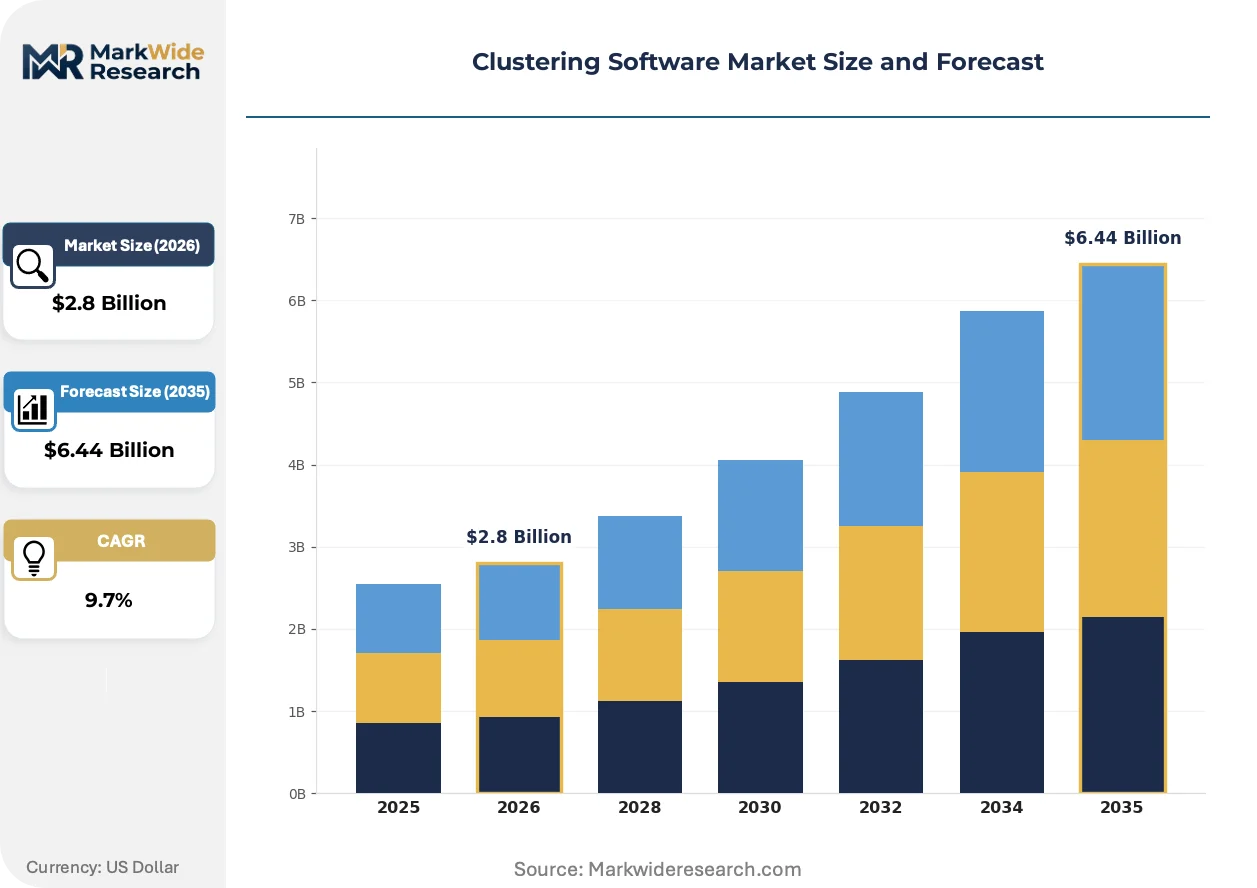
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail, Healthcare, Finance, Education Application: Market Segmentation, Image Analysis, Anomaly Detection, Customer Profiling Solution: Machine Learning, Data Mining, Business Intelligence, Predictive Analytics |
| Companies Covered | SAP SE, Amazon Web Services, IBM Corporation, Fujitsu, VMware, Oracle Corporation, Hewlett Packard Enterprise, Red Hat, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clustering Software Market Strategic Shifts & Innovations
Algorithmic explainability and elastic infrastructure consumption are converging to reshape how clustering capabilities are packaged, priced, and governed across regulated industries.
Density-based spatial clustering (DBSCAN) and its hierarchical variants are fragmenting the traditional k-means dominated landscape as autonomous vehicle developers and precision agriculture operators demand noise-robust segmentation for LiDAR point clouds and satellite imagery. Automotive Tier 1 suppliers in Germany and Japan are adopting these algorithms at compressed procurement cycles, with validation timelines collapsing from eighteen months to six. The structural consequence is fragmenting vendor specialization, with pure-play clustering toolkits capturing share from general-purpose analytics suites in safety-critical applications.
The EU AI Act's risk classification system is imposing documentation burdens on clustering applications used for biometric categorization and predictive policing, forcing vendors to embed technical file maintenance and conformity assessment workflows. Industrial consequence includes elevated R&D allocation toward audit trail generation and counterfactual explanation interfaces. Healthcare imaging vendors serving European hospitals are responding by pre-certifying clustering modules under the MDR software-as-medical-device pathway, creating first-mover certification moats.
Consumption-based licensing for cloud-native clustering workloads is displacing perpetual seat licenses as the dominant procurement model in United States financial services and technology sectors. Independent software vendors are unbundling professional services from core algorithm access, with channel partners capturing implementation margins. This pattern is most visible in New York and San Francisco metropolitan areas, where hedge funds and ad-tech platforms are consolidating vendor relationships around usage-metered contracts with automatic elasticity clauses.
Clustering Software Market Segmentation
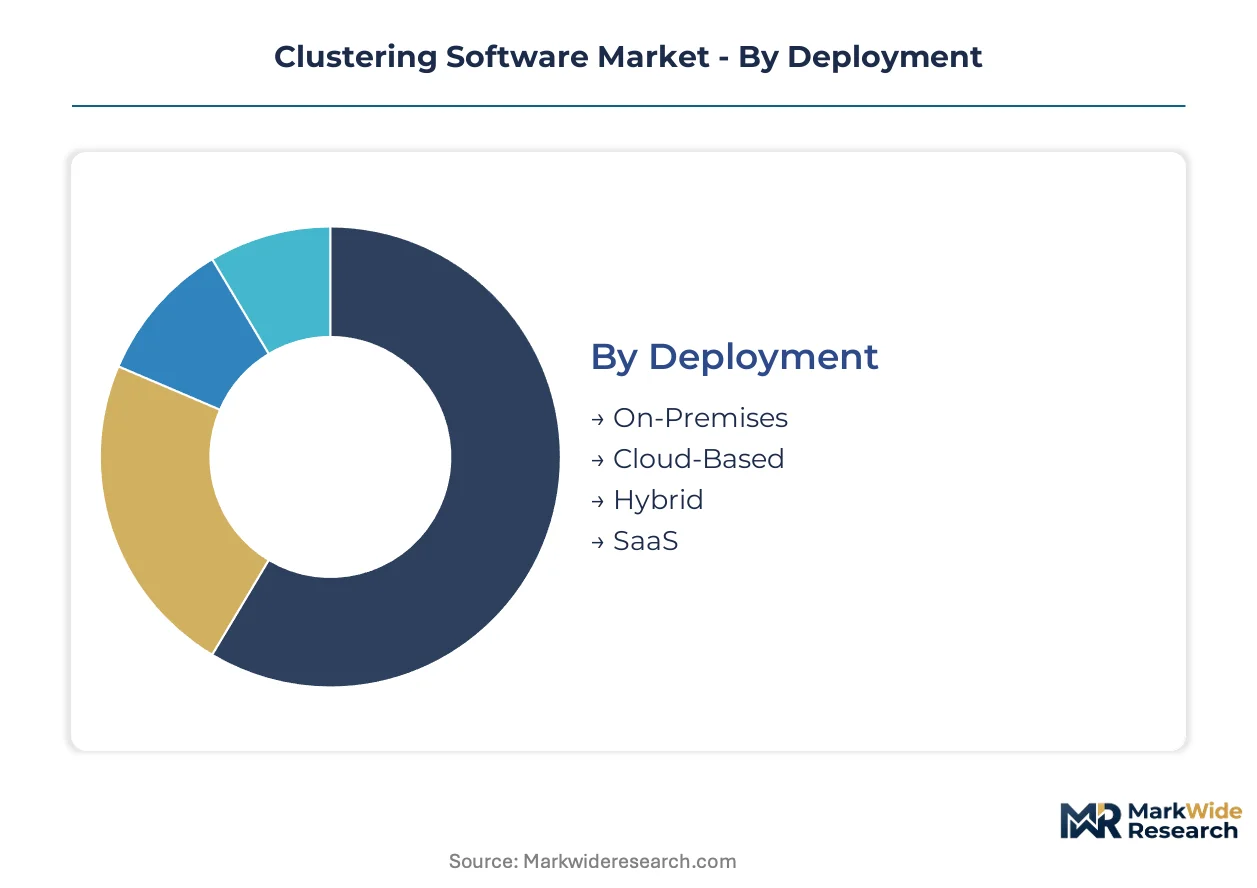
Segmentation in clustering software determines procurement pathways, with deployment mode dictating whether vendors capture revenue through perpetual licenses or consumption-based contracts. End-user verticals and application types further stratify pricing power, as regulated healthcare deployments command premium positioning against commoditized retail implementations.
Deployment:
Cloud-based configurations flow through hyperscaler marketplaces and direct SaaS channels, while on-premises deployments route through systems integrators and value-added resellers with embedded professional services.
- Cloud-Based:Elastic compute integration enables pay-per-query consumption models. United States financial services firms in New York and San Francisco metropolitan areas are consolidating procurement around usage-metered contracts with automatic elasticity clauses, driven by hedge fund demand for variable-cost pattern recognition infrastructure.
- SaaS:Pre-configured algorithmic modules reduce implementation timelines from months to weeks. Healthcare providers across Germany and Japan are adopting SaaS clustering for patient segmentation, constrained by EU AI Act risk-tiered compliance obligations that favor vendor-managed audit trails.
- On-Premises:Legacy Teradata and Oracle installations in United States federal agencies require custom API development, extending sales cycles.
- Hybrid:Federated architectures split sensitive data processing between edge nodes and cloud inference, prevalent in German automotive manufacturing quality control.
By volume, Cloud-Based leads. By growth pace, SaaS is climbing the fastest.
End User:
Customer concentration varies sharply by vertical, with finance and healthcare presenting concentrated account bases of large enterprises while education fragments across thousands of institutional buyers.
- Healthcare:HIPAA-constrained demand for privacy-preserving pattern recognition drives procurement of auditable clustering tools. Radiology workflows in the United States are penetrating patient segmentation algorithms, with diagnostic imaging vendors pre-certifying modules under the MDR software-as-medical-device pathway for European hospital access.
- Finance:Anomaly detection for fraud prevention and algorithmic trading signal generation commands premium pricing. United States hedge funds and ad-tech platforms are consolidating vendor relationships around consumption-based licensing with embedded explainability features.
- Retail:Customer behavior segmentation faces substitution pressure from large language models with embedded semantic clustering capabilities.
- Education:Learning analytics and student performance clustering remain price-sensitive, with procurement concentrated in state university systems.
Healthcare captures the highest average contract value. Finance demonstrates the steepest expansion trajectory in new account acquisition.
Application:
Margin structure inverts between mature segmentation use cases and emerging safety-critical deployments, with autonomous vehicle LiDAR processing commanding validation timelines that compress from eighteen months to six.
- Anomaly Detection:Noise-robust density-based spatial clustering penetrates safety-critical infrastructure monitoring. German and Japanese automotive Tier 1 suppliers are adopting DBSCAN variants for real-time quality control at compressed procurement cycles.
- Image Analysis:Specialized positioning in healthcare diagnostic imaging and autonomous systems verticals creates defensible vendor specialization. Precision agriculture operators in satellite imagery processing demand hierarchical clustering variants for crop health segmentation.
- Customer Profiling:Foundation models with embedded semantic capabilities are displacing standalone algorithmic tools in this application.
- Market Segmentation:Traditional k-means implementations face commoditization in retail and media planning use cases.
Anomaly Detection leads in pricing power. Image Analysis is gaining share fastest in regulated verticals.
Solution:
Technology stack layering determines whether clustering capabilities embed within broader analytics platforms or deploy as specialized modules, with predictive analytics bundling commanding the highest attach rates.
- Predictive Analytics:Integration of clustering outputs with structural equation modeling creates new pricing power in pharmaceutical patient stratification. Convergence with causal inference techniques differentiates offerings in United States life sciences verticals.
- Machine Learning:GPU compute cost volatility for training density-based models at scale creates input cost exposure, favoring vendors with sustained NVIDIA H100 accelerator access.
- Business Intelligence:Embedded clustering modules within enterprise dashboards face margin compression from unbundling trends.
- Data Mining:Legacy toolkits compete on price against cloud-native alternatives with elastic scalability.
Predictive Analytics dominates revenue contribution. Machine Learning is expanding most quickly in cloud-native deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIST AI Risk Management Framework and HIPAA constraints in the United States shape procurement patterns for clustering solutions handling sensitive data environments. Cloud migration mandates under the EU AI Act and parallel data governance frameworks are compressing procurement cycles across multiple jurisdictions.
United States
Enterprise data infrastructure spending and AI governance investments outpace other national markets. NIST AI Risk Management Framework and sector-specific HIPAA constraints shape how healthcare and finance end users evaluate clustering solutions. New York and San Francisco metropolitan areas consolidate vendor relationships around usage-metered contracts with automatic elasticity clauses.
Germany
Automotive Tier 1 suppliers adopt density-based spatial clustering algorithms at compressed procurement cycles for real-time quality control. EU AI Act risk-tiered obligations compel healthcare and finance end users to accelerate replacement of legacy black-box clustering tools. Federated architectures split sensitive data processing between edge nodes and cloud inference in automotive manufacturing quality control.
Japan
Manufacturers deploy distributed inference nodes for real-time quality control using federated clustering implementations. METI standards influence industrial adoption of noise-robust segmentation algorithms for LiDAR point clouds and satellite imagery. Tokyo and Osaka metropolitan areas concentrate demand for cloud-native clustering workloads with elastic scalability.
United Kingdom
Financial services firms in London drive consumption-based licensing for cloud-native clustering workloads. GDPR compliance requirements elevate explainability features as non-negotiable selection criteria for enterprise deployments. The Southeast region anchors demand for predictive analytics bundling with clustering capabilities.
Brazil
ANVISA's accelerated medical device software pathway opens regulated market access for patient clustering tools in diagnostic workflows. Healthcare digitization initiatives create demand for auditable clustering modules. São Paulo anchors procurement concentration for enterprise analytics subscriptions embedding clustering capabilities.
Clustering Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscaler cloud platforms and legacy enterprise software vendors occupying distinct competitive positions. The market structure reflects consolidation around platforms with embedded infrastructure advantages and fragmentation among pure-play algorithmic toolkits. Strategic archetypes include cloud-native service providers, enterprise software incumbents with analytics portfolios, and open-source distribution specialists. Dominant competitive moves encompass strategic partnerships with systems integrators and portfolio diversification into adjacent predictive analytics capabilities.
Within the integrated platform tier, Microsoft Corporation and Amazon Web Services exemplify cloud-native deployment dominance, while IBM Corporation occupies a position representing specialized offerings for regulated industries. These three anchors illustrate how vendor specialization fragments across safety-critical applications, with each representing distinct approaches to embedding clustering tools within broader enterprise workflows or maintaining competitive relevance through targeted vertical solutions.
| Leading Market Players |
|---|
| SAP SE |
| Amazon Web Services |
| IBM Corporation |
| Fujitsu |
| VMware |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| Red Hat |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
Ninety-day implementation timelines for on-premises clustering deployments compress pricing power for legacy vendors while elevating consumption-based SaaS premiums. Cloud-native delivery concentrates supplier leverage among hyperscalers, forcing mid-tier algorithmic vendors into channel partnerships that erode direct margin capture.
Pricing Analysis
United States financial services firms pay premiums of forty to sixty percent above German healthcare providers for equivalent clustering throughput, reflecting HIPAA-constrained auditability requirements and embedded explainability features. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by EU AI Act certification grade and volume scale of inference queries. Cost compression in the standard tier intensifies because large language models with embedded semantic clustering displace standalone tools in customer profiling. Retail and education segments demonstrate acute price sensitivity, while finance and healthcare buyers prioritize compliance-grade documentation over unit cost.
Supply Chain Analysis
The United States and Taiwan anchor GPU accelerator fabrication for clustering training workloads, with NVIDIA H100 supply rationing creating allocation bottlenecks for mid-tier SaaS vendors. Software supply draws from open-source algorithmic libraries, proprietary optimization layers, and cloud orchestration middleware. Single-source vulnerability in advanced semiconductor fabrication exposes vendors to foundry capacity constraints. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and systems integrators embedding clustering modules within broader analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation models with embedded clustering capabilities threaten standalone algorithmic toolkits, forcing incumbents to defend through workflow integration and regulatory certification moats.
For Market Incumbents: Compound defensive positioning by pre-certifying clustering modules under EU AI Act and MDR software-as-medical-device pathways, creating compliance barriers against unvalidated substitutes. Deepen upstream control over GPU allocation through multi-year cloud capacity reservations, insulating margin structure from accelerator cost volatility. Prioritize embedding clustering tools within Microsoft Azure and AWS native workflows to increase switching costs. For New Entrants and Emerging Players: ANVISA's accelerated medical device software pathway in Brazil offers regulated market access with compressed validation timelines relative to European MDR routes. Target Brazilian healthcare digitization initiatives and Japanese federated manufacturing quality control as white-space geographies with underpenetrated clustering demand. Lead with managed service positioning that bundles implementation expertise with algorithmic access, capturing professional services margins incumbents have unbundled. For Investors and Strategic Acquirers: Carve-out targets emerge from enterprise software parents divesting non-core analytics assets with embedded clustering IP but subscale go-to-market infrastructure. Long-term viability hinges on differentiation against foundation model substitution through vertical specialization and regulatory certification depth. Watch EU AI Act enforcement intensity as the inflection indicator—accelerated conformity assessment timelines would compress valuation multiples for uncertified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | MDR software-as-medical-device pathway creates first-mover compliance moats in European hospital procurement. |
| Hyperscaler Marketplace Integration | Azure and AWS native embedding captures enterprise workflow lock-in against standalone toolkit displacement. |
| Managed Service Channel Development | French and Dutch systems integrators build recurring revenue by bundling clustering within analytics subscriptions. |
| GPU Capacity Reservation | Multi-year NVIDIA H100 allocation agreements insulate margin structure from foundry rationing volatility. |
| Causal Inference Convergence | Structural equation modeling integration commands premium positioning in pharmaceutical patient stratification. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with enterprise CTOs, healthcare CIOs, financial services data science leads, and hyperscaler platform engineers; and secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and hospital procurement databases. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate enterprise software spending produced convergent estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including deployment architecture, end-user vertical, application type, and solution stack layering. CAGRs were derived from elasticity-adjusted demand curves incorporating GPU cost trajectories and regulatory compliance timeline acceleration. Forecast inputs included EU AI Act implementation schedules, ANVISA pathway processing rates, and federated manufacturing adoption patterns in German automotive Tier 1 suppliers.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscaler cloud growth and moderate foundation model substitution rates; material deviation in semiconductor supply or regulatory enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act conformity assessment timelines and GPU foundry capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Illustration Software Market
Software & Services
Global Architect Software Market
Software & Services
Collaboration Tools Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Global Gamification Software Market
Software & Services
Non-Profit Software Market
Software & Services
Video Converter Software Market
Software & Services
Air Cargo Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Account-Based Advertising Software Market