
 Europe Drone Software Market | 2026-2036
Europe Drone Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Drone Software Market Analytics
Germany's industrial drone corridor is fragmenting into specialized software clusters around Munich and Berlin. Pix4D sustains its mapping technology leadership through photogrammetry R&D intensity in Lausanne. DELAIR anchors fixed-wing drone analytics for infrastructure networks across Southern Europe. Skydio navigates competitive positioning in autonomous navigation stacks for defense and public safety applications.
Europe drone software encompasses the embedded and cloud-based programs that govern flight autonomy, sensor fusion, geospatial processing, and fleet orchestration for unmanned aerial systems operating under EASA's specific and certified categories. These platforms process real-time telemetry, execute waypoint navigation with GNSS correction, and generate orthomosaics from multispectral payloads for commercial and government end users. Mapping software occupies the largest margin pool due to recurring SaaS renewals from surveying and construction firms, while data analytics software represents the fastest-expanding segment as agricultural enterprises demand predictive yield models. Fleet management software competes on integration depth with enterprise ERP systems used by logistics providers.
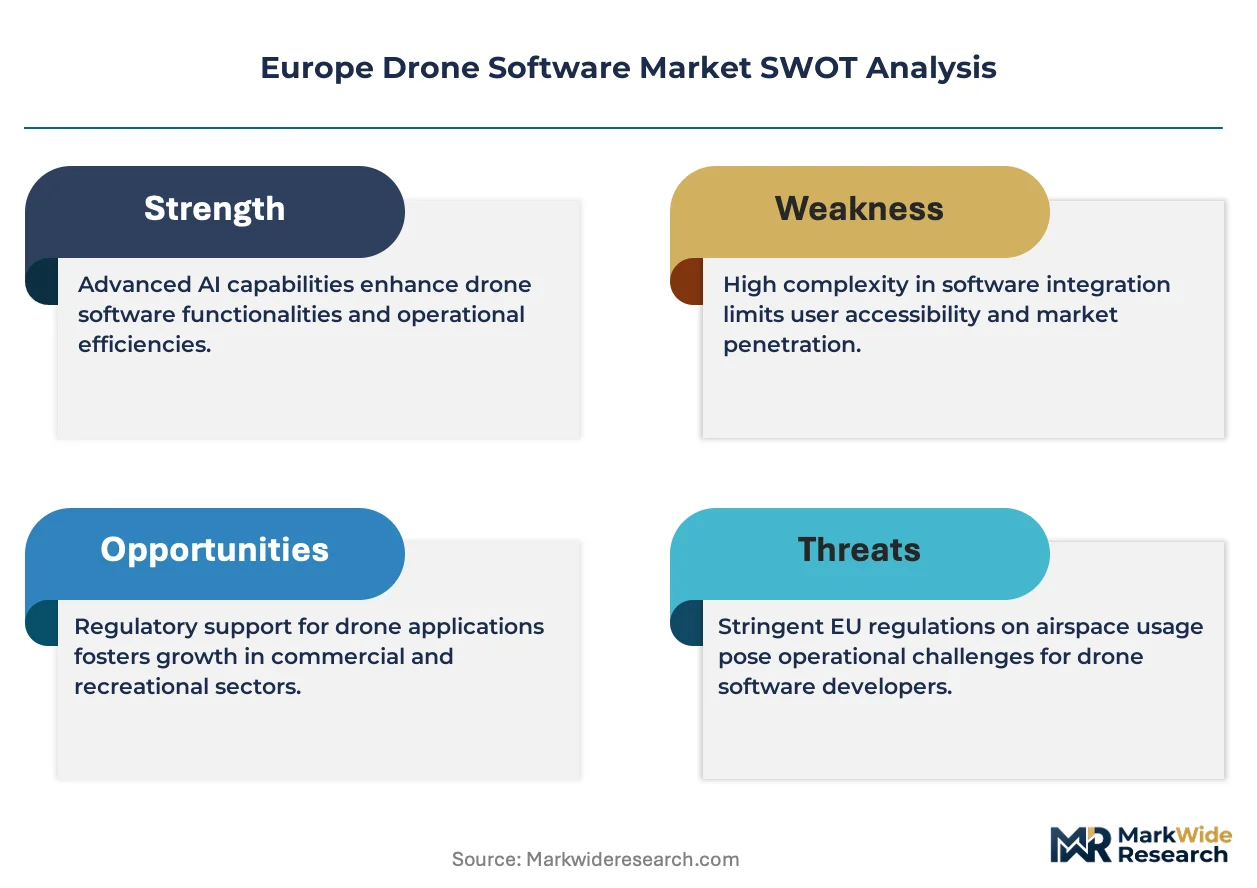
EASA's drone regulatory framework, the EU AI Act's risk classification for autonomous systems, and CE marking requirements under the Radio Equipment Directive collectively shape product certification timelines and market access conditions for software vendors. GDPR compliance constrains how flight data and captured imagery traverse cloud-based deployment architectures. Stakeholders must monitor how the EU Green Deal's digital agriculture funding redirects procurement priorities among government agencies and agricultural enterprises.
Market Dynamics
EU AI Act risk classifications for autonomous flight systems are forcing software vendors to re-architect algorithmic decision-making pipelines, compressing certification timelines and redrawing competitive boundaries across the continent.
Growth Catalysts
- EU Green Deal digital agriculture funding:Subsidies for precision farming platforms are accelerating sensor fusion software procurement across German and French agricultural cooperatives.
- CE marking under Radio Equipment Directive:Standardized certification pathways for drone communication modules are reducing time-to-market for fleet management vendors targeting logistics networks.
- Photogrammetry automation:Cloud-based orthomosaic generation is displacing manual surveying workflows in construction and mining operations throughout Spain and Italy.
Market Restraints
- GDPR data residency requirements:Flight telemetry and captured imagery must remain within EU jurisdictional boundaries, inflating cloud infrastructure costs for analytics platforms.
- Swiss component concentration:High-precision GNSS correction modules rely on a narrow supplier base around Zurich and Geneva, creating single-source vulnerability.
- Battery energy density plateau:Lithium-polymer chemistry limits are constraining flight endurance for software-demanding multispectral payloads.
Strategic Opportunities
- Polish logistics corridor:Underpenetrated last-mile drone delivery networks present white space for fleet orchestration software integrating with DHL and InPost distribution hubs.
- EU AI Act compliance services:Risk classification documentation and algorithmic audit tooling represent emerging revenue streams for specialized consultancies.
- Digital twin convergence:Integration between real-time drone telemetry and building information modeling platforms is opening new construction lifecycle management contracts.
Industry Challenges
- Embedded systems talent scarcity:Shortages of engineers proficient in real-time operating systems and sensor fusion algorithms are inflating R&D payrolls in Toulouse and Munich clusters.
- EASA specific-to-certified category migration:Software vendors face 18-24 month recertification timelines when upgrading platforms from lower-risk to higher-risk operational categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Drone Software Market |
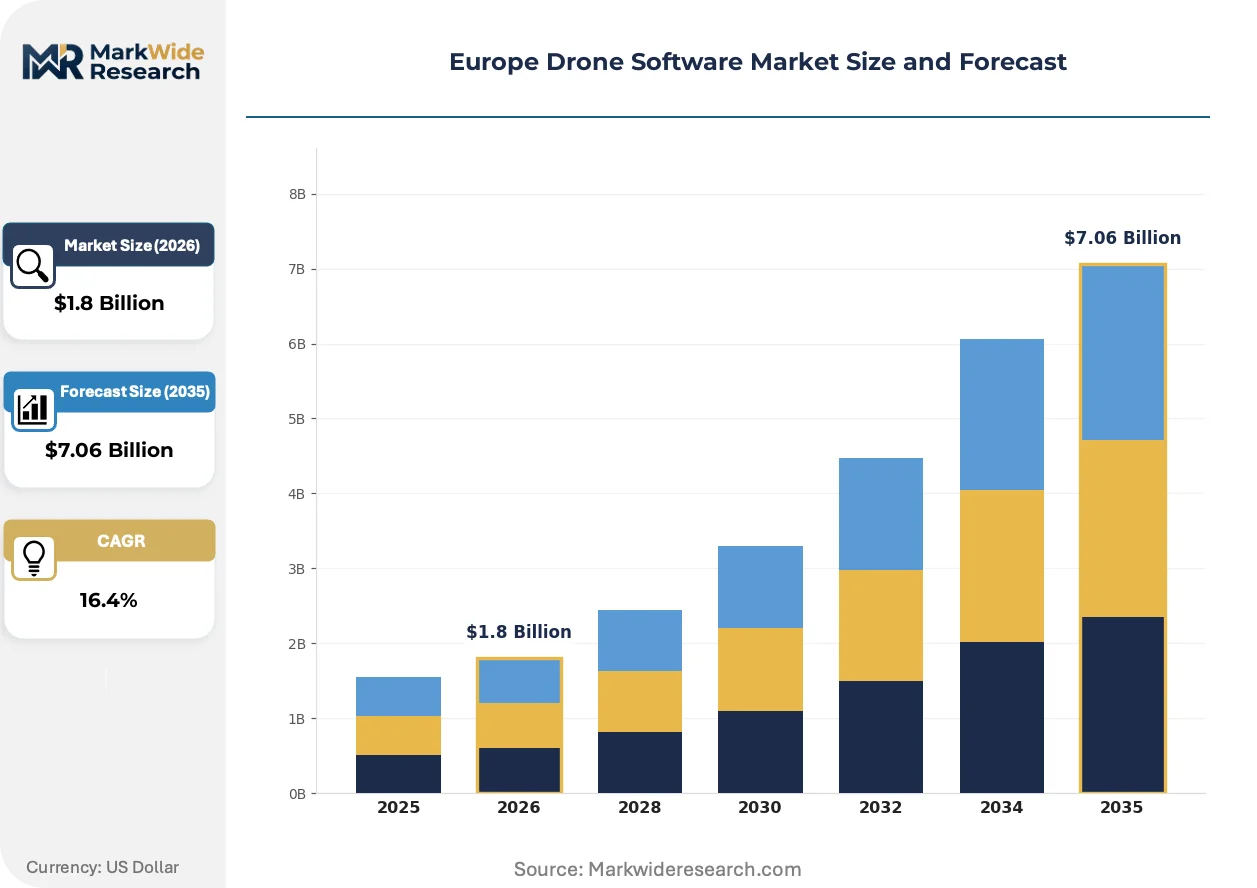
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control Software, Mapping Software, Fleet Management Software, Data Analytics Software Application: Agriculture, Surveillance, Delivery, Infrastructure Inspection End User: Agricultural Enterprises, Government Agencies, Logistics Providers, Construction Firms Deployment: On-Premise, Cloud-Based, Hybrid, SaaS |
| Companies Covered | DroneDeploy, Pix4D, SZ DJI Technology, Skydio, Kespry, PrecisionHawk, Esri, AirMap, DELAIR, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Drone Software Market Evolving Landscape
Edge computing architectures are redistributing computational load from ground stations to onboard processors, collapsing latency for time-critical autonomous decisions and enabling new subscription pricing models for software vendors.
Sensor fusion middleware is virtualizing the distinction between hardware-specific flight controllers and platform-agnostic autonomy stacks. German industrial drone operators are migrating toward vendor-neutral software layers that abstract across DJI, Autel, and custom airframes. This virtualization is compressing switching costs and fragmenting historical hardware-software bundling arrangements.
GDPR's Article 22 restrictions on automated decision-making are compelling French and Dutch drone software developers to implement human-in-the-loop override protocols for all autonomous navigation systems. Agricultural spraying platforms face the steepest compliance burden, with yield prediction algorithms now requiring explicit operator confirmation before executing variable-rate fertilizer applications. Vendors are responding by embedding audit trails and explainability dashboards into their SaaS offerings.
Surveying firms and construction contractors are unbundling perpetual license purchases in favor of consumption-based pricing tied to acreage processed or orthomosaic tiles generated. This shift is most pronounced in Iberian markets, where midsize engineering consultancies prioritize cash-flow flexibility over capital expenditure. Software providers are adapting by introducing tiered subscription bands with overage penalties rather than traditional enterprise agreements.
Europe Drone Software Market Segmentation
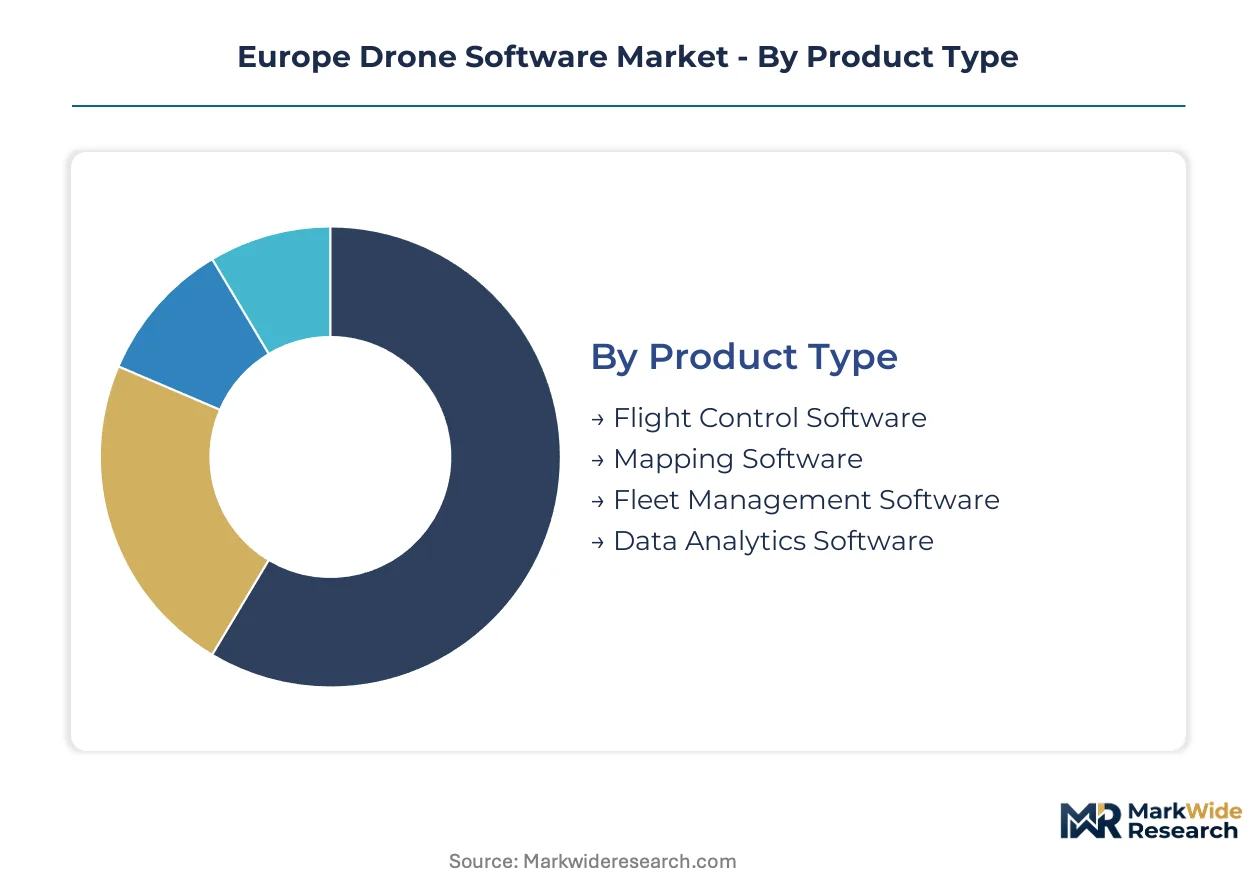
Drone software architectures fragment across four critical dimensions: embedded flight systems, geospatial processing engines, fleet orchestration layers, and predictive analytics modules. Each segmentation axis reveals distinct margin profiles, certification burdens, and procurement patterns that shape vendor strategy across EASA jurisdictions.
Product Type:
Use-case spectrum spans embedded autopilot stacks for single-drone operations through distributed cloud platforms coordinating hundreds of aircraft.
- Flight Control Software:Embedded real-time operating systems execute sensor fusion, waypoint navigation, and fail-safe protocols on onboard processors. German agricultural drone operators in Bavaria demand GNSS-RTK precision for centimeter-level spraying accuracy, driving procurement of EASA-certified autopilot modules.
- Mapping Software:Photogrammetry engines generate orthomosaics, digital elevation models, and 3D point clouds from multispectral imagery. Surveying firms throughout Spain and Italy are displacing manual workflows with cloud-based reconstruction platforms that process terabyte-scale datasets.
- Fleet Management Software:Multi-vehicle orchestration platforms integrate airspace deconfliction, battery swap logistics, and maintenance scheduling for enterprise drone operations.
- Data Analytics Software:Machine learning pipelines extract actionable intelligence from aerial sensor feeds, with predictive yield models gaining traction among French agricultural cooperatives.
The dominant share belongs to Mapping Software, while Data Analytics Software is closing the gap fastest.
Application:
Deployment intensity varies sharply by operational risk classification under EU AI Act frameworks.
- Agriculture:Variable-rate application systems fuse NDVI indices with prescription maps for precision crop management. EU Green Deal subsidies are accelerating sensor fusion procurement across German and French agricultural enterprises.
- Surveillance:Real-time video analytics for border patrol, event security, and critical infrastructure monitoring demand low-latency edge processing.
- Delivery:Last-mile logistics networks require dynamic rerouting algorithms and vertiport integration modules.
- Infrastructure Inspection:Automated defect detection for power lines, bridges, and pipelines leverages computer vision models trained on proprietary damage databases.
Agriculture commands the largest installed base, though Infrastructure Inspection is expanding most quickly as utilities digitize asset lifecycle management.
End User:
Procurement sophistication diverges between regulated government tenders and commercial fleet operators.
- Agricultural Enterprises:Cooperative purchasing consortia in France negotiate volume discounts on multispectral analytics subscriptions tied to harvest cycles.
- Government Agencies:Civil protection and environmental monitoring departments mandate EASA certified-category compliance with exhaustive audit trails.
- Logistics Providers:DHL and InPost distribution hubs in Poland pilot drone integration with warehouse management systems for underpenetrated last-mile corridors.
- Construction Firms:Engineering consultancies in Iberian markets favor consumption-based pricing for progress monitoring and earthworks volumetrics.
Government Agencies anchor premium pricing tiers, while Logistics Providers are gaining share fastest as delivery networks scale beyond pilot phases.
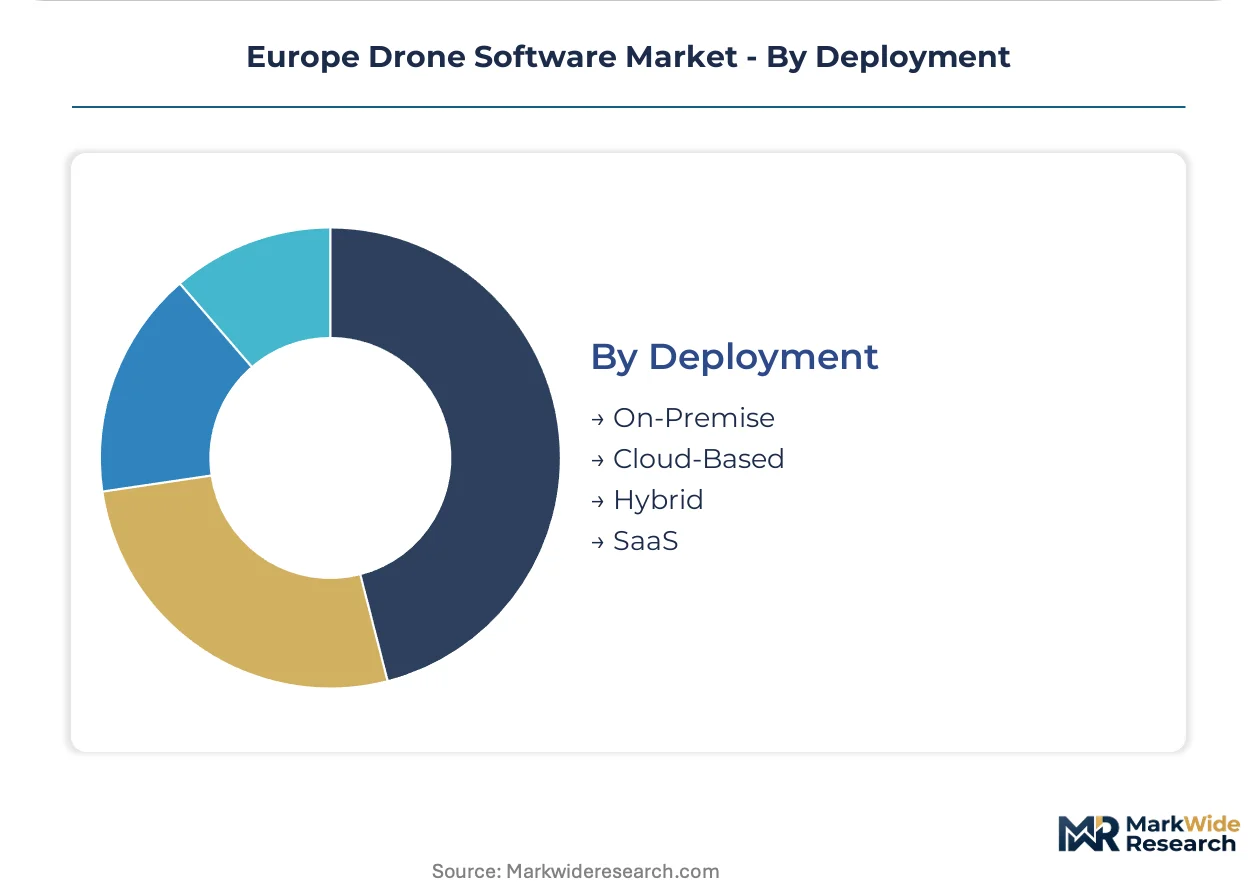
Deployment:
Architectural choices trade latency against scalability and GDPR compliance overhead.
- On-Premise:Air-gapped installations for defense and critical infrastructure operators processing classified imagery.
- Cloud-Based:Elastic compute resources for photogrammetry pipelines, though GDPR data residency requirements inflate infrastructure costs for analytics platforms.
- Hybrid:Edge preprocessing with cloud aggregation balances real-time autonomy demands against long-term data archival needs.
- SaaS:Tiered subscription bands with overage penalties displace perpetual licenses among midsize engineering consultancies prioritizing cash-flow flexibility.
Cloud-Based deployments retain the dominant position, yet Hybrid architectures are climbing the fastest as latency-sensitive applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA's regulatory framework anchors software certification timelines across the continent, with national industrial clusters diverging in specialization depth and procurement sophistication. Member states deploy varying subsidy intensities for precision agriculture platforms, while GDPR data residency requirements reshape cloud infrastructure geography.
Germany
Bavarian agricultural cooperatives drive sensor fusion procurement for variable-rate spraying applications. The EU Green Deal channels digital agriculture subsidies toward precision farming platforms in Lower Saxony and Baden-Württemberg. Munich and Berlin host competing software clusters for embedded autopilot stacks and cloud-based fleet orchestration.
France
The aerospace corridor around Toulouse concentrates EASA-certified autopilot development for certified-category operations. ANSM and CNIL oversight shapes GDPR compliance architectures for flight telemetry processing. Agricultural enterprises in the Île-de-France basin negotiate cooperative purchasing consortia for multispectral analytics subscriptions.
Poland
Underpenetrated last-mile delivery networks attract fleet management vendors targeting DHL and InPost distribution hubs. CE marking under the Radio Equipment Directive accelerates time-to-market for logistics-integrated communication modules. Warsaw and Kraków emerge as testing grounds for urban air mobility software stacks.
Spain
Photogrammetry automation displaces manual surveying workflows among construction contractors and mining operators. Iberian engineering consultancies favor consumption-based SaaS pricing for progress monitoring applications. Barcelona and Madrid anchor competing clusters for cloud-based orthomosaic generation platforms.
Switzerland
High-precision GNSS correction module suppliers concentrate around Zurich and Geneva, creating critical component dependencies for neighboring markets. Swissmedic-equivalent certification standards influence EASA's risk classification methodologies. Lausanne sustains photogrammetry R&D intensity through specialized university-industry partnerships.
Europe Drone Software Market Competitive Landscape
Photogrammetry specialists and autonomous navigation stacks split the market along use-case specialization lines. Vendor concentration remains moderate, with tiered competitive dynamics separating EASA-certified platform providers from uncertified workflow tools. Two strategic archetypes dominate: mapping-software incumbents with recurring SaaS renewal bases, and autonomy-stack challengers competing on edge-computing latency. Consolidation pressure manifests through strategic partnerships bridging hardware-software boundaries, while geographic expansion into underpenetrated logistics corridors accelerates.
Within the photogrammetry tier, Pix4D and DELAIR exemplify contrasting geographic and architectural positioning. Skydio occupies a distinctive position in autonomous navigation for defense and public safety applications. These three anchors illustrate how vendor strategy fragments across embedded flight systems, cloud-based processing engines, and hybrid deployment architectures competing for procurement preference among EASA-regulated operators.
| Leading Market Players |
|---|
| DroneDeploy |
| Pix4D |
| SZ DJI Technology |
| Skydio |
| Kespry |
| PrecisionHawk |
| Esri |
| AirMap |
| DELAIR |
| Others |
Value Network & Pricing Analysis
Swiss GNSS correction module concentration around Zurich and Geneva anchors single-source vulnerability that compresses margin spreads across EASA-certified autopilot tiers while inflating cloud infrastructure costs for GDPR-compliant analytics deployments. This component chokepoint forces software vendors to absorb upstream pricing volatility or pass through to agricultural cooperatives and logistics operators with varying elasticity.
Pricing Analysis
Iberian markets exhibit the widest SaaS subscription spreads, with Spanish engineering consultancies driving consumption-based pricing adoption while German agricultural enterprises accept premium tiers for EASA-certified-category compliance. Three-tier pricing structure across certified autopilot, standard mapping, and economy analytics levels differentiates procurement across government tenders and commercial fleets. Cost compression in standard-tier photogrammetry subscriptions is intensifying because cloud infrastructure costs for GDPR data residency inflate operational overhead. Logistics providers in Poland demonstrate highest price sensitivity, while French civil protection agencies anchor premium pricing with mandated audit trail requirements.
Supply Chain Analysis
Tariff exposure between Switzerland and EU member states dominates component sourcing strategy for high-precision GNSS modules that feed into Toulouse and Munich autopilot development clusters. Manufacturing concentrates in Switzerland, Germany, and Taiwan for semiconductor flight controllers, multispectral sensors, and lithium-polymer battery management systems. Raw material dependencies span gallium nitride for RF components, rare earth elements for sensor calibration, and cobalt for power density optimization. Single-source vulnerability in Swiss precision correction services creates systemic risk for centimeter-level navigation accuracy. Distribution runs through specialized aerospace distributors in Toulouse and direct OEM relationships for fleet-scale logistics deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone software markets monetize through recurring SaaS attach rates that expand faster than hardware replacement cycles, with consumption-based orthomosaic generation and predictive yield analytics outpacing perpetual license revenue pools.
For Market Incumbents: Build switching-cost moats through deep ERP integration with warehouse management systems at DHL and InPost distribution hubs. Defensive consolidation should prioritize acquisition of edge-computing autonomy stacks to neutralize latency advantages from Skydio and emerging navigation challengers. EASA certified-category recertification timelines stretching 18-24 months create regulatory barriers worth reinforcing through preemptive compliance investment. For New Entrants and Emerging Players: Pursue Polish last-mile logistics corridors where fleet orchestration software penetration remains underdeveloped relative to Western European benchmarks. White-space concentration in urban air mobility software testing around Warsaw and Kraków offers lower competitive density than saturated German agricultural platforms. Go-to-market positioning should emphasize CE marking acceleration under Radio Equipment Directive pathways to compress time-to-market against established vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors recurring-revenue software platforms with EASA certification moats over hardware-dependent autonomy challengers. Long-term viability across the projection horizon hinges on GDPR-compliant cloud architectures that sustain margin expansion against on-premise deployment cost structures. Acquisition target archetype: photogrammetry SaaS vendors with Iberian consumption-based pricing traction and established agricultural cooperative channel relationships. Signal to watch: EU AI Act risk classification documentation tooling emerging as standalone revenue stream.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Service Launch | Risk classification documentation creates recurring revenue from algorithmic audit mandates. |
| Edge Computing Architecture Migration | Onboard processing collapse latency for time-critical autonomous navigation decisions. |
| ERP Integration Partnership | Warehouse management system connectivity secures logistics provider switching costs. |
| Hybrid Deployment Tier Introduction | Edge preprocessing with cloud aggregation balances GDPR compliance against latency. |
| GNSS Module Supplier Diversification | Reduced Swiss concentration mitigates single-source vulnerability for RTK precision. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs at agricultural drone operators, EASA certification officers, logistics procurement leads, and photogrammetry software engineers, then refined through secondary validation against SEC filings from listed autonomy vendors, EASA regulatory notices, EU Green Deal subsidy disbursement records, and hyperscaler cloud infrastructure capex disclosures. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against EASA operational category fleet registrations anchored market sizing.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeling across flight control, mapping, fleet management, and data analytics product types, further disaggregated by agriculture, surveillance, delivery, and infrastructure inspection applications. CAGRs derived from fitted adoption curves for sensor fusion software procurement among French and German agricultural cooperatives, cross-referenced against cloud infrastructure scaling patterns for GDPR-compliant data residency.
Macroeconomic conditions sit as an overlay; deviation in EU digital agriculture subsidy disbursement rates or lithium-polymer battery chemistry cost curves would shift the trajectory for fleet-scale deployment economics. Forecasts reflect underlying assumptions about EASA regulatory stability and CE marking pathway continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Saas Backup Software Market
Software & Services
Global Open API Market
Software & Services
Enterprise Search Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Global Address Verification Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Global Nosql Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Automotive Design Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Global SEO Software Market