
 Diaper Packaging Machines Market | 2026-2036
Diaper Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Diaper Packaging Machines Market Analysis
Biodegradable polymer films is decoupling diaper packaging economics from conventional plastic-dependent machine designs. GDM S.p.A. leverages its Italian engineering base to dominate high-speed horizontal systems for premium diaper brands. COESIA S.p.A. sustains competitive pressure through integrated automation platforms spanning multiple hygiene categories. Optima Packaging Group GmbH anchors its position in robotic end-of-line solutions for flexible packaging formats.
Diaper packaging machines constitute electromechanical systems engineered to form, fill, and seal absorbent hygiene products at speeds typically exceeding 600 units per minute, utilizing servo-driven motion control and vision-based quality verification to maintain seal integrity and contamination-free output. Automatic technology leads installed capacity across mature manufacturing bases, while robotic segments capture fastest-growing interest for changeover-intensive production environments. Horizontal packaging occupies the core margin pool in developed markets, whereas flow wrapping expands in cost-sensitive geographies seeking versatile format handling.
FDA regulations govern sanitary contact surfaces and material compliance for diaper packaging destined for US healthcare channels, while EU REACH and F-Gas frameworks constrain adhesive and film chemistries used in European-sold equipment configurations. China's SAMR enforces GB standards for imported packaging machinery, creating certification barriers for non-domestic suppliers. Stakeholders must monitor how fragmented national sustainability mandates reshape machine specification requirements across their installed base and order pipelines.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing equipment replacement cycles as manufacturers race to certify biodegradable film-compatible machinery before mandates take full effect.
Growth Catalysts
- EU Green Deal packaging mandates:European diaper manufacturers face binding reduction targets for virgin plastic content, forcing wholesale upgrades to machinery capable of handling compostable laminates and paper-based barrier films.
- Healthcare channel expansion:US institutional buyers serving long-term care facilities and pediatric hospitals are specifying FDA-validated packaging lines with full batch traceability and sterile-seal verification.
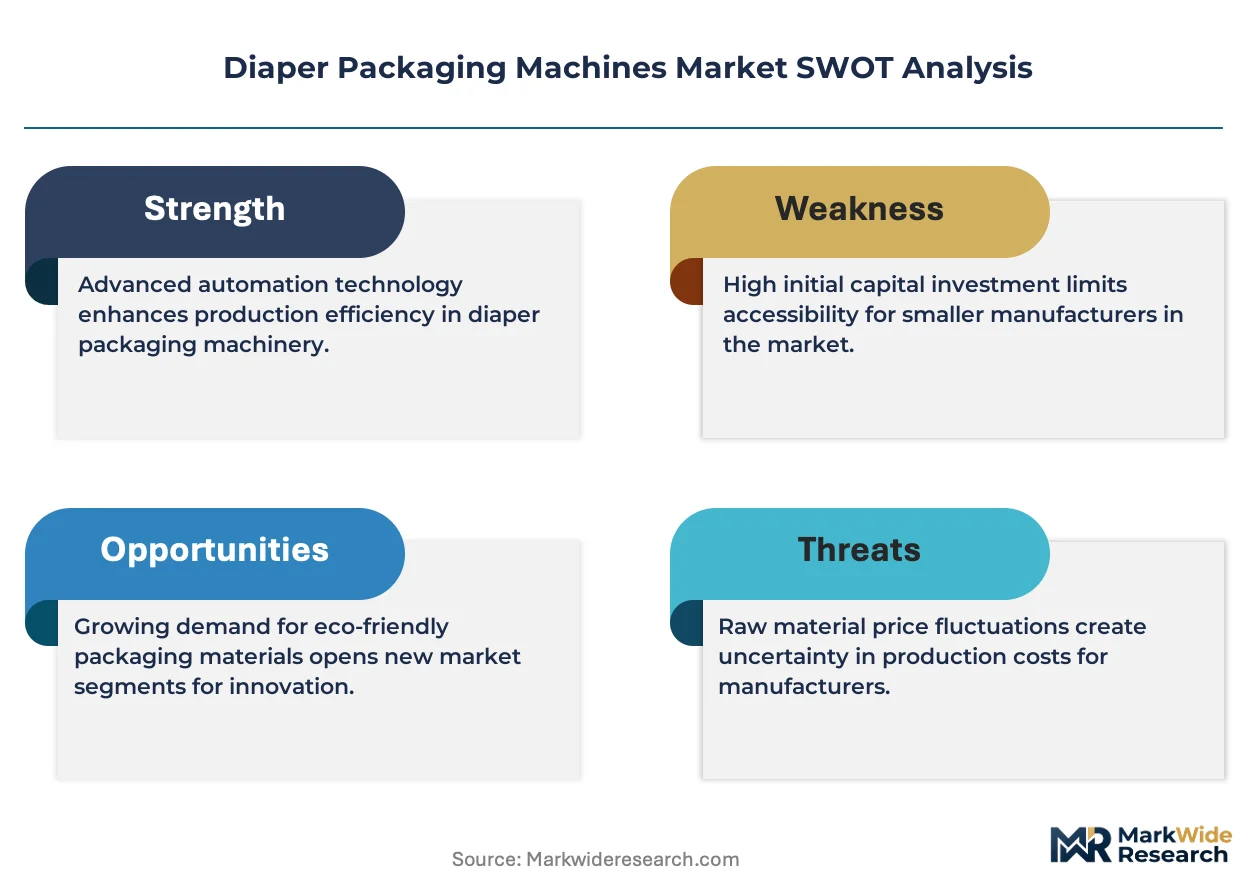
- Servo-driven motion architectures:Electromechanical systems replacing pneumatic actuators deliver 15-20% energy savings while enabling sub-millimeter registration accuracy for thinner, more sustainable film gauges.
Market Restraints
- Biodegradable film cost premiums:PLA and PBAT-based substrates cost 40-60% more than conventional PE structures, compressing OEM margins on entry-level equipment configurations.
- Critical component concentration:Precision servo motors and harmonic drives for high-speed indexing remain concentrated among Japanese and German suppliers, exposing lead time vulnerabilities.
- REACH chemical compliance:ECHA restrictions on certain adhesive chemistries and F-Gas phase-down rules for heat-sealing systems force costly revalidation of established machine designs.
Strategic Opportunities
- Saudi Arabia localization:SFDA medical device packaging requirements and MOHAP hygiene product standards are creating demand for regional assembly capacity serving Gulf Cooperation Council markets.
- Robotic changeover systems:Collaborative robotics for format-size adjustment are unifying changeover time compression with reduced skilled labor dependency in high-mix contract manufacturing environments.
- China dual carbon alignment:NMPA efficiency standards and provincial carbon intensity targets are accelerating replacement of legacy thermal-sealing equipment with induction and ultrasonic alternatives.
Industry Challenges
- Multi-standard certification timelines:Simultaneous FDA, CE, and GB validation for a single machine platform extends commercialization cycles by 8-14 months.
- Legacy control architecture integration:Proprietary fieldbus systems from 1990s-era installed bases resist seamless integration with modern IoT-enabled quality monitoring layers.
- Mechatronics talent scarcity:The intersection of servo tuning, vision algorithm configuration, and hygienic mechanical design commands premium compensation in manufacturing clusters near Bologna and Stuttgart.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaper Packaging Machines Market |
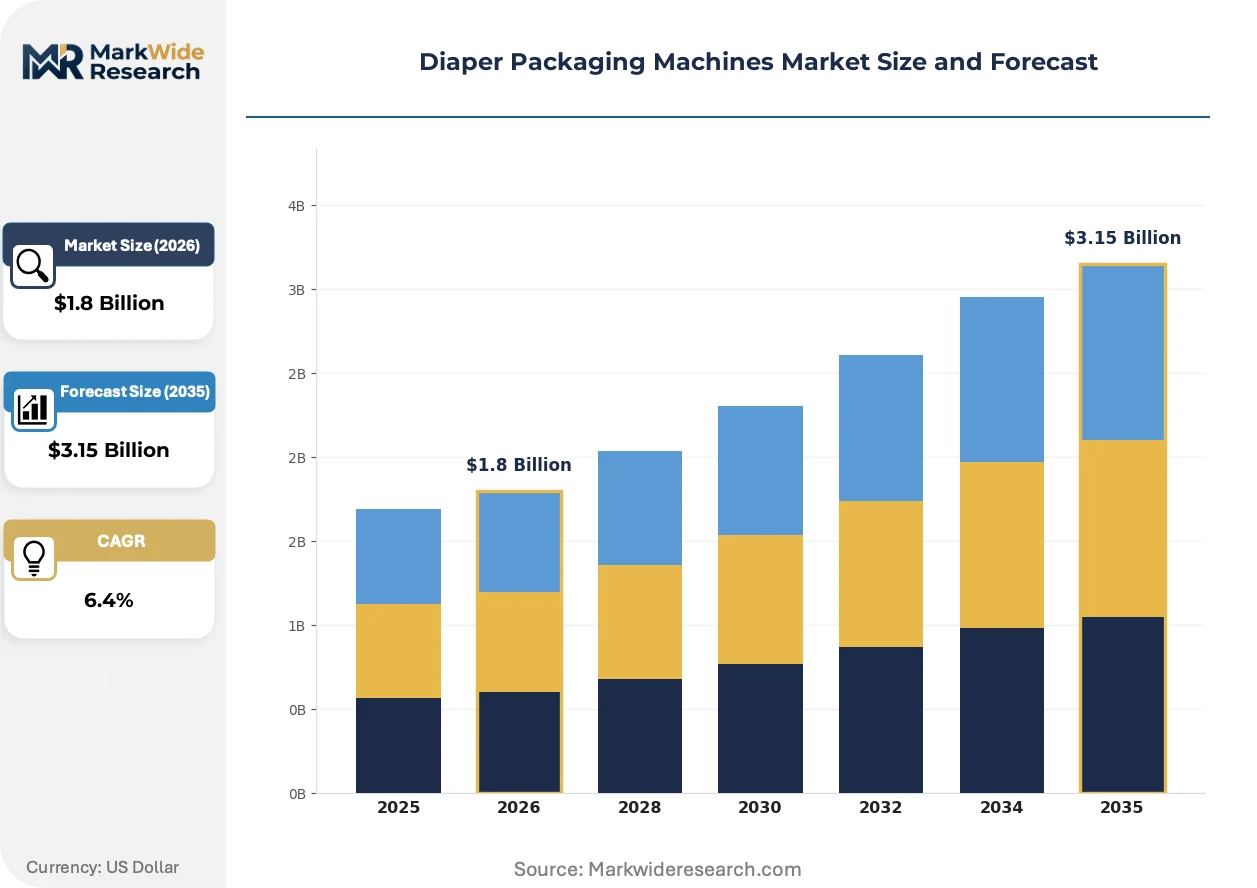
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Packaging, Horizontal Packaging, Flow Wrapping, Blister Packaging Technology: Automatic, Semi-Automatic, Manual, Robotic End User: Manufacturers, Distributors, Retailers, Hospitals Packaging Material: Plastic, Paper, Biodegradable, Composite |
| Companies Covered | GDM S.p.A., COESIA S.p.A., Optima Packaging Group GmbH, AnQing Heng Chang Machinery, Delta SRL Unipersonale, Fameccanica Data SPA, Edson Packaging Machinery Ltd, Welldone, Curt G. Joa, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaper Packaging Machines Market Emerging Trajectories
Active material science breakthroughs and regulatory chemistry constraints are forcing simultaneous hardware and process reinvention across the installed base.
Ultrasonic sealing technology is unifying hermetic seal integrity with reduced thermal stress on heat-sensitive biodegradable films. Premium diaper brands in Germany and the Netherlands are specifying all-ultrasonic sealing stations for their newest production lines. This convergence is compressing the viable lifespan of conventional hot-bar sealing equipment in European manufacturing facilities.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-coated sealing jaws from equipment configurations sold into EU member states. Machine builders are responding with ceramic-coated and plasma-treated metal surfaces that sacrifice some release properties for regulatory compliance. Pediatric and incontinence product lines with the strictest chemical contact standards are experiencing the most acute reconfiguration pressure.
Contract manufacturers are consolidating procurement authority for packaging lines at the parent-company level rather than individual plant discretion. This centralization is displacing regional machinery distributors with direct OEM relationships and embedded service contracts. The shift is most visible among North American private-label hygiene producers seeking standardized changeover protocols across multi-site networks.
Diaper Packaging Machines Market Segmentation
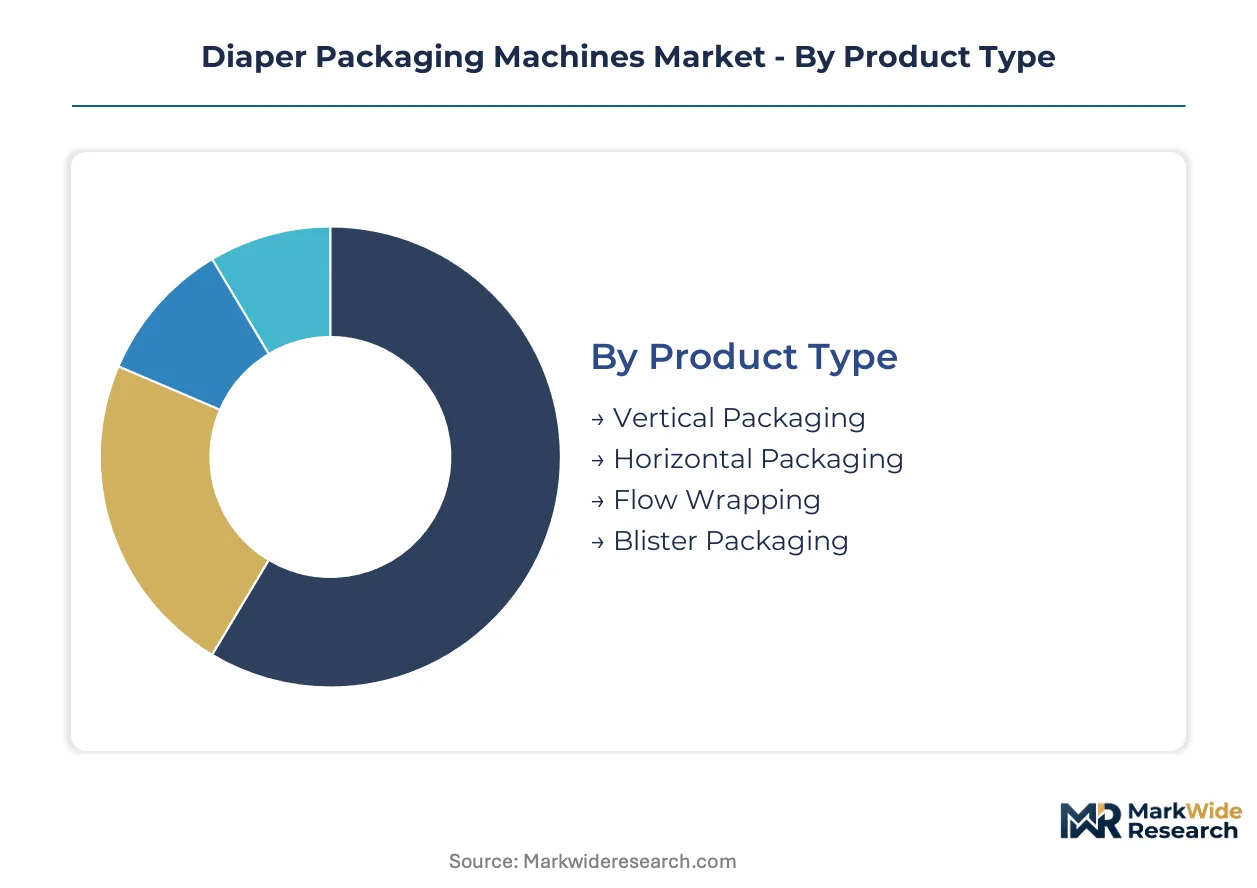
Segmentation in diaper packaging machines reveals how equipment specifications diverge across hygiene product categories, manufacturing scales, and sustainability mandates. Each dimension carries distinct technical requirements that shape procurement decisions and OEM development priorities.
Product Type:
Standalone packaging systems dominate high-volume diaper production, while modular subsystems integrate into broader hygiene manufacturing lines. Integration depth varies by facility age and product mix complexity.
- Horizontal Packaging:Servo-driven cartoning systems handle pre-formed diaper stacks at speeds exceeding 600 units per minute, utilizing continuous motion for minimal dwell time. German and Dutch manufacturers specify these for premium diaper lines facing EU Green Deal packaging waste mandates. Horizontal systems command the core margin pool in developed European markets.
- Flow Wrapping:Rotary jaw mechanisms wrap individual diapers or small counts in flexible film, offering format versatility with lower capital intensity. Demand concentrates in Southeast Asian contract manufacturing hubs serving private-label brands. Flow wrapping expands most quickly in cost-sensitive geographies seeking multi-SKU flexibility.
- Vertical Packaging:Form-fill-seal towers accommodate bulk diaper counts in gusseted bags, common in club-store and institutional formats. These systems embed readily into automated warehouse feeding lines.
- Blister Packaging:Thermoformed cavity systems seal diapers in rigid-backed trays, primarily for retail display packs and travel-size SKUs. Hospital and long-term care channels drive niche demand.
Horizontal packaging leads volumes today; flow wrapping is gaining share fastest.
Technology:
Capital intensity and labor availability determine technology selection, with cost tiers separating fully automated lines from operator-assisted configurations.
- Automatic:PLC-controlled electromechanical systems execute forming, filling, and sealing without operator intervention, integrating vision inspection and reject handling. Automatic technology anchors installed capacity across mature manufacturing bases in Germany, Italy, and the US.
- Robotic:Collaborative arms and delta robots manage changeover, palletizing, and quality verification tasks, compressing format-switch downtime from hours to minutes. Robotic segments are climbing the fastest as contract manufacturers prioritize high-mix flexibility.
- Semi-Automatic:Operator-fed systems with automated sealing cycles serve emerging market producers scaling from manual operations. These configurations balance throughput with technical workforce constraints.
- Manual:Foot-pedal or hand-actuated sealers persist in micro-enterprises and specialty medical diaper production. Regulatory compliance limitations constrain expansion.
Automatic systems dominate current installations; robotic configurations show steepest expansion trajectory.
End User:
Customer scale and channel requirements fragment demand across integrated manufacturers and fragmented downstream handlers.
- Manufacturers:Brand owners and contract producers operate captive packaging lines with dedicated OEM service contracts, specifying FDA-validated or CE-marked equipment. Manufacturers absorb the majority of capital expenditure in this market.
- Distributors:Third-party logistics providers repackage bulk shipments into retail-ready configurations, utilizing semi-automatic equipment for seasonal demand surges.
- Retailers:Private-label program operators increasingly specify packaging machinery at supplier facilities, centralizing format standardization.
- Hospitals:Institutional procurement departments demand sterile-seal verification and full batch traceability for long-term care and pediatric units.
Manufacturers account for the largest equipment base; hospital specifications are tightening fastest.
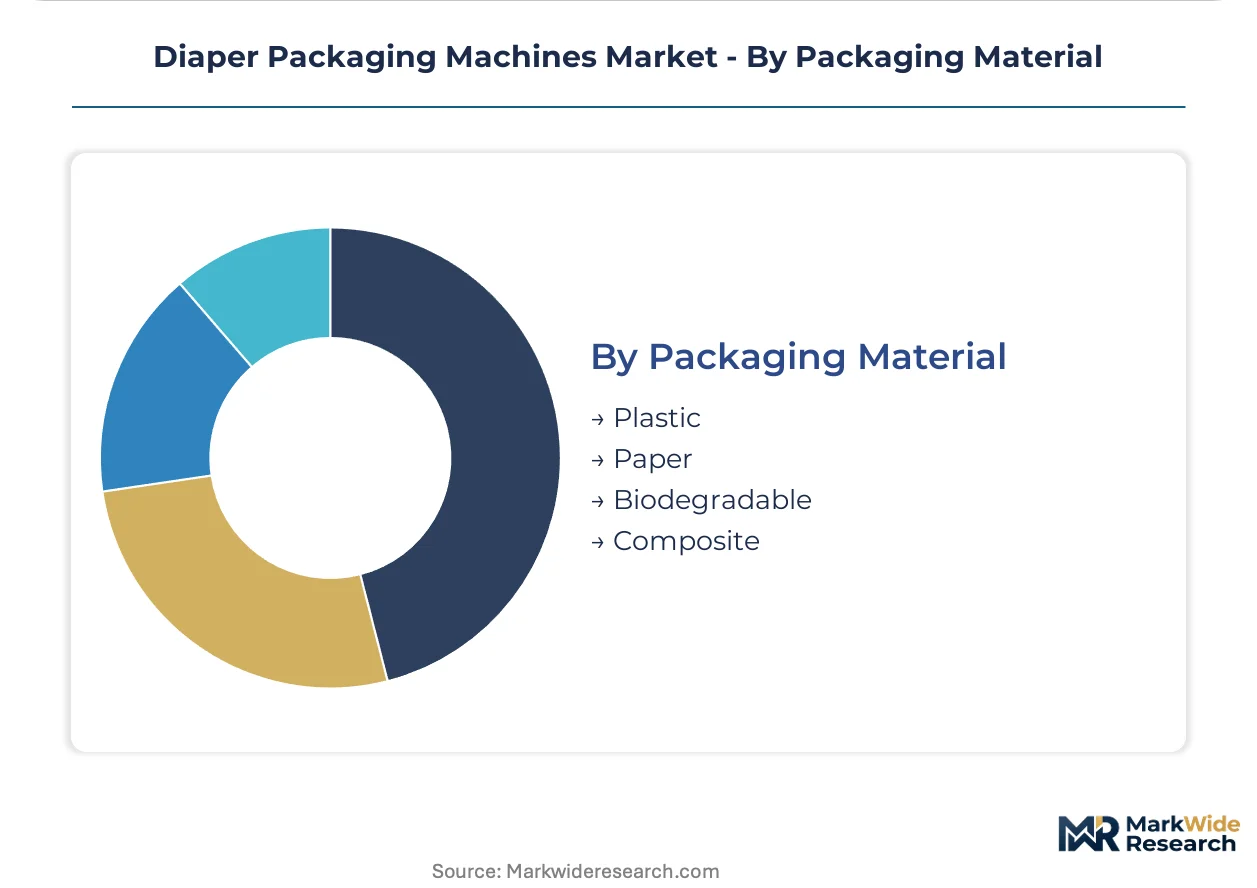
Packaging Material:
Substrate chemistry dictates sealing technology, film handling, and regulatory compliance architecture across machine configurations.
- Biodegradable:PLA, PBAT, and paper-based barrier films require modified sealing temperatures and reduced thermal stress, driving ultrasonic and induction sealing adoption. EU REACH and F-Gas frameworks accelerate biodegradable-compatible machinery demand in European markets.
- Plastic:Conventional PE and PP structures remain dominant in high-speed lines, optimized for hot-bar sealing with fluoropolymer-coated jaws. Cost premiums on sustainable alternatives sustain plastic-film equipment relevance.
- Paper:Kraft and coated paper formats serve premium eco-brands and select retail channels, demanding specialized tension control and moisture barrier integration.
- Composite:Multi-layer laminates combining plastic, paper, and metallized films offer barrier performance with partial renewable content, complicating recycling streams and machine specification.
Plastic-based systems retain volume leadership; biodegradable-compatible equipment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's machinery OEM clusters around Stuttgart and Bologna anchor diaper packaging equipment supply chains serving European and Middle Eastern buyers. Manufacturers in these hubs retrofit servo-driven systems for biodegradable film compatibility ahead of EU Green Deal enforcement timelines.
Germany
Baden-Württemberg manufacturers face binding virgin plastic reduction targets under EU packaging waste directives. ECHA REACH restrictions on fluoropolymer coatings force sealing jaw redesigns at OEM facilities near Stuttgart. Machine builders in the region certify biodegradable-compatible lines for export to GCC markets.
Italy
Emilia-Romagna's packaging machinery corridor specializes in high-speed horizontal systems for premium diaper brands. CE marking requirements under EU machinery directives govern equipment validation protocols. Bologna-area OEM clusters integrate ultrasonic sealing modules to handle compostable laminates.
United States
FDA-validated packaging lines with batch traceability serve healthcare channel expansion into long-term care facilities. EPA industrial emissions frameworks influence thermal-sealing equipment specifications. Wisconsin and Illinois manufacturing bases supply robotic end-of-line systems for North American contract manufacturers.
China
Provincial carbon intensity targets under dual carbon goals accelerate induction and ultrasonic sealing adoption in Yangtze River Delta production hubs. SAMR GB standards create certification barriers for imported machinery. Zhejiang and Jiangsu fabricators localize servo motor supply chains to reduce Japanese component dependency.
Saudi Arabia
SFDA medical device packaging requirements and MOHAP hygiene standards drive demand for regional assembly capacity. Equipment suppliers establish service presence in Riyadh and Jeddah to serve GCC markets. Localized production reduces lead times for biodegradable film-compatible machinery deployments.
Diaper Packaging Machines Market Vendor Landscape
Technology licensing dominates the current landscape as OEMs exchange servo control architectures and sealing process patents. The vendor base concentrates among Italian and German engineering houses with captive automation platforms, alongside emerging Chinese fabricators scaling modular equipment lines. Two strategic archetypes define positioning: integrated hygiene automation providers spanning multiple product categories, and pure-play packaging specialists with deep format-handling expertise. Geographic expansion into GCC markets and portfolio diversification into biodegradable-compatible systems represent the dominant competitive vectors.
Within the European integrated automation tier, COESIA S.p.A. and GDM S.p.A. exemplify machinery houses with multi-category hygiene platforms, while Optima Packaging Group GmbH anchors the robotic end-of-line specialization vector. Among Asian fabricators, AnQing Heng Chang Machinery represents the modular equipment archetype targeting cost-sensitive geographies. These named entities occupy positions across the premium-to-standard equipment spectrum without exhaustive market share claims.
| Leading Market Players |
|---|
| GDM S.p.A. |
| COESIA S.p.A. |
| Optima Packaging Group GmbH |
| AnQing Heng Chang Machinery |
| Delta SRL Unipersonale |
| Fameccanica Data SPA |
| Edson Packaging Machinery Ltd |
| Welldone |
| Curt G. Joa, Inc. |
| Others |
Supply Flow & Price Mechanics
Ultrasonic sealing adoption across European diaper packaging lines simultaneously elevates capital expenditure thresholds and concentrates procurement authority among integrated OEMs capable of certifying biodegradable-compatible systems. This technology transition compresses margins for entry-level equipment suppliers while amplifying pricing power for German and Italian engineering houses with captive servo control architectures.
Pricing Analysis
Input-cost pass-through from precision servo motors and harmonic drives runs through equipment pricing tiers, with Japanese and German component premiums inflating base machine costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated healthcare configurations from CE-marked industrial lines and semi-automatic emerging-market units. Cost compression in economy-tier equipment is intensifying because Chinese fabricators localize servo supply chains. Contract manufacturers exhibit highest price sensitivity due to centralized parent-level procurement, while hospital channel buyers prioritize sterile-seal verification over capital cost.
Supply Chain Analysis
Refurbishment flows for 1990s-era thermal-sealing equipment create secondary market circulation before EU F-Gas phase-down rules render legacy systems non-compliant. Geographic supply concentration centers on Germany, Italy, and China, with Baden-Württemberg and Emilia-Romagna anchoring high-speed horizontal system production. Raw material dependencies draw from specialty steel for sealing jaws, ceramic coatings replacing fluoropolymers, and biodegradable film substrates. Single-source vulnerability persists for precision indexing drives from Japanese suppliers. Distribution runs through direct OEM relationships displacing regional machinery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diaper packaging machines market functions as a stable compounder underpinned by EU Green Deal mandates that force recurring equipment replacement cycles regardless of macroeconomic cycles.
For Market Incumbents: Extend ultrasonic sealing module standardization across equipment platforms to capture biodegradable film transition premiums. Consolidate service contracts with North American contract manufacturers undergoing parent-level procurement centralization. Defend against Chinese modular fabricators by embedding IoT-enabled quality monitoring layers that resist legacy control architecture integration. For New Entrants and Emerging Players: Begin with robotic changeover system subsystems for high-mix contract manufacturing environments where skilled labor scarcity commands premium pricing. The Saudi Arabian localization opportunity under SFDA medical device packaging requirements offers the most penetrable geography. Pursue joint venture structures with Zhejiang fabricators to bypass SAMR GB certification barriers for imported machinery. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap packaging automation specialists because parent-level procurement centralization displaces fragmented regional distributor networks. Five-to-ten-year viability hinges on biodegradable-compatible equipment certification depth rather than conventional plastic-film machine volumes. Monitor ECHA REACH Annex XVII expansion timelines for early signals of additional sealing jaw coating restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing Module Development | EU F-Gas phase-down rules eliminate thermal-sealing equipment viability in member states. |
| Biodegradable Film Compatibility Certification | REACH restrictions on fluoropolymer coatings force hardware revalidation for European sales. |
| Robotic Changeover System Integration | High-mix contract manufacturers compress format-switch downtime from hours to minutes. |
| GCC Regional Assembly Capacity | SFDA and MOHAP standards in Saudi Arabia reduce lead times for Middle Eastern deployments. |
| Servo Motor Supply Chain Localization | Chinese provincial carbon intensity targets accelerate domestic component substitution. |
Methodological Framework
Multiple input streams — OEM engineering directors, contract manufacturer procurement leads, hygiene product plant managers, and aftermarket service heads — were reconciled against customs trade data, EU machinery directive filings, and SEC equipment supplier disclosures. Bottom-up installation base estimates were triangulated with top-down capital expenditure projections across the analysis window.
Historical capacity deployment patterns were cross-referenced against panel input from industry stakeholders to model segment-level trajectories. Segmentation dimensions included packaging format type, automation technology tier, end-user scale, and substrate material chemistry. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate enforcement timelines, with specific weighting applied to EU Green Deal compliance deadlines and FDA healthcare channel validation requirements.
Several conditions sit outside the modeled scope, including unannounced adhesive chemistry restrictions under REACH Annex XVII, sudden F-Gas regulation acceleration, and geopolitical disruptions to Japanese servo motor supply chains. Practitioners should monitor ECHA substance restriction proposals and NMPA efficiency standard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Tray Loader Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Strap Dispenser Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Beverage Packaging Equipment Market