
 Retail Media Creative Optimization Market | 2026-2036
Retail Media Creative Optimization Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Media Creative Optimization Market Insights
Real-time creative assembly is fragmenting the traditional ad-tech stack into retailer-specific ecosystems. Amazon leverages proprietary demand-side infrastructure to control the full campaign lifecycle from creative generation to attribution. Criteo competes as an independent intermediary, sustaining access across multiple retail media platforms without captive inventory. Walmart anchors its network through in-store purchase data linked to digital ad exposure, differentiating on closed-loop measurement.
Retail media creative optimization encompasses the automated generation, testing, and deployment of advertising assets within retailer-controlled digital properties, where machine learning models dynamically assemble creative elements based on inventory availability, shopper behavior, and contextual signals. Its primary commercial purpose is to maximize return on ad spend by reducing the latency between consumer intent signals and relevant creative delivery. The optimization technique dimension shows machine learning models capturing the fastest expansion as advertisers shift from rule-based automation toward predictive systems that anticipate purchase propensity. Creative format dynamics reveal dynamic ads pulling margin pools away from static display units, as real-time product feeds enable personalization at scale.
The Federal Trade Commission scrutinizes data practices in retail media networks, while the European Union's GDPR and Digital Markets Act impose consent and interoperability requirements that shape platform architecture. The California Consumer Privacy Act extends these constraints to US-based operations, forcing technical investments in privacy-preserving targeting methods. Stakeholders must monitor how regulatory fragmentation between jurisdictions affects cross-border campaign orchestration and data portability.
Market Dynamics
Real-time creative assembly is compressing the traditional ad-tech supply chain into closed retailer ecosystems. Advertisers now face platform-specific technical requirements that fragment campaign management and force duplicative creative production workflows.
Growth Catalysts
- First-Party Data Imperative:The European Union's GDPR and Digital Markets Act are accelerating advertiser migration toward retailer-owned data environments. CPG brands redirect digital budgets to capture deterministic purchase signals.
- Closed-Loop Attribution:In-store purchase data linked to digital ad exposure enables precise ROAS measurement. Walmart and Kroger leverage this capability to differentiate their networks.
- Machine Learning Assembly:Predictive models now anticipate purchase propensity rather than reacting to behavior signals. Dynamic creative optimization reduces latency between intent and relevant delivery.
Market Restraints
- Platform Fragmentation:Each retail media network operates proprietary creative specifications and auction mechanics. Advertisers must maintain separate production pipelines for Amazon, Walmart, and Target.
- Privacy-Preserving Targeting Costs:Technical investments required for GDPR and California Consumer Privacy Act compliance increase operational overhead without proportional performance gains.
- Data Silo Lock-In:Retailers restrict cross-platform data portability. Campaign insights remain trapped within individual retail media networks.
Strategic Opportunities
- Independent Intermediary Positioning:Technology vendors sustaining access across multiple retail platforms without captive inventory capture margin pools from fragmented demand.
- CTV Retail Media Extension:Connected television inventory within retailer-owned streaming properties enables upper-funnel creative formats previously unavailable in search and display.
- EU Interoperability Mandates:The Digital Markets Act's data portability requirements may force retail media networks to open APIs, reducing switching costs for advertisers.
Industry Challenges
- Creative Production Bottleneck:Real-time assembly demands exponentially more asset variants than static campaigns. Creative operations teams lack tooling to generate and quality-control dynamic templates.
- Measurement Standardization Gap:No unified methodology exists for comparing performance across Amazon, Walmart, and independent retail media networks. Advertisers struggle to allocate budgets optimally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Media Creative Optimization Market |
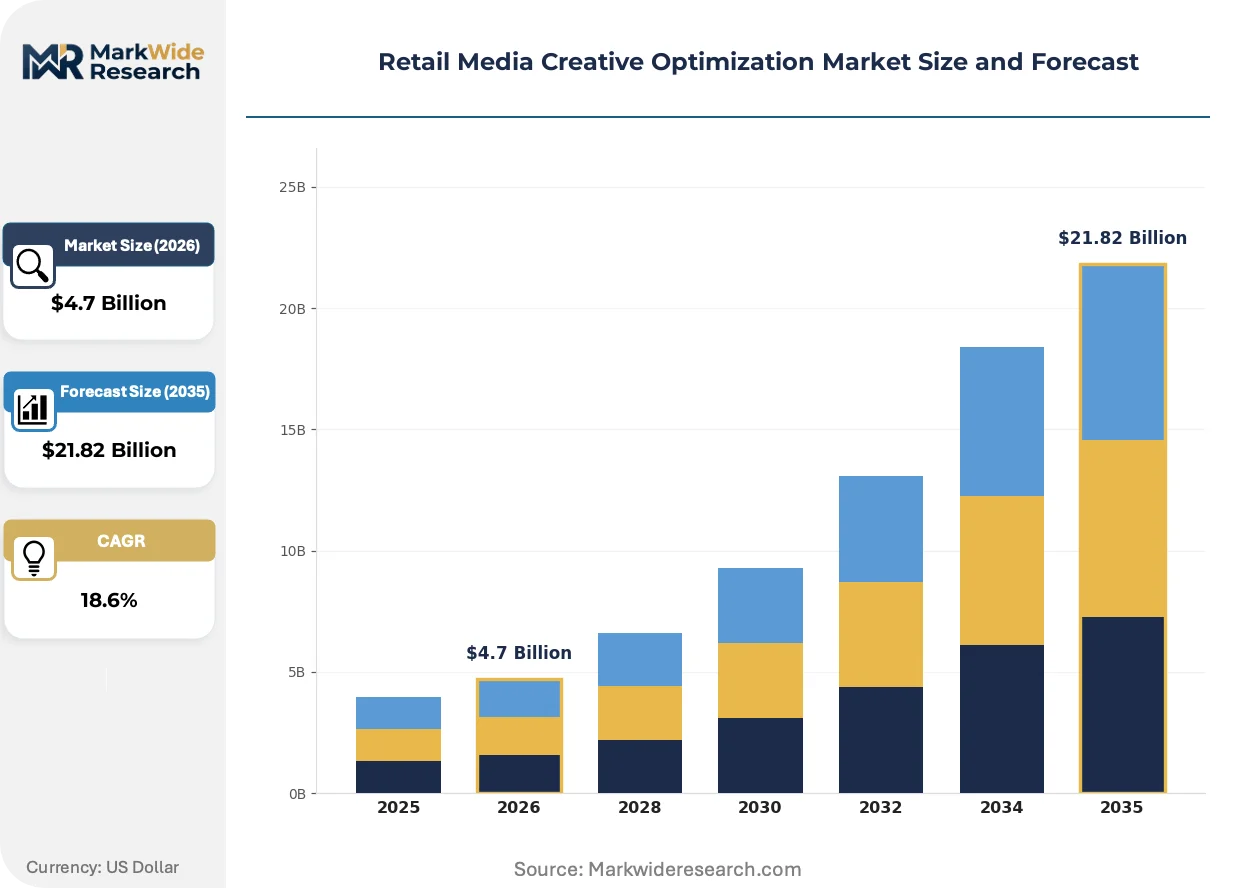
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Channel Type: Search Engines, Social Networks, Video Platforms, Email Marketing, Mobile Apps, Affiliate Networks Creative Format: Display Ads, Native Ads, Interactive Banners, Rich Media, Sponsored Content, Dynamic Ads Optimization Technique: A/B Testing, Multivariate Testing, Machine Learning Models, Behavioral Targeting, Predictive Analytics, Rule-Based Automation Customer Category: Brand Manufacturers, Online Retailers, Digital Agencies, Content Producers, Marketing Consultants, E-commerce Platforms |
| Companies Covered | Amazon, Criteo, Walmart, Target, Kroger, Instacart, eBay, Wayfair, Kevel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Media Creative Optimization Market Trends and Innovations
Generative creative systems are compressing production timelines from weeks to hours. Three converging developments are restructuring how advertising assets are conceived, validated, and deployed within retail environments.
Generative AI models trained on product catalogs and performance data now produce creative variants without human art direction. Consumer packaged goods brands with high SKU counts deploy these systems to maintain creative freshness across thousands of product combinations. Static template-based production is rendering obsolete as algorithms generate personalized imagery and copy based on real-time inventory signals.
The Federal Trade Commission's scrutiny of retail media data practices is tightening consent requirements for audience targeting. California's Consumer Privacy Act extends similar constraints to US-based operations, forcing technical investments in differential privacy and federated learning. Advertisers in the United States are responding by shifting budget toward contextual and first-party data strategies that reduce regulatory exposure.
Brand marketers now demand outcome-based compensation tied to verified purchase events rather than impression or click metrics. Retail media networks are unbundling creative services from media buying to accommodate this shift. This reconfiguration is most visible in the United States, where Walmart and Target have introduced self-service interfaces that separate creative asset management from campaign execution.
Retail Media Creative Optimization Market Segmentation
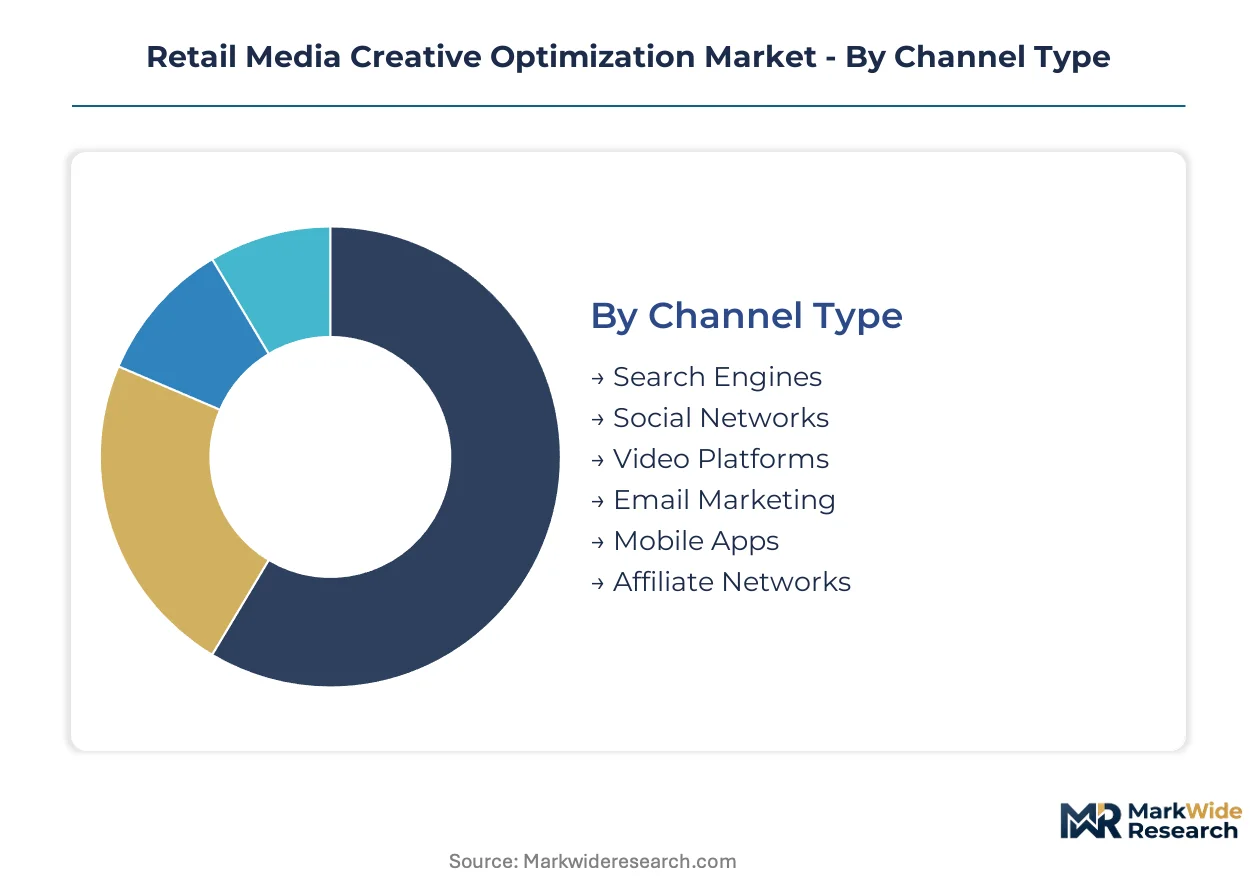
Segmentation in retail media creative optimization reveals how technical requirements and buyer sophistication vary across deployment contexts. Channel infrastructure, creative complexity, and optimization maturity each create distinct operational profiles that shape vendor positioning and capability investments.
Channel Type:
Search engines turn over creative assets fastest as query volumes shift hourly, while affiliate networks operate on monthly cycles with longer lead times for publisher integration.
- Search Engines:Text and shopping ad formats demand real-time keyword alignment with inventory feeds. Retailers like Amazon and Walmart prioritize this channel for capturing bottom-funnel intent signals from high-volume commercial queries.
- Social Networks:Visual-first creative formats require rapid iteration against engagement metrics. Meta and TikTok integration within retail media stacks concentrates demand among beauty and fashion advertisers seeking discovery-driven purchase paths.
- Video Platforms:Connected television inventory extends retail media into upper-funnel awareness campaigns.
- Email Marketing:Personalized product recommendations embedded in retailer-owned newsletters leverage deterministic purchase history.
- Mobile Apps:In-app retail media networks capture on-the-go purchase intent through geofenced notifications.
- Affiliate Networks:Publisher-mediated placements require standardized creative templates for scale.
Search engines anchor the volume base while video platforms gain share at the steepest rate as connected television inventory expands.
Creative Format:
Production cost tiers separate static units from data-intensive formats, with premium pricing attached to real-time assembly capabilities.
- Dynamic Ads:Algorithmic assembly of product imagery, pricing, and promotional copy responds to inventory fluctuations and shopper signals. Amazon's demand-side infrastructure and Walmart's in-store linkage drive advertiser migration toward this format.
- Native Ads:Editorial-style placements within retailer content feeds reduce ad avoidance. Target's Roundel network emphasizes these units for CPG brands seeking contextual alignment with shopping inspiration content.
- Display Ads:Standard banner formats remain prevalent for awareness objectives.
- Interactive Banners:Expandable units with embedded product carousels increase engagement duration.
- Rich Media:Video and gamified elements command production premiums.
- Sponsored Content:Long-form retailer-published articles feature brand messaging.
Display ads retain the largest installed base while dynamic ads expand most quickly as machine learning assembly matures.
Optimization Technique:
Capability maturity separates rule-based systems from predictive architectures, with implementation complexity rising alongside performance potential.
- Machine Learning Models:Neural networks trained on purchase propensity signals anticipate consumer needs before explicit search behavior. Kroger's 84.51° data science division and Amazon's proprietary algorithms exemplify this approach.
- Behavioral Targeting:Segmentation based on browsing and purchase history enables relevance without real-time prediction. GDPR consent requirements in the European Union and CCPA obligations in California constrain data collection scope.
- A/B Testing:Controlled experiments compare creative variants against defined success metrics.
- Multivariate Testing:Factorial designs isolate individual creative element contributions.
- Predictive Analytics:Statistical models forecast campaign performance from historical patterns.
- Rule-Based Automation:Predefined triggers execute creative swaps without algorithmic learning.
Rule-based automation dominates current deployment volumes while machine learning models capture the steepest adoption trajectory.
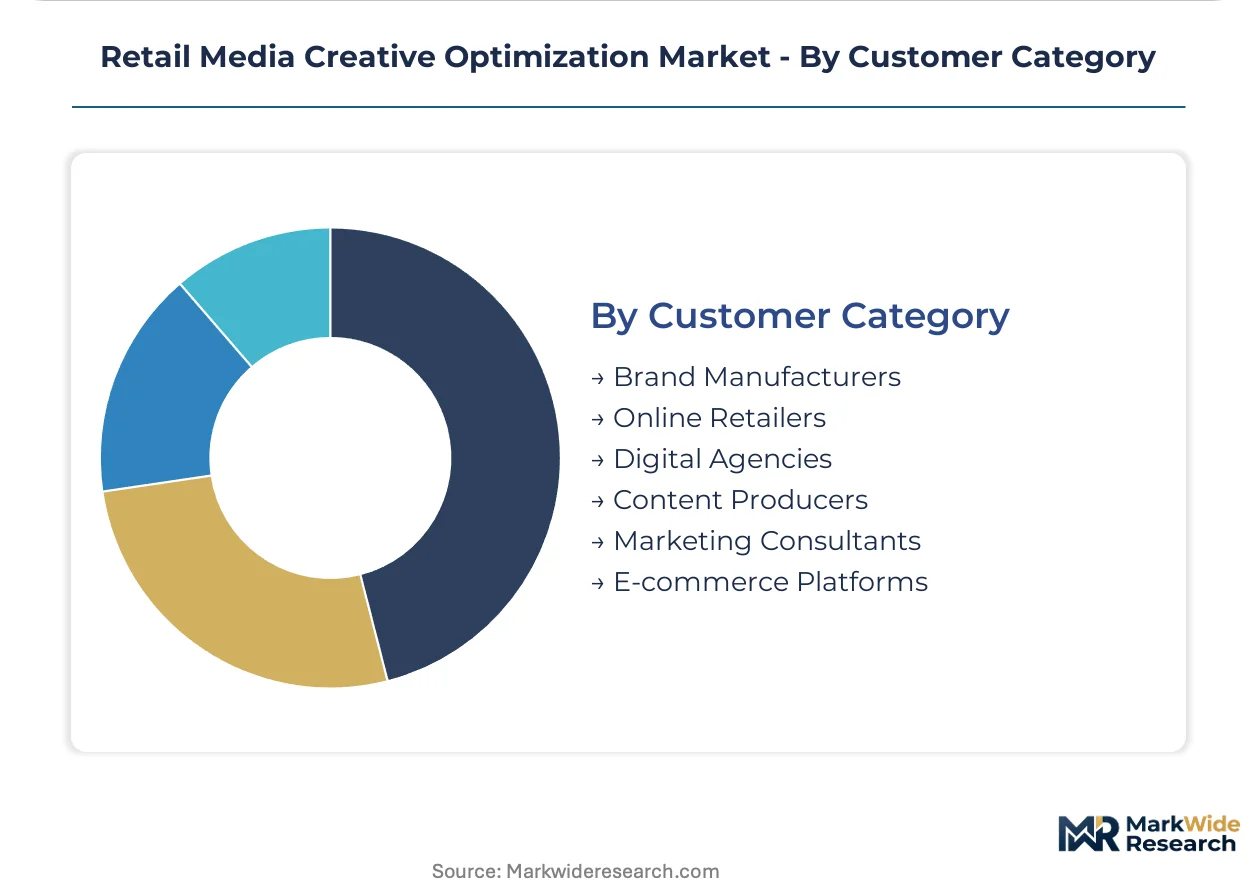
Customer Category:
Organizational scale and technical sophistication determine service model requirements, from self-service platforms to managed creative operations.
- Brand Manufacturers:Consumer packaged goods companies with high SKU counts require automated creative generation at scale. Procter & Gamble and Unilever allocate increasing digital budgets to retail media networks for closed-loop attribution.
- Digital Agencies:Intermediary buyers manage cross-platform campaigns for multiple advertisers. Independent shops compete against in-house retail media specialists at holding companies.
- Online Retailers:Marketplace sellers and direct-to-consumer brands purchase placement within competitor networks.
- E-commerce Platforms:Retailers operating their own media networks sell inventory to third-party advertisers.
- Content Producers:Publishers and creators monetize audiences through retail media partnerships.
- Marketing Consultants:Advisory firms guide strategy without executing media buys.
Brand manufacturers anchor the spending base while digital agencies gain influence fastest as platform fragmentation increases outsourcing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial surplus in retail media creative optimization technology exports, while the European Union and China remain net importers of optimization infrastructure and machine learning assembly tools. Cross-border data flows for closed-loop attribution face mounting regulatory friction.
United States
Consumer packaged goods brands concentrate digital budget allocation toward Walmart, Target, and Kroger networks. The FTC scrutinizes data practices in retail media, tightening consent requirements for audience targeting. New York and Chicago anchor the agency ecosystem managing cross-platform campaign orchestration for multinational advertisers.
United Kingdom
Grocery retailers Tesco and Sainsbury's expand self-service media platforms to capture CPG spending migrating from Meta and Google. GDPR and the Digital Markets Act impose interoperability requirements that shape platform architecture. London's ad-tech cluster concentrates independent intermediaries sustaining access across multiple retail networks.
Germany
Retailers Rewe and Edeka build proprietary demand-side infrastructure to compete with Amazon's dominance in continental Europe. The EU AI Act and GDPR constrain machine learning model training on consumer purchase data. Berlin and Hamburg host privacy-preserving targeting startups developing federated learning solutions.
China
Alibaba and JD.com operate closed retail media ecosystems with creative optimization capabilities rivaling Western platforms. SAMR enforces data localization and antitrust provisions affecting cross-border campaign management. Shanghai and Shenzhen concentrate engineering talent for real-time creative assembly systems.
Japan
Rakuten and Seven & I Holdings expand retail media networks leveraging convenience store purchase data for digital attribution. METI promotes data portability frameworks affecting retailer data silos. Tokyo's marketing technology corridor hosts agencies specializing in dynamic creative optimization for high-SKU beauty and electronics brands.
Retail Media Creative Optimization Market Competitive Landscape
On the supply side, the industry is consolidating around retailer-owned platforms with captive inventory, while independent intermediaries sustain relevance through cross-platform access. Three strategic archetypes dominate: vertically integrated retailers controlling full campaign lifecycles, technology vendors operating as neutral intermediaries, and specialized creative automation firms. Competitive moves center on API interoperability investments and privacy-preserving targeting technology licensing.
Within the retailer-integrated tier, Amazon and Walmart exemplify closed-ecosystem dominance through proprietary demand-side infrastructure and in-store purchase data linkages. Criteo occupies a position as the leading independent intermediary, sustaining advertiser access across multiple retail media platforms without captive inventory. These three anchors represent divergent structural bets on whether retail media creative optimization converges toward consolidation or persists in fragmented, multi-platform configurations.
| Leading Market Players |
|---|
| Amazon |
| Criteo |
| Walmart |
| Target |
| Kroger |
| Instacart |
| eBay |
| Wayfair |
| Kevel |
| Others |
Pricing and Supply Chain Analysis
Seattle's engineering corridor concentrates demand-side infrastructure development, with Amazon's proprietary platform investments feeding downstream pricing power toward closed-ecosystem retailers. Cost compression in creative automation tooling is intensifying because generative AI vendors compete for enterprise SaaS contracts.
Pricing Analysis
Industrial OEM buyers anchor a subscription-SaaS tiered pricing structure across creative optimization platforms. Three-tier pricing structure across premium, standard, and economy levels separates full-stack managed services from self-service API access and basic template libraries. Price differentiation rests on customization depth and closed-loop attribution certification. Brand manufacturers with high SKU counts show least price sensitivity due to ROAS verification requirements, while small marketplace sellers face margin pressure from per-impression minimums.
Supply Chain Analysis
Extended payment terms from retail media networks to creative automation vendors now stretch 90-120 days, compressing working capital for independent intermediaries. Supply concentrates in the United States, China, and Germany for machine learning infrastructure and cloud compute resources. Raw material dependencies span GPU chipsets, training data licensing, and federated learning frameworks. Single-source vulnerability runs through NVIDIA's datacenter hardware dominance. Distribution runs through direct API integrations and managed service partnerships with holding company agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail media creative optimization functions as a defensive-moat market where switching costs lock advertisers into retailer-specific data environments. Regulatory entrenchment via GDPR and Digital Markets Act compliance deepens incumbent advantages.
For Market Incumbents: Insulate platform dominance through backward integration into generative AI training infrastructure and exclusive data partnerships with grocery retailers. Independent intermediaries like Criteo threaten margin capture across fragmented networks. Vertical integration into first-party data clean rooms fortifies advertiser retention against interoperability mandates.
For New Entrants and Emerging Players: Establish a beachhead in privacy-preserving targeting technology serving EU-based advertisers facing GDPR consent constraints. The most penetrable segment comprises mid-market CPG brands lacking in-house creative operations. A go-to-market angle emphasizing cross-platform API standardization addresses fragmentation pain points.
For Investors and Strategic Acquirers: Long-term, this sits as a data-utility play because closed-loop attribution infrastructure becomes irreplaceable as third-party cookies deprecate. Acquisition targets include creative automation startups with retailer-agnostic template engines. The signal to watch is Digital Markets Act enforcement action forcing API openness.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Training Infrastructure | Amazon's proprietary models reduce creative production latency from weeks to hours for CPG advertisers. |
| Privacy-Preserving Targeting Investment | Differential privacy tooling addresses FTC scrutiny and CCPA compliance costs without performance degradation. |
| CTV Inventory Expansion | Walmart's streaming partnerships extend retail media into upper-funnel formats previously unavailable. |
| Cross-Platform API Standardization | Independent intermediaries capture margin pools from advertisers managing Amazon, Target, and Kroger simultaneously. |
| First-Party Data Clean Room Buildout | Kroger's 84.51° unit leverages in-store purchase linkage to differentiate closed-loop measurement. |
Research Methodology
Operator-level perspectives from retail media platform executives, CPG brand digital directors, agency trading desk leads, and creative automation engineers anchored the qualitative base. Secondary validation drew from SEC filings of publicly traded retail networks, FTC consent decree documentation, EU Digital Markets Act regulatory texts, and hyperscaler advertising revenue disclosures. Bottom-up triangulation across advertiser spending patterns and top-down reconciliation against retail media network revenue disclosures ensured cross-verification.
Scenario-bracketing framed the analytical approach across the projection horizon, with bull-case assumptions around generative AI adoption velocity and bear-case constraints from regulatory enforcement intensity. Segmentation dimensions modeled include channel type, creative format complexity, optimization technique maturity, and customer organizational scale. CAGRs derived from fitted growth curves against historical retail media spending migration patterns. Industry-specific forecast inputs encompass privacy regulation implementation timelines and closed-loop attribution technology diffusion rates.
Sensitivities concentrate around Digital Markets Act enforcement timing and generative AI creative quality thresholds. Forecasts reflect documented assumptions regarding retailer platform consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Global Printed Signage Market