
 Global Social Advertising and Social Media Market | 2026-2036
Global Social Advertising and Social Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Social Advertising and Social Media Market Foresight
Platform bundling of ad inventory with creator tools and analytics dashboards is broadening buyer choice across the social advertising ecosystem. Meta Platforms leverages its integrated suite of Facebook, Instagram, and WhatsApp to sustain cross-platform campaign orchestration for large advertisers. Google anchors search and YouTube social ad demand through unified audience profiling and intent-based targeting infrastructure. TikTok competes through short-form video native ad formats that dominate youth demographic engagement.
Social advertising and social media encompass digital channels where brands purchase sponsored placements within user-generated content feeds, leveraging programmatic auction systems, behavioral targeting algorithms, and real-time engagement metrics to drive measurable commercial outcomes. The technical stack relies on pixel-based conversion tracking, machine learning bid optimization, and first-party data integration to maintain attribution accuracy amid cookie deprecation. Video ads and sponsored posts represent the most dynamic format categories, with video commanding premium CPMs due to completion-rate performance while sponsored posts capture organic-style engagement that native ads monetize through blended feed placement. Cost-per-click and cost-per-impression business models remain mature revenue pools, though cost-per-action pricing gains traction as advertisers demand outcome-based accountability.
FDA oversight of pharmaceutical advertising on social platforms, FCC transparency requirements for political ad disclosures, and GDPR data-processing constraints in Europe collectively shape platform compliance investments and targeting capabilities. The EU AI Act adds algorithmic accountability mandates that affect automated ad delivery systems across European user bases. Stakeholders must monitor evolving privacy regulations and first-party data strategies to maintain addressable audience scale.
Market Dynamics
First-party data strategies are restructuring competitive advantage across social advertising as third-party cookie deprecation forces platforms to rebuild targeting infrastructure around direct user relationships and consent-based data collection.
Growth Catalysts
- EU AI Act algorithmic accountability:Platforms investing in transparent ad delivery systems gain preferential access to European Union markets where automated decision-making now requires documented compliance.
- Short-form video infrastructure:Advertisers allocate larger creative budgets to vertical video formats as completion rates on mobile-native content exceed traditional landscape placements.
- E-commerce platform integration:Social channels with native checkout capabilities capture direct-response advertising spend previously directed to external retail sites.
Market Restraints
- GDPR data-processing constraints:European privacy enforcement limits behavioral targeting precision and increases compliance costs for cross-border campaign management.
- Cloud infrastructure concentration:Three hyperscale providers dominate ad-serving compute capacity, creating single-point-of-failure risk for real-time bidding systems.
- Attribution window compression:Browser privacy features shorten conversion tracking from 28 days to 7 days, degrading campaign optimization accuracy.
Strategic Opportunities
- India digital advertising infrastructure:Underpenetrated small-business advertiser base offers expansion potential as UPI payment integration enables direct-response monetization.
- Retail media network convergence:Off-site social inventory sold through retail data clean rooms combines purchase intent signals with platform reach.
- Connected TV social extension:Living-room screen inventory allows video-first platforms to capture brand advertising budgets migrating from linear television.
Industry Challenges
- Machine learning engineering talent scarcity:Bid optimization and predictive modeling functions compete with technology sector compensation, constraining platform R&D velocity.
- Legacy measurement system integration:Advertiser demand-side platforms require costly API redevelopment to ingest privacy-preserving attribution signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Social Advertising and Social Media Market |
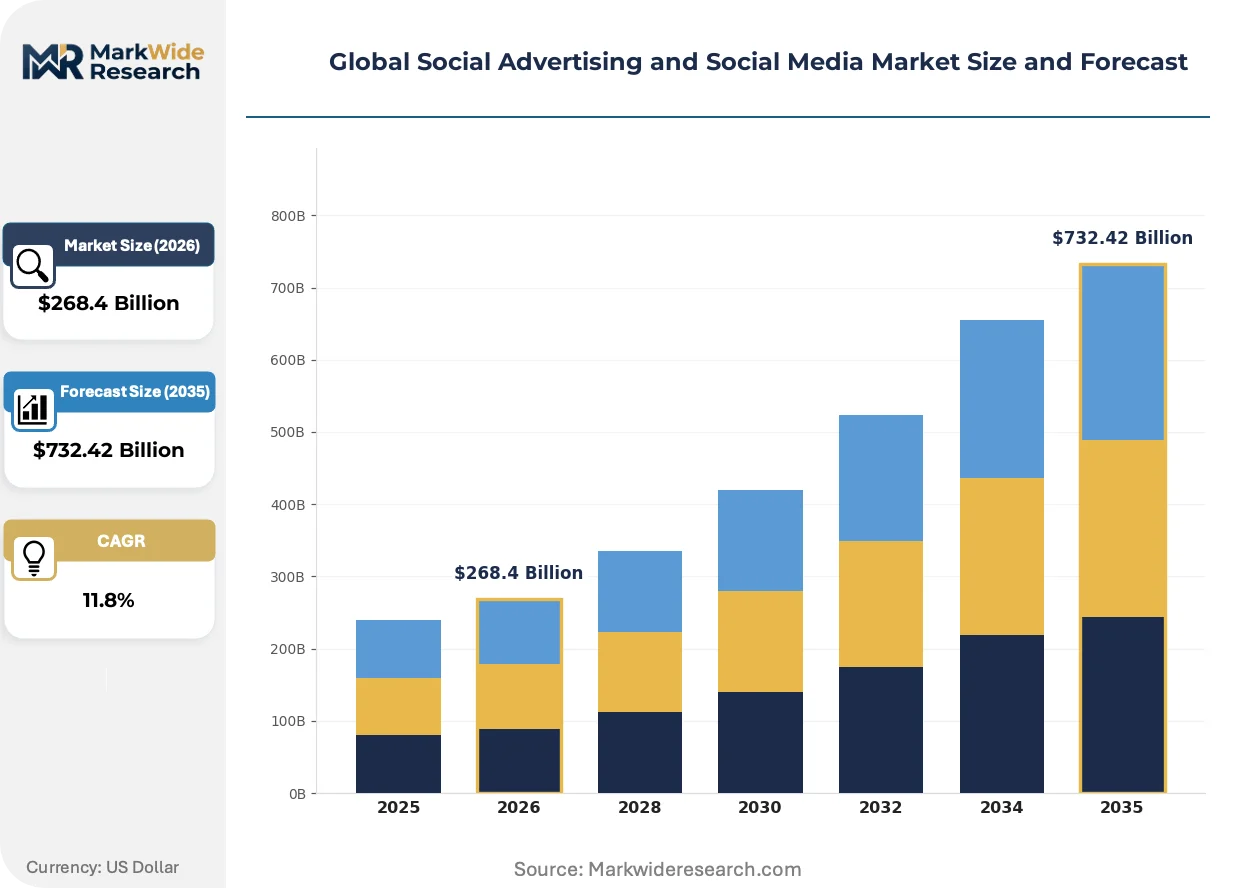
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $732.42 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Social Networks, Microblogging Sites, Media Sharing Sites, Discussion Forums, Community Blogs Advertising Format: Display Ads, Video Ads, Sponsored Posts, Native Ads, Carousel Ads Business Model: Cost Per Click, Cost Per Impression, Cost Per Action, Subscription, Freemium Target Audience: Small Businesses, Digital Agencies, Content Creators, Influencers, Nonprofit Organizations |
| Companies Covered | Meta Platforms, Google, TikTok, Amazon, Snapchat, Pinterest, LinkedIn, Twitter, Sprinklr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Social Advertising and Social Media Market Shifts & Advancements
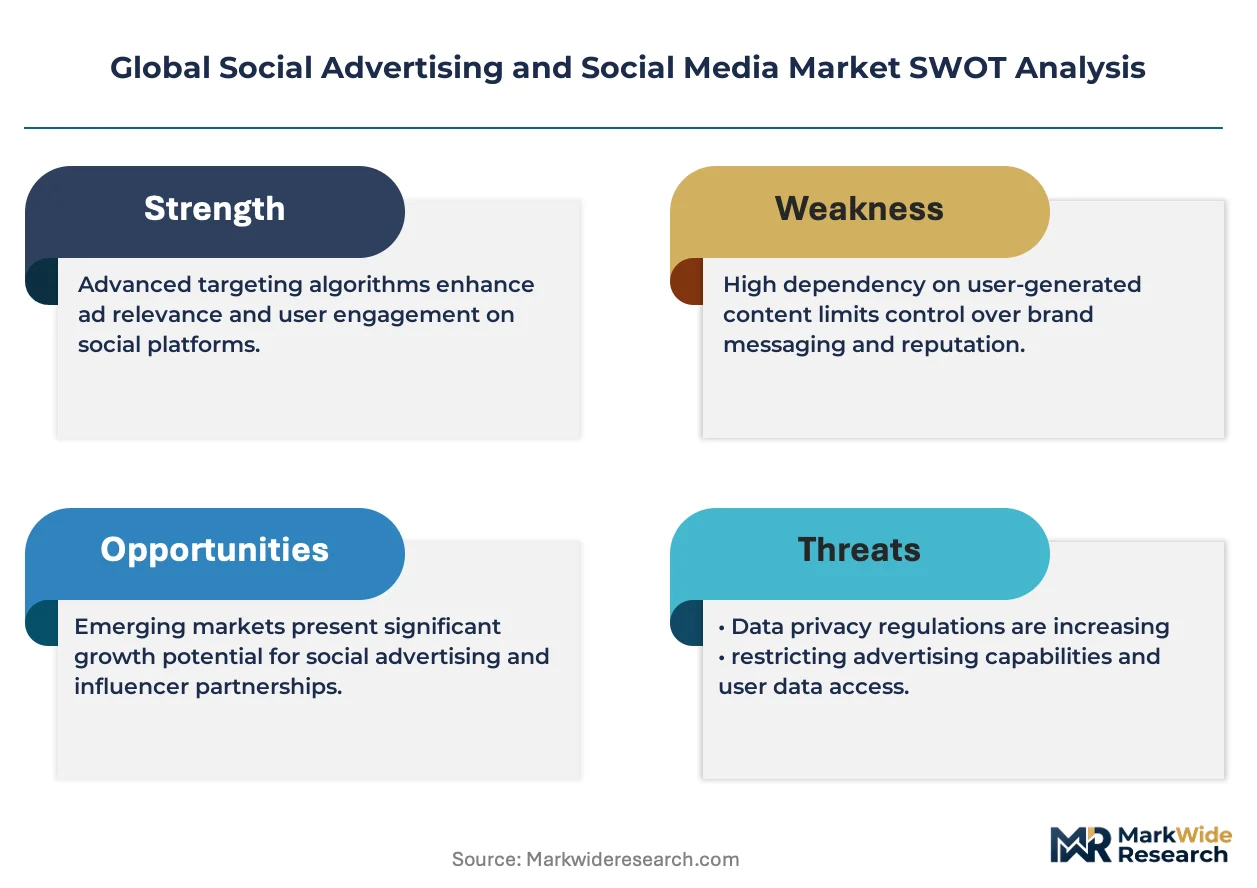
Privacy-preserving targeting infrastructure is displacing legacy cookie-dependent systems, forcing simultaneous investment in contextual intelligence, cohort-based modeling, and server-side data processing across the technical stack.
Server-side conversion tracking is decentralizing attribution architecture by shifting event collection from browser pixels to advertiser-controlled cloud endpoints. Enterprise advertisers with dedicated data engineering teams deploy these systems fastest, while mid-market buyers lag 18-24 months. This migration is decentralizing platform dependency as advertisers retain direct customer event streams.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for ad delivery systems processing European user data. Platforms must document training data provenance and decision logic for high-risk automated placements. Social advertising infrastructure in France, Germany, and the Netherlands faces the steepest compliance retrofit requirements.
Brand safety verification protocols are unbundling from bundled media buys as advertisers demand independent third-party measurement of content adjacency. Specialist verification vendors displace platform-native brand safety tools in agency RFP requirements. This shift concentrates most visibly in United States and United Kingdom markets where advertiser procurement functions have dedicated ad-tech sourcing expertise.
Global Social Advertising and Social Media Market Segmentation
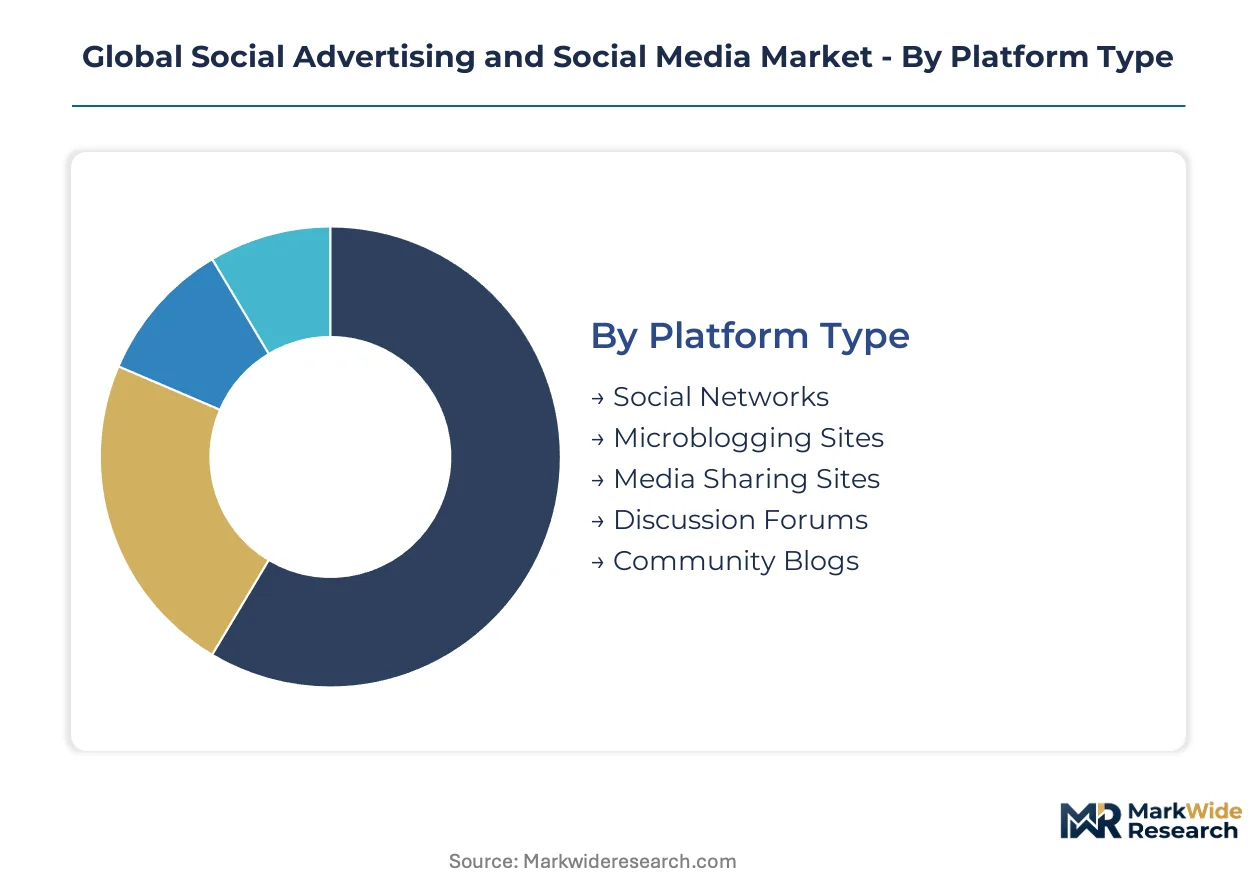
Segmentation in social advertising reveals how advertiser priorities diverge across platform infrastructure, creative formats, and performance accountability. Buyers select channels based on audience composition, measurement granularity, and native commerce integration rather than reach alone.
Platform Type:
Advertisers choose platforms based on content format compatibility and audience intent depth rather than monthly active user counts alone.
- Social Networks:Facebook and LinkedIn anchor enterprise B2B and B2C campaign orchestration through granular demographic layering and lookalike modeling. Demand concentrates among large advertisers in the United States seeking cross-platform frequency management and unified creative deployment across multiple properties.
- Media Sharing Sites:YouTube and TikTok monetize through vertical video inventory commanding premium CPMs based on completion-rate guarantees and sound-on engagement metrics. Demand concentrates in India and Brazil where mobile-first consumption patterns favor short-form video over text-based discovery.
- Microblogging Sites:Twitter/X and Threads serve real-time cultural moment marketing with keyword-triggered placement.
- Discussion Forums:Reddit and Quora capture niche community targeting through interest-based subreddit segmentation.
- Community Blogs:Medium and Substack enable long-form sponsored content with newsletter distribution integration.
Social Networks lead volumes today; Media Sharing Sites are gaining share fastest.
Advertising Format:
Creative format selection tracks mobile screen real estate economics and attention span compression across demographic cohorts.
- Video Ads:Vertical 9:16 aspect ratio placements dominate mobile feed consumption with autoplay sound-on defaults maximizing brand recall. Demand concentrates among CPG advertisers in Germany and France where GDPR-constrained targeting makes high-engagement formats essential for efficient reach.
- Sponsored Posts:Organic-style blended placements mimic user-generated content aesthetics to bypass banner blindness and drive native engagement. Demand concentrates among direct-to-consumer brands in the United Kingdom leveraging creator partnerships for social proof integration.
- Display Ads:Static and animated banner inventory persists in sidebar and story placements.
- Native Ads:Algorithmically promoted content matches surrounding feed aesthetics through dynamic creative optimization.
- Carousel Ads:Multi-image swipeable units enable sequential storytelling and product catalog browsing.
Video Ads lead volumes today; Sponsored Posts are expanding most quickly.
Business Model:
Pricing model adoption correlates with advertiser maturity and attribution infrastructure sophistication rather than campaign scale alone.
- Cost Per Click:Auction-based keyword and interest bidding remains the default for performance marketers optimizing toward landing page traffic. Demand concentrates among mid-market e-commerce advertisers in the United States with established conversion funnels and pixel-based attribution systems.
- Cost Per Action:Outcome-based pricing ties platform revenue to verified conversions, app installs, or lead form completions. Demand concentrates among mobile app developers in South Korea and Japan where lifetime value modeling justifies higher acquisition costs against strict return thresholds.
- Cost Per Impression:CPM-based brand awareness buying persists for reach-and-frequency campaigns.
- Subscription:Recurring platform fees for advanced analytics and audience insights tools.
- Freemium:Tiered feature access converting free users to paid campaign management tiers.
Cost Per Click leads volumes today; Cost Per Action is climbing the fastest.
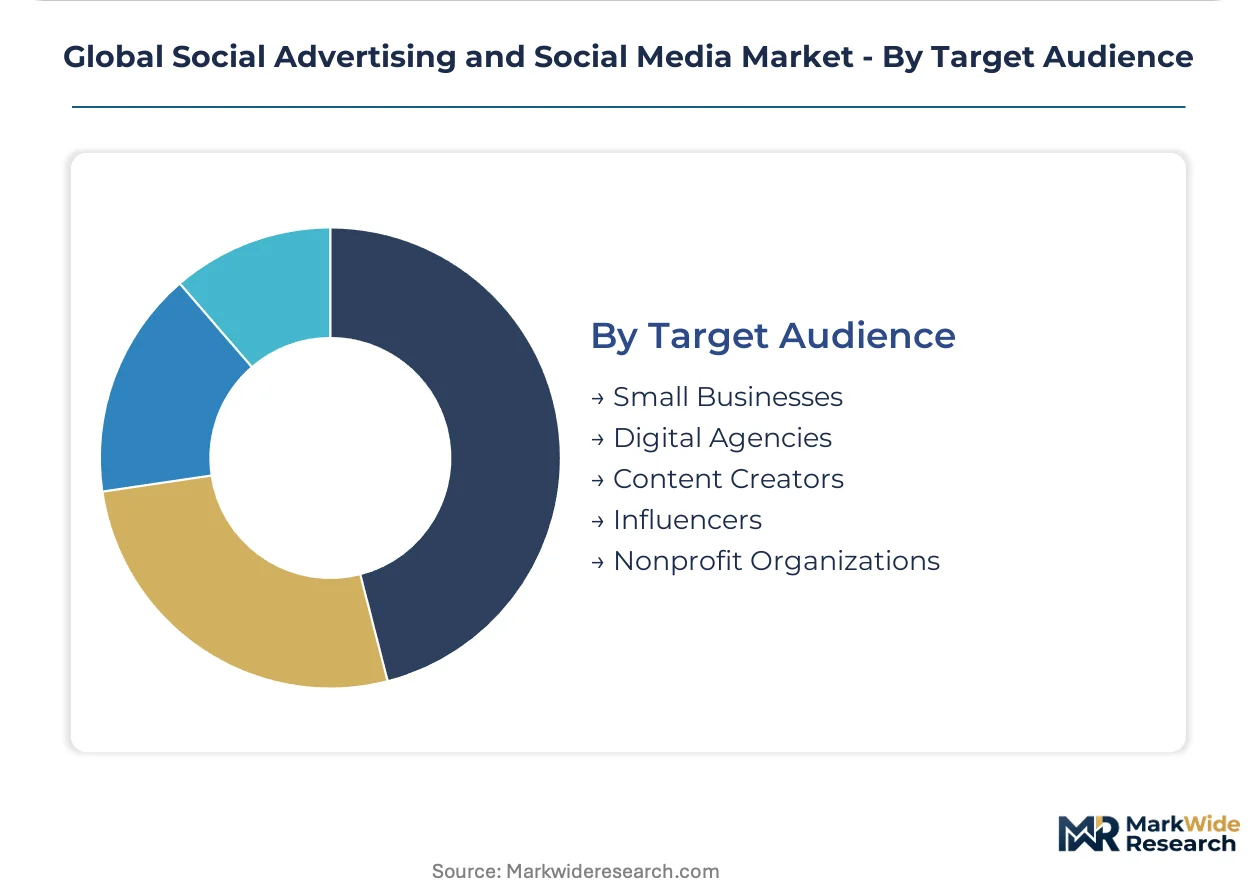
Target Audience:
Buyer type determines service model requirements from self-serve auction interfaces to managed agency partnerships.
- Digital Agencies:Multi-client campaign management demands API access, bulk creative tools, and consolidated billing across advertiser portfolios. Demand concentrates among holding company media buyers in the United Kingdom and Netherlands where cross-platform planning requires unified reporting dashboards.
- Small Businesses:Simplified self-serve interfaces with automated bidding and creative templates lower entry barriers. Demand concentrates among local service providers in India and Mexico where UPI and OXXO payment integration enables direct-response campaign activation without credit card infrastructure.
- Content Creators:Individual monetization through platform-native creator funds and branded content marketplaces.
- Influencers:Talent agencies and individual creators negotiating sponsored placement rates directly.
- Nonprofit Organizations:Discounted or donated inventory programs for cause marketing and donation solicitation.
Digital Agencies lead volumes today; Small Businesses are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Social advertising infrastructure originated in United States university networks before scaling through Silicon Valley platform development. Early commercial deployments concentrated in California and New York media corridors. Contemporary demand patterns now distribute across distinct national regulatory environments and mobile penetration rates.
United States
Enterprise advertisers in New York and Los Angeles drive premium CPM spending through cross-platform campaign orchestration. FCC political ad transparency mandates require disclosure repositories for sponsored electoral content. The San Francisco Bay Area hosts Meta Platforms and Google headquarters where algorithmic targeting infrastructure receives continuous R&D investment.
China
Domestic platforms capture mobile-native advertising spend through super-app ecosystems integrating messaging, payments, and commerce. SAMR antitrust enforcement and data security regulations constrain cross-border data flows for targeting systems. Beijing and Shenzhen clusters concentrate machine learning engineering talent for bid optimization development.
Germany
Automotive and industrial advertisers in Bavaria and Baden-Württemberg prioritize GDPR-compliant first-party data strategies. The KBA federal transport authority influences mobility-related advertising standards for connected vehicle platforms. Berlin hosts mid-market agency networks specializing in EU AI Act documentation for algorithmic accountability.
India
UPI payment integration enables direct-response monetization for small-business advertisers in Maharashtra and Karnataka. TRAI digital advertising guidelines address spam classification and consumer consent frameworks. Mumbai and Bangalore clusters concentrate creator economy infrastructure supporting influencer marketing campaign execution.
Brazil
CPG advertisers in São Paulo and Rio de Janeiro allocate budgets toward video-first platforms with high mobile engagement rates. ANVISA pharmaceutical advertising oversight restricts health-related sponsored content dissemination. The Southeast region anchors Latin American regional campaign management operations for multinational brands.
Global Social Advertising and Social Media Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data infrastructure depth and advertiser relationship tenure. The market structure concentrates around three hyperscale platforms with integrated ad tech stacks, supplemented by specialized vertical networks and independent software vendors. Dominant archetypes include full-stack ecosystem operators, short-form video specialists, and enterprise SaaS campaign management providers. Competitive dynamics center on first-party data asset accumulation and cross-platform identity resolution capabilities.
Within the full-stack ecosystem tier, Meta Platforms and Google exemplify integrated infrastructure spanning social, search, and messaging inventory. TikTok occupies a position as the short-form video specialist archetype, capturing youth demographic engagement through native mobile formats. These three entities anchor the competitive structure through differentiated content format dominance and advertiser self-serve platform sophistication.
| Leading Market Players |
|---|
| Meta Platforms |
| TikTok |
| Amazon |
| Snapchat |
| Sprinklr |
| Others |
Supply & Pricing Matrix
Machine learning engineering talent concentration in the San Francisco Bay Area and Bengaluru creates labor-cost differentials that widen pricing-tier spreads between premium managed-service offerings and self-serve auction platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates advertiser-facing revenue models, with differentiation driven by API access depth and dedicated account management coverage. Price differentiation separates enterprise advertisers with custom algorithmic bidding from mid-market buyers on automated optimization tiers. Cost compression in the self-serve tier is intensifying because hyperscale platforms subsidize onboarding to capture lifetime value. Small businesses in India and Mexico exhibit highest price sensitivity, while multinational CPG brands in Germany and France show lowest elasticity due to compliance-bundled service requirements.
Supply Chain Analysis
Domestic-content mandates in China and India are reshaping sourcing patterns for ad-serving infrastructure and data residency compliance. Compute capacity concentrates in the United States, Ireland, and Singapore, with raw dependencies on advanced GPUs, high-bandwidth memory modules, and specialized AI accelerators. Single-source vulnerability in Taiwan-based semiconductor fabrication threatens real-time bidding system resilience. Distribution runs through hyperscale cloud marketplaces and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global social advertising functions as a stable compounder, with regulatory-driven platform investment in privacy-preserving infrastructure ensuring sustained advertiser demand for compliant reach.
For Market Incumbents: Extend first-party data asset accumulation through retail media network partnerships and connected TV inventory expansion. Defend against TikTok's short-form video encroachment by accelerating Reels and Shorts monetization in India and Brazil. Prioritize EU AI Act documentation investment to maintain European Union market access against compliance-retrofit delays.
For New Entrants and Emerging Players: Mid-market direct-to-consumer brands in Southeast Asia represent an underserved buyer archetype with unmet demand for creator-commerce integration. Capture share through vertical-specific self-serve tools for Shopify-integrated merchants in Indonesia and Vietnam. Lead with transparent attribution modeling that addresses 7-day window compression pain points.
For Investors and Strategic Acquirers: Retail media technology vendors are the most active acquirer in this space, consolidating clean-room infrastructure and off-site social inventory orchestration capabilities. Five-to-ten-year viability hinges on cross-platform identity resolution scale. Monitor signal: regulatory fragmentation accelerating first-party data walled-garden formation.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Clean Room Deployment | Enables GDPR-compliant audience matching for CPG advertisers in Germany and France. |
| Short-Form Video Infrastructure Expansion | Captures mobile-native engagement in India and Brazil through vertical 9:16 formats. |
| Server-Side Conversion Tracking Migration | Preserves attribution accuracy amid Safari and Chrome privacy feature rollouts. |
| Retail Media Network Partnership | Combines Amazon and Walmart purchase signals with Meta and Google platform reach. |
| EU AI Act Compliance Certification | Unlocks algorithmic advertising deployment across French, German, and Dutch user bases. |
Research Methodology
Direct dialogue with platform monetization executives, agency media buyers, brand marketing directors, and ad-tech integration specialists grounded the qualitative foundation. Secondary validation drew from Meta and Google SEC filings, IAB Europe ad spend reports, TRAI digital advertising guidelines, and EU AI Act implementation documents. Bottom-up advertiser spend modeling and top-down platform revenue triangulation ensured cross-verification.
Market size outputs across the analysis window reflect segment-level modeling of platform type, advertising format, business model, and target audience dimensions. CAGRs emerged from historical trajectory analysis and regulatory impact scenario weighting. Forecast inputs incorporated UPI payment penetration rates in India, GDPR enforcement intensity indices, and short-form video consumption velocity metrics.
Underlying measurement precision varies by segment; United States and United Kingdom advertiser spend carries tighter precision than emerging market small-business estimates. Forecasts assume sustained mobile data cost declines and stable antitrust enforcement trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Digital Out of Home (OOH) Advertising Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Internet Advertising Market