
 Copyright Licensing Market | 2026-2036
Copyright Licensing Market Size, Share, and Industry Trends Forecast 2026-2036
Copyright Licensing Market Analysis
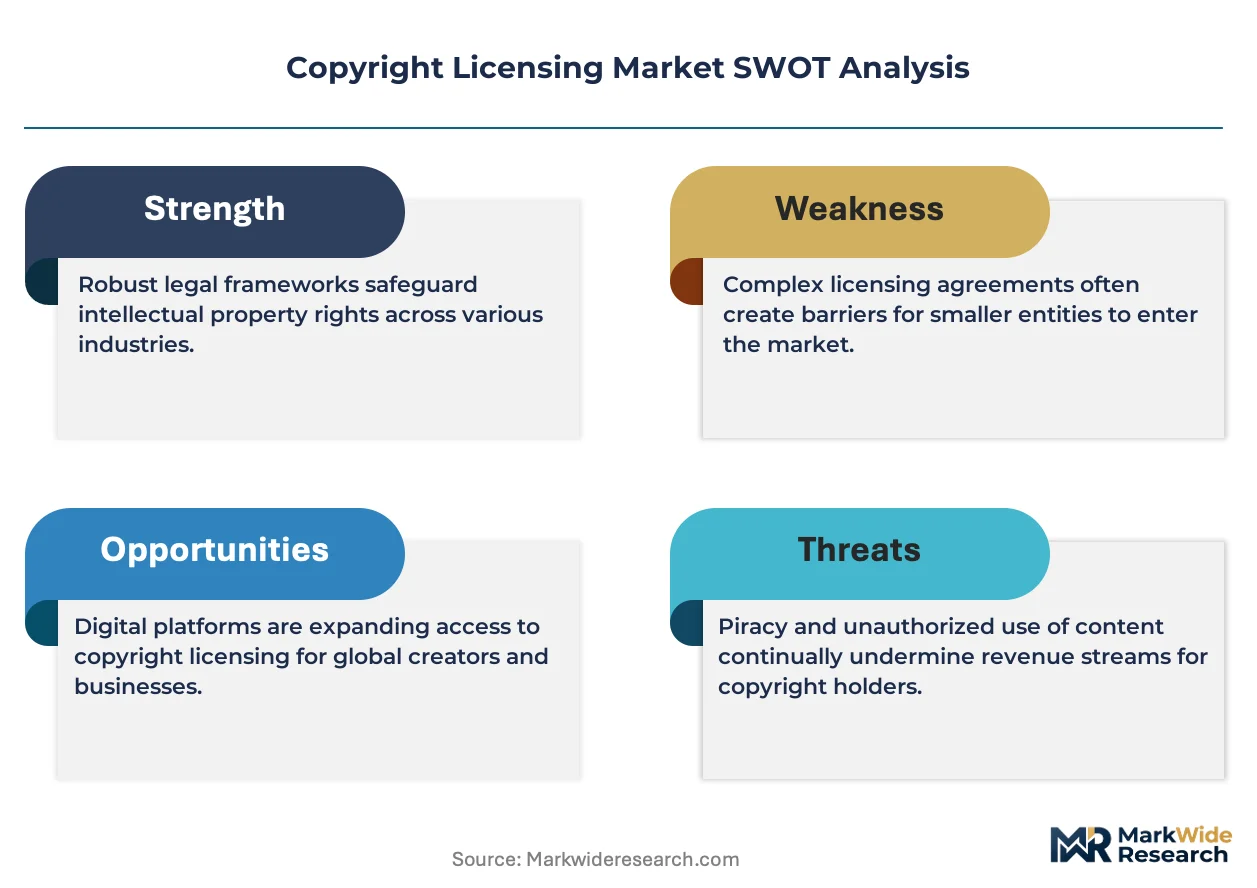
Revenue-based financing and royalty securitization are reshaping how independent creators and mid-tier rights holders participate in the Copyright Licensing Market. Getty Images leverages its archival depth to sustain premium pricing for editorial and commercial imagery. Shutterstock competes through subscription bundling that anchors recurring revenue from enterprises and individual creators. Disney Media & Entertainment Distribution dominates theatrical and streaming rights through captive production and extensive intellectual property control.
Copyright licensing encompasses the legal grant of usage rights for original creative works spanning literary, visual, musical, and software assets, typically governed by territorial scope, duration clauses, and royalty structures. Its primary commercial purpose is enabling lawful exploitation of protected content while generating returns for rights holders across distribution channels. The industry sector dimension shows film and music commanding the largest transaction volumes, with software licensing expanding fastest as enterprise SaaS adoption deepens. License type segmentation reveals subscription models capturing growing share from perpetual arrangements, while non-exclusive agreements concentrate margin pools through volume scalability across multiple licensees.
The U.S. Copyright Office and the EU's European Commission Directorate-General for Communications Networks, Content and Technology shape market access through registration frameworks, enforcement protocols, and cross-border licensing coordination. China's National Copyright Administration and MIIT impose content review and platform licensing obligations that affect international rights holders seeking distribution in that market. Stakeholders must monitor evolving collective bargaining frameworks and automated content recognition mandates that will determine bargaining power between platforms and rights aggregators.
Market Dynamics
Streaming platform consolidation is compressing bargaining timelines for rights holders while automated content recognition systems are shifting enforcement costs onto distribution intermediaries rather than originating creators.
Growth Catalysts
- EU Digital Services Act:Platform liability mandates for unlicensed material are expanding the addressable market for legitimate licensing intermediaries across member states.
- Enterprise SaaS deepening:Corporate software procurement is normalizing subscription-based copyright arrangements for code libraries and creative assets.
- Revenue-based financing:Royalty securitization mechanisms are unlocking liquidity for independent creators previously excluded from institutional capital markets.
Market Restraints
- Input cost volatility:Legal clearance and rights verification expenses scale non-linearly with catalog depth, squeezing mid-tier aggregator margins.
- Supply concentration risk:Major studio portfolio consolidation in the United States is reducing the universe of independent negotiation counterparties.
- Technical limitation:Cross-border royalty tracking infrastructure remains fragmented, creating reconciliation friction for multi-territory licenses.
Strategic Opportunities
- Underpenetrated geography:India's content production volume growth outpaces formal licensing infrastructure development, creating first-mover positioning for rights management platforms.
- Regulatory tailwind:China's National Copyright Administration platform licensing obligations are mandating compliance spending that favors established international rights holders.
- Technology convergence:Blockchain-based provenance tracking combined with machine learning content matching is reducing verification costs for high-volume asset categories.
Industry Challenges
- Specialized talent scarcity:Negotiation professionals fluent in both territorial copyright law and platform economics command premium compensation that strains independent operator budgets.
- Licensing complexity:Fragmented collective management organization mandates across jurisdictions create compliance overhead for multi-territory rights holders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copyright Licensing Market |
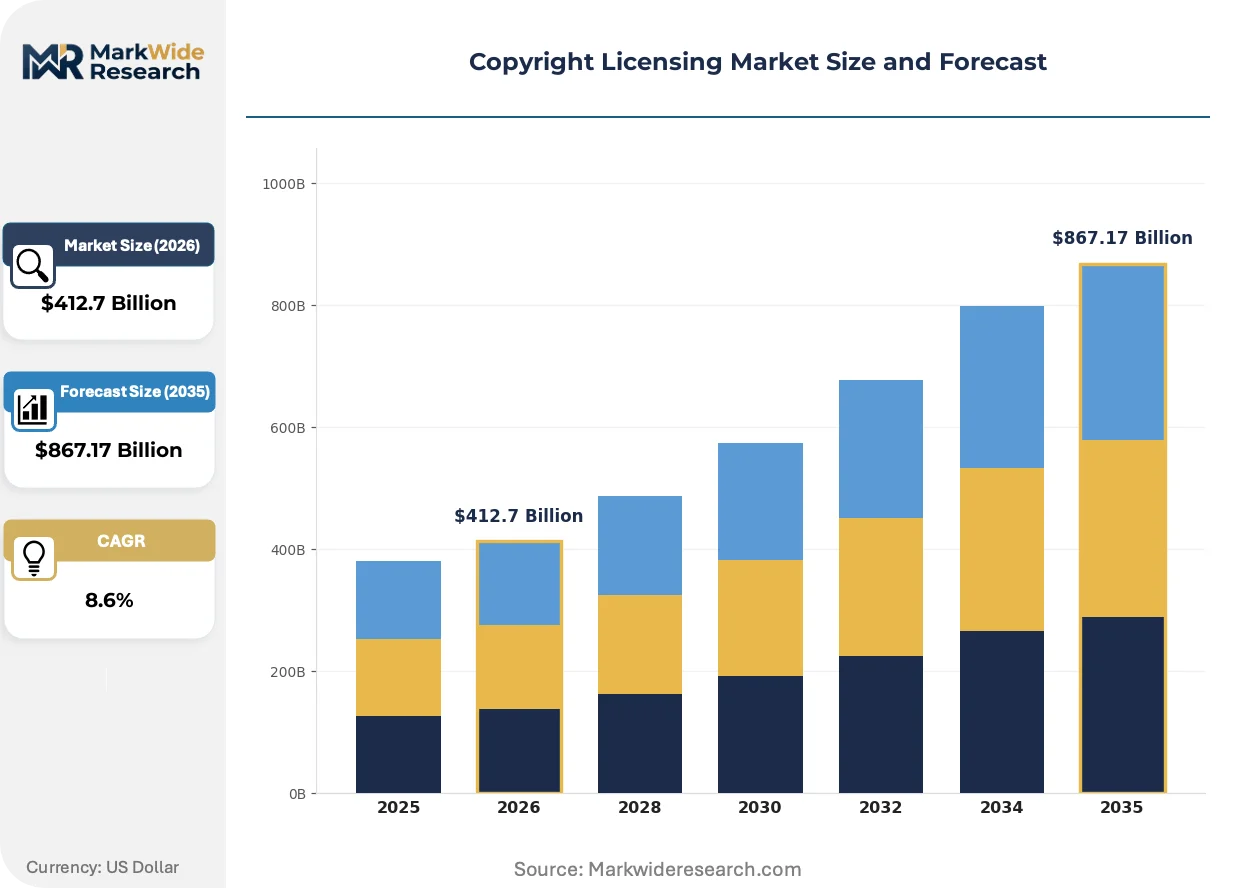
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $867.17 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | License Type: Exclusive, Non-exclusive, Assignments, Subscription Industry Sector: Publishing, Music, Film, Software License Duration: Perpetual, Fixed Term, Limited Term, Open-ended End User: Enterprises, Individuals, Educational Institutions, Nonprofits |
| Companies Covered | Shutterstock, Getty Images, Disney Media & Entertainment Distribution, Warner Bros. Entertainment, Motion Picture Licensing Company, Christian Copyright Licensing International, Pond5, NLA Media Access, Authors' Licensing and Collecting Society, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copyright Licensing Market Emerging Trajectories
Automated content recognition infrastructure is displacing manual rights clearance workflows while regulatory pressure on platform accountability is accelerating investment in licensed content verification systems.
Machine learning content identification systems are digitizing rights verification processes across video and audio asset categories. Major streaming platforms and social media distributors are deploying these tools at scale to preempt takedown disputes. This capability compression is reducing the cost structure for high-volume licensing operations while shifting competitive advantage toward data-rich incumbents.
The EU Digital Services Act and copyright directive updates are tightening intermediary liability for unlicensed material distribution. Platforms now face direct accountability for content appearing in feeds and recommendations. This regulatory pressure is most acute in Germany and France, where rights holder collectives are leveraging new enforcement channels to accelerate licensing negotiations.
Enterprise buyers are consolidating creative asset procurement through subscription bundles rather than transactional licensing. Marketing departments and content studios are replacing project-based image and music licensing with recurring platform relationships. This behavioral shift is most visible in the United States, where corporate procurement teams are negotiating enterprise-wide agreements that span photography, video, and software code libraries.
Copyright Licensing Market Segmentation
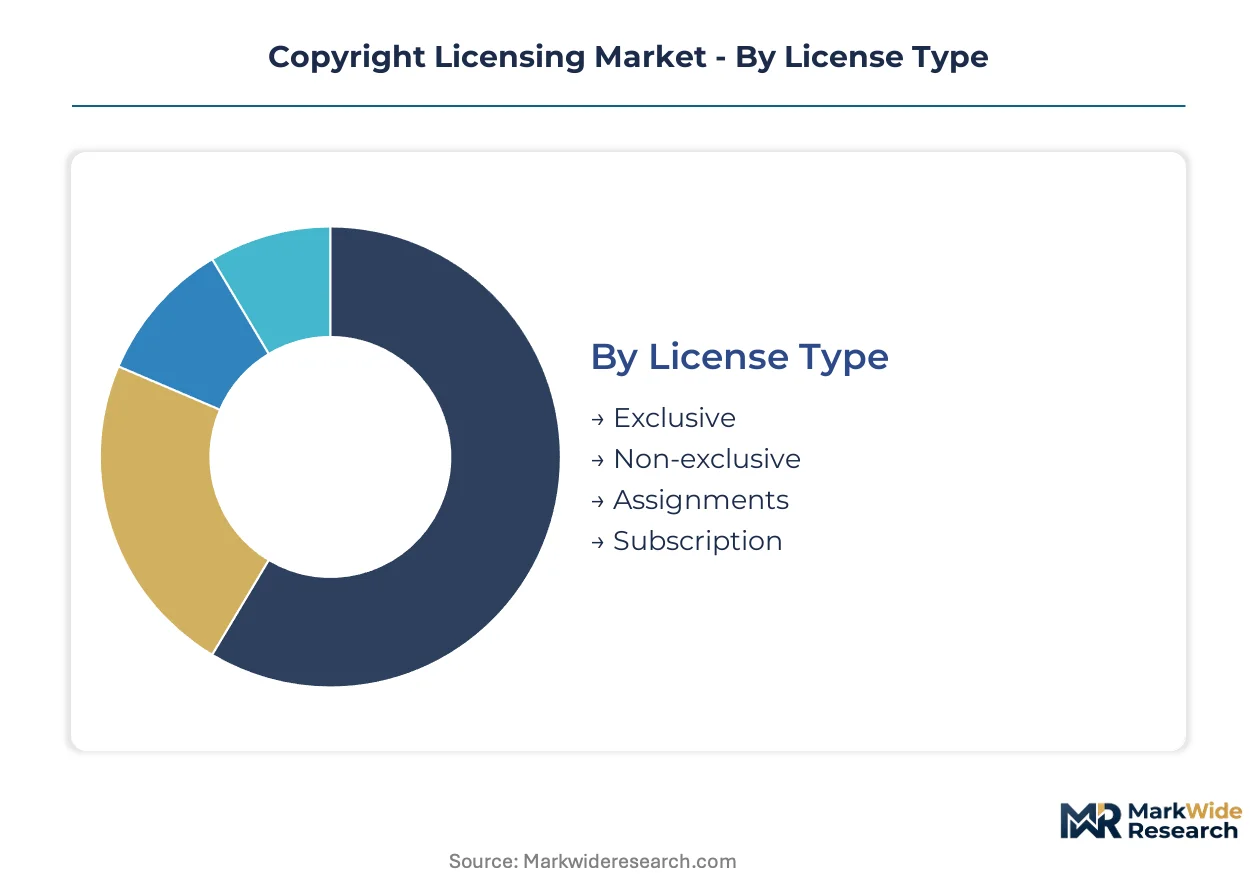
Segmentation in copyright licensing determines negotiation leverage, pricing architecture, and compliance burden across rights holders. License structure and duration clauses directly shape cash flow predictability and portfolio valuation methodologies.
License Type:
Exclusive agreements lock in the longest cycle times due to complex reversion clauses and territorial carve-outs, while subscription models turn over fastest through auto-renewal mechanics and usage-based repricing.
- Exclusive:Grants sole usage rights to a single licensee within defined territories and media channels. Major studios concentrate exclusive theatrical and streaming rights in the United States to maximize windowing revenue. High negotiation friction limits transaction velocity.
- Non-exclusive:Permits multiple simultaneous licensees without territorial restriction. Stock photography platforms and music libraries exploit this structure across enterprise marketing departments and individual creators. Volume scalability compresses per-unit margins.
- Assignments:Transfers full ownership of copyright from creator to acquirer. Music publishers and literary estates deploy assignments to consolidate catalog control.
- Subscription:Recurring access models replacing perpetual purchases across software and creative assets. Enterprise procurement teams favor predictable annual commitments.
Non-exclusive agreements anchor the volume base while subscription licensing gains share at the steepest rate.
Industry Sector:
Publishing licenses exhibit the most mature contract standardization, while software licensing undergoes the fastest structural transformation as SaaS delivery displaces perpetual code ownership.
- Publishing:Literary, academic, and journalistic content governed by territorial translation rights and print-digital bifurcation. Educational institutions drive recurring demand for textbook and research licensing.
- Music:Composition and recording rights fragmented across performance, mechanical, and synchronization channels. Streaming platforms in Germany and France negotiate blanket licenses with collective management organizations.
- Film:Theatrical, streaming, and broadcast windowing governed by exclusive territorial assignments. Major studio consolidation in the United States reduces independent negotiation counterparties.
- Software:Enterprise code libraries and end-user license agreements shifting decisively toward subscription delivery. Corporate procurement normalizes recurring payments for development tools.
Film and music command the largest transaction values while software licensing expands most quickly through enterprise SaaS deepening.
License Duration:
Perpetual arrangements tie up capital indefinitely and demand premium upfront pricing, whereas limited-term structures enable rapid repricing and portfolio rebalancing.
- Perpetual:Grants indefinite usage rights with no expiration clause. Enterprise software buyers historically favored this structure for critical infrastructure dependencies.
- Fixed Term:Defined expiration dates triggering renegotiation or renewal. Standard for film distribution windows and music synchronization deals.
- Limited Term:Short-duration access for specific campaigns or projects. Marketing agencies exploit this for seasonal advertising content.
- Open-ended:Continues until terminated by either party with notice provisions. Common in platform content partnerships with rolling performance reviews.
Fixed-term structures dominate transaction volume while open-ended arrangements climb the fastest among platform-native content deals.
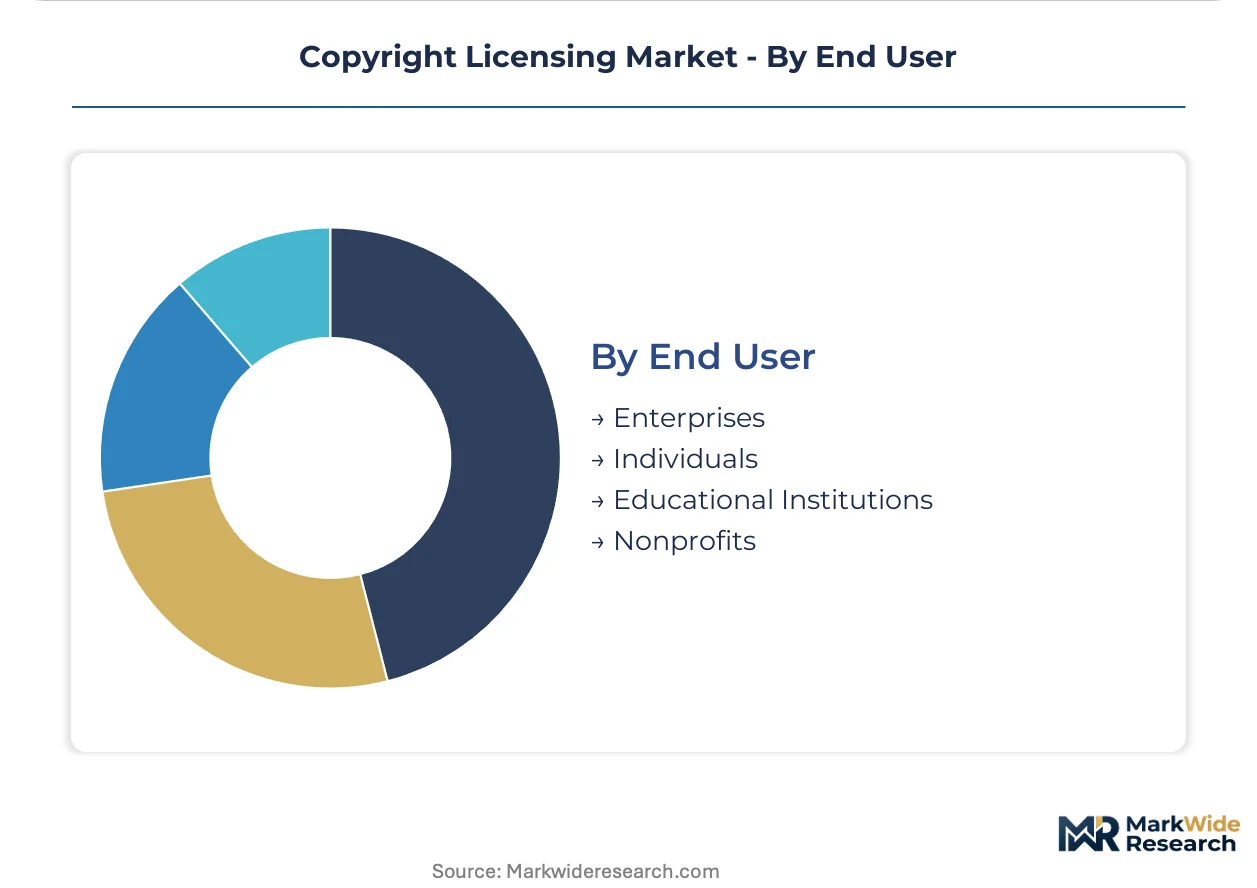
End User:
Enterprise procurement operates on annual budget cycles with centralized legal review, while individual licensing completes through automated checkout with minimal friction.
- Enterprises:Corporate legal and procurement teams negotiate multi-year agreements spanning photography, video, and software assets. Volume commitments secure tiered pricing.
- Individuals:Single-seat purchases through self-service platforms with immediate download access. Creators and small agencies populate this segment.
- Educational Institutions:Universities and K-12 systems demand curriculum-aligned content with institutional pricing. Library consortia aggregate bargaining power.
- Nonprofits:Charitable and advocacy organizations accessing discounted or donated licensing. Grant-funded operations constrain budget flexibility.
Enterprises generate the revenue concentration while educational institutions represent the most price-sensitive expansion segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports licensing frameworks and rights aggregation expertise while importing localized content adaptations for emerging markets. Major studios in Los Angeles and New York monetize intellectual property across territories, creating a structural trade surplus in licensing services. Net licensing revenue flows concentrate in rights-exporting economies with mature copyright enforcement infrastructure.
United States
Studio consolidation in Los Angeles and streaming platform headquarters in Seattle drive premium rights transactions. The U.S. Copyright Office registration frameworks provide enforceable title documentation for cross-border deals. New York City's financial district anchors royalty securitization and rights-backed financing instruments for independent creators.
Germany
Collective management organizations in Berlin and Munich administer blanket licenses for music performance rights across broadcast and digital channels. The German Copyright Administration enforces platform liability under EU directive implementations. Frankfurt's media cluster hosts rights verification technology providers serving European distributors.
China
Platform licensing obligations from the National Copyright Administration and MIIT compel compliance spending by streaming services in Beijing and Shenzhen. Content review requirements affect international rights holders seeking distribution access. Shanghai's Pudong district concentrates domestic rights aggregation platforms negotiating with foreign studios.
United Kingdom
London's Soho district anchors international film and television rights trading with specialized legal and financial services. The Intellectual Property Office maintains registration systems supporting cross-border enforcement. Manchester and Birmingham host emerging creative production clusters generating original content for licensing export.
India
Bollywood production volume in Mumbai outpaces formal licensing infrastructure development, creating infrastructure gaps for rights management platforms. The Indian Copyright Office registration backlog delays title verification for international deals. Hyderabad's Telugu film industry and Chennai's Tamil production centers generate regional language content requiring territorial licensing frameworks.
Copyright Licensing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. Rights aggregation concentrates among studios with captive production libraries and technology-enabled intermediaries with automated content recognition infrastructure. Three archetypes dominate: vertically integrated entertainment conglomerates, subscription-based stock asset platforms, and specialized collective management organizations. Competitive positioning hardens through portfolio consolidation and technology licensing for automated rights verification.
Within the stock photography and video segment, Shutterstock and Getty Images exemplify platform-scale intermediaries competing through subscription bundling versus premium archival depth. Disney Media & Entertainment Distribution occupies a position as a vertically integrated rights holder with captive production pipelines. These three entities represent divergent strategic postures: technology-enabled volume licensing, premium scarcity positioning, and in-house intellectual property monetization.
| Leading Market Players |
|---|
| Shutterstock |
| Getty Images |
| Disney Media & Entertainment Distribution |
| Warner Bros. Entertainment |
| Motion Picture Licensing Company |
| Christian Copyright Licensing International |
| Pond5 |
| NLA Media Access |
| Authors' Licensing and Collecting Society |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific data transmission corridors connecting Los Angeles content hubs to Asian streaming platforms carry escalating bandwidth costs that concentrate pricing power among rights aggregators with captive server infrastructure, while downstream price differentiation separates premium archival licensing from volume subscription tiers.
Pricing Analysis
Enterprise procurement teams anchor subscription-based pricing structures across creative asset portfolios. Price differentiation hinges on territorial exclusivity scope and automated content recognition integration depth. Pricing pressure intensifies as streaming platform consolidation compresses negotiation timelines for independent rights holders. Individual creators exhibit highest price sensitivity, while major studio licensors command premium positioning through portfolio scarcity.
Supply Chain Analysis
Tariff exposure between United States and Chinese content markets dominates supply chain risk calculations for international rights holders. Production concentration rests on Los Angeles theatrical distribution, London financial structuring, and Berlin collective management administration. Raw material dependencies span original content creation, archival digitization infrastructure, and machine learning training datasets. Distribution runs through platform-native APIs and enterprise procurement portals rather than traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where automated content recognition interoperability between streaming distributors and rights registries is reshaping competitive moats around data-rich incumbents.
For Market Incumbents: Harden automated content recognition infrastructure investments to preempt regulatory liability exposure under EU Digital Services Act enforcement. Consolidate archival depth through targeted catalog acquisitions from distressed independent estates. Vertical integration into royalty securitization platforms preserves margin capture from emerging revenue-based financing demand. For New Entrants and Emerging Players: Build out rights verification technology stacks serving India's formal licensing infrastructure gaps as Bollywood production volume accelerates. Target educational institution procurement cycles with curriculum-aligned subscription bundles. Position through API-first integration with existing learning management platforms rather than direct creator marketplace competition. For Investors and Strategic Acquirers: Technology-enabled collective management organizations with machine learning content matching capabilities represent the most defensible acquisition archetype. Long-term viability centers on regulatory enforcement durability across European platform liability mandates. Watch collective bargaining framework negotiations in Germany and France as inflection signals for intermediary margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Royalty Securitization Platform Launch | Unlocks institutional capital access for independent creators previously excluded from traditional financing channels. |
| Automated Content Recognition Infrastructure Buildout | Reduces rights verification costs for high-volume asset categories while shifting enforcement liability onto distributors. |
| Archival Digitization Partnership | Preserves premium pricing power for historical editorial and commercial imagery through exclusive access control. |
| Enterprise Subscription Bundle Expansion | Captures recurring revenue from corporate procurement teams consolidating creative asset procurement across photography, video, and software. |
| India Rights Management Platform Entry | Addresses infrastructure gaps as regional content production volume outpaces formal licensing development. |
Methodological Framework
Operator-level perspectives from rights licensing executives, streaming platform content acquisition leads, collective management organization administrators, and enterprise procurement officers anchored the qualitative base. Secondary validation drew from U.S. Copyright Office registration databases, EU directive implementation tracking, SEC filings of publicly traded content platforms, and trade data on cross-border intellectual property flows. Bottom-up transaction modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning license type exclusivity, industry sector concentration, and territorial enforcement maturity. CAGRs derived from historical licensing transaction velocity patterns and regulatory implementation timelines. Forecast inputs incorporated platform content budget disclosures and collective bargaining negotiation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated entertainment conglomerates or state-backed content platforms would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Philippines OOH and DOOH Market
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
Global Music Copyright Market