
 Native Video Advertising Market | 2026-2036
Native Video Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Native Video Advertising Market Outlook
The split between premium publisher inventory and commodity open-exchange supply is realigning how advertisers value placement quality. Taboola Inc. leverages its recommendation widget infrastructure to anchor premium publisher relationships across North America and Europe. Outbrain competes through direct integration with news websites, sustaining higher viewability standards than programmatic alternatives. Nativo Inc. specializes in in-article formats that match editorial design, differentiating on brand safety metrics rather than scale alone.
Native video advertising refers to video placements designed to match the form and function of surrounding editorial or user-generated content, typically delivered through automated insertion into content feeds without interrupting user experience. These units rely on real-time rendering engines that adapt aspect ratios, autoplay behavior, and sound settings to each host environment, serving the commercial purpose of reducing ad avoidance while maintaining engagement metrics comparable to organic content. In-feed ads and out-stream ads together capture the dominant share of platform investment, with streaming services emerging as the fastest-growing platform type due to subscription-fatigue-driven ad tier expansion. Brand storytelling commands premium pricing within content type segmentation, whereas user-generated content sponsorships trade at lower CPMs but deliver higher completion rates among Gen Z audiences.
The FTC in the United States enforces disclosure standards that mandate clear labeling of sponsored native content, directly shaping creative production workflows and platform compliance investments. The EU's GDPR and Digital Services Act impose additional consent and transparency requirements that limit behavioral targeting precision, forcing advertisers to rely more heavily on contextual and first-party data signals. Stakeholders must weigh the trade-off between scale efficiency through open programmatic pipes and the brand safety guarantees of direct publisher integrations as regulatory friction intensifies.
Market Dynamics
Platform operators now face intensifying regulatory pressure around disclosure transparency, forcing a fundamental reallocation of compliance investment away from scale optimization toward legal infrastructure and creative workflow redesign.
Growth Catalysts
- FTC Enforcement Escalation:The FTC's expanded disclosure mandates for sponsored content in the United States create competitive moats for compliant platforms while squeezing non-compliant inventory out of circulation.
- Mobile App In-Feed Investment:Retail brands redirect television budgets toward in-feed placements within high-engagement mobile environments, prioritizing completion rates over reach metrics.
- Streaming Ad Tier Expansion:Subscription fatigue across major streaming services drives rapid deployment of advertising-supported tiers, opening premium video inventory previously locked behind paywalls.
Market Restraints
- GDPR Consent Friction:The EU's GDPR and Digital Services Act impose granular consent requirements that degrade behavioral targeting precision and inflate effective CPMs for European campaigns.
- Publisher Concentration Risk:Premium inventory concentrates among a narrowing set of large platform operators, limiting buyer negotiating leverage and compressing margin for mid-tier intermediaries.
- Creative Production Bottleneck:Native format adaptation requires platform-specific rendering engines and aspect ratio variations, multiplying production costs versus standardized pre-roll units.
Strategic Opportunities
- Brazil Social Commerce Integration:Underpenetrated direct-response capabilities within Brazil's social media ecosystems offer first-mover advantage for performance advertisers building localized attribution infrastructure.
- Contextual Targeting Renaissance:First-party data deprecation is expanding into semantic content analysis and publisher-provided contextual signals, reducing reliance on cookie-based audience modeling.
- CTV-Programmatic Convergence:Connected television inventory is adopting programmatic native formats, enabling dynamic creative optimization previously restricted to digital display environments.
Industry Challenges
- Cross-Platform Measurement Fragmentation:Viewability and engagement metrics vary materially across TikTok, Instagram Reels, and YouTube Shorts, complicating unified campaign optimization.
- Brand Safety Verification Lag:Real-time content adjacency scoring for user-generated video remains technically immature, exposing advertisers to placement risk in high-velocity feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Native Video Advertising Market |
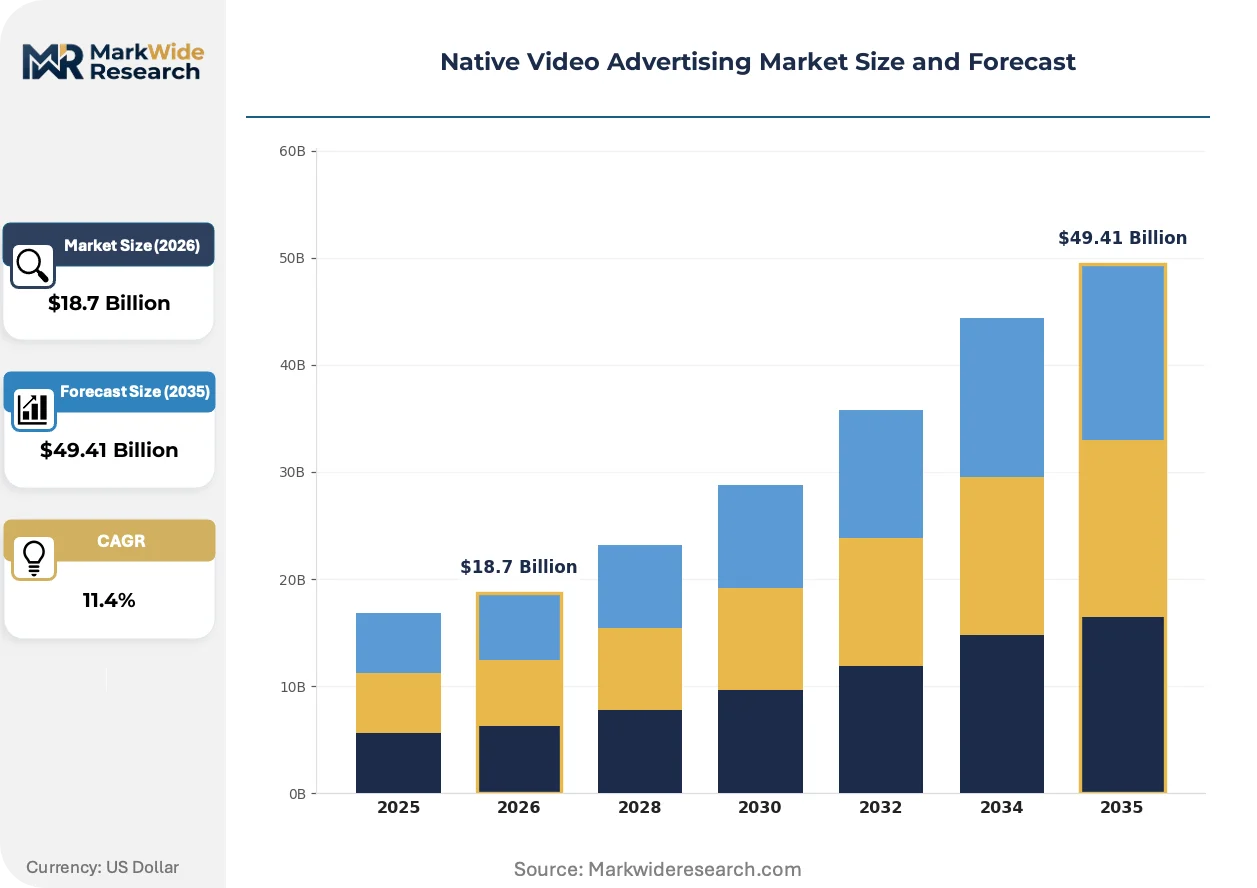
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Social Media, Streaming Services, Mobile Apps, News Websites Content Type: Brand Storytelling, Product Demonstration, User-Generated Content, Sponsored Content Ad Format: In-Feed Ads, Out-Stream Ads, In-Article Ads, Recommendation Widgets Target Audience: Millennials, Gen Z, Homeowners, Fitness Enthusiasts |
| Companies Covered | Taboola Inc., Outbrain, Nativo Inc., Sharethrough Inc., TripleLift Inc., MGID, Innovid, PubMatic, Inc., ExoClick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Native Video Advertising Market Strategic Shifts
Real-time rendering engines now dominate creative adaptation, collapsing the traditional gap between production and distribution while forcing infrastructure investment toward edge computing and dynamic asset assembly.
Server-side ad insertion technology is expanding into streaming environments, enabling frame-accurate placement within live and on-demand content without client-side latency. Disney and Netflix deploy these engines across their ad-supported tiers, compressing the technical distinction between broadcast and digital video delivery. The technology is expanding into addressable creative versioning, allowing thousand-variant campaigns from single master assets.
The EU's Digital Services Act disclosure requirements reshape platform architecture across member states, mandating algorithmic transparency and ad repository access that exposes competitive spending patterns. Publishers operating across European markets must rebuild recommendation engines to satisfy audit trails, diverting engineering resources from engagement optimization. French and German regulators lead enforcement, creating a compliance template that smaller member states adopt verbatim.
Buyer concentration among direct-to-consumer brands is rotating demand toward performance-native hybrids that prioritize attributable conversions over brand lift metrics. These advertisers displace traditional brand storytelling budgets with product-centric creative optimized for swipe-up behavior. India and Southeast Asia exhibit the most pronounced shift, where mobile-first commerce integration outpaces legacy awareness campaigns.
Native Video Advertising Market Segmentation
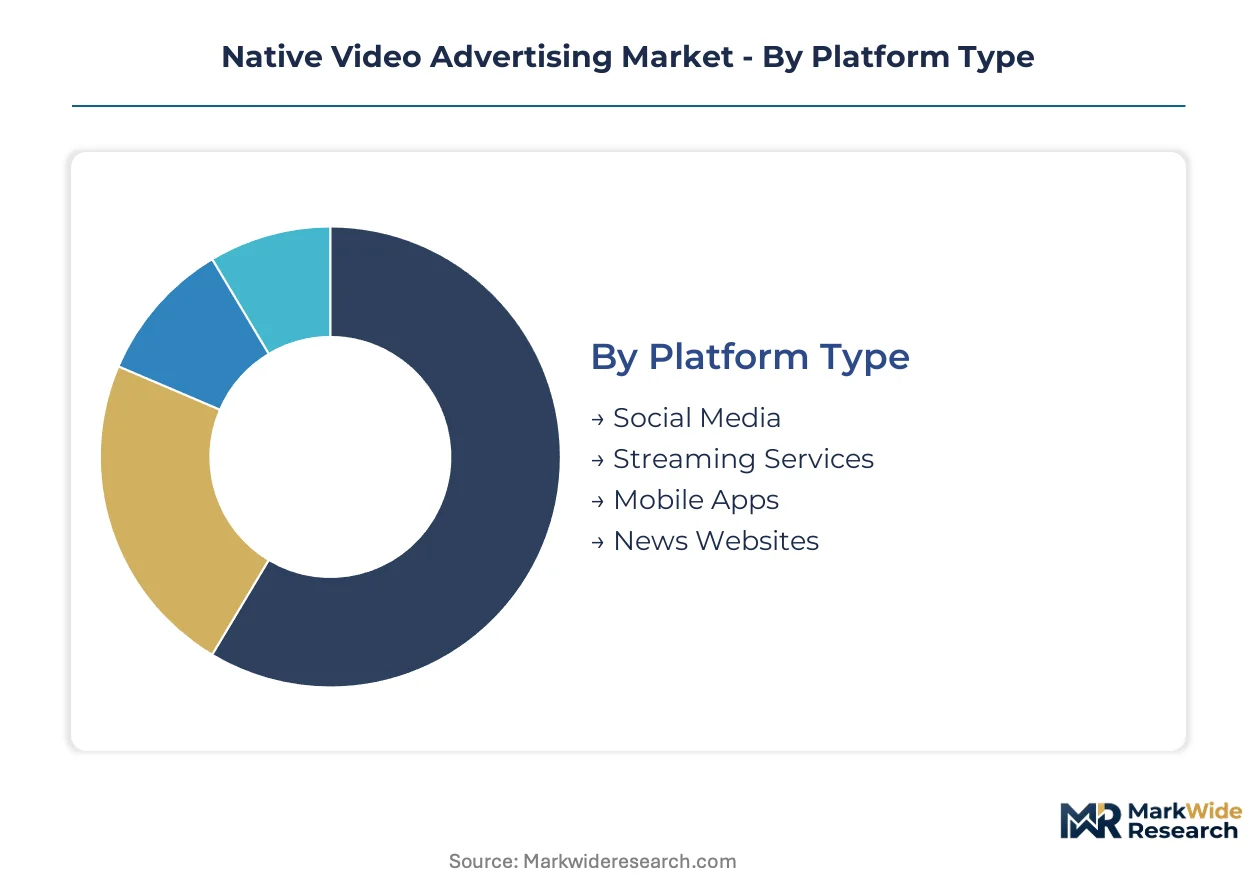
Platform operators and advertisers allocate budgets across divergent inventory types based on completion rates, viewability standards, and regulatory exposure. Segmentation reveals where premium pricing commands justify compliance investment versus where scale efficiency dominates buying decisions.
Platform Type:
Upgrade cycles in video infrastructure and shifting subscription economics reshape where advertisers concentrate platform spend.
- Social Media:In-feed placements on TikTok, Instagram Reels, and YouTube Shorts deploy real-time rendering engines that adapt aspect ratios and autoplay behavior to each host environment. Demand concentrates in India and Brazil where mobile-first commerce integration outpaces legacy awareness campaigns, though FTC disclosure mandates in the United States elevate compliance costs for sponsored content workflows.
- Streaming Services:Server-side ad insertion enables frame-accurate placement within live and on-demand content without client-side latency, with Disney and Netflix deploying these engines across ad-supported tiers opened by subscription fatigue. The fastest expansion belongs to this segment as premium inventory previously locked behind paywalls becomes programmatically accessible.
- Mobile Apps:Retail brands redirect television budgets toward high-engagement mobile environments, prioritizing completion metrics over reach.
- News Websites:Direct publisher integrations sustain higher viewability standards than programmatic alternatives, though inventory concentrates among narrowing operator sets.
Volume placements concentrate in Social Media; the steepest expansion trajectory belongs to Streaming Services.
Content Type:
Creative production workflows diverge sharply based on whether campaigns prioritize attributable conversions or brand lift measurement.
- Brand Storytelling:Long-form narrative content commands premium pricing within publisher direct deals, requiring substantial production investment and editorial alignment. Demand clusters among established consumer brands in North American and European markets where GDPR consent friction has shifted investment toward contextual placement strategies.
- User-Generated Content:Sponsorships of creator-produced video trade at lower CPMs but deliver higher completion rates among Gen Z audiences, particularly in Southeast Asia where mobile-first commerce integration accelerates. The fastest-growing trajectory belongs to this segment as direct-to-consumer brands displace traditional storytelling budgets with product-centric creative optimized for swipe-up behavior.
- Product Demonstration:Performance-native hybrids prioritize attributable conversions through feature-focused video formats.
- Sponsored Content:FTC-mandated disclosure labels reshape creative production workflows and platform compliance investments.
Revenue concentration favors Brand Storytelling for premium publishers; volume expansion is climbing the fastest in User-Generated Content.
Ad Format:
Technical adaptation requirements multiply production costs versus standardized pre-roll units, fragmenting buyer strategies across format types.
- In-Feed Ads:Units inserted directly into content feeds without interrupting user experience rely on edge computing infrastructure for dynamic asset assembly. Retail brands in the United States allocate larger budgets to these placements as television budgets migrate toward mobile app environments.
- Out-Stream Ads:Autoplay video units deployed outside traditional video content maximize viewability through publisher-controlled placement. Expansion is gaining share fastest in Brazil and India where social commerce integration remains underpenetrated.
- In-Article Ads:Formats matching editorial design differentiate on brand safety metrics rather than scale alone.
- Recommendation Widgets:Taboola and Outbrain leverage widget infrastructure to anchor premium publisher relationships across North America and Europe.
Investment flows concentrate in In-Feed placements; Out-Stream formats are expanding most quickly in emerging social commerce markets.
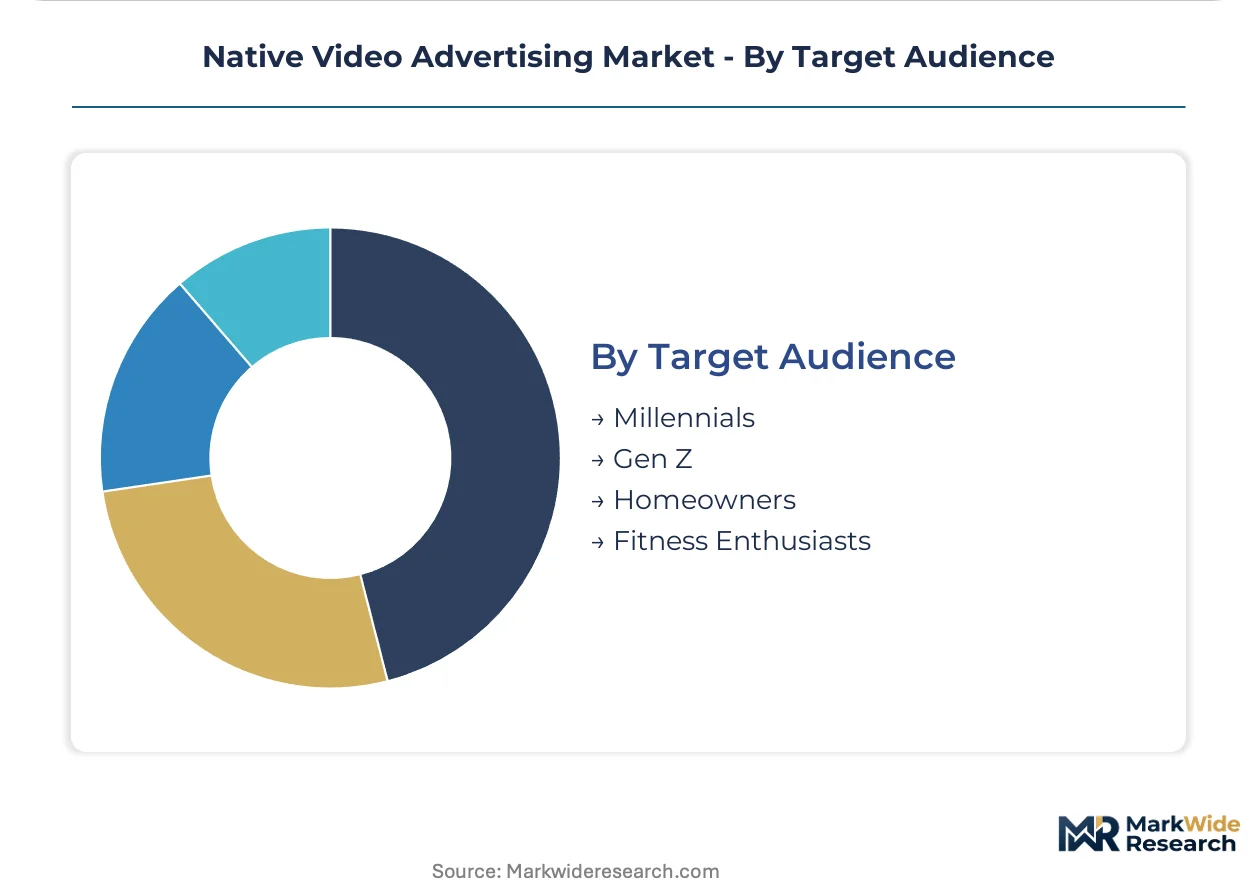
Target Audience:
Demographic-specific creative versioning drives addressable campaign complexity and data infrastructure requirements.
- Gen Z:Short-form native video consumption on TikTok and Instagram Reels demands platform-specific rendering engines with sound-off optimization. Completion rate premiums in this segment justify higher production costs for swipe-up-optimized creative in India and Southeast Asia.
- Millennials:Cross-platform viewing behaviors spanning streaming services and social feeds require unified measurement frameworks that remain technically fragmented.
- Homeowners:Localized service advertising concentrates in Nextdoor and hyperlocal news environments with limited programmatic scale.
- Fitness Enthusiasts:Wearable-integrated video campaigns on Strava and Peloton ecosystems exploit first-party data signals as cookie deprecation accelerates.
Platform investment concentrates in Gen Z targeting; Fitness Enthusiasts represent the fastest-growing niche for first-party data exploitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the highest concentration of native video advertising technology development, hosting engineering clusters that build real-time rendering engines for in-feed placements. Platform operators and retail brands coordinate campaign deployment across four distinct national markets with divergent regulatory exposure and mobile commerce maturity.
United States
Retail brands redirect television budgets toward in-feed placements within high-engagement mobile environments, prioritizing completion rates over reach metrics. The FTC enforces expanded disclosure mandates for sponsored content, creating compliance moats that squeeze non-compliant inventory from circulation. Los Angeles and New York media clusters concentrate creative production infrastructure for platform-specific rendering workflows.
Brazil
Social commerce integration accelerates demand for out-stream video formats within underpenetrated direct-response ecosystems. ANVISA and consumer protection agencies enforce advertising transparency standards that reshape platform disclosure architectures. São Paulo anchors performance advertiser activity building localized attribution infrastructure for swipe-up-optimized campaigns.
India
Mobile-first commerce integration outpaces legacy awareness campaigns across TikTok-competing short-form platforms. TRAI guidelines on digital advertising transparency impose labeling requirements that elevate compliance investment for foreign platform operators. Bengaluru and Mumbai clusters concentrate engineering talent for contextual targeting systems reducing cookie dependency.
Germany
GDPR consent friction degrades behavioral targeting precision, inflating effective CPMs and shifting investment toward contextual placement strategies. The Digital Services Act mandates algorithmic transparency and ad repository access that exposes competitive spending patterns. Berlin and Hamburg host publisher engineering teams rebuilding recommendation engines to satisfy audit trail requirements.
United Kingdom
Streaming service ad tier expansion opens premium inventory previously locked behind subscription paywalls, attracting television budget migration. The Information Commissioner's Office enforces GDPR-aligned consent frameworks that limit granular audience modeling. London's Soho district concentrates server-side ad insertion engineering for frame-accurate placement within live content.
Native Video Advertising Market Competitive Environment
Premium-margin players sit above commodity-margin players across disclosure compliance and publisher direct relationship depth, with the market consolidating around three functional tiers. Widget infrastructure specialists anchor premium publisher relationships through recommendation engine integration, while programmatic intermediaries compete on scale efficiency with thinner brand safety guarantees. Two strategic archetypes dominate: direct publisher integrators sustaining higher viewability standards, and open-exchange operators maximizing reach through automated pipes. Competitive moves concentrate on M&A to capture first-party data assets and geographic expansion into underpenetrated social commerce markets.
Within the widget infrastructure tier, Taboola Inc. and Outbrain occupy positions as premium publisher relationship anchors across North America and Europe. Nativo Inc. exemplifies the in-article format specialization archetype, differentiating on brand safety metrics rather than scale alone. These three entities represent distinct competitive vectors—recommendation engine dominance, direct news website integration, and editorial design matching—that structure how advertisers allocate between quality-assured and efficiency-optimized inventory procurement.
| Leading Market Players |
|---|
| Taboola Inc. |
| Outbrain |
| Nativo Inc. |
| Sharethrough Inc. |
| TripleLift Inc. |
| MGID |
| Innovid |
| PubMatic, Inc. |
| ExoClick |
| Others |
Value Chain & Pricing Dynamics
Creative production costs for platform-specific rendering engines cascade through three distinct pricing tiers, with premium publisher direct deals commanding substantial premiums over programmatic open-exchange inventory. Retail brands absorbing these upstream cost pressures redirect television budgets toward completion-rate-optimized mobile placements, compressing margins for mid-tier intermediaries unable to anchor direct publisher relationships.
Pricing Analysis
Completion rate premiums anchor value-based pricing for in-feed placements on TikTok and Instagram Reels, with brand storytelling campaigns commanding substantial CPM premiums over user-generated content sponsorships. Price differentiation separates premium publisher direct deals from commodity open-exchange supply based on viewability certification and brand safety scoring. Cost compression in programmatic tiers intensifies as GDPR consent friction degrades behavioral targeting precision and inflates effective CPMs for European campaigns. Direct-to-consumer brands exhibit highest price sensitivity, prioritizing attributable conversions over brand lift metrics, while established consumer brands in North America absorb premium pricing for editorial-aligned placements.
Supply Chain Analysis
Logistics costs for real-time rendering infrastructure concentrate engineering talent clusters in San Francisco, Bengaluru, and Berlin, with edge computing deployment determining latency performance for dynamic asset assembly. Raw material dependencies span server-side ad insertion technology, semantic content analysis engines, and first-party data management platforms. Supply chain risk centers on single-source vulnerability for premium publisher inventory concentrated among narrowing operator sets. Distribution runs through direct publisher integrations for quality-assured buyers and open programmatic pipes for scale-focused advertisers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Native Video Advertising Market functions as a cost-of-compliance story where FTC disclosure mandates create barrier-to-entry moats for platforms with pre-built legal infrastructure, squeezing non-compliant inventory from circulation and consolidating margin among prepared incumbents.
For Market Incumbents: Cement premium publisher relationships through exclusive recommendation engine integrations before GDPR and Digital Services Act enforcement hardens compliance requirements across European markets. Invest in server-side ad insertion capabilities for streaming ad tier expansion as subscription fatigue opens premium inventory. Vertical integration into first-party data assets defends against cookie deprecation threatening behavioral targeting precision. For New Entrants and Emerging Players: Enter via Brazil's underpenetrated social commerce ecosystems where localized attribution infrastructure remains scarce and ANVISA transparency standards have not yet hardened platform architectures. Target India's mobile-first commerce integration gap on TikTok-competing short-form platforms where TRAI guidelines elevate compliance costs for foreign operators. Build contextual targeting capabilities as cookie-based audience modeling faces systematic deprecation. For Investors and Strategic Acquirers: FTC enforcement escalation against non-compliant sponsored content is the leading indicator that regulatory friction will consolidate market share toward prepared platforms with pre-built disclosure workflows. First-party data assets and direct publisher integration depth represent priority acquisition archetypes over scale-focused programmatic intermediaries. Watch for streaming service ad tier expansion announcements as signals of premium inventory programmatic accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Publisher Direct Integration | Secures premium inventory access ahead of GDPR consent friction degrading open-exchange viability. |
| Server-Side Ad Insertion Deployment | Enables frame-accurate placement within Disney and Netflix ad-supported tiers opened by subscription fatigue. |
| Contextual Targeting Capability Buildout | Reduces cookie dependency as TRAI and Digital Services Act limitations constrain behavioral precision. |
| Brazil Social Commerce Infrastructure | Captures first-mover advantage in underpenetrated direct-response ecosystems before ANVISA standards harden. |
| First-Party Data Asset Acquisition | Defends targeting capabilities against systematic deprecation of third-party cookie audience modeling. |
Study Parameters
Document review covered SEC filings from ad technology platforms, FTC enforcement action records, and EU Digital Services Act implementation guidance, complemented by interviews with platform engineering directors, brand media buyers at retail advertisers, publisher monetization leads, and regulatory compliance officers. Secondary validation drew from TRAI consultation papers, ANVISA advertising transparency standards, and streaming service ad tier expansion announcements. Bottom-up segmentation modeling triangulated against top-down market sizing from disclosed platform revenue and programmatic spend estimates.
Historical spend trajectories cross-referenced against panel input from media buying agencies and ad tech vendors shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform type, content format, ad delivery mechanism, target audience demographic, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed platform revenue and programmatic volume estimates, with streaming ad tier expansion and social commerce penetration serving as primary demand drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FTC enforcement or GDPR consent friction scenarios beyond current regulatory timelines. Forecasts reflect assumptions regarding platform compliance investment rates, streaming subscription fatigue velocity, and mobile commerce integration maturity. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
North America Advertising Market