
 Qatar OOH and DOOH Market | 2026-2036
Qatar OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar OOH and DOOH Market Insights
Modular screen bundling is rebalancing procurement patterns across Qatar's outdoor advertising sector. JCDecaux leverages its airport and transit concessions to anchor premium inventory in Doha's highest-traffic zones. Elan Media competes through specialized mall and retail network coverage. Daktronics Inc. differentiates via LED manufacturing scale and technical support capabilities for large-format stadium and highway deployments.
Out-of-home (OOH) and digital out-of-home (DOOH) advertising encompasses physical and electronic display systems deployed in public spaces to deliver commercial messaging to mobile audiences. LED technology dominates large-format installations with brightness ratings exceeding 5,000 nits for direct-sun visibility in Qatar's desert climate. Digital Screens within the Advertising Medium dimension command the fastest expansion as programmatic buying platforms connect inventory to real-time audience data. LED within Technology Type leads capital deployment due to energy efficiency gains and modular panel architectures that reduce field replacement costs.
MOCI advertising content standards and Qatar's municipal signage permitting frameworks govern screen placement, brightness limits, and operating hours across Doha, Lusail, and Al Wakrah. The Qatar General Electricity and Water Corporation (KAHRAMAA) efficiency codes and Ministry of Municipality and Environment urban planning directives shape power supply requirements and installation locations for new digital assets. Stakeholders must monitor evolving procurement rules for government-linked entities and assess how FIFA-legacy venue conversions into permanent commercial districts will redistribute premium inventory value across the emirate.
Market Dynamics
Programmatic trading platforms are restructuring inventory access across Qatar's outdoor advertising sector. Real-time audience data integration allows advertisers to bid on DOOH impressions dynamically, compressing traditional media-buying timelines and elevating yield management sophistication for screen operators.
Growth Catalysts
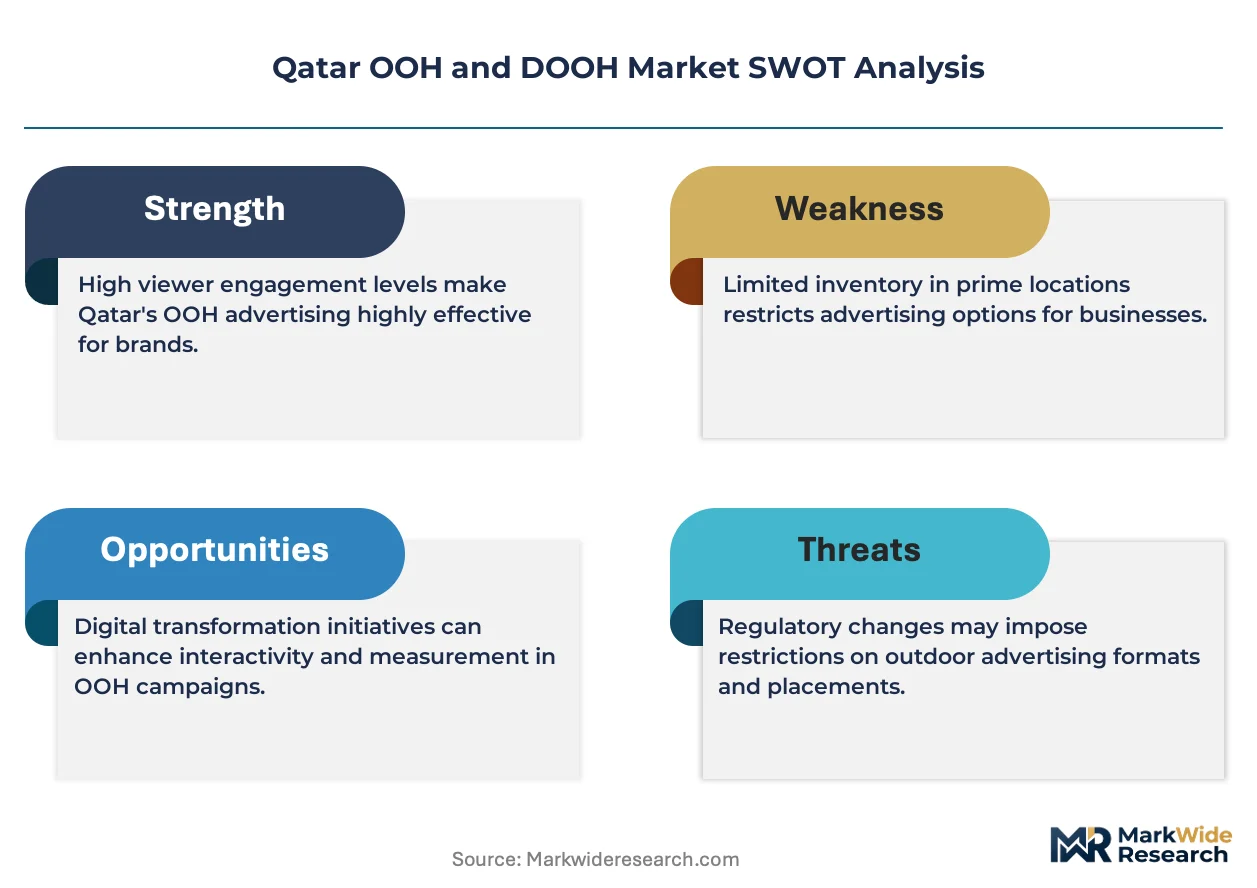
- Qatar National Vision 2030:Urban development targets mandate digital infrastructure deployment across Lusail and Al Wakrah, creating embedded demand for transit-corridor and retail district screen networks.
- LED thermal management advances:Heat-dissipation coatings and active cooling systems now sustain 5,000+ nit brightness in ambient temperatures exceeding 45°C, eliminating operational downtime during peak summer months.
- Hospitality sector expansion:Luxury hotel groups and FIFA-legacy venue operators are commissioning permanent digital façade systems to monetize pedestrian traffic in Doha's West Bay and Pearl-Qatar zones.
Market Restraints
- Import dependency for LED modules:SMD chip supply concentrates among East Asian manufacturers, exposing operators to shipping delays and currency fluctuation risks for critical display components.
- KAHRAMAA efficiency compliance costs:Power supply specifications for outdoor digital assets require redundant transformer infrastructure, elevating connection fees for new installations relative to legacy static formats.
- Permitting timeline variability:Municipal signage approvals across Doha, Lusail, and Al Wakrah lack standardized processing windows, creating deployment uncertainty for network expansion schedules.
Strategic Opportunities
- Hamad International Airport transit corridors:Underutilized pedestrian pathways between terminals and metro links present high-dwell-time inventory for programmatic retail and hospitality campaigns.
- MOCI digital content mandates:Ministry of Commerce and Industry guidelines incentivize Arabic-English bilingual creative standards, favoring operators with localized production capabilities.
- 5G edge computing convergence:Low-latency connectivity enables real-time creative optimization and mobile device synchronization, opening interactive campaign formats previously limited to indoor environments.
Industry Challenges
- Technical specialist scarcity:Field engineers with expertise in LED calibration and content management system integration command premium compensation, constraining network maintenance scalability.
- Legacy static format transition friction:Existing billboard lease structures and advertiser contracts complicate rapid conversion to digital inventory without revenue interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar OOH and DOOH Market |
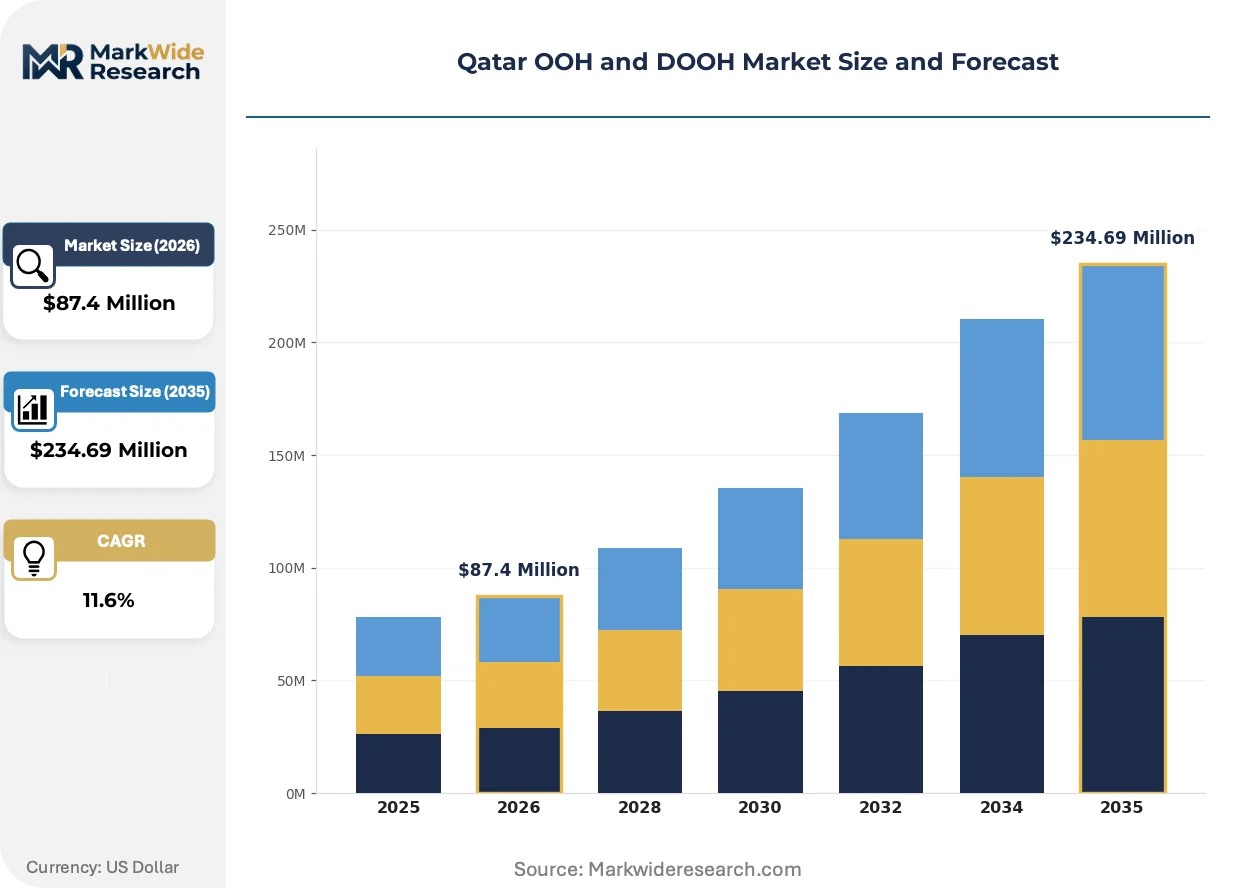
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Advertising Medium: Billboards, Transit Ads, Street Furniture, Digital Screens Technology Type: LED, LCD, Projected Displays, Neon Placement Type: Indoor, Outdoor, Mobile, Fixed Target Audience: Tourists, Locals, Business Professionals, Families |
| Companies Covered | Elan Media, Dooha Media, JCDecaux, Hypermedia FZ-LLC, Daktronics Inc., Elevision, Al Arabia, Backlight Media, Viola Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar OOH and DOOH Market Trends and Innovations
Data-driven audience measurement is displacing circulation-based rate cards across Qatar's outdoor advertising sector. Buyers now demand impression verification and demographic profiling comparable to digital channels, forcing inventory holders to invest in sensor networks and third-party validation partnerships.
Programmatic DOOH platforms is consolidating media planning workflows for multinational brands operating in Doha. Hospitality and luxury retail advertisers now execute cross-channel campaigns spanning mobile, social, and outdoor screens through unified demand-side interfaces. This convergence compresses the gap between awareness and conversion metrics, elevating DOOH's share of integrated marketing budgets.
Ministry of Municipality and Environment urban planning directives are tightening brightness limits and operating-hour restrictions for new digital installations. These codes respond to residential complaints in high-density districts and reshape site selection criteria toward commercial zones with limited adjacent housing. Operators are responding with adaptive dimming systems and directional shielding to preserve inventory value while achieving compliance.
Agency consolidation of media buying functions is concentrating purchasing power among three holding-company networks active in Qatar. This shift elevates volume-based rate negotiations and technical integration requirements, squeezing margins for independent screen operators lacking programmatic certification or direct agency relationships. Smaller networks now face pressure to join cooperative sales consortiums or invest in self-serve platforms to retain advertiser access.
Qatar OOH and DOOH Market Segmentation
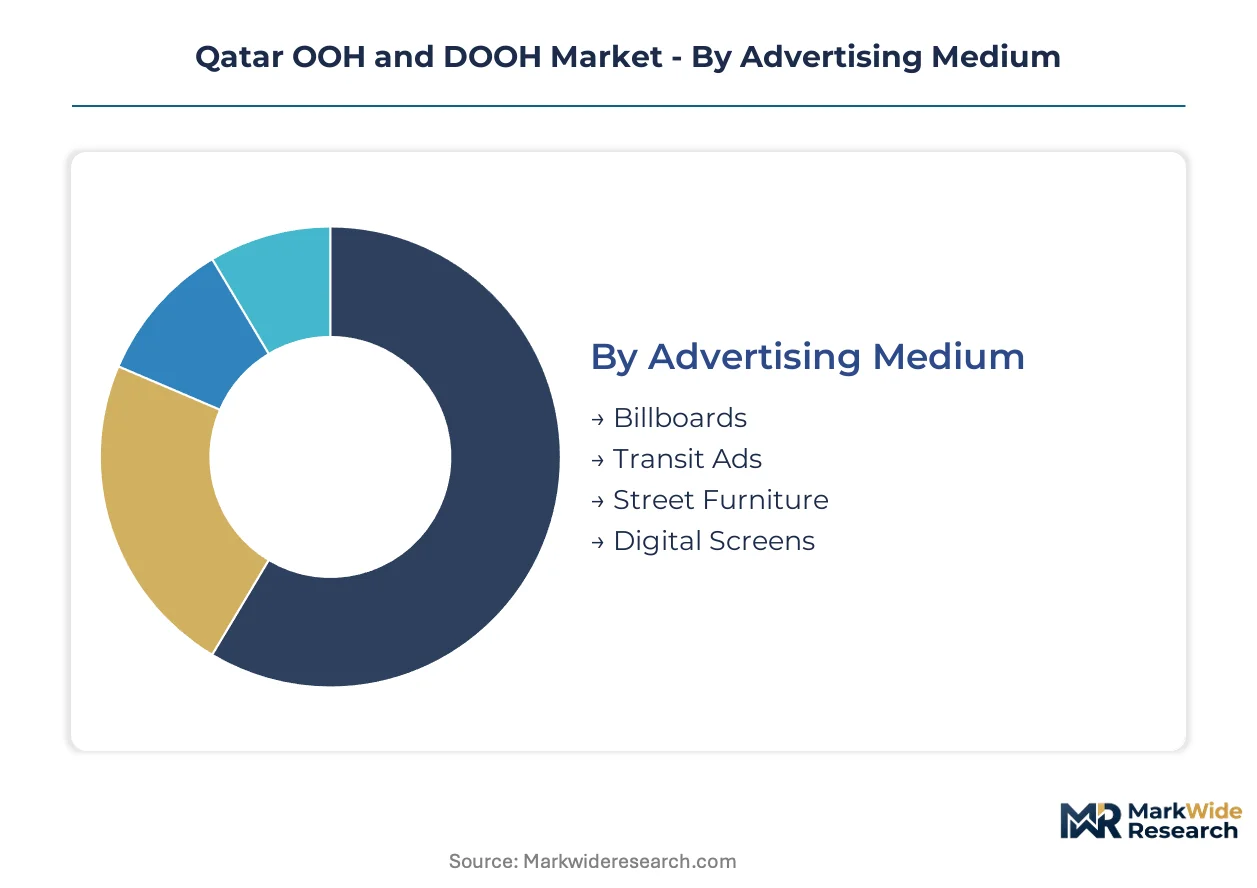
Segmentation reveals how procurement decisions diverge across Qatar's outdoor advertising ecosystem. Buyers prioritize thermal resilience and brightness specifications for desert deployment, while placement type determines regulatory compliance pathways and revenue yield structures.
Advertising Medium:
Buyers select advertising medium based on dwell-time economics and audience mobility patterns across Doha, Lusail, and Al Wakrah corridors.
- Digital Screens:LED and LCD panels enable programmatic trading and real-time content rotation. Demand concentrates in West Bay business towers and Pearl-Qatar retail zones where luxury brands bid dynamically for impression inventory.
- Billboards:Large-format static and digital structures dominate highway visibility corridors linking Hamad International Airport to central Doha. Procurement prioritizes 5,000+ nit brightness ratings and KAHRAMAA-compliant power infrastructure.
- Transit Ads:Metro interior panels, bus wraps, and airport terminal displays capture captive commuter audiences. MOCI content standards mandate Arabic-English bilingual creative for all transit inventory.
- Street Furniture:Bus shelters, kiosks, and wayfinding-integrated screens monetize pedestrian zones. Municipal permitting timelines vary across Doha, Lusail, and Al Wakrah municipalities, creating deployment uncertainty.
Billboards lead on scale; Digital Screens lead on momentum.
Technology Type:
Technology selection hinges on thermal management requirements and field maintenance accessibility in ambient temperatures exceeding 45°C.
- LED:Modular SMD chip architectures deliver 5,000+ nit brightness with active cooling systems. Heat-dissipation coatings sustain operational uptime during peak summer months across Qatar's desert climate.
- LCD:Liquid crystal displays suit indoor transit and retail environments with controlled temperature exposure. Lusail's climate-controlled metro stations and Hamad International Airport terminals drive procurement concentration.
- Projected Displays:Laser and lamp-based projection systems enable temporary activations and building façade mapping. FIFA-legacy venue conversions into permanent commercial districts create demand for large-format immersive formats.
- Neon:Traditional gas-discharge tubing persists in heritage district aesthetics and boutique hospitality branding. Limited deployment reflects high energy consumption and KAHRAMAA efficiency code compliance costs.
LED dominates capital deployment; Projected Displays expand most quickly.
Placement Type:
Placement determines regulatory jurisdiction, brightness limits, and operating hour restrictions under Ministry of Municipality and Environment directives.
- Outdoor:Highway and urban corridor installations face strict brightness caps and residential proximity restrictions. Adaptive dimming systems preserve inventory value while achieving compliance in high-density districts.
- Indoor:Mall, airport, and transit interior screens escape municipal brightness limits but compete for programmatic budget share with mobile and social channels.
- Fixed:Permanent installations on building façades and dedicated structures require transformer infrastructure and KAHRAMAA connection fees exceeding legacy static format costs.
- Mobile:Vehicle-mounted and temporary deployable units serve event activations and construction site advertising. Regulatory clarity on mobile operating permits remains fragmented across municipal jurisdictions.
Outdoor leads on revenue concentration; Indoor leads on programmatic yield sophistication.
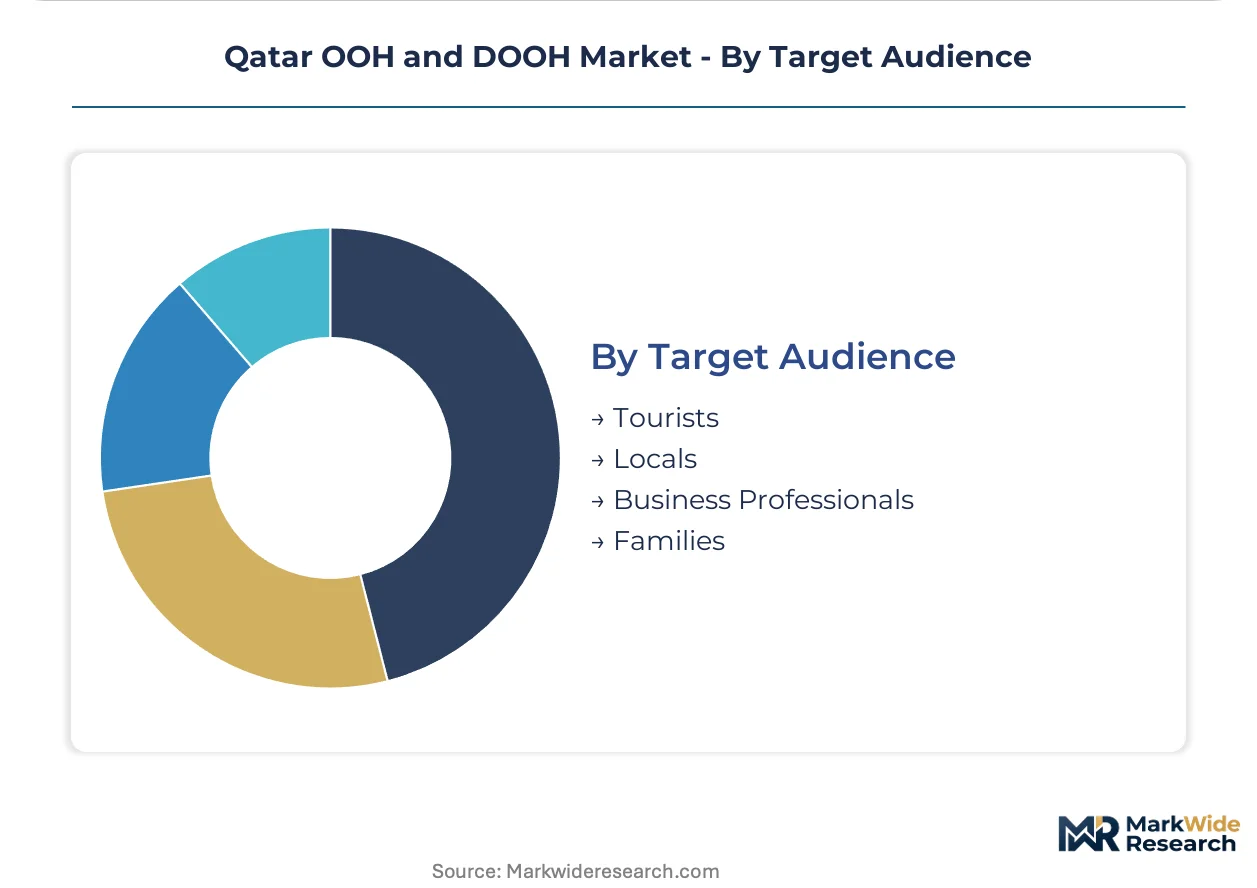
Target Audience:
Audience targeting shapes creative localization requirements and bilingual content investment under MOCI digital content mandates.
- Business Professionals:West Bay and Lusail corporate zones demand B2B services and luxury automotive messaging. High-frequency exposure during weekday commute windows elevates CPM rates.
- Tourists:Hamad International Airport arrival corridors and Souq Waqif heritage districts concentrate hospitality and retail campaigns. English-primary creative dominates with Arabic secondary placement.
- Locals:Qatari nationals and long-term residents respond to family-oriented retail and financial services messaging. Arabic-primary creative with cultural customization commands premium production investment.
- Families:Mall and entertainment district screens target household purchasing decisions. Pearl-Qatar and Katara Cultural Village deployments align with weekend leisure traffic patterns.
Business Professionals lead on spending per impression; Tourists lead on volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qatar OOH and DOOH industry traces its modern scale to FIFA World Cup 2022 infrastructure investments, which transformed Doha into a dense network of digital display corridors. Legacy venue conversions and transit-oriented development now sustain deployment momentum across the emirate's urban core.
Doha Metropolitan Area
West Bay business towers and the Corniche waterfront concentrate premium digital inventory for luxury automotive and financial services advertisers. The Ministry of Municipality and Environment enforces strict brightness caps in high-density districts. Adaptive dimming systems preserve impression value while achieving compliance in the Msheireb Downtown and Souq Waqif heritage zones.
Lusail City
Planned urban development under Qatar National Vision 2030 mandates embedded digital infrastructure across transit corridors and retail districts. The Lusail Light Rail and Marina district generate captive commuter audiences for programmatic campaigns. Stadium precinct conversions into permanent commercial districts redistribute premium inventory value northward from central Doha.
Al Wakrah Municipality
Industrial zone adjacency and expanding residential communities attract mid-market retail and family-oriented messaging. Municipal permitting timelines lag Doha's standardized frameworks, creating deployment uncertainty for network operators. The Al Wakrah Souq heritage district presents localized inventory opportunities with Arabic-primary creative requirements.
Pearl-Qatar and Katara Cultural Village
High-income residential clusters and weekend leisure traffic patterns support luxury hospitality and retail campaigns. The Qatar Tourism Authority's destination marketing programs subsidize premium digital façade installations. English-primary creative dominates, with Arabic secondary placement mandated under MOCI bilingual content standards.
Hamad International Airport Corridor
Underutilized pedestrian pathways between terminals and metro links present high-dwell-time inventory for programmatic retail campaigns. Qatar Airways' hub operations sustain year-round tourist volume regardless of seasonal hospitality fluctuations. Real-time audience data integration enables dynamic bidding for arrival and departure zone impressions.
Qatar OOH and DOOH Market Competitive Landscape
Premium-margin players sit above commodity-margin players across airport concession and transit corridor access. Inventory holders with Ministry of Transport exclusive agreements command yield premiums unavailable to municipal-permit-dependent operators. Three archetypes dominate: integrated concession holders with government relationships, specialized retail network operators, and LED manufacturing-technical service hybrids. Consolidation pressure intensifies as agency buying power concentrates among holding-company networks, while cooperative sales consortiums emerge among independent screen operators lacking direct agency relationships.
Within the integrated concession tier, JCDecaux anchors premium positioning through airport and transit asset control. Elan Media exemplifies the specialized retail network archetype with mall and hospitality zone coverage. Daktronics Inc. occupies the manufacturing-technical service hybrid position, supplying LED infrastructure for stadium and highway deployments. Each represents a distinct competitive vector: concession exclusivity, placement specialization, and hardware-software integration capability.
| Leading Market Players |
|---|
| Elan Media |
| Dooha Media |
| JCDecaux |
| Hypermedia FZ-LLC |
| Daktronics Inc. |
| Elevision |
| Al Arabia |
| Backlight Media |
| Viola Communications |
| Others |
Pricing and Supply Chain Analysis
LED calibration specialists concentrated in Doha and Al Wakrah command premium compensation packages that widen pricing spreads between premium-tier full-service operators and economy-tier hardware-only suppliers. Labor-cost differentials across these technical workforce pools directly shape how procurement teams evaluate total-cost-of-ownership bids for stadium and transit corridor deployments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Qatar's OOH procurement landscape. Premium tiers attach to JCDecaux's airport concessions and Elan Media's mall networks where programmatic yield management justifies higher rates. Standard tiers cover municipal-permit highway billboards with KAHRAMAA-compliant transformer infrastructure. Economy tiers serve mobile and temporary activations with limited after-sales support. Price differentiation rests on thermal management certification and Arabic-English bilingual creative production capabilities. Pricing pressure stems from agency consolidation among holding-company networks squeezing independent operators. Tourism-focused advertisers at Hamad International Airport show least price sensitivity; mid-market retail in Al Wakrah shows most.
Supply Chain Analysis
Dual-sourcing requirements for SMD LED modules now appear in Qatar General Electricity and Water Corporation procurement guidelines for large-format installations. Supply concentrates in China, South Korea, and Taiwan for chip fabrication and driver electronics. Heat-dissipation coatings and active cooling subsystems draw from German and Japanese component suppliers. Raw material dependencies span gallium nitride substrates, aluminum heat sinks, and copper power cabling. Single-source vulnerability persists for 5,000+ nit brightness-rated modules certified for 45°C ambient operation. Distribution runs through Doha-based integrators with Ministry of Municipality and Environment installation permits, bypassing direct manufacturer-to-operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's OOH sector offers margin-expansion potential as LED thermal management standardization drives down field maintenance costs and programmatic trading elevates premium inventory yields.
For Market Incumbents: Acquire underutilized transit corridor permits between Hamad International Airport terminals and metro links. Consolidate these high-dwell-time assets before new entrants secure Ministry of Transport concession agreements. Backward integration into Arabic-English bilingual creative production studios defends against agency consolidation pressure. Investment in 5G edge computing infrastructure preserves technical differentiation as interactive campaign formats displace static digital rotation. For New Entrants and Emerging Players: AI-powered audience measurement sensors represent the most penetrable technology wedge for unseating established rate-card systems. Target Al Wakrah Municipality's fragmented permitting environment where municipal approval timelines lag Doha's standardized frameworks. Pursue FIFA-legacy venue conversion projects in Lusail where stadium precincts transition into permanent commercial districts with embedded digital infrastructure mandates. Partner with Qatar Tourism Authority destination marketing programs to subsidize premium digital façade installations. For Investors and Strategic Acquirers: Hospitality sector conglomerates are the most active acquirer in this space, seeking captive advertising channels for luxury hotel and entertainment assets. Five-to-ten year viability hinges on Qatar National Vision 2030 urban development execution sustaining transit-oriented screen network deployment. Acquisition target archetype: specialized retail network operators with Pearl-Qatar and Katara Cultural Village coverage lacking programmatic certification. Watch for MOCI digital content mandate enforcement tightening as the signal for accelerated bilingual creative capability consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Certification | Unlocks access to holding-compency agency buying pools that control luxury brand budgets. |
| KAHRAMAA Efficiency Compliance Investment | Reduces connection fee burden for new fixed installations relative to legacy static formats. |
| Arabic-English Bilingual Creative Studio Acquisition | Aligns with MOCI digital content mandates favoring localized production capabilities. |
| 5G Edge Computing Infrastructure Deployment | Enables real-time creative optimization and mobile synchronization for interactive formats. |
| Transit Corridor Concession Expansion | Captures high-dwell-time inventory between Hamad International Airport and metro links. |
Research Methodology
Coverage spans Doha, Lusail, Al Wakrah, and the Hamad International Airport corridor, with primary inputs from each municipality's regulatory environment. The research combines structured interviews with network operations directors, LED integration engineers, media buying leads at hospitality brands, and Ministry of Commerce and Industry licensing officials with secondary validation. Secondary sources include KAHRAMAA efficiency code filings, Ministry of Municipality and Environment urban planning directives, Qatar National Vision 2030 progress reports, and programmatic platform technical documentation. Bottom-up screen inventory counts triangulate against top-down advertising expenditure estimates across the analysis window.
Rate-of-change decomposition separates volume expansion from yield-per-improvement across the projection horizon. The analytical framework models Advertising Medium, Technology Type, Placement Type, and Target Audience segmentation dimensions with particular attention to thermal resilience specifications and bilingual content compliance pathways. CAGRs derive from installed base growth curves adjusted for FIFA-legacy venue conversion timelines and Qatar National Vision 2030 transit infrastructure completion schedules. Forecast inputs incorporate LED module import dependency patterns and municipal permitting timeline variability across Doha, Lusail, and Al Wakrah jurisdictions.
The model holds under continued Qatar National Vision 2030 execution and stable MOCI content standard enforcement; deviation in Ministry of Transport concession renewal terms or KAHRAMAA efficiency code revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Vietnam OOH and DOOH Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
China OOH and DOOH Market