
 Saudi Arabia OOH and DOOH Market | 2026-2036
Saudi Arabia OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia OOH and DOOH Market Insights
A shortage of certified digital display technicians is unwinding deployment timelines for programmatic DOOH networks. JCDecaux SE leverages its European engineering protocols to sustain premium transit shelter installations across Riyadh and Jeddah. Arabian Contracting Services Co. anchors large-format billboard construction through its steel fabrication and site-permitting capabilities. Daktronics, Inc. competes on LED module reliability for stadium and entertainment venue applications.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display media deployed in public spaces, including LED video walls with pixel pitches ranging from 2.5mm to 16mm depending on viewing distance, and printed vinyl substrates on steel monopole structures. The primary commercial purpose is to deliver brand messaging to audiences in transit, retail, or leisure environments where mobile and desktop media cannot reach. Digital screens command the fastest expansion within media type segmentation due to real-time content rotation and programmatic trading capabilities. Static formats still dominate total inventory volume but carry lower yield per face. Interactive and mobile formats within the format dimension are gaining traction in retail and entertainment sectors where engagement metrics drive buyer decisions.
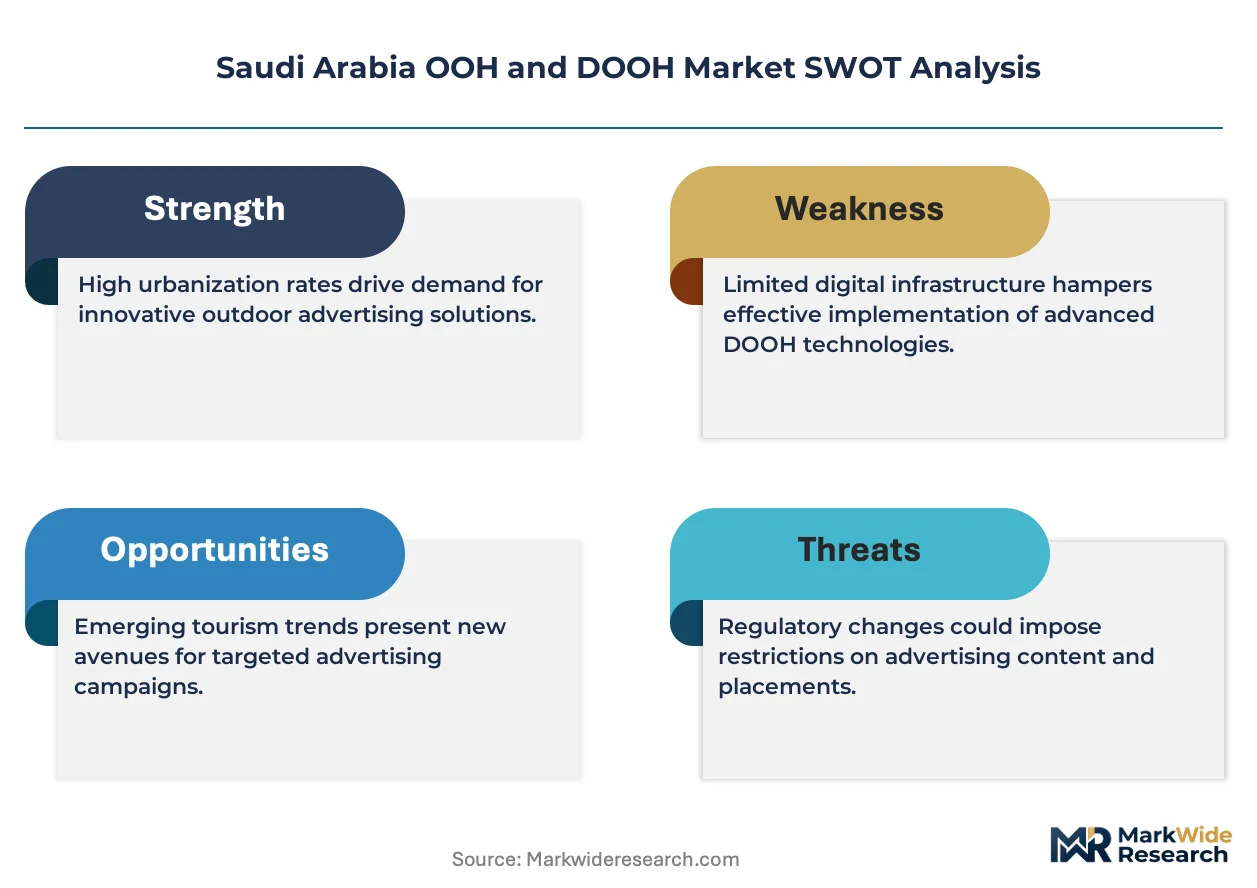
The General Authority for Audiovisual Media (GCAM) governs content standards and operator licensing, while municipal authorities in Riyadh, Jeddah, and Dammam control roadside placement permits and safety clearances. The Saudi Building Code and civil defense requirements shape structural specifications for elevated installations in high-wind zones. Stakeholders must monitor how GCAM's evolving digital content classification rules intersect with municipal smart-city data governance frameworks.
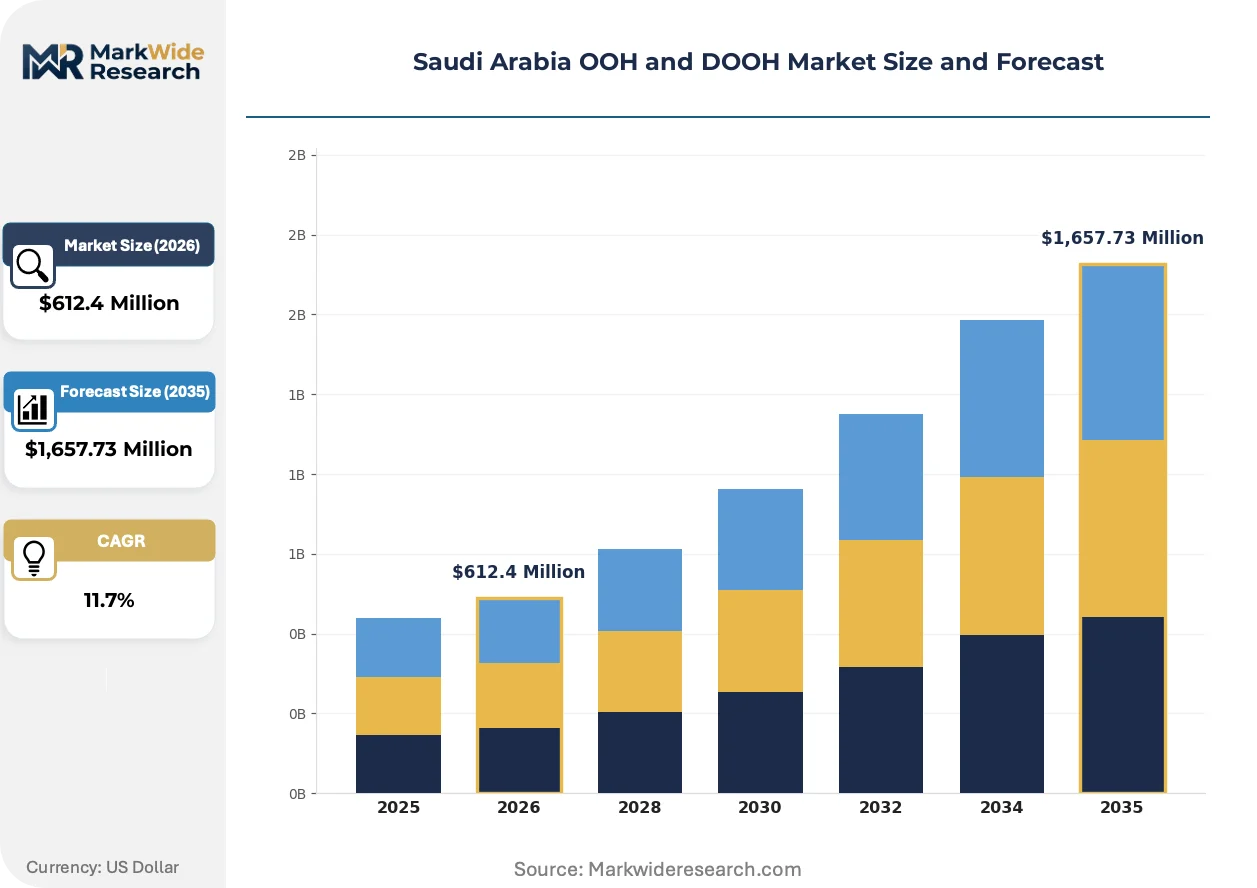
Market Dynamics
Programmatic DOOH trading infrastructure is concentrating buying power among Saudi advertisers with data management platform capabilities, while GCAM's content pre-approval requirements extend deployment lead times for real-time campaigns.
Growth Catalysts
- Transit Authority Modernization:Municipal transport authorities in Riyadh and Jeddah are retrofitting bus shelters and metro stations with networked digital displays, creating captive audience inventory for daily commuters.
- GCAM Licensing Framework:The General Authority for Audiovisual Media's standardized operator certification is professionalizing the vendor base and reducing content compliance friction for licensed players.
- Retail Entertainment Integration:Mixed-use developments along Riyadh's commercial corridors are embedding LED video walls into architectural facades, merging advertising with destination experiences.
Market Restraints
- LED Module Import Dependency:Premium SMD and COB display components concentrate in East Asian manufacturing clusters, exposing operators to shipping cost volatility and customs clearance delays.
- Steel Monopole Fabrication Bottlenecks:Domestic structural steel capacity limits large-format billboard construction velocity, extending permit-to-installation timelines for highway-facing inventory.
- GCAM Content Pre-Approval:Mandatory review periods for dynamic creative assets prevent same-day campaign activation, compressing the addressable market for time-sensitive advertisers.
Strategic Opportunities
- Neom and Red Sea Project Greenfield Deployment:Giga-project developments offer unencumbered right-of-way for DOOH network installation without legacy infrastructure retrofit constraints.
- 5G-Enabled Programmatic Trading:Low-latency connectivity convergence with ad-serving platforms enables impression-level auction mechanics previously unavailable in static-dominant markets.
- Dammam Industrial Corridor Undersupply:Eastern Province manufacturing and logistics zones carry minimal DOOH penetration relative to population density and commercial vehicle traffic.
Industry Challenges
- Certified Display Technician Scarcity:Network maintenance and pixel calibration expertise concentrates among expatriate specialists, constraining nationwide service coverage expansion.
- Municipal Permit Fragmentation:Riyadh, Jeddah, and Dammam authorities maintain non-harmonized safety clearance protocols, multiplying compliance overhead for multi-city operators.
- Legacy Static Contract Rollover:Long-term billboard lease structures delay digital conversion timelines as incumbent operators defend rental income from printed vinyl installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia OOH and DOOH Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,657.73 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboards, Posters, Digital Screens, Transit Advertising Sector: Retail, Sports, Entertainment, Government Format: Static, Digital, Interactive, Mobile Ownership Model: Public, Private, Partnership, Franchise |
| Companies Covered | Arabian Contracting Services Co. (AlArabia), JCDecaux SE, Saudi Signs Media Co., Alan Media and Advertising Co., Alliance Media Holdings (Pty) Ltd, Daktronics, Inc., Advertising Ways Company Ltd., Faden Media Advertising Agency, SMC (Saudi Media Company), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia OOH and DOOH Market Trends and Innovations
Real-time audience measurement is displacing traffic-count methodologies as the primary currency for inventory valuation, while content management platforms migrate toward cloud-native architectures.
AI-powered dynamic creative optimization is fragmenting traditional campaign planning workflows. The technology ingests environmental triggers including traffic density, weather conditions, and sports event outcomes to rotate messaging without human intervention. QSR and automotive advertisers in Jeddah's retail districts are piloting these systems for lunch-hour and weekend promotion cycles. This capability is compressing the competitive advantage of operators with static-only inventory positions.
GCAM's evolving digital content classification rules are tightening pre-approval protocols for programmatic-served assets. The regulation now requires frame-by-frame review for motion-activated displays in proximity to educational and religious institutions. Transit shelter operators in Riyadh's King Abdullah Financial District face the steepest compliance burden, responding by building dedicated content operations teams rather than outsourcing to agency partners.
Advertiser procurement patterns are consolidating around outcome-based impression guarantees rather than slot-based rental contracts. Media buyers at Saudi FMCG and telecom groups now demand verified audience attention metrics from computer vision analytics. This shift is most visible in Riyadh's luxury retail zones, where landlords and operators share infrastructure investment risk through revenue-sharing arrangements tied to measured engagement duration.
Saudi Arabia OOH and DOOH Market Segmentation
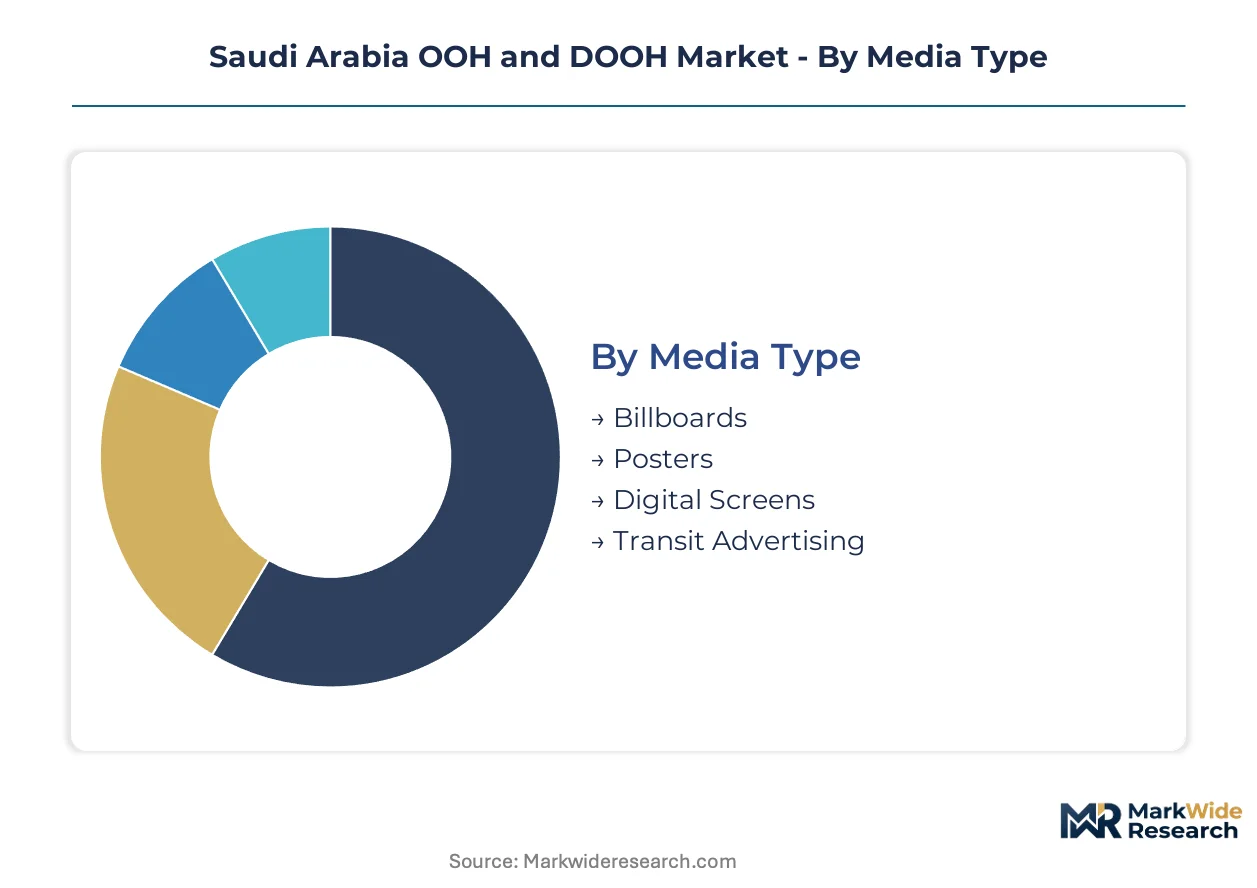
Segmentation in Saudi Arabia's OOH and DOOH landscape reveals where capital allocation and regulatory attention concentrate. Understanding these divisions clarifies why certain inventory types command premium rates while others face conversion pressure.
Media Type:
Margin pools sit heaviest in formats that combine high dwell time with programmatic delivery capability.
- Digital Screens:LED and LCD displays with pixel pitches from 2.5mm to 16mm enable real-time content rotation and impression-level trading. Demand concentrates in Riyadh's King Abdullah Financial District and Jeddah's retail corridors, where advertisers pay premiums for programmatic audience targeting.
- Billboards:Steel monopole and cantilever structures carrying printed vinyl or static digital faces dominate highway-facing inventory. Steel fabrication bottlenecks in the Eastern Province extend installation timelines, compressing near-term supply expansion.
- Transit Advertising:Networked displays in bus shelters and metro stations capture captive commuter audiences. Riyadh and Jeddah municipal authorities are retrofitting these assets with digital connectivity.
- Posters:Smaller-format printed substrates on street furniture and indoor panels serve local retail and service advertisers. Lower yield per face limits capital investment relative to large-format alternatives.
Digital Screens holds installed capacity. Transit Advertising is rotating up the share rankings.
Sector:
Customer procurement sophistication varies sharply across verticals, with entertainment and retail leading on data-driven buying.
- Retail:Mixed-use developments along Riyadh's commercial corridors embed LED video walls into architectural facades, merging advertising with destination experiences. Luxury brands in these zones now demand verified audience attention metrics from computer vision analytics.
- Entertainment:Stadiums, cinemas, and leisure venues deploy large-format LED for brand immersion. Daktronics anchors supply for venue operators seeking module reliability under high-ambient-light conditions.
- Sports:Venue-based inventory commands event-day rate premiums, though seasonal demand concentration creates utilization challenges during off-peak periods.
- Government:Municipal and state entities control transit shelter networks and public safety messaging infrastructure, prioritizing compliance over yield optimization.
Retail captures the steepest pricing premiums. Entertainment is climbing the fastest on engagement-metric demand.
Format:
Technology maturity curves separate inventory types with real-time adaptability from legacy static positions.
- Digital:Programmable displays with cloud-native content management enable frame-by-frame rotation without physical site visits. GCAM's pre-approval requirements extend deployment lead times for real-time campaigns.
- Interactive:Motion-activated and touch-enabled displays in retail and entertainment sectors generate engagement metrics that drive buyer decisions. Frame-by-frame GCAM review applies near educational and religious institutions.
- Static:Printed vinyl on rigid substrates still dominates total inventory volume but carries lower yield per face and longer contract lock-in periods.
- Mobile:Vehicle-mounted and portable display units serve event-based and tactical campaigns with limited recurring revenue visibility.
Static maintains volume dominance. Digital is expanding most quickly on programmatic trading infrastructure.
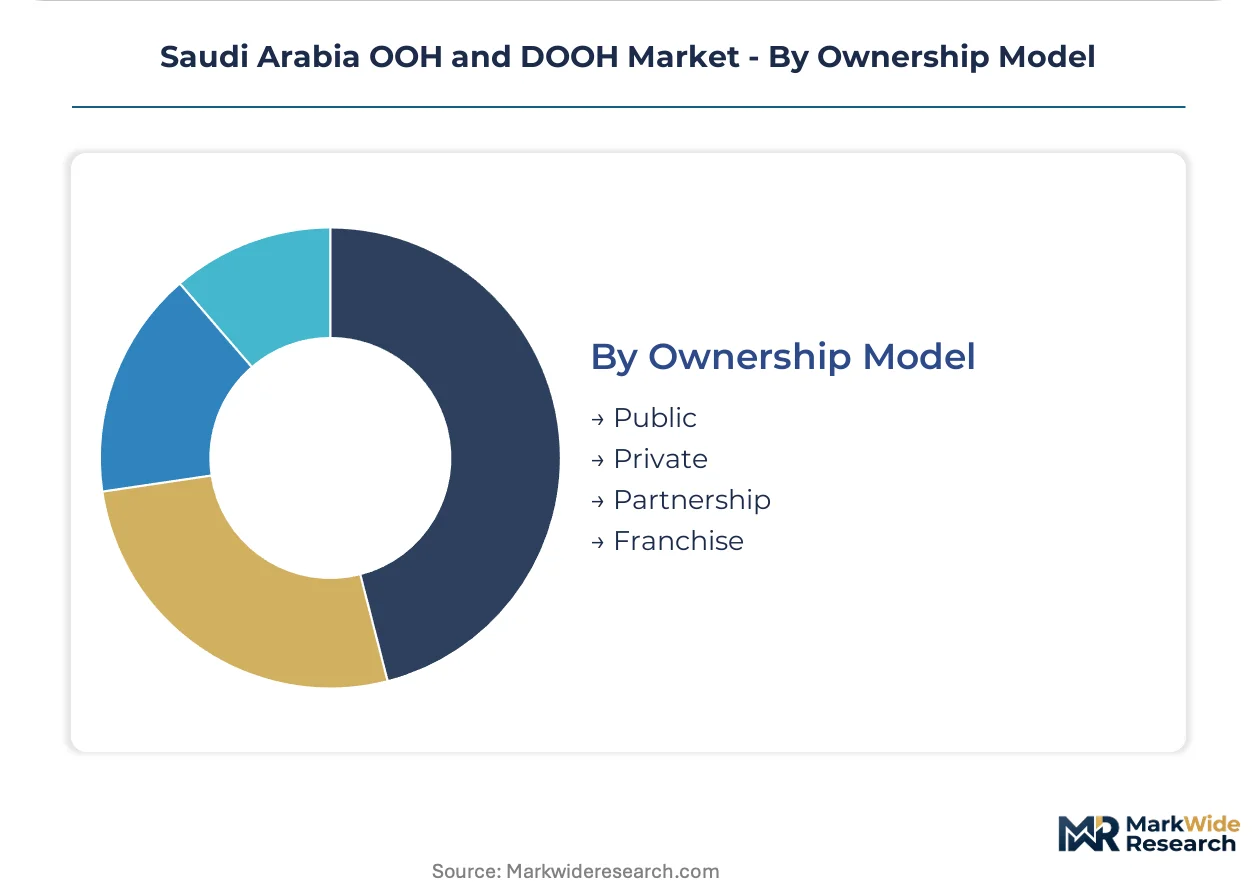
Ownership Model:
Capital intensity and regulatory burden distribution shape operator returns across governance structures.
- Private:Independent operators control premium inventory in Riyadh and Jeddah commercial zones, bearing full capital risk for digital conversion timelines.
- Partnership:Revenue-sharing arrangements between landlords and operators tie infrastructure investment to measured engagement duration, visible in Riyadh's luxury retail zones.
- Public:Municipal authorities retain control of transit shelter and street furniture networks, prioritizing public service messaging over commercial yield.
- Franchise:Branded network operators license technology and operational protocols to local partners, concentrating in emerging Dammam corridor markets.
Private operators hold premium inventory concentration. Partnership structures are gaining share on risk-sharing preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GCAM's licensing framework anchors regulatory oversight across Saudi Arabia's out-of-home advertising landscape. Municipal authorities in Riyadh, Jeddah, and Dammam control placement permits and safety clearances. The market concentrates inventory investment in commercial corridor developments and transit modernization programs.
Riyadh
King Abdullah Financial District drives premium digital screen deployment for programmatic trading. Riyadh Municipality's smart-city data governance intersects with GCAM content classification rules. Mixed-use developments along commercial corridors embed LED video walls into architectural facades.
Jeddah
Retail districts pilot AI-powered dynamic creative optimization for lunch-hour promotion cycles. Jeddah Municipality maintains distinct safety clearance protocols from Riyadh authorities. Red Sea coastal tourism zones attract entertainment venue LED installations.
Eastern Province
Dammam's industrial corridor carries minimal DOOH penetration relative to commercial vehicle traffic density. Eastern Province manufacturing zones face steel monopole fabrication bottlenecks. Dhahran's corporate headquarters cluster generates demand for transit shelter network retrofits.
NEOM Northwest
Giga-project developments offer unencumbered right-of-way for greenfield DOOH network installation. NEOM's absence of legacy infrastructure eliminates retrofit constraints. Northwest coastal positioning enables 5G-enabled programmatic trading infrastructure deployment.
Western Region
Makkah and Madinah pilgrimage routes concentrate transit advertising inventory for seasonal audience capture. Regional municipal authorities enforce stricter content pre-approval near religious institutions. Highway-facing static billboards dominate intercity corridor inventory.
Saudi Arabia OOH and DOOH Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Saudi Arabia's OOH and DOOH market. European engineering protocols distinguish premium transit shelter operators from domestic fabricators. Three archetypes dominate: municipal partnership specialists, steel fabrication integrators, and LED module reliability providers. Capacity expansion and revenue-sharing arrangements with landlords represent the dominant competitive moves.
Among European-based operators, JCDecaux SE exemplifies the municipal partnership archetype through transit shelter protocol transfer. Arabian Contracting Services Co. anchors steel fabrication and site-permitting capabilities for large-format billboard construction. Daktronics, Inc. occupies a position within LED module supply for stadium and entertainment venue applications.
| Leading Market Players |
|---|
| Arabian Contracting Services Co. (AlArabia) |
| JCDecaux SE |
| Saudi Signs Media Co. |
| Alan Media and Advertising Co. |
| Alliance Media Holdings (Pty) Ltd |
| Daktronics, Inc. |
| Advertising Ways Company Ltd. |
| Faden Media Advertising Agency |
| SMC (Saudi Media Company) |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between municipal transport authorities and network operators lock in supply access for transit shelter inventory while anchoring price visibility across multi-year deployment cycles. These structures insulate operators from spot-market volatility in LED module procurement but compress margins when steel fabrication costs escalate.
Pricing Analysis
Contract-based long-term offtake structures dominate premium inventory in Riyadh's King Abdullah Financial District and Jeddah's retail corridors. Price differentiation rests on pixel density grade and GCAM certification tier, with programmatic-enabled displays commanding premiums over static alternatives. Cost compression in standard-format billboards is intensifying because domestic steel fabrication capacity constraints extend permit-to-installation timelines. Municipal authorities exhibit lowest price sensitivity given public-service messaging mandates, while mid-market retail advertisers demonstrate acute sensitivity to impression-guarantee verification costs.
Supply Chain Analysis
Strategic stockpile preferences among Saudi operators concentrate around LED module inventories sourced from China, South Korea, and Taiwan to buffer against shipping cost volatility and customs clearance delays. Raw material dependencies center on SMD and COB display components, structural steel for monopole fabrication, and aluminum extrusions for frame housing. Single-source vulnerability in East Asian semiconductor packaging exposes networks to allocation constraints during demand spikes. Distribution runs through Jeddah and Dammam port clusters for inbound components, with final-mile installation coordinated through Riyadh-based technical service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's OOH and DOOH market fragments across regulatory jurisdictions and technical capability tiers, creating niches for specialists who master GCAM compliance workflows or captive steel fabrication. Advertiser procurement consolidation around outcome-based impression guarantees rewards operators with verified audience measurement infrastructure.
For Market Incumbents: Compound advantages in municipal partnership networks by embedding revenue-sharing terms tied to engagement-duration metrics before lease renewal cycles. Deepen upstream control over steel fabrication capacity to compress permit-to-installation timelines. Prioritize certification investment in GCAM's evolving digital content classification protocols to defend against compliance-specialist entrants. For New Entrants and Emerging Players: Lead with Dammam's industrial corridor, where commercial vehicle traffic density far exceeds DOOH penetration relative to Riyadh and Jeddah benchmarks. Target franchise arrangements with European engineering protocol holders to bypass certified technician scarcity constraints. Anchor go-to-market positioning on 5G-enabled programmatic trading infrastructure for impression-level auction mechanics unavailable to static-dominant incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators combining steel fabrication capabilities with municipal transit shelter concessions across the analysis window. Acquisition targets should display captive supply of structural components and established GCAM licensing workflows. The signal to watch is GCAM's frame-by-frame review protocol expansion, which will concentrate compliance overhead and accelerate consolidation toward licensed players with dedicated content operations teams.| Strategic Initiative | Industry Significance |
|---|---|
| Revenue-Sharing Partnership Structure | Aligns landlord and operator incentives through engagement-duration-linked returns in Riyadh luxury retail zones. |
| Backward Integration into Steel Fabrication | Compresses permit-to-installation timelines for highway-facing inventory constrained by Eastern Province capacity limits. |
| GCAM Certification Pre-Investment | Positions operators for compliance advantage as frame-by-frame review protocols tighten near educational institutions. |
| 5G-Enabled Programmatic Platform Deployment | Enables impression-level auction mechanics previously unavailable in Saudi static-dominant inventory markets. |
| Certified Technician Training Pipeline | Addresses network maintenance scarcity constraining nationwide service coverage expansion for digital screen operators. |
Research Methodology
A spread of perspectives from municipal transport planners, GCAM licensing officers, media procurement directors at Saudi FMCG groups, LED module distributors, and steel fabrication plant managers converged on the working assumptions. Primary interview intelligence combined with secondary validation from GCAM regulatory filings, Saudi Building Code amendments, municipal tender databases, and customs import records. Bottom-up inventory counts across Riyadh, Jeddah, and Dammam transit shelter networks triangulated against top-down media spending estimates from advertiser association disclosures.
Segmentation dimensions modeled span media type, sector vertical, format technology, and ownership structure across the projection horizon. CAGRs derived from installed base expansion rates, digital conversion timelines, and programmatic trading penetration curves. Forecast inputs incorporate municipal retrofit program announcements, giga-project development schedules, and GCAM licensing issuance trajectories.
Underlying assumptions cover sustained municipal transit modernization funding, stable East Asian LED module supply flows, and gradual GCAM regulatory harmonization, with deviation risk concentrated in steel fabrication capacity constraints and certified technician availability. Revision becomes warranted when GCAM content pre-approval periods extend beyond operational tolerances for real-time campaign activation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
China OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Magazine Advertising Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Malaysia OOH and DOOH Market
Advertising and Marketing Media
United States Marketing Agencies Market