
 Kids Digital Advertising Market | 2026-2036
Kids Digital Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Digital Advertising Market Outlook
Programmatic ad-buying platforms with self-serve interfaces and outcome-based pricing is reconfiguring which publishers and developers can monetize child-facing content without dedicated sales teams. Google LLC leverages its demand-side platform dominance to anchor programmatic inventory across family-safe YouTube channels. Meta Platforms Inc. competes through Instagram Reels and Messenger Kids integrations that sustain advertiser reach within walled-garden environments. KIDOZ Inc. specializes in COPPA-compliant mobile ad mediation that differentiates its SDK-based model from generalist networks.
Kids digital advertising encompasses promotional content delivered through digital channels to audiences under eighteen, employing age-gating algorithms, contextual targeting, and zero-data personalization to replace behavioral tracking. Its primary commercial purpose connects toy manufacturers, entertainment studios, and food brands with minors through brand-safe inventory that satisfies parental and regulatory scrutiny. Streaming services and mobile apps represent the fastest-expanding platform categories as subscription fatigue pushes platforms toward hybrid ad-supported tiers for family accounts. Interactive ads and games command premium engagement rates among the preschool and early childhood segments, where attention spans reward participatory formats over passive banners.
The Federal Trade Commission enforces COPPA penalties that shape how U.S. publishers collect verifiable parental consent before serving personalized ads to children under thirteen. Europe's GDPR-K and the proposed EU Digital Services Act extend similar guardrails across member states, forcing platforms to deploy age-estimation technology or default to non-profiling delivery. China's SAMR and MIIT administer parallel minors-protection provisions that restrict ad frequency and content categories for users under eighteen. Stakeholders must monitor regulatory divergence across these three jurisdictions to determine whether centralized compliance architecture or market-specific operations delivers lower total cost of ownership.
Market Dynamics
Programmatic ad-buying platforms with self-serve interfaces are compressing sales cycles and reconfiguring which publishers can monetize child-facing content without dedicated commercial teams.
Growth Catalysts
- Hybrid ad-supported tiers:Streaming services are introducing family account structures that combine subscription revenue with compliant ad inventory, expanding addressable impressions for toy manufacturers and entertainment studios.
- GDPR-K enforcement:Europe's strengthened minors-protection framework is accelerating investment in age-estimation technology and contextual targeting infrastructure across member states.
- Interactive ad formats:Gamified and participatory creative units command engagement premiums in preschool segments where attention metrics reward active participation over passive consumption.
Market Restraints
- Verifiable consent infrastructure:COPPA-mandated parental verification systems impose fixed compliance costs that disproportionately burden smaller publishers and independent app developers.
- Data deprecation:The phase-out of device identifiers and third-party cookies eliminates behavioral targeting signals that historically powered personalization in youth segments.
- Platform concentration:Demand-side platform dominance by major technology companies creates gatekeeper dependencies for inventory access and pricing transparency.
Strategic Opportunities
- Zero-data personalization:Contextual and cohort-based targeting technologies that operate without individual profiling are opening compliant pathways in jurisdictions with strict minors-protection rules.
- Educational platform integration:Curriculum-aligned content environments in the United Kingdom and China offer brand-safe inventory with inherent parental trust and extended session duration.
- Connected TV expansion:Family viewing profiles on streaming devices create addressable household segments that bypass individual-level tracking restrictions.
Industry Challenges
- Age-estimation engineering:Developing reliable technical systems that distinguish between child and adult users without collecting biometric data requires specialized machine-learning expertise that remains scarce.
- Cross-jurisdictional compliance:Operating across COPPA, GDPR-K, and China's SAMR frameworks forces architectural decisions between centralized or market-specific technology stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Digital Advertising Market |
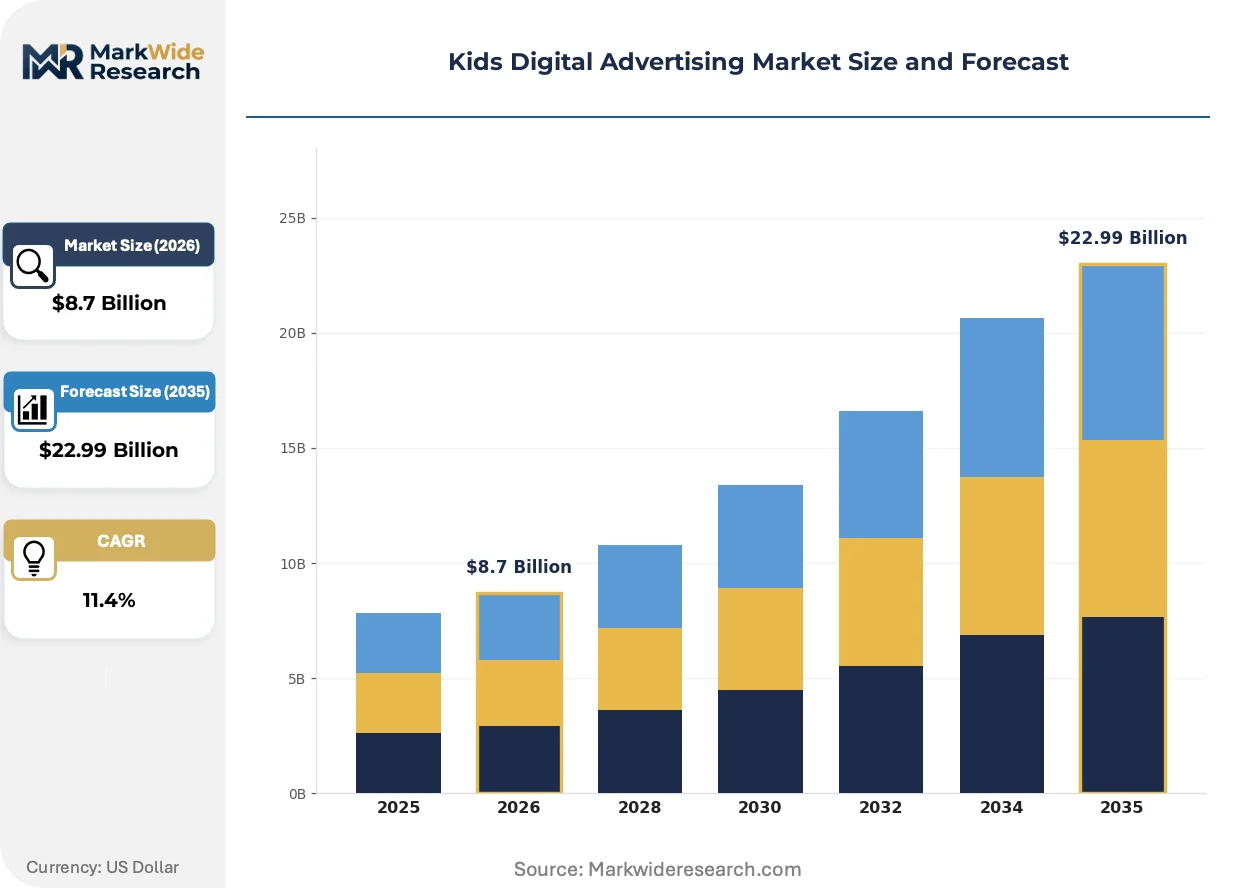
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Social Media, Streaming Services, Mobile Apps, Websites Content Format: Videos, Banners, Interactive Ads, Games Target Age Group: Preschool, Early Childhood, Middle School, Teenagers Engagement Method: Influencer Marketing, Contest Promotions, Sponsored Content, Brand Collaborations |
| Companies Covered | Microsoft Corporation, KIDOZ Inc., Adobe Inc., Blue Wheel Media LLC, AppLovin Corporation, Amazon.com Inc., Meta Platforms Inc., SuperAwesome, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Digital Advertising Market Strategic Shifts
Contextual intelligence and privacy-preserving measurement are displacing legacy behavioral infrastructure across child-facing digital environments.
Contextual intelligence engines are hybridizing natural language processing with content metadata analysis to infer audience composition without user-level tracking. Educational publishers and family-safe YouTube channel operators are deploying these systems to maintain addressability under tightening data restrictions. The technology is hybridizing previously separate functions of brand safety verification and audience qualification into unified pre-bid decisioning.
The EU Digital Services Act extends GDPR-K provisions with mandatory age-gating and transparency requirements for algorithmic content recommendation. Platforms must now document how their systems expose minors to advertising and provide parental oversight tools. This framework is forcing the largest inventory sources to rebuild recommendation architectures, creating temporary supply constraints while smaller compliant publishers gain relative access.
Buyer concentration among direct-to-consumer toy brands and subscription entertainment services is consolidating planning and execution into in-house programmatic operations. Agencies specializing in youth marketing are losing share to platform-native buying tools and self-serve interfaces. This pattern is most pronounced in the United States where advertiser technology maturity enables direct publisher relationships without intermediary layers.
Kids Digital Advertising Market Segmentation
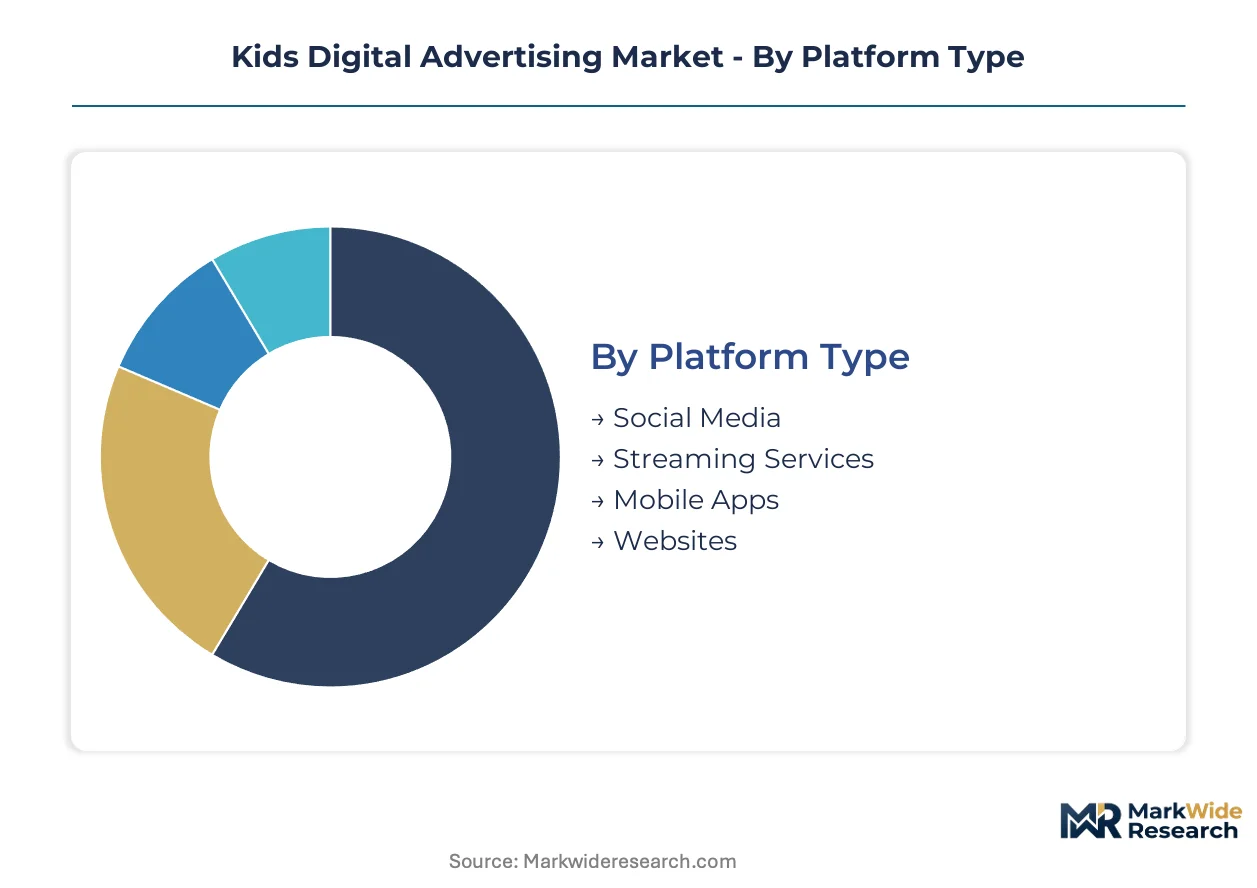
Segmentation in kids digital advertising determines which inventory formats command premium rates and which face regulatory friction. Platform type dictates compliance architecture, while age-group targeting shapes creative permissible under COPPA and GDPR-K. Content format selection directly correlates with attention metrics and parental acceptance thresholds.
Platform Type:
Inventory refresh cycles vary dramatically across platforms, with social media turning over fastest and websites maintaining the longest campaign lifespans.
- Streaming Services:Hybrid ad-supported family tiers generate addressable impressions through connected TV devices. Disney+, Netflix, and Paramount+ compete for toy manufacturer budgets in the United States and United Kingdom where household penetration of streaming hardware concentrates.
- Mobile Apps:SDK-based mediation layers from KIDOZ and SuperAwesome enable COPPA-compliant monetization for independent developers. China's MIIT restrictions on minors' gaming duration compress session windows, forcing higher ad frequency caps.
- Social Media:YouTube Kids and Instagram Reels dominate reach.
- Websites:Educational publishers maintain extended engagement.
Mobile apps dominate installed base. Streaming services are where expansion concentrates.
Content Format:
Production cost tiers separate premium interactive units from standardized display inventory, with video occupying the middle ground.
- Interactive Ads:Gamified creative units command engagement premiums through participatory mechanics. Preschool segments in the United Kingdom reward active participation with completion rates that justify higher production investment.
- Videos:Pre-roll and mid-roll formats scale across platform types. YouTube's family-safe channel ecosystem anchors volume in the United States while China's SAMR content restrictions limit permissible categories.
- Games:Advergaming integrates brand messaging into play mechanics.
- Banners:Static display faces deprecation pressure.
Videos dominate installed base. Interactive ads are climbing the fastest.
Target Age Group:
Regulatory scrutiny intensifies as age decreases, with preschool segments facing the strictest consent requirements and teenagers permitting broader targeting.
- Preschool:Zero-data personalization is mandatory under COPPA's behavioral tracking prohibitions. Contextual targeting on PBS Kids and Nick Jr. properties sustains addressability for toy manufacturers.
- Early Childhood:Parental co-viewing patterns extend session duration. Educational platform integrations in China curriculum-aligned environments offer brand-safe inventory with inherent trust transfer.
- Middle School:Platform migration begins toward generalist social media.
- Teenagers:GDPR-K age thresholds relax, permitting limited profiling.
Early childhood dominates installed base. Preschool inventory is gaining share fastest.
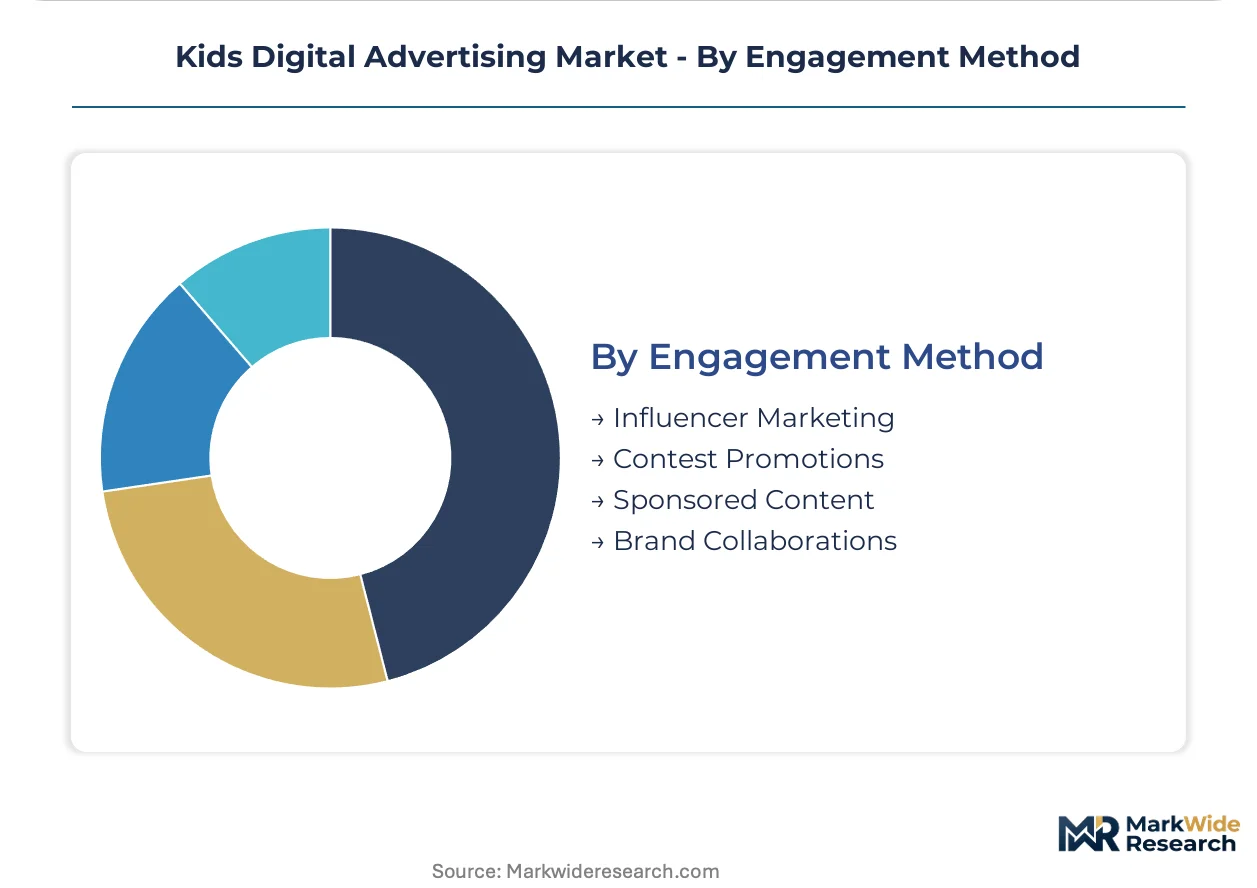
Engagement Method:
Agency involvement varies by method, with influencer marketing requiring specialized talent representation and sponsored content permitting direct publisher relationships.
- Influencer Marketing:FTC disclosure requirements extend to child-directed content. YouTube family vloggers and TikTok creators in the United States maintain compliance through #ad tagging and scripted integration disclosures.
- Sponsored Content:Native formats on educational platforms bypass ad-blocking. China's minors-protection provisions restrict commercial messaging in curriculum-aligned environments, forcing subtle brand integration.
- Brand Collaborations:Entertainment studio partnerships dominate.
- Contest Promotions:Sweepstakes mechanics face parental consent gates.
Sponsored content dominates installed base. Influencer marketing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Entertainment studios and toy manufacturers concentrate their digital advertising procurement in markets with established COPPA-equivalent frameworks and high connected-TV penetration. These buyer archetypes prioritize regulatory clarity over audience scale, directing spend toward jurisdictions with documented compliance precedents.
United States
Disney, Mattel, and Nickelodeon parent Paramount anchor demand through family-safe YouTube channels and streaming ad tiers. The FTC enforces COPPA penalties that shape publisher investments in verifiable parental consent infrastructure. Los Angeles and New York media clusters host specialized youth marketing agencies that bridge brand-direct and programmatic buying workflows.
United Kingdom
BBC Studios and ITV Commercial command inventory across educational platforms and children's streaming services with inherent parental trust transfer. The Information Commissioner's Office administers GDPR-K enforcement, accelerating age-estimation technology deployment among London-based ad-tech vendors. Manchester and Bristol house independent game studios pioneering COPPA-compliant interactive ad formats for preschool segments.
China
Tencent Video and iQiyi monetize family account structures through hybrid subscription-advertising tiers targeting entertainment studios and domestic toy brands. SAMR and MIIT administer parallel minors-protection provisions that restrict ad frequency and content categories for users under eighteen. Beijing and Shenzhen clusters concentrate SDK-based mediation layers that enable compliant monetization for independent mobile developers.
Germany
RTL Deutschland and ProSiebenSat.1 Media SE compete for toy manufacturer budgets through connected-TV inventory with household-level addressability. The KJM and state media authorities interpret GDPR-K provisions strictly, forcing platforms to default to non-profiling delivery without verifiable age verification. Hamburg and Cologne ad-tech hubs specialize in contextual intelligence engines that infer audience composition without user-level tracking.
Japan
TV Tokyo and Nippon Television Holdings integrate brand messaging into curriculum-aligned digital content environments with extended session duration. METI guidelines on minors' digital engagement shape platform investments in parental oversight tools and transparent algorithmic documentation. Tokyo's Shibuya and Roppongi districts concentrate influencer marketing agencies representing YouTube family vloggers with FTC-equivalent disclosure compliance.
Kids Digital Advertising Market Competitive Environment
Channel-controlling players compete with product-specialist players for inventory access and advertiser relationships. The market structures around three tiers: demand-side platforms with self-serve interfaces, SDK-based mediation specialists, and content-integrated walled gardens. Consolidation pressure operates on the demand-side tier while fragmentation persists among compliance-technology vendors. Dominant competitive moves include programmatic infrastructure partnerships and contextual targeting capability acquisitions.
Within the walled-garden tier, Google LLC and Meta Platforms Inc. anchor demand aggregation across family-safe video and messaging environments. KIDOZ Inc. occupies a specialist position exemplifying SDK-based COPPA-compliant mediation for independent mobile publishers. These three entities represent distinct strategic archetypes: horizontal platform dominance, vertical content integration, and regulatory-technology specialization.
| Leading Market Players |
|---|
| Microsoft Corporation |
| KIDOZ Inc. |
| Adobe Inc. |
| Blue Wheel Media LLC |
| AppLovin Corporation |
| Amazon.com Inc. |
| Meta Platforms Inc. |
| SuperAwesome |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
COPPA-mandated parental consent infrastructure acts as a regulatory chokepoint that compresses pricing spreads between premium programmatic tiers and remnant inventory while simultaneously forcing supply chain consolidation around compliant technology vendors. This compliance burden reshapes both how publishers monetize child-facing content and which mediation layers capture value across the ecosystem.
Pricing Analysis
Cost-plus contracts with indexation to FTC enforcement activity and GDPR-K audit frequency dominate publisher-advertiser agreements. Three-tier pricing structure across premium, standard, and economy levels separates COPPA-certified interactive formats from contextual video and basic display remnant. Price differentiation hinges on verifiable consent infrastructure investment and brand safety certification tier. Cost compression in the economy tier is intensifying because independent developers face fixed compliance costs that do not scale with impression volume. Mid-tier educational platforms exhibit the highest price sensitivity, while entertainment studios purchasing connected-TV inventory demonstrate the lowest.
Supply Chain Analysis
Contract manufacturing concentration among KIDOZ, SuperAwesome, and Google LLC's AdMob division holds the majority of SDK-based mediation capacity for COPPA-compliant mobile inventory. Supply concentrates in the United States, the United Kingdom, and China as these jurisdictions maintain documented compliance precedents that attract advertiser procurement. Raw material dependencies include age-estimation machine learning models, contextual intelligence engines, and parental verification API services. Single-source vulnerability around Google's demand-side platform dominance creates gatekeeper risk for inventory access and pricing transparency. Distribution runs through programmatic exchanges with self-serve interfaces that compress sales cycles and disintermediate traditional agency relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution by privacy-preserving contextual engines that displace behavioral infrastructure, as zero-data personalization technologies threaten to commoditize compliant ad mediation.
For Market Incumbents: Insulate proprietary demand-side platform relationships through exclusive inventory partnerships with family-safe YouTube channels and streaming services. Deepen investment in age-estimation engineering talent pools to maintain technical differentiation against emerging contextual intelligence vendors. Vertical integration into parental consent verification infrastructure reduces exposure to third-party API pricing volatility. For New Entrants and Emerging Players: Curriculum-aligned educational platforms in the United Kingdom and China represent the most penetrable entry point for compliant inventory aggregation. Independent mobile game developers in Manchester and Bristol offer underserved supply that lacks dedicated sales teams. A go-to-market angle emphasizing outcome-based pricing with self-serve interfaces bypasses incumbent agency relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory-technology specialists with documented COPPA and GDPR-K compliance architectures. Long-term viability rests on jurisdictional diversification across three regulatory frameworks to reduce single-market enforcement risk. The signal to watch is FTC penalty frequency against major platforms as an indicator of compliance cost inflation.| Strategic Initiative | Industry Significance |
|---|---|
| Contextual Intelligence Acquisition | Purchasing NLP engines from London ad-tech vendors accelerates zero-data personalization capability. |
| Educational Platform Partnership | Curriculum-aligned integrations with BBC Studios properties transfer parental trust to brand messaging. |
| Connected-TV Inventory Expansion | Disney+ and Netflix family tier access captures household-level addressability without individual tracking. |
| Age-Estimation Technology Licensing | Machine-learning systems from Berlin vendors enable compliant delivery across GDPR-K jurisdictions. |
| Self-Serve Interface Development | Programmatic tools for direct toy manufacturer relationships disintermediate youth marketing agencies. |
Study Parameters
Cross-validation between primary interviews with ad-tech executives and secondary validation through SEC filings and programmatic platform disclosures anchors the qualitative findings. The research combined discussions with demand-side platform product managers, COPPA compliance officers at mobile publishers, brand safety verification engineers, and youth marketing agency directors. Secondary sources included FTC enforcement records, ICO GDPR-K guidance documents, SAMR minors-protection provisions, and programmatic exchange volume disclosures. Bottom-up triangulation across SDK installation data and top-down advertiser spend estimates calibrated market sizing.
Calibration against historical enforcement cycles and platform policy shifts shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform type, content format, target age group, and engagement method alongside regulatory jurisdiction cluster. CAGRs were derived from impression volume growth trajectories and effective CPM evolution patterns. Industry-specific forecast inputs encompassed streaming service subscriber migration to ad-supported tiers and mobile app session duration compression under China's MIIT restrictions.
Practitioners should monitor FTC penalty announcements, GDPR-K audit frequency, and SAMR content restriction updates for early signals of compliance cost inflation. Forecasts reflect assumptions regarding regulatory stability and platform policy continuity that could shift with enforcement intensity. Quarterly review of programmatic inventory availability and age-estimation technology deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
China OOH and DOOH Market