
 South East Asia Advertising Market | 2026-2036
South East Asia Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Advertising Market Analytics
Indonesia's expanding mobile-first consumer base is realigning how agencies structure media planning across the archipelago. Publicis Groupe SA leverages its integrated creative and media capabilities to anchor large FMCG accounts throughout Jakarta and Manila. Dentsu International Asia Pte. Ltd. sustains deep relationships with Japanese automotive and electronics brands seeking localized campaigns. GroupM Asia Pacific Holdings Ltd. dominates programmatic buying infrastructure, giving it disproportionate influence over inventory access.
Advertising in South East Asia encompasses paid, non-personal communication transmitted through broadcast, print, outdoor, and digital channels to influence audience behavior or brand preference. The discipline relies on audience segmentation algorithms, impression attribution models, and cross-platform frequency management to optimize return on ad spend. Digital medium spending now leads regional growth as mobile penetration exceeds fixed broadband access across Indonesia, Philippines, and Vietnam. Video content type commands premium CPMs because completion rates on short-form platforms outpace static display formats. SME client type segments represent the fastest-growing demand pool as self-serve ad platforms lower minimum spend thresholds.
Singapore's Personal Data Protection Commission enforces consent requirements that constrain third-party data deployment for audience targeting. Thailand's Personal Data Protection Act and Indonesia's forthcoming data protection regulations add compliance layers to cross-border campaign execution. Vietnam's Ministry of Information and Communications monitors foreign platform content licensing, affecting where multinational advertisers place inventory. Stakeholders must track which regulatory framework gains enforcement priority as data localization mandates proliferate.
Market Dynamics
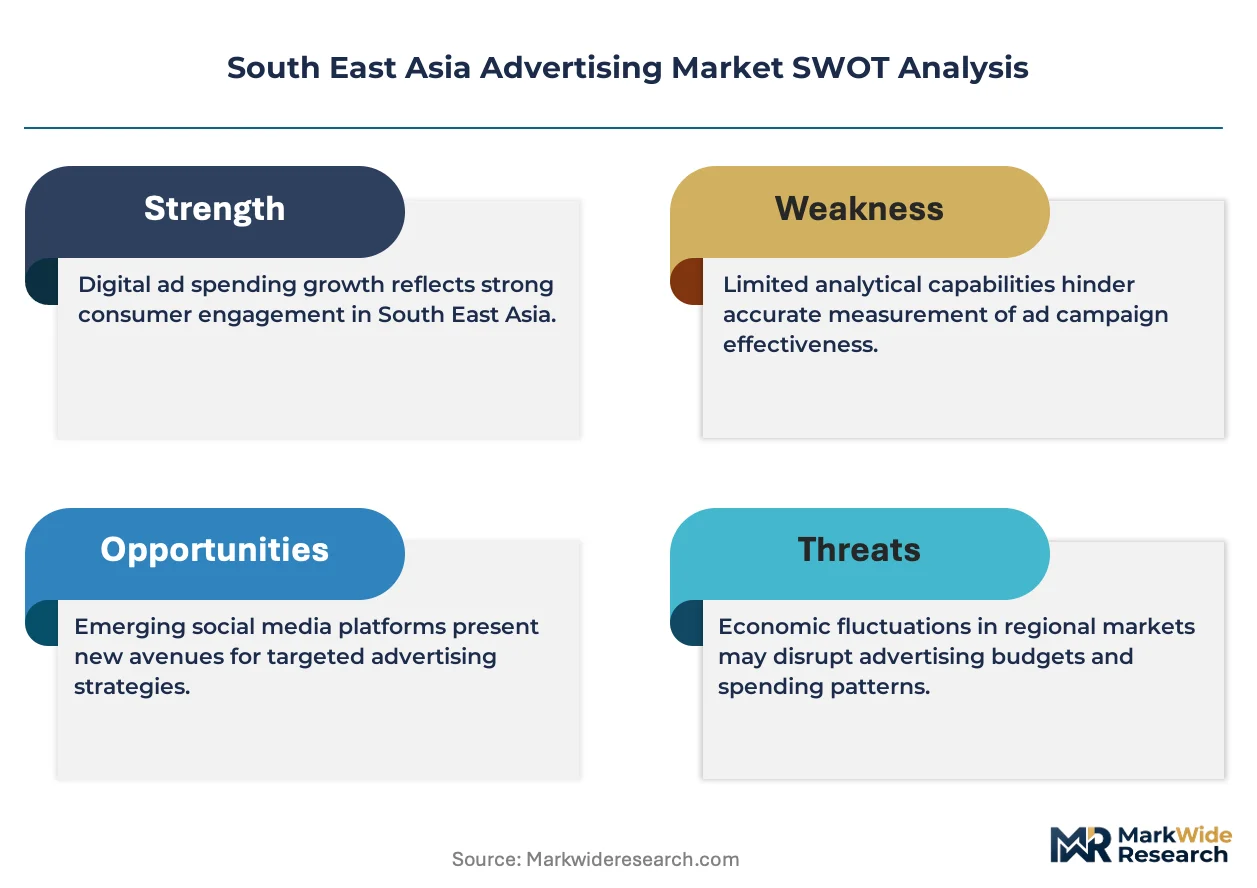
Mobile-first audience migration across Indonesia, Philippines, and Vietnam is compressing media planning cycles and forcing agencies to rebuild attribution models around platform-native ecosystems rather than traditional broadcast-centric frameworks.
Growth Catalysts
- Short-form video infrastructure:TikTok and YouTube Shorts are capturing disproportionate attention minutes among 18-34 demographics in Bangkok and Jakarta, pulling FMCG ad budgets from static display formats.
- Singapore's PDPC consent framework:First-party data strategies are gaining investment priority as third-party targeting faces enforcement tightening, advantaging publishers with direct subscriber relationships.
- Self-serve programmatic platforms:Meta Ads Manager and Google Ads are lowering minimum spend thresholds, enabling SME participation in previously agency-dominated inventory auctions across Ho Chi Minh City and Manila.
Market Restraints
- Cross-border data friction:Thailand's Personal Data Protection Act and Indonesia's pending regulations are adding compliance layers to regional campaign execution, extending legal review timelines.
- Platform concentration risk:Meta and Google capture dominant shares of programmatic demand in Jakarta, Bangkok, and Ho Chi Minh City, constraining buyer negotiation leverage on CPM pricing.
- Attribution opacity:Walled garden measurement standards prevent unified cross-platform frequency management, forcing advertisers to over-allocate to duplicate reach.
Strategic Opportunities
- Retail media networks:Shopee and Lazada are building closed-loop ad products linking search to purchase, creating closed attribution systems unavailable to traditional publishers.
- Vietnam's emerging tier-two cities:Da Nang and Can Tho present underpenetrated demand as e-commerce logistics networks extend beyond Ho Chi Minh City and Hanoi.
- AI-generated creative adaptation:Generative tools are converging with dynamic creative optimization to enable real-time localization of global brand assets for Bahasa Indonesia and Thai language markets.
Industry Challenges
- Measurement standardization gaps:MRC-accredited viewability vendors remain scarce across Southeast Asia, forcing advertisers to accept platform-reported metrics without independent verification.
- Privacy-preserving targeting skills:Agency talent pools lack depth in contextual and cohort-based alternatives to cookie-dependent audience building, slowing campaign deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Advertising Market |
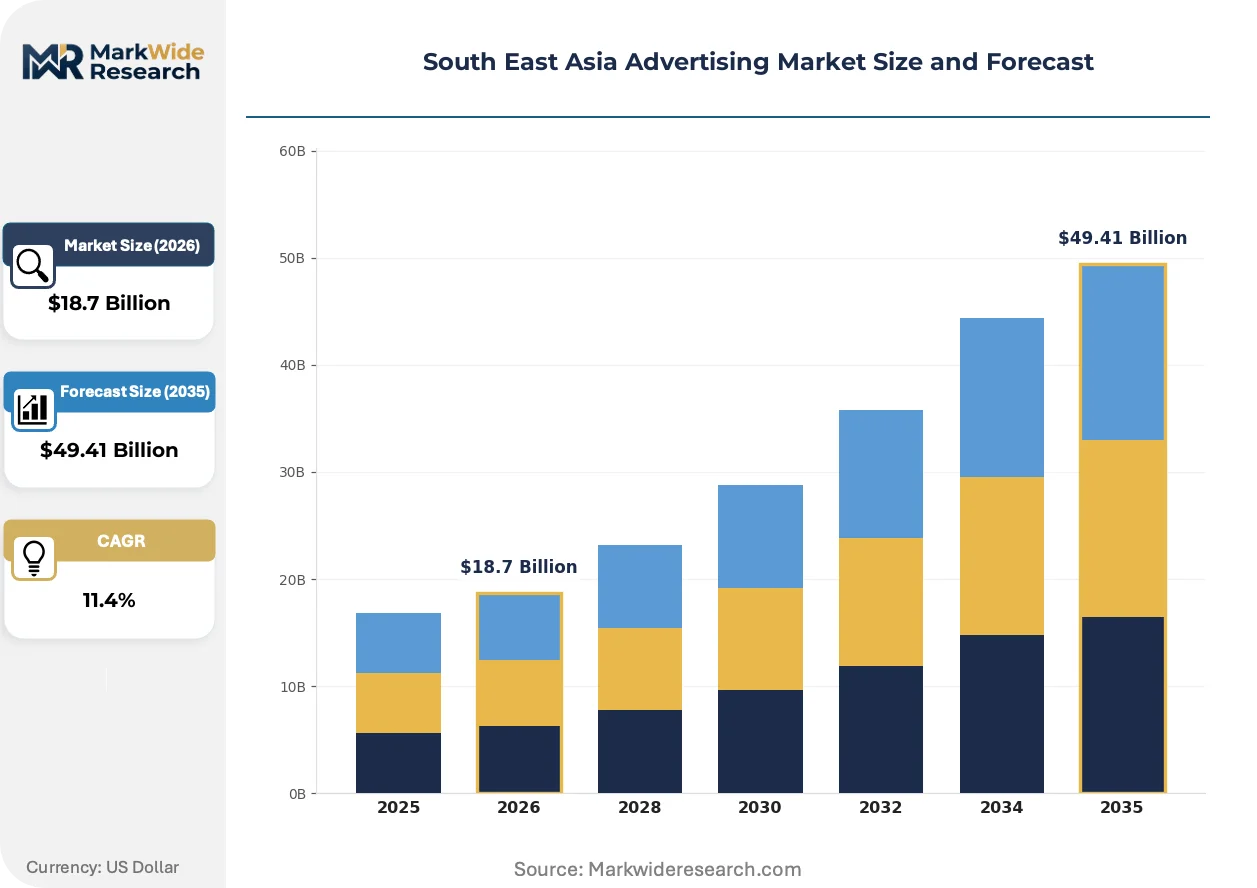
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium: Digital, Print, Television, Radio Client Type: SMEs, Corporates, Startups, Nonprofits Content Type: Video, Graphics, Articles, Infographics Objective: Brand Awareness, Lead Generation, Customer Engagement, Direct Sales |
| Companies Covered | Publicis Groupe SA, GVN Marketing, Dentsu International Asia Pte. Ltd., Smartly.io, Mutant Communications, GroupM Asia Pacific Holdings Ltd., Havas Media Asia Pacific Pte. Ltd., FirstPage Digital, Omnicom Media Group Asia Pacific Pte. Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Advertising Market Evolving Landscape
Artificial intelligence is compressing production timelines and enabling real-time creative adaptation at scale, while regulatory fragmentation forces architectural decisions that favor first-party data infrastructure over third-party dependencies.
Programmatic buying infrastructure is automating manual insertion order workflows and audience segment building that previously required dedicated trading desk staffing. Mid-market advertisers in Thailand and Malaysia are adopting these self-serve interfaces faster than traditional agency-held accounts, collapsing the service layer between demand and supply. This compression is reallocating agency value toward strategic planning and away from execution.
Singapore's Personal Data Protection Commission is enforcing consent requirements that constrain third-party data deployment for audience targeting. Industrial consequence includes mandatory opt-in frameworks for retargeting campaigns and heightened documentation burdens for cross-border data transfers. Multinational advertisers operating regional hubs from Singapore are responding by consolidating first-party data collection through owned-and-operated properties.
Direct platform relationships are displacing traditional media agency intermediation among performance-focused advertisers in Indonesia and Vietnam. SME segments are bypassing retainer-based agency contracts to manage campaigns through native Meta and Google interfaces, compressing service fees and forcing agencies to reposition around creative and analytics capabilities. This shift is most visible in Jakarta's DTC e-commerce vertical, where brands prioritize speed-to-market over strategic counsel.
South East Asia Advertising Market Segmentation
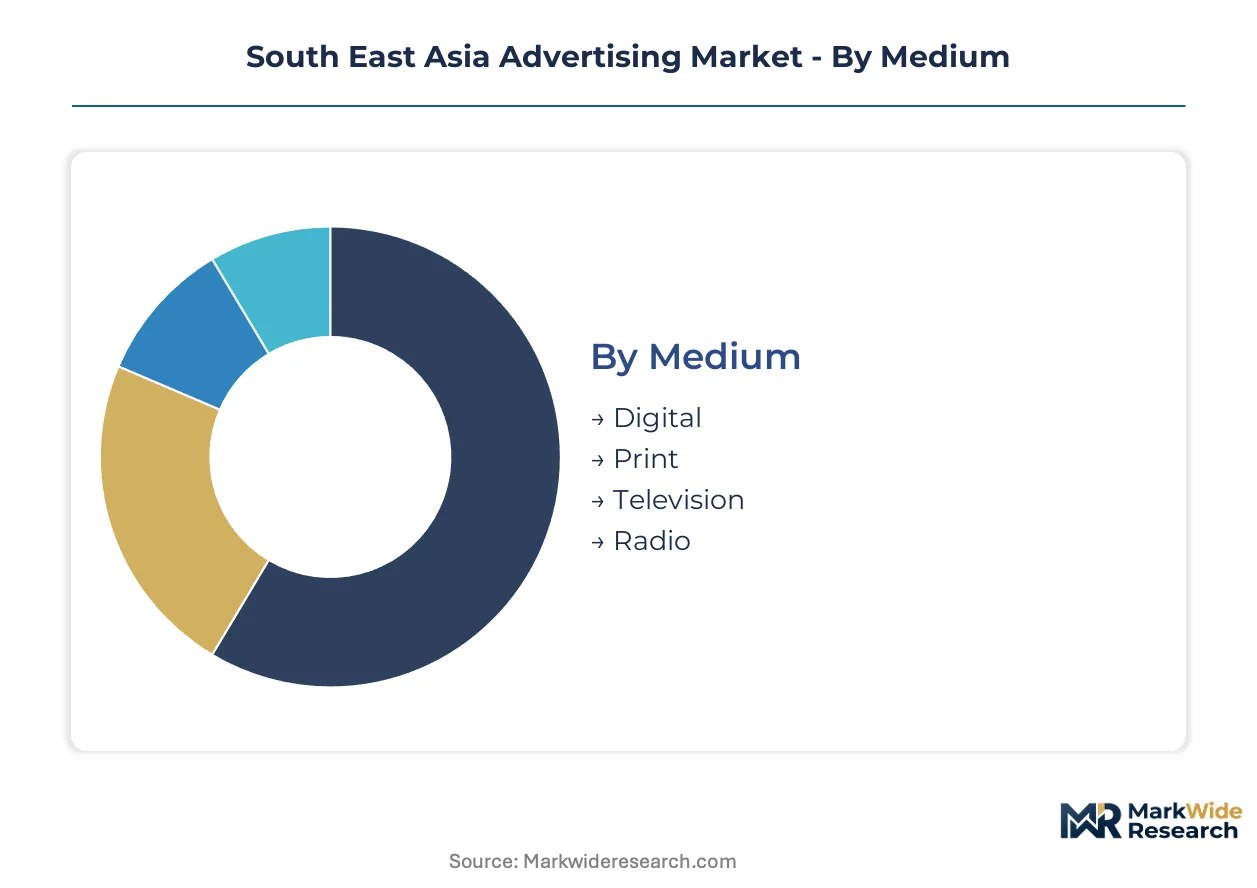
Advertising spend allocation across South East Asia follows distinct patterns shaped by platform infrastructure maturity and regulatory compliance burdens. Advertisers segment budgets by medium accessibility, client sophistication, content production capabilities, and measurable outcome requirements.
Medium:
Digital inventory requires Singapore PDPC consent documentation for retargeting campaigns, while broadcast television demands national licensing from Indonesia's Ministry of Communication and Information Technology and Vietnam's Ministry of Information and Communications. Print and radio face lighter compliance loads but carry distribution infrastructure constraints.
- Digital:Programmatic buying infrastructure concentrates demand in Jakarta, Bangkok, and Ho Chi Minh City, with mobile-first formats capturing disproportionate attention minutes among 18-34 demographics. Self-serve platforms are lowering minimum spend thresholds, enabling SME participation in previously agency-dominated auctions.
- Television:National broadcast licensing requirements from Indonesia's Kominfo and Vietnam's MIC create regulatory moats protecting incumbent inventory holders. Prime-time slots in Metro Manila and Greater Jakarta command premium rates despite audience fragmentation to streaming alternatives.
- Print:Newspaper and magazine advertising retains relevance in Malaysia's bilingual markets and Thailand's provincial dailies where digital penetration lags urban centers. Production lead times exceed digital formats by orders of magnitude.
- Radio:Commuter-hour programming in Metro Manila and Jakarta sustains listenership for FMCG advertisers targeting lower-income demographics. Hyper-local station networks enable geographic precision unavailable to national broadcasters.
Leading the category by volume: Digital. Growing fastest: Digital.
Client Type:
Budget thresholds and in-house capability depth separate client segments, with compliance documentation burdens scaling disproportionately for cross-border campaign execution.
- SMEs:Self-serve ad platforms through Meta Ads Manager and Google Ads are collapsing the service layer between demand and supply, compressing agency retainer fees. DTC e-commerce brands in Jakarta prioritize speed-to-market over strategic counsel.
- Corporates:FMCG and automotive multinationals anchor large accounts requiring integrated creative and media capabilities across Jakarta and Manila. First-party data infrastructure investment is gaining priority as third-party targeting faces enforcement tightening.
- Startups:Venture-backed technology companies in Singapore and Ho Chi Minh City allocate aggressively to performance marketing with direct response metrics. Attribution opacity across walled gardens forces over-allocation to duplicate reach.
- Nonprofits:Donor acquisition campaigns rely on donated inventory and pro-bono agency support, constraining creative production quality. Singapore's PDPC consent frameworks apply equally to charitable solicitations.
Volume concentration: Corporates. Steepest expansion trajectory: SMEs.
Content Type:
Production cost structures and platform algorithm preferences are resegmenting creative investment, with generative tools compressing localization timelines for Bahasa Indonesia and Thai language markets.
- Video:Short-form completion rates on TikTok and YouTube Shorts outpace static display formats, commanding premium CPMs in Bangkok and Jakarta. AI-generated creative adaptation enables real-time localization of global brand assets.
- Graphics:Display banners and social statics retain utility in retargeting funnels where production speed outweighs engagement depth. Dynamic creative optimization automates variant testing previously requiring manual trafficking.
- Articles:Native content partnerships with publisher direct relationships bypass third-party data dependencies constrained by Thailand's Personal Data Protection Act. SEO-integrated editorial requires longer activation timelines than paid formats.
- Infographics:Data visualization formats concentrate in B2B verticals and financial services advertising where complexity simplification drives engagement. Production costs sit between static graphics and full video.
Revenue share leader: Video. Gaining share fastest: Video.
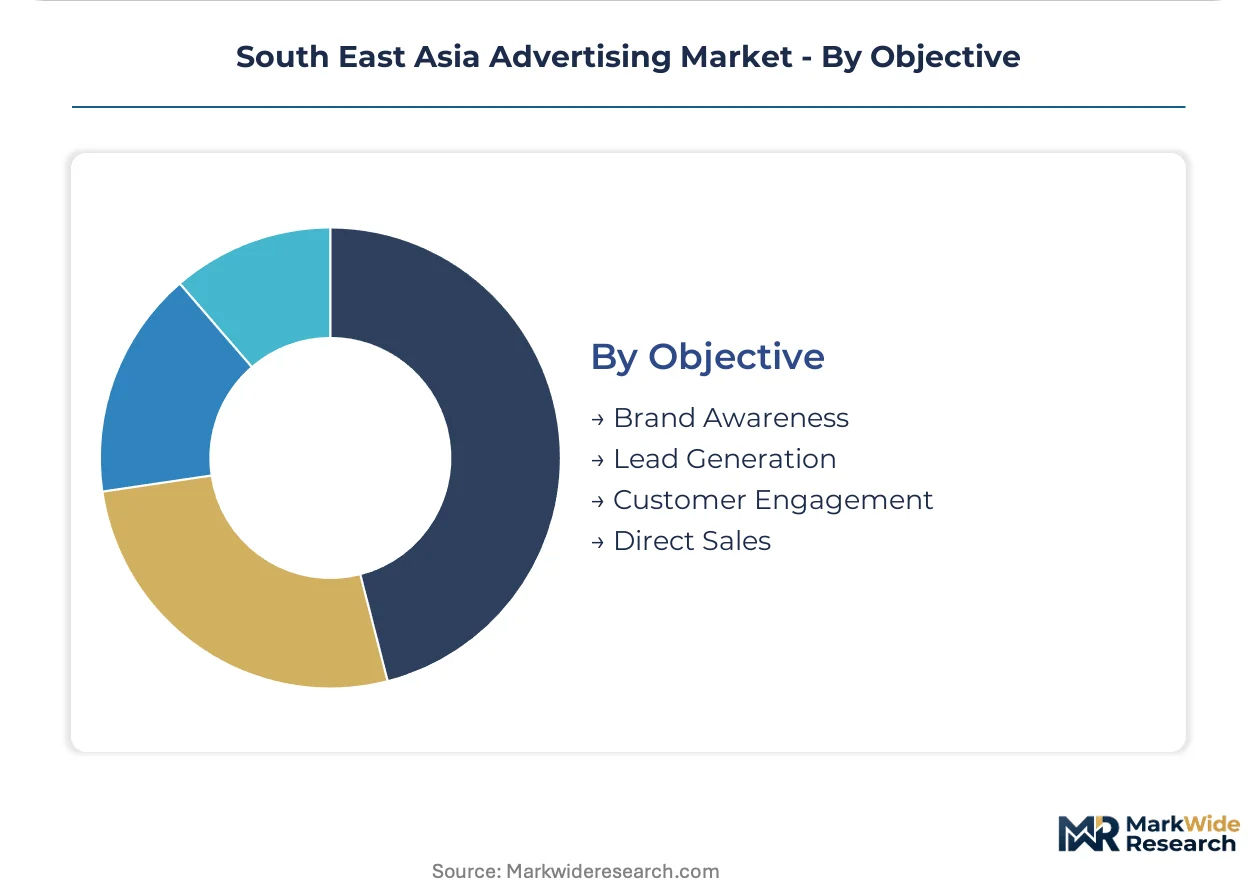
Objective:
Measurement standardization gaps force advertisers to accept platform-reported metrics without independent verification, with MRC-accredited viewability vendors remaining scarce across Southeast Asia.
- Brand Awareness:Reach and frequency planning requires cross-platform frequency management tools unavailable in walled garden environments. Retail media networks on Shopee and Lazada are building closed-loop ad products linking search to purchase.
- Lead Generation:Form-fill and call-to-action campaigns concentrate in real estate, education, and financial services verticals. First-party data collection through owned-and-operated properties responds to Singapore PDPC consent requirements.
- Customer Engagement:Community management and retention marketing leverage platform-native ecosystems rather than traditional broadcast-centric frameworks. Agency talent pools lack depth in contextual and cohort-based alternatives to cookie-dependent audience building.
- Direct Sales:Performance advertisers in Indonesia and Vietnam are bypassing retainer-based agency contracts to manage campaigns through native Meta and Google interfaces. Attribution to purchase requires closed systems unavailable to traditional publishers.
Current spend majority: Brand Awareness. Expanding most quickly: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta's mobile-first consumer base anchors regional advertising demand as Indonesia's archipelago geography reshapes media distribution economics across Southeast Asia.
Indonesia
Mobile penetration exceeding fixed broadband access compresses media planning cycles around platform-native ecosystems. Kominfo's national broadcast licensing requirements create regulatory moats protecting incumbent television inventory holders. Greater Jakarta concentrates programmatic buying infrastructure as e-commerce platforms expand ad budgets aggressively.
Singapore
Regional hub operations for multinational advertisers drive first-party data infrastructure investment as third-party targeting faces enforcement tightening. The Personal Data Protection Commission mandates opt-in frameworks for retargeting campaigns and heightened documentation burdens for cross-border data transfers. Marina Bay financial district hosts consolidated data operations responding to consent requirements.
Thailand
Bangkok's 18-34 demographics pull FMCG ad budgets toward short-form video formats on TikTok and YouTube Shorts. The Personal Data Protection Act adds compliance layers to regional campaign execution, extending legal review timelines. Metro Bangkok dominates inventory concentration while provincial dailies retain print relevance where digital penetration lags.
Vietnam
Ho Chi Minh City and Hanoi anchor programmatic demand as the Ministry of Information and Communications monitors foreign platform content licensing. E-commerce logistics networks extending to Da Nang and Can Tho present underpenetrated demand pools. Direct platform relationships displace traditional agency intermediation among performance-focused advertisers.
Malaysia
Bilingual markets sustain newspaper advertising relevance alongside digital migration. The Personal Data Protection Act tightens consent frameworks for targeted advertising, constraining third-party data deployment. Kuala Lumpur concentrates corporate headquarters activity while provincial radio networks enable geographic precision for FMCG advertisers.
South East Asia Advertising Market Competitive Landscape
Global majors compete with regional champions across creative capabilities and programmatic infrastructure, producing a tiered structure where integrated networks hold large FMCG accounts while specialized boutiques capture performance marketing segments. Three archetypes dominate: full-service holding companies with media-buying scale, creative-led independents with localization depth, and technology-enabled specialists in self-serve platforms. Consolidation through strategic partnerships and first-party data infrastructure investment represent the dominant competitive vectors.
Within the holding company tier, Publicis Groupe SA and Dentsu International Asia Pte. Ltd. exemplify integrated creative and media capabilities anchoring multinational accounts across Jakarta and Manila. GroupM Asia Pacific Holdings Ltd. occupies a position defining programmatic buying infrastructure and inventory access influence. Among technology-enabled specialists, Smartly.io represents the automation archetype compressing manual workflows for mid-market advertisers.
| Leading Market Players |
|---|
| Publicis Groupe SA |
| GVN Marketing |
| Dentsu International Asia Pte. Ltd. |
| Smartly.io |
| Mutant Communications |
| GroupM Asia Pacific Holdings Ltd. |
| Havas Media Asia Pacific Pte. Ltd. |
| FirstPage Digital |
| Omnicom Media Group Asia Pacific Pte. Ltd. |
| Others |
Value Network & Pricing Analysis
Agency-retainer versus self-serve platform divergence bifurcates South East Asia advertising procurement, with bundled strategic services commanding premium positioning in Jakarta and Manila while unbundled execution-only tiers compress margins through direct Meta and Google interfaces. This tier separation manifests in supply chain configurations where full-service networks anchor multinational FMCG accounts through integrated creative-media capabilities, and automated platforms disintermediate traditional trading desks across Ho Chi Minh City and Bangkok.
Pricing Analysis
Warranty-equivalent service bundling separates premium agency retainers from unbundled self-serve alternatives, with strategic planning and creative adaptation included in corporate contracts but stripped out for SME direct platform access. Pricing stratifies across premium full-service, mid-tier hybrid, and economy self-serve levels based on creative customization depth and compliance documentation burden. Cost compression in the self-serve tier intensifies as Meta Ads Manager and Google Ads lower minimum spend thresholds, eroding agency execution fees. SMEs exhibit highest price sensitivity, prioritizing speed-to-market over strategic counsel, while corporates accept premium positioning for integrated cross-market campaign management.
Supply Chain Analysis
Direct-to-advertiser channels handle performance-marketing demand in Indonesia and Vietnam, while agency-mediated pathways retain multinational corporate accounts across Singapore and Thailand. Supply concentrates in Indonesia, Singapore, and Vietnam as programmatic infrastructure anchors in Jakarta, Marina Bay, and Ho Chi Minh City. Raw material dependencies include creative production talent, first-party data infrastructure, and platform API access. Single-source vulnerability runs through Meta and Google's dominant programmatic demand share, constraining buyer negotiation leverage. Distribution runs through holding company networks, independent creative boutiques, and technology-enabled self-serve specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial intelligence-generated creative adaptation is displacing manual localization workflows, compressing production timelines for Bahasa Indonesia and Thai language markets while forcing architectural investment in generative infrastructure.
For Market Incumbents: To counter self-serve platform disintermediation, Publicis Groupe SA and Dentsu International must deepen first-party data infrastructure investment responding to Singapore PDPC consent tightening, while consolidating creative-media integration around AI-powered localization capabilities that automated platforms cannot replicate. For New Entrants and Emerging Players: Technology-first programmatic specialization offers entry into underpenetrated retail media networks on Shopee and Lazada, where closed-loop attribution systems remain unavailable to traditional publishers. Target Vietnam's tier-two cities of Da Nang and Can Tho as e-commerce logistics extend beyond Ho Chi Minh City and Hanoi. Lead with performance-marketing analytics capabilities rather than creative production scale. For Investors and Strategic Acquirers: Re-rating potential sits with first-party data infrastructure specialists given Singapore PDPC enforcement tightening and Thailand's Personal Data Protection Act compliance layers. Long-term viability favors agencies with direct subscriber publisher relationships and owned-and-operated property networks. Watch for inflection in MRC-accredited viewability vendor penetration across Southeast Asia as signal of measurement standardization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Investment | Direct subscriber relationships bypass Singapore PDPC constraints on third-party targeting deployment. |
| AI-Powered Creative Localization | Generative tools compress Bahasa Indonesia and Thai adaptation timelines for real-time campaign deployment. |
| Retail Media Network Partnership | Shopee and Lazada closed-loop systems offer attribution unavailable to traditional programmatic publishers. |
| Self-Serve Platform Capability Build | Automated interfaces capture SME segments bypassing agency retainer contracts in Jakarta and Manila. |
| Cross-Border Compliance Architecture | Unified frameworks address Thailand's PDPA and Indonesia's pending data protection regulatory layers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with media agency executives, brand marketing directors, platform partnership leads, and programmatic trading desk operators. Secondary sources included Singapore PDPC enforcement notices, Thailand PDPA compliance guidance, Indonesia Kominfo licensing databases, and e-commerce platform advertising revenue disclosures. Bottom-up segment sizing and top-down macro validation triangulated market estimates across the analysis window.
Data-stream reconciliation integrated spend allocation patterns by medium, client type, content format, and campaign objective with mobile penetration metrics and platform-native ecosystem adoption curves. Segmentation dimensions modeled included digital-television-print-radio medium splits, SME-corporate-startup-nonprofit client archetypes, video-graphics-articles-infographics content types, and brand awareness-lead generation-engagement-direct sales objectives. CAGRs derived from trend extrapolation of self-serve platform adoption and regulatory compliance cost trajectories.
Several conditions sit outside the modeled scope, including sudden platform algorithm changes affecting attribution models, geopolitical disruptions to cross-border data flows, and accelerated regulatory fragmentation beyond current PDPA and PDPC frameworks. Forecasts reflect documented assumptions around mobile-first audience migration continuity and short-form video attention capture sustainability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Philippines OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertising Platform Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
Global Advertising Agency Software Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
North America Programmatic Advertisement Market