
 United Kingdom Marketing Agencies Market | 2026-2036
United Kingdom Marketing Agencies Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Marketing Agencies Market Insights
The capability gap between data-asset-heavy networks and creative boutiques is unwinding traditional competitive moats in the United Kingdom marketing agencies landscape. WPP plc leverages its global data infrastructure to anchor enterprise accounts across London's financial district. Wieden + Kennedy competes through creative specialization, sustaining premium positioning with brand storytelling that commands higher retainer rates.
United Kingdom marketing agencies comprise professional service firms that strategize, produce, and distribute promotional content across paid, owned, and earned media channels, typically operating through blended teams of account strategists, creative directors, media planners, and data analysts executing campaigns with measurable performance metrics. These entities primarily generate revenue through fee-based structures tied to media spend, project scope, or recurring strategic advisory, serving commercial organizations seeking to capture consumer attention in fragmented digital environments. Digital marketing services command the largest share of agency billings as clients redirect budgets from linear television toward programmatic display and social platforms. SEO and content creation represent faster-expanding service lines where specialized boutiques capture margin pools through technical expertise and subscription-based recurring revenue models.
The Advertising Standards Authority enforces the UK Code of Non-broadcast Advertising and Direct Promotional Marketing, restricting misleading claims and mandating disclosure of sponsored content across influencer channels. The Information Commissioner's Office applies GDPR-derived rules on consent and data processing, forcing agencies to restructure audience targeting practices and rebuild measurement frameworks around privacy-preserving methodologies. Stakeholders must monitor how the Digital Markets Competition and Consumers Bill reshapes platform-agency relationships and whether first-party data strategies become the decisive capability differentiator.
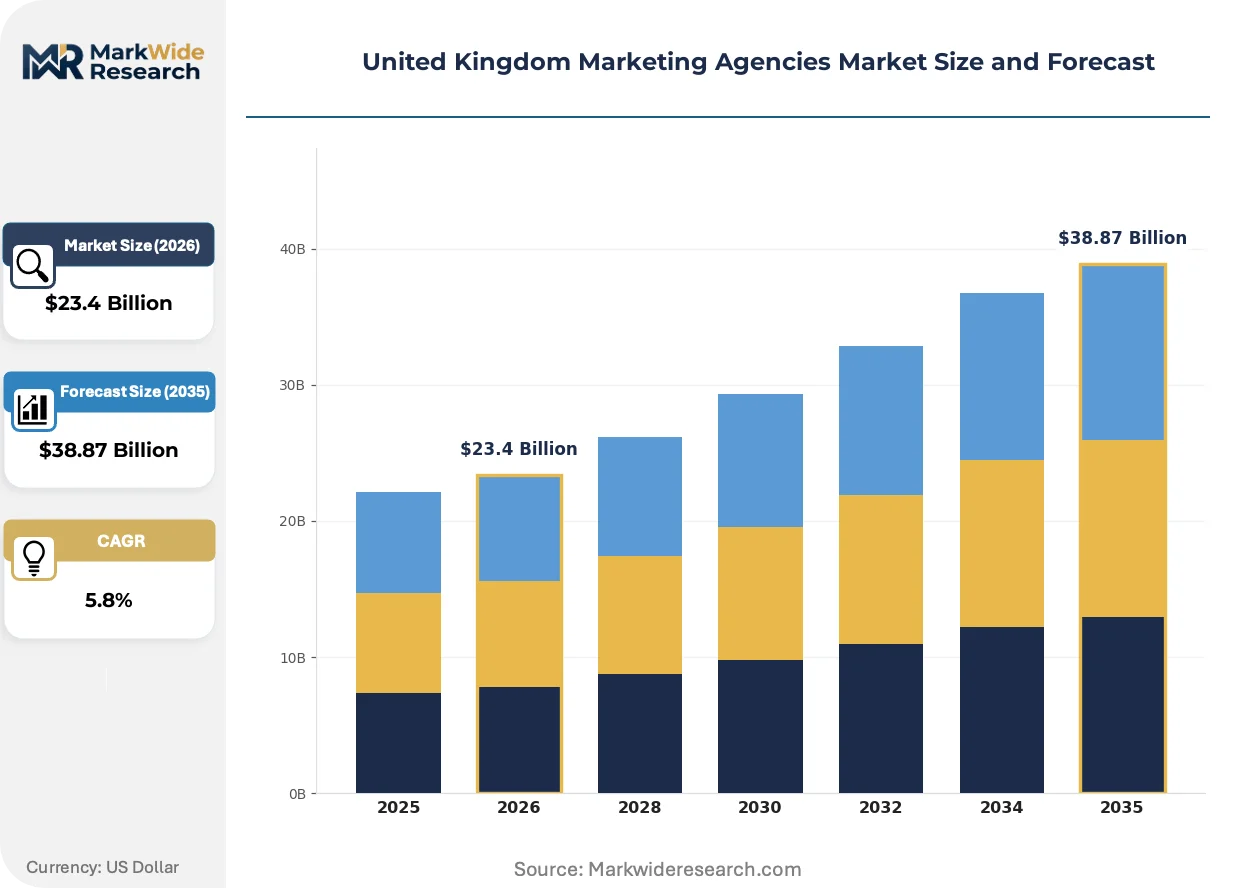
Market Dynamics
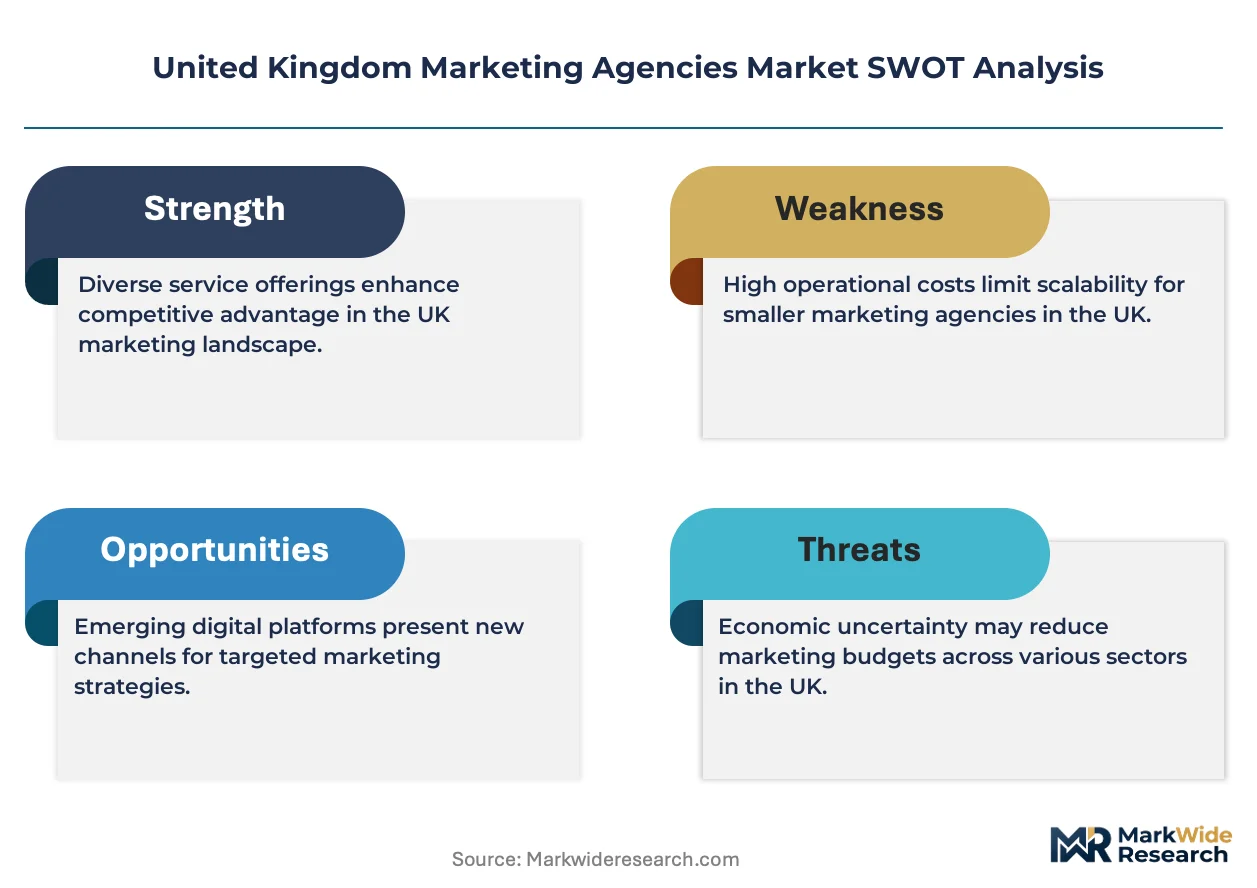
First-party data architectures are displacing third-party cookie dependencies across United Kingdom marketing agencies, forcing structural reinvestment in consent management infrastructure and privacy-preserving analytics stacks.
Growth Catalysts
- London fintech expansion:Venture-backed payment platforms and neobanks generate sustained demand for performance marketing and regulatory-compliant customer acquisition campaigns.
- GDPR Article 7 enforcement:Stricter consent validation requirements compel brands to outsource compliant audience targeting to specialized agencies with certified data governance frameworks.
- Programmatic audio:Streaming platforms and podcast networks open inventory pools that Manchester-based digital shops exploit for northern England e-commerce clients.
Market Restraints
- Platform concentration risk:Meta and Alphabet algorithm changes in Menlo Park and Mountain View throttle organic reach unpredictably, forcing budget reallocation without notice.
- Technical talent scarcity:Privacy engineering and server-side tagging expertise commands premium compensation that boutique agencies cannot match against network salary bands.
- Input cost inflation:Cloud infrastructure and martech SaaS subscriptions from US-domiciled vendors expose billings to sterling-dollar volatility and forced renewal pricing.
Strategic Opportunities
- Manchester media cluster expansion:Lower operational costs and proximity to Leeds-Bradford manufacturing bases attract brand headquarters relocations from London.
- AI-assisted creative production:Generative tools compress asset turnaround times for social campaigns, enabling fixed-fee models that improve margin capture.
- Online Safety Bill preparedness:Harmful content moderation mandates create advisory revenue streams as platforms and advertisers seek compliance interpretation.
Industry Challenges
- Server-side infrastructure migration:Client-side pixel deprecation demands capital investment in cloud tagging architectures that mid-size agencies lack balance sheet capacity to fund.
- Cross-functional talent integration:Data science, creative, and regulatory expertise rarely coexist in single practitioners, complicating team assembly for integrated accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Marketing Agencies Market |
| Market Size in 2026 | $23.4 Billion |
| Market Size in 2035 | $38.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Marketing, Content Creation, SEO, Branding Client Type: Startups, SMEs, Corporations, Nonprofits Delivery Model: Full-service, In-house, Freelance, Retainer Industry Vertical: E-commerce, Technology, Healthcare, Education |
| Companies Covered | WPP plc, Publicis Groupe SA, Omnicom Group Inc., The Interpublic Group of Companies Inc., Wieden + Kennedy, McCann, Croud, Open Partners, Impression, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Marketing Agencies Market Trends and Innovations
Generative workflows and privacy-preserving measurement are collapsing traditional production timelines and attribution models simultaneously. Agencies that restructure around these capabilities capture margin expansion while laggards face compression.
Generative image and video synthesis is fragmenting content production economics. Retail and direct-to-consumer brands in Birmingham and Bristol adopt these tools for rapid variant testing. The technology compresses creative retainer values while expanding volume-based output contracts.
The Advertising Standards Authority's enhanced influencer disclosure guidelines reshape campaign contracting. Mandatory paid-partnership labeling reduces organic engagement rates. Beauty and lifestyle verticals in London recast creator agreements around transparent compensation structures.
Outcome-based compensation structures displace fixed retainers in enterprise pitches. Procurement teams at financial services and telecom clients demand performance-linked fee components. This shift concentrates risk with agencies while transferring media efficiency accountability upstream.
United Kingdom Marketing Agencies Market Segmentation
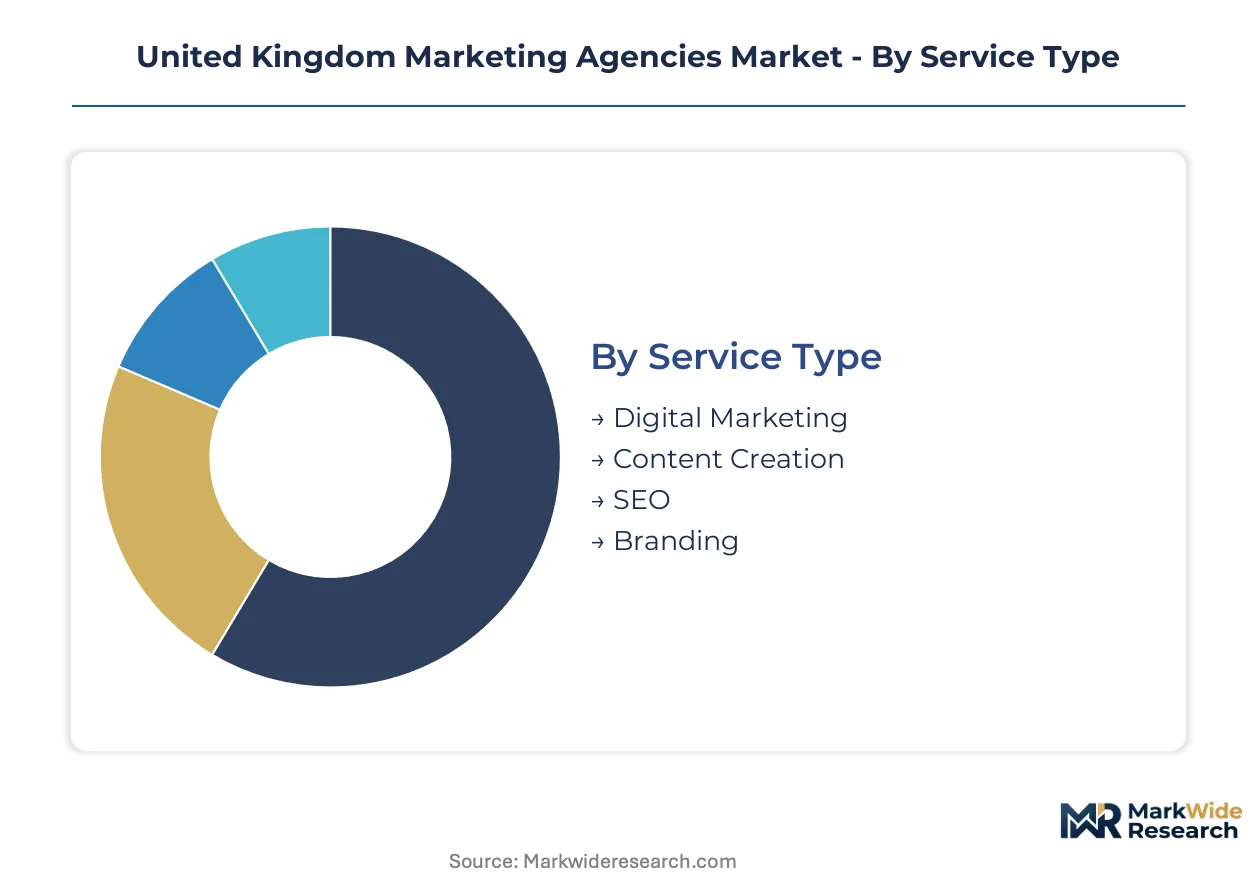
Segmentation in United Kingdom marketing agencies reveals how service specialization and client scale dictate operational models. London-based networks dominate enterprise retainers while Manchester and Bristol clusters capture mid-market digital work. Understanding these splits exposes where margin pools concentrate and which delivery structures attract capital investment.
Service Type:
Domestic demand concentrates in London and Manchester for performance-driven services, while content creation serves export-oriented clients seeking global brand consistency.
- Digital Marketing:Programmatic media buying, paid social, and conversion rate optimization form the technical core. Manchester agencies deploy these capabilities for northern England e-commerce clients facing platform concentration risk from Meta and Alphabet algorithm shifts. Digital marketing commands the established base.
- Content Creation:Video production, copywriting, and visual asset development operate through subscription and project-based contracts. Bristol and Birmingham studios serve direct-to-consumer brands adopting generative tools for rapid variant testing, compressing traditional creative retainer values while expanding volume-based output contracts.
- SEO:Technical site optimization and link-building services run through specialized boutiques with recurring revenue models.
- Branding:Strategic positioning and visual identity systems attract premium fees from London financial district clients.
Digital marketing commands the established base. The steepest expansion runs through SEO.
Client Type:
Cost tier stratification separates venture-backed startups on performance budgets from corporations with integrated agency rosters and compliance overhead.
- Startups:Venture-backed fintech and direct-to-consumer brands in London demand rapid customer acquisition with measurable unit economics. These clients prioritize performance-linked compensation structures that transfer media efficiency risk to agencies.
- SMEs:Regional manufacturers and professional services firms in Leeds-Bradford and Bristol rely on project-based engagements without dedicated marketing leadership. The steepest expansion runs through this segment as cloud-based tools democratize access to previously enterprise-only capabilities.
- Corporations:Financial services and telecom procurement teams mandate outcome-based fee components and certified data governance frameworks.
- Nonprofits:Charitable organizations access pro-bono and discounted services through agency social impact programs.
Corporations anchor revenue stability. Startups are gaining share fastest.
Delivery Model:
Volume concentration favors retainer relationships in London, while project-based freelance and in-house models expand in cost-sensitive regional markets.
- Full-service:Integrated strategy, creative, media, and analytics under single P&L structures. WPP plc and comparable networks leverage global data infrastructure to anchor these relationships across London's financial district, though server-side infrastructure migration demands capital investment mid-size competitors cannot fund.
- In-house:Embedded teams operating within client premises on long-term contracts. The steepest expansion runs through this model as GDPR Article 7 enforcement compels brands to outsource compliant audience targeting to specialized agencies with certified frameworks rather than building captive capabilities.
- Freelance:Individual practitioners and micro-collectives serving project-based demand without overhead recovery.
- Retainer:Fixed monthly fees for ongoing strategic advisory and campaign management, now pressured by outcome-based procurement demands.
Retainer structures retain the established base. In-house is expanding most quickly.
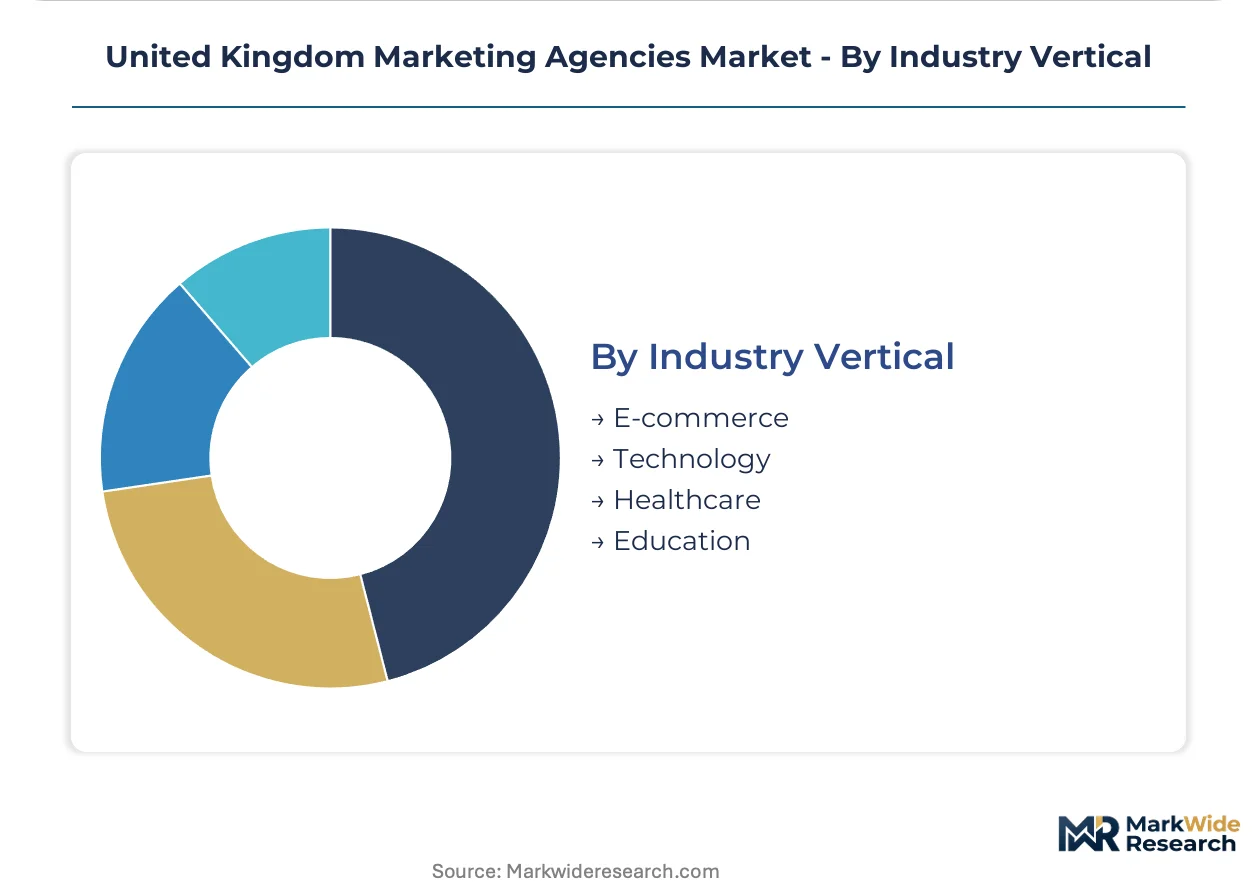
Industry Vertical:
Application concentration varies by regulatory exposure, with healthcare and education facing stricter compliance than technology and e-commerce.
- E-commerce:Direct-to-consumer retail brands in Birmingham and Manchester drive demand for programmatic display and social commerce optimization. These clients adopt generative image and video synthesis for rapid variant testing, fragmenting content production economics while expanding volume-based contracts.
- Technology:SaaS platforms and fintech startups require regulatory-compliant customer acquisition campaigns under Advertising Standards Authority guidelines. The steepest expansion runs through this vertical as London venture-backed payment platforms and neobanks generate sustained demand for performance marketing.
- Healthcare:Pharmaceutical and wellness brands navigate Information Commissioner's Office GDPR-derived consent rules and restricted promotional claims.
- Education:Universities and edtech providers compete for domestic and international student recruitment through digital channels.
E-commerce holds the revenue base. Technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom runs a services trade surplus in marketing and advertising, with London-based agencies exporting creative and strategic expertise to North American and Middle Eastern clients while importing specialized technology infrastructure and martech platforms primarily from US vendors.
London and the Southeast
Venture-backed fintech startups in Shoreditch and Canary Wharf drive demand for performance marketing and regulatory-compliant customer acquisition campaigns. The Advertising Standards Authority enforces the UK Code of Non-broadcast Advertising across influencer channels and paid social. WPP plc anchors enterprise relationships across the financial district with global data infrastructure.
North England
Manchester's media cluster serves e-commerce and technology clients with programmatic display and social commerce optimization. The Information Commissioner's Office applies GDPR-derived consent rules that reshape audience targeting practices. Leeds-Bradford manufacturing bases attract brand headquarters relocations seeking lower operational costs than London.
Midlands
Birmingham studios adopt generative image and video synthesis for rapid variant testing by direct-to-consumer retail brands. The Online Safety Bill creates advisory revenue streams as platforms seek compliance interpretation. West Midlands automotive and logistics sectors demand integrated brand and performance campaigns.
Southwest
Bristol's creative boutiques capture subscription-based SEO and content creation contracts from regional professional services firms. Cloud-based tools democratize access to previously enterprise-only capabilities for SMEs without dedicated marketing leadership. Bath and Bristol studios specialize in sustainable brand positioning for B Corp-certified clients.
Scotland
Edinburgh's financial services sector generates demand for certified data governance frameworks under GDPR Article 7 enforcement. The Scottish Government's digital strategy funding supports agency capability building in privacy-preserving analytics. Glasgow's media production facilities serve UK-wide broadcast and streaming content contracts.
United Kingdom Marketing Agencies Market Competitive Landscape
Concentration sits with global network holding companies that leverage cross-border data infrastructure and consolidated media buying power. The United Kingdom marketing agencies landscape structures around three tiers: multinational networks with enterprise retainers, mid-size integrated shops with regional strength, and specialized boutiques capturing margin pools through technical expertise. Dominant competitive moves include strategic acquisitions of data analytics capabilities and expansion of in-house embedded team contracts.
Within the network tier, WPP plc and Publicis Groupe SA occupy positions defined by global scale and infrastructure investment. Wieden + Kennedy represents the creative specialization archetype, sustaining premium positioning through brand storytelling that commands higher retainer rates. Among UK-based independents, Croud and Impression exemplify the digital-native model built around performance marketing and technical SEO expertise.
| Leading Market Players |
|---|
| WPP plc |
| Publicis Groupe SA |
| Omnicom Group Inc. |
| The Interpublic Group of Companies Inc. |
| Wieden + Kennedy |
| McCann |
| Croud |
| Open Partners |
| Impression |
| Others |
Pricing and Supply Chain Analysis
Ninety-day SaaS renewal cycles concentrate pricing power with US-domiciled martech vendors, forcing UK agencies to absorb sterling-dollar volatility or pass through cost increases to clients already squeezed by outcome-based procurement demands. This lead-time compression in software licensing reshapes margin structures across London networks and Manchester boutiques alike.
Pricing Analysis
The customization-premium spread separates enterprise retainers with bespoke data governance frameworks from fixed-fee project work serving regional SMEs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with GDPR-compliant audience targeting commanding substantial uplifts. Cost compression in the mid-market tier intensifies as generative tools democratize creative production. SMEs exhibit highest price sensitivity, while financial services procurement teams accept premium positioning for certified compliance architectures.
Supply Chain Analysis
Just-in-time talent deployment dominates agency operations, with freelance and contract specialists replacing permanent headcount during campaign surges. Cloud infrastructure and martech platforms draw from the United States, Ireland, and the Netherlands, with creative production talent anchored in the UK. Single-source vulnerability concentrates in Meta and Alphabet algorithm dependencies that throttle organic reach unpredictably. Distribution runs through direct client relationships and embedded in-house teams rather than intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through this market as GDPR Article 7 enforcement and server-side infrastructure migration splinter demand between compliance-heavy enterprise accounts and tool-enabled mid-market efficiency plays.
For Market Incumbents: Fortify data governance capabilities through certified privacy engineering talent acquisition and cloud tagging architecture investment. The Advertising Standards Authority's evolving influencer disclosure guidelines threaten traditional campaign contracting models. Vertical integration into consent management infrastructure anchors enterprise retention against boutique competitors. For New Entrants and Emerging Players: Differentiate on Manchester and Bristol regional presence with lower operational cost bases than London. The Leeds-Bradford manufacturing corridor offers underpenetrated SME demand for performance marketing without dedicated marketing leadership. Go-to-market positioning around AI-assisted creative production and fixed-fee output contracts captures margin expansion as generative tools compress traditional retainer values. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because server-side infrastructure migration demands capital investment that fragments the mid-tier competitive set. Acquisition targets center on specialized boutiques with certified GDPR frameworks and recurring SEO subscription revenue. The signal to watch is first-party data strategy maturity as the decisive capability differentiator separating acquirable assets from stranded legacy operations.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy Engineering Talent Acquisition | Certified data governance frameworks anchor enterprise retention against network competitors. |
| Cloud Tagging Architecture Investment | Server-side infrastructure migration demands capital deployment mid-size competitors cannot fund. |
| AI-Assisted Creative Production Scale-Up | Generative tools compress asset turnaround times for social campaigns enabling fixed-fee margin capture. |
| Manchester Media Cluster Expansion | Lower operational costs and northern England e-commerce proximity attract brand headquarters relocations. |
| Outcome-Based Compensation Restructuring | Performance-linked fee components transfer media efficiency accountability upstream to agency balance sheets. |
Research Methodology
Initial hypotheses were tested against primary input from agency managing directors, brand-side procurement leads, martech vendor sales executives, and regulatory compliance officers and refined through secondary validation against Advertising Standards Authority enforcement records, Information Commissioner's Office guidance documents, Companies House filings, and trade association membership data. Bottom-up service line estimates triangulated against top-down sector expenditure benchmarks.
Variance decomposition across service type, client scale, delivery model, and industry vertical dimensions structured the analytical framework over the projection horizon. CAGRs derived from historical billing trend extrapolation adjusted for regulatory inflection points and technology substitution effects. Privacy-preserving measurement adoption curves and programmatic audio inventory expansion fed sector-specific trajectory modeling.
The analysis sits within stated boundaries; outcomes outside sustained fintech venture funding velocity or abrupt platform algorithm shifts would require recalibration. Forecasts reflect documented assumptions around GDPR enforcement intensity and cloud infrastructure cost trajectories. Revision becomes warranted when sterling-dollar volatility crosses thresholds that materially alter SaaS procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertising Platform Market
Advertising and Marketing Media
North America Advertising Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
Japan OOH and DOOH Market