
 Next Generation Genomics Market | 2026-2036
Next Generation Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Genomics Market Foresight
Software-defined analysis pipelines is realigning how sequencing platforms monetize value, shifting revenue from instrument sales to recurring bioinformatics subscriptions. Illumina Inc. anchors this transition through its cloud-based variant interpretation ecosystem. Thermo Fisher Scientific Inc. leverages integrated reagent-instrument-software bundles to sustain laboratory wallet share. Oxford Nanopore Technologies differentiates through portable, real-time sequencing hardware that competes against centralized high-throughput installations.
Next generation genomics encompasses high-throughput DNA and RNA sequencing, microarray profiling, and gene editing technologies operating at sub-nanogram input thresholds and single-molecule resolution, enabling parallel analysis of millions of genetic loci for diagnostic, therapeutic, and research applications. Sequencing instruments and consumables occupy the largest value pool, while CRISPR-based gene editing tools represent the fastest-expanding technology segment as therapeutic developers advance from research to clinical validation. Diagnostics and personalized medicine applications command premium margins, whereas academic research laboratories remain volume-heavy but price-sensitive end users.
FDA oversight of laboratory-developed tests and companion diagnostics shapes product development timelines and commercialization pathways for US market participants. EMA's In Vitro Diagnostic Regulation and GDPR-compliant genomic data handling requirements in Europe impose parallel compliance burdens on multinational suppliers. ISO 15189 medical laboratory accreditation and WHO guidance on genomic surveillance further standardize quality benchmarks across jurisdictions. Stakeholders must monitor evolving reimbursement frameworks for molecular diagnostics as payors recalibrate coverage criteria against clinical utility evidence.
Market Dynamics
Software-defined bioinformatics pipelines are compressing instrument hardware margins while elevating recurring revenue from cloud-based variant interpretation and automated reporting workflows.
Growth Catalysts
- FDA-cleared companion diagnostics:Pharmaceutical sponsors now embed genomic stratification into Phase II trial protocols, accelerating regulatory validation timelines for targeted therapies.
- CRISPR-based gene editing:Therapeutic developers advance from research-grade reagents to GMP-compliant manufacturing, expanding addressable applications in oncology and rare disease.
- United States reimbursement expansion:Medicare coverage determinations for molecular profiling in solid tumors are standardizing prior authorization pathways for community oncology practices.
Market Restraints
- Reagent supply concentration:Three suppliers control over 70% of sequencing flow cell manufacturing, creating vulnerability to single-source disruptions.
- GDPR genomic data handling:European laboratories face 72-hour breach notification requirements and pseudonymization mandates that extend data processing timelines.
- Technical read-length limitations:Short-read platforms struggle with highly repetitive regions and structural variant detection, forcing hybrid workflows that increase per-sample cost.
Strategic Opportunities
- India diagnostic penetration:CDSCO streamlined IVD registration pathways and PLI scheme incentives are attracting reagent manufacturing investments for price-sensitive hospital networks.
- Long-read clinical adoption:Integration of nanopore and single-molecule real-time sequencing with short-read verification is opening Mendelian disease and pharmacogenomics applications.
- ISO 15189 laboratory accreditation:Quality standardization across Middle East and Southeast Asia is creating demand for integrated LIMS and quality control automation platforms.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories compete with technology firms for variant curators and pipeline engineers, inflating compensation benchmarks.
- CAP/CLIA certification timelines:New laboratory sites face 12-18 month validation periods for NGS-based oncology panels, delaying revenue generation.
- Legacy EHR integration:Genomic data formats lack standardization with Epic and Cerner workflows, requiring costly middleware development for clinical decision support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Genomics Market |
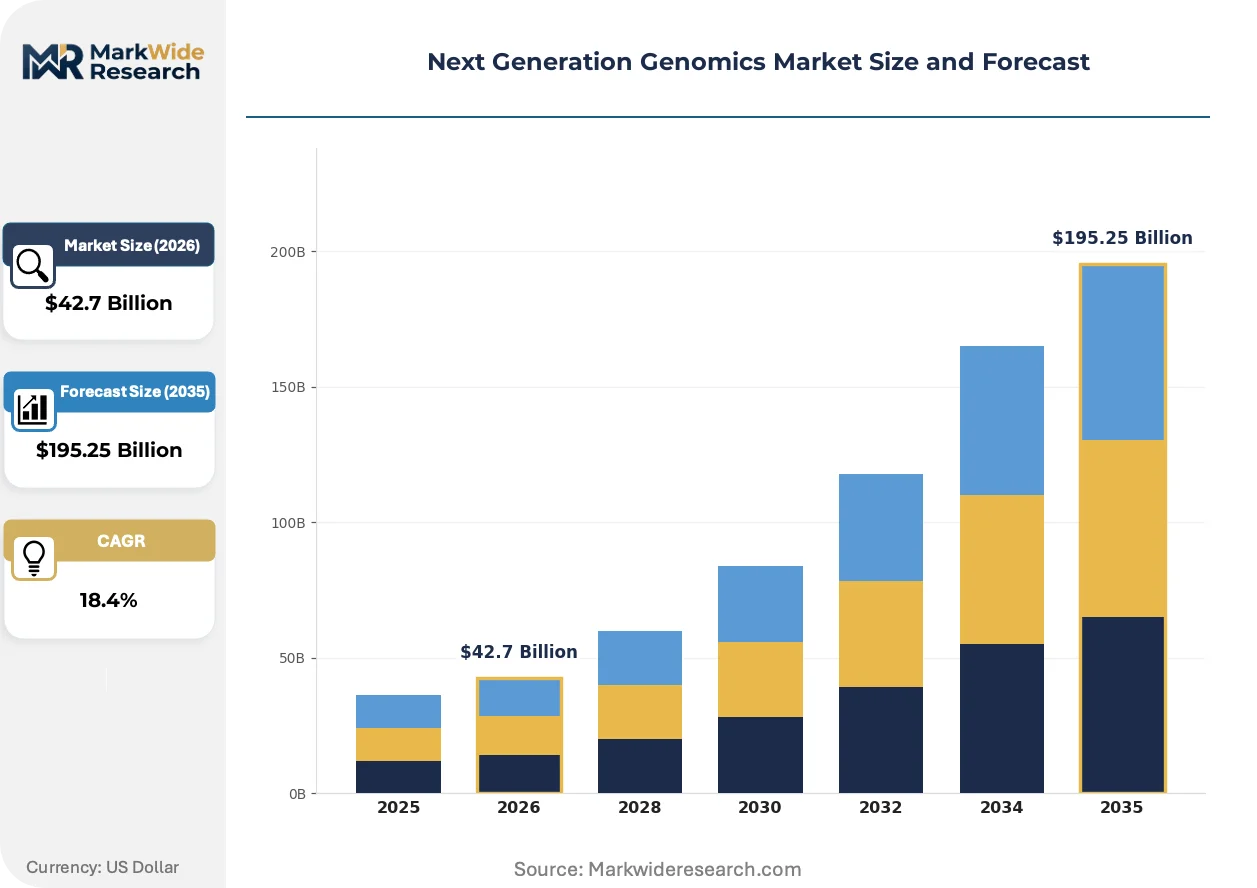
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $195.25 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing Kits, Reagents, Software, Instruments Technology: Sequencing, Microarray, PCR, CRISPR Application: Diagnostics, Research, Drug Development, Personalized Medicine End User: Hospitals, Academic Institutions, Research Laboratories, Biopharma |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., QIAGEN N.V., Oxford Nanopore Technologies, Pacific Biosciences Inc., Agilent Technologies Inc., Bio-Rad Laboratories Inc., BGI Genomics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Genomics Market Shifts & Advancements
Three forces are restructuring competitive positioning: portable sequencing hardware challenging centralized high-throughput installations, regulatory frameworks forcing data governance investments, and pharmaceutical procurement consolidating around integrated trial-enrollment platforms.
Artificial intelligence-powered variant classification is electrifying diagnostic interpretation workflows. Clinical laboratories at academic medical centers deploy deep learning models for rare disease case resolution, compressing turnaround from weeks to days. This capability is enabling direct-to-physician reporting that bypasses traditional genetic counselor review queues.
EMA's In Vitro Diagnostic Regulation (IVDR) is reclassifying genomic assays into higher-risk categories requiring notified body involvement. Manufacturers face expanded clinical evidence requirements for Class C and D devices, extending time-to-market for new oncology panels. European diagnostic firms are responding by consolidating quality management systems and pre-submission engagement with designated conformity assessment bodies.
Pharmaceutical sponsors now procure genomic testing through centralized trial-enrollment platforms rather than site-specific laboratory contracts. Contract research organizations aggregate sequencing, variant interpretation, and patient-matching services into single-source agreements. This concentration is most visible in United States oncology trials, where three preferred provider networks now handle majority of biomarker screening volume.
Next Generation Genomics Market Segmentation
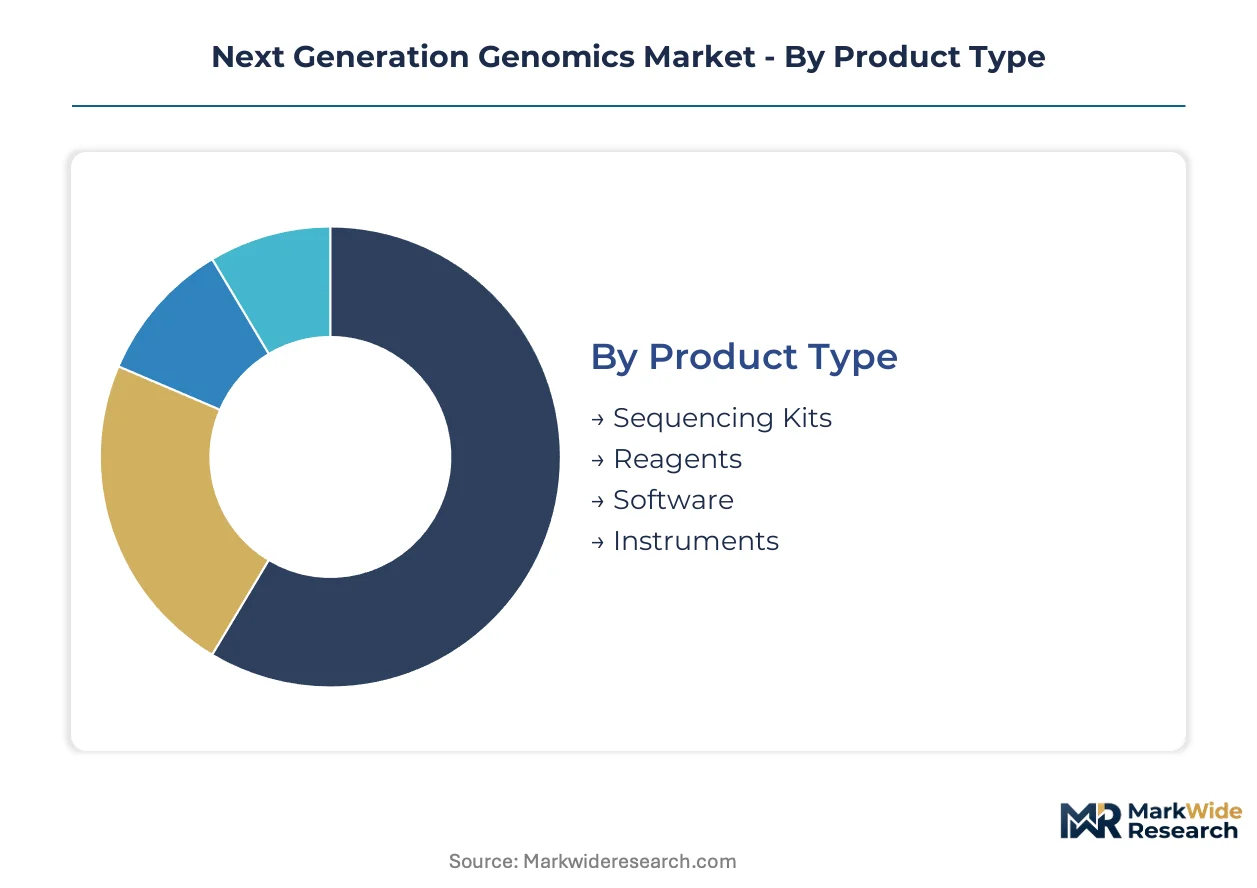
Genomics procurement patterns split sharply between capital-intensive instrument purchases and recurring consumable commitments. Understanding these segment boundaries clarifies where suppliers capture lifetime value versus one-time transactions.
Product Type:
Budget allocation cycles determine supplier relationships here, with capital equipment requiring committee approval while reagents flow through standing purchase orders.
- Sequencing Kits:Pre-formulated library preparation and target enrichment chemistries dominate laboratory recurring spend. Academic medical centers in the United States negotiate multi-year kit supply agreements to lock in per-run economics amid volatile flow cell pricing.
- Reagents:Enzymes, buffers, and nucleotide mixes constitute the highest-volume consumable category. Biopharma quality control laboratories specify GMP-grade reagent documentation to satisfy FDA pre-approval inspection requirements.
- Software:Variant interpretation pipelines and laboratory information management systems monetize through seat-based or per-sample subscriptions. Cloud deployment models are displacing on-premise installations at mid-sized clinical laboratories.
- Instruments:Sequencing platforms, liquid handlers, and sample prep automation represent multi-year capital commitments. Purchase decisions increasingly bundle multi-omics compatibility to future-proof against technology obsolescence.
Volume sits with reagents and kits; growth tilts toward software as laboratories outsource informatics infrastructure.
Technology:
Technical performance specifications—read length, accuracy, throughput, and sample input requirements—shape competitive substitution patterns across research and clinical settings.
- Sequencing:Short-read platforms deliver highest throughput for population-scale studies. Long-read technologies from Pacific Biosciences and Oxford Nanopore are penetrating Mendelian disease diagnostics where structural variant resolution matters.
- Microarray:Genotyping arrays and expression profiling maintain cost advantages for high-sample-count applications. Agricultural biotechnology firms deploy microarrays for marker-assisted breeding programs at scale.
- PCR:Quantitative and digital PCR methods provide targeted validation of sequencing findings. Clinical laboratories retain PCR workflows for infectious disease testing where regulatory pathways are established.
- CRISPR:Gene editing reagents and synthetic guide RNA libraries represent the steepest expansion trajectory. Therapeutic developers advance CRISPR-based cell therapies through FDA IND-enabling studies.
Sequencing commands installed base; CRISPR climbs fastest as therapeutic applications mature.
Application:
Reimbursement clarity and regulatory precedent determine which applications attract sustained investment versus experimental deployment.
- Diagnostics:Oncology companion diagnostics and rare disease testing generate reimbursed revenue streams. United States Medicare coverage for molecular profiling in solid tumors standardizes prior authorization pathways.
- Research:Academic and government-funded investigations drive instrument placement and publication volume. National Institutes of Health funding priorities shift resources toward pandemic preparedness and health disparities research.
- Drug Development:Pharmaceutical sponsors embed genomic biomarkers into Phase II trial protocols. Patient stratification requirements are expanding contract research organization sequencing service procurement.
- Personalized Medicine:Pharmacogenomic testing and polygenic risk scoring target preventive care applications. Direct-to-consumer genetic testing firms are pivoting toward physician-ordered clinical reports.
Diagnostics holds revenue concentration; drug development spending accelerates fastest on biomarker-driven trial design.
End User:
Technical sophistication and purchasing authority vary dramatically, from centralized biopharma procurement to fragmented hospital laboratory decision-making.
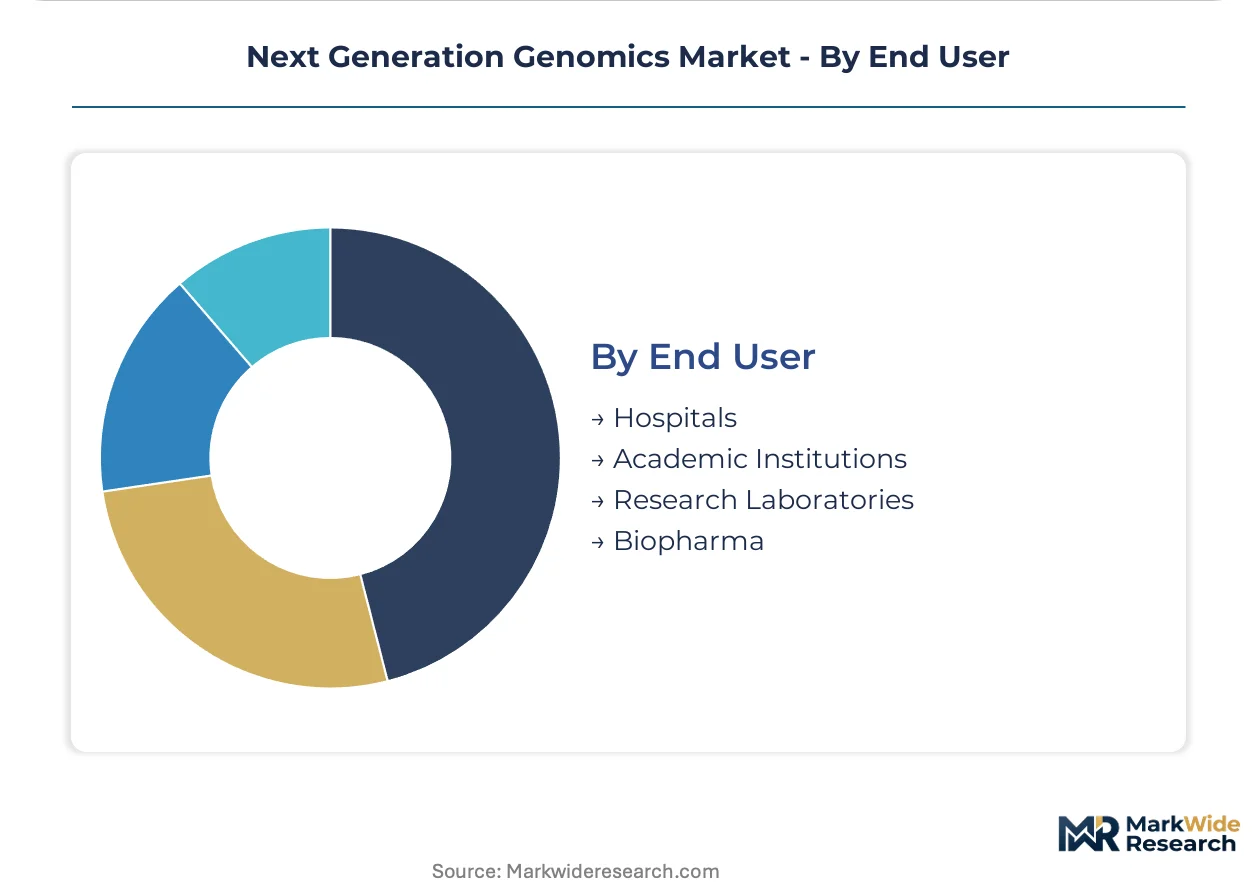
- Hospitals:Clinical pathology departments integrate NGS into oncology and prenatal testing menus. Community hospitals face CAP/CLIA certification barriers that delay test launch timelines.
- Academic Institutions:Research universities combine core facility instrumentation with investigator-initiated grant funding. Federal funding agency priorities shape equipment refresh cycles.
- Research Laboratories:Government and private research institutes operate outside reimbursement constraints. These users prioritize publication-grade data quality and open-source analysis tools.
- Biopharma:Integrated pharmaceutical and biotechnology firms deploy genomics across discovery, clinical, and manufacturing quality functions. Procurement consolidation around preferred vendor networks is compressing supplier margins.
Biopharma aggregates the largest contract values; hospitals represent the most fragmented expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing concentrates in the United States and China while diagnostic consumption spreads across tertiary hospital networks in Germany, Japan, and India. Reagent supply chains remain vulnerable to single-source dependencies. Regulatory divergence between FDA clearance pathways and EMA's IVDR implementation creates compliance complexity for multinational suppliers.
United States
FDA-cleared companion diagnostics command premium pricing in oncology and rare disease applications. Medicare coverage determinations for molecular profiling in solid tumors standardize prior authorization pathways for community oncology practices. The Boston-Cambridge corridor anchors therapeutic development pipelines where pharmaceutical sponsors embed genomic stratification into Phase II trial protocols.
Germany
EMA's In Vitro Diagnostic Regulation reclassifies genomic assays into higher-risk categories requiring notified body involvement. ISO 15189 medical laboratory accreditation standardizes quality benchmarks across university hospital networks. The Munich-Stuttgart axis concentrates diagnostic instrument distribution hubs serving Central and Eastern European expansion markets.
China
NMPA streamlined registration pathways for sequencing-based diagnostic devices accelerate domestic manufacturer market entry. National genomic surveillance programs under WHO guidance expand sequencing capacity at provincial CDC laboratories. The Yangtze River Delta clusters reagent manufacturing investments targeting price-sensitive hospital procurement frameworks.
Japan
PMDA review timelines for novel genomic diagnostics shape product launch sequencing for Asia-Pacific market entry. METI funding priorities shift resources toward pandemic preparedness and health disparities research applications. The Kanto region maintains centralized high-throughput installations serving national biobank initiatives and pharmaceutical contract research.
India
CDSCO streamlined IVD registration pathways and PLI scheme incentives attract reagent manufacturing investments for price-sensitive hospital networks. DGFT import tariff structures on sequencing instruments influence domestic assembly partnerships. Maharashtra and Karnataka states concentrate diagnostic laboratory accreditation programs creating demand for integrated LIMS platforms.
Next Generation Genomics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across sequencing platform development and bioinformatics service delivery. Three suppliers control over 70% of sequencing flow cell manufacturing, creating tiered supply security versus innovation trade-offs. Strategic archetypes separate integrated life science conglomerates from precision oncology specialists and portable hardware innovators. Competitive moves concentrate on cloud-based variant interpretation ecosystems and multi-omics compatibility bundling to future-proof instrument placements.
Within the integrated platform tier, Illumina Inc. and Thermo Fisher Scientific Inc. exemplify recurring revenue models shifting from instrument sales toward consumable and subscription monetization. Oxford Nanopore Technologies occupies a position representing portable, real-time sequencing hardware that challenges centralized high-throughput installations. These three entities anchor distinct competitive vectors: cloud-based bioinformatics, integrated reagent-instrument-software bundles, and field-deployable molecular diagnostics.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN N.V. |
| Oxford Nanopore Technologies |
| Pacific Biosciences Inc. |
| Agilent Technologies Inc. |
| Bio-Rad Laboratories Inc. |
| BGI Genomics Co. Ltd. |
| Others |
Supply & Pricing Matrix
Pharmaceutical sponsor consolidation around centralized trial-enrollment platforms is compressing per-sample sequencing margins and forcing reagent suppliers into multi-year consumable lock-in contracts to defend wallet share.
Pricing Analysis
Margin tightening in the sequencing consumables tier reflects pharmaceutical procurement teams consolidating vendor relationships around integrated reagent-instrument-software bundles. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic workflows from research-grade applications and emerging market hospital networks. Cost-down pressure on flow cell manufacturing accelerates because three suppliers control over seventy percent of production capacity. Academic medical centers exhibit highest price sensitivity due to grant-funded budget cycles, while biopharma quality control laboratories absorb premium GMP-grade documentation costs.
Supply Chain Analysis
ISO 13485 and GMP certification requirements for sequencing flow cell manufacturing concentrate production expertise in the United States, China, and Germany. Raw material dependencies center on high-purity silicon wafers, synthetic oligonucleotides, and fluorophore-conjugated nucleotides. Single-source vulnerability pervades the flow cell coating chemistry segment where proprietary surface chemistry patents limit qualified suppliers. Distribution runs through direct field service organizations for instrument placements and authorized distributors for reagent replenishment in price-sensitive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's In Vitro Diagnostic Regulation reclassification of genomic assays into higher-risk device categories erects a cost-of-compliance barrier that favors incumbents with established quality management systems and notified body relationships.
For Market Incumbents: Acquire cloud-based variant interpretation platforms to anchor recurring revenue streams against instrument hardware margin compression. Integrate CRISPR reagent manufacturing capabilities in-house to capture therapeutic developer procurement consolidation. Defend against portable sequencing hardware substitution by bundling multi-omics compatibility into next-generation instrument placements. For New Entrants and Emerging Players: The mid-tier pricing gap between Illumina's premium ecosystem and Oxford Nanopore's field-deployable instruments opens white-space for automated sample prep automation targeting community hospital laboratories in India and Southeast Asia. CDSCO streamlined registration pathways and PLI scheme incentives lower barrier-to-entry for reagent manufacturing investments serving price-sensitive diagnostic networks. Pursue ISO 15189 laboratory accreditation partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: The window for entry favors precision oncology specialists with FDA-cleared companion diagnostic portfolios and established pharmaceutical sponsor relationships. Long-term viability hinges on regulatory moat sustainability through IVDR and FDA premarket approval pathways. Watch for Medicare coverage determination expansions beyond solid tumor profiling as the inflection signal for molecular diagnostics reimbursement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Variant Interpretation Platform | Illumina's DRAGEN ecosystem anchors recurring bioinformatics subscriptions shifting revenue from hardware sales. |
| GMP-Grade CRISPR Reagent Manufacturing | Therapeutic developers advancing cell therapies through FDA IND-enabling studies demand documented quality systems. |
| ISO 15189 Laboratory Accreditation Partnership | Middle East and Southeast Asia quality standardization creates demand for integrated LIMS and automation platforms. |
| Long-Read Clinical Sequencing Integration | Pacific Biosciences and Oxford Nanopore penetration of Mendelian disease diagnostics opens structural variant applications. |
| Centralized Trial-Enrollment Platform | Contract research organizations aggregate sequencing and patient-matching services into single-source pharmaceutical agreements. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EMA IVDR classification decisions, and Medicare coverage determination trajectories anchored the trend analysis, supplemented by interviews with diagnostic laboratory directors, pharmaceutical biomarker strategy leads, reagent manufacturing quality officers, and health technology assessment specialists. Secondary validation drew from FDA 510(k) premarket notification databases, EMA In Vitro Diagnostic Regulation guidance documents, ClinicalTrials.gov genomic stratification protocol entries, and CMS national coverage determination records. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocations.
Input-output matrices modeled sequencing instrument placements, consumable throughput per installed base, and software subscription attach rates across product type, technology, application, and end user dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical instrument shipment data and pharmaceutical sponsor sequencing procurement trends. Industry-specific forecast inputs incorporated CRISPR therapeutic pipeline advancement rates and companion diagnostic regulatory validation timelines.
Inputs from FDA premarket notification databases and EMA notified body engagement records were available through the study window; gaps in private pharmaceutical sponsor sequencing procurement contract terms introduce uncertainty bands around biopharma segment projections. Forecasts reflect assumptions regarding IVDR implementation pacing and Medicare coverage expansion trajectories. A model refresh is warranted upon material change in FDA laboratory-developed test enforcement posture or EMA IVDR classification appeal outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Spatial OMICS Market
Genomics
North America Microarray Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Animal Genetics Market
Genomics
Human Genetics Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Reproductive Genetics Market
Genomics
Genetic Material Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Europe Epigenetics Market
Genomics
Global Digital PCR Market
Genomics
Global Microarray Analysis Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Genetic Analysis Services Market
Genomics
Global Molecular Cytogenetics Market