
 Global Electrical Switches Market | 2026-2036
Global Electrical Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical Switches Market Analysis
Aftermarket service revenue for legacy electromechanical switch replacement is fragmenting as building automation integrators shift toward predictive maintenance contracts bundled with smart switch deployments. Schneider Electric leverages its EcoStruxure platform to anchor service revenue in European commercial retrofit programs. Legrand competes through deep product specialization in modular wiring devices for healthcare and data center verticals. Siemens AG dominates railway and heavy industrial applications through IEC 61373-certified switchgear assemblies.
Electrical switches are electromechanical or solid-state devices designed to open, close, or redirect current paths in circuits rated from milliamps to thousands of amps, with contact materials ranging from silver-nickel alloys to gold-plated copper depending on load characteristics and cycle life requirements. Their primary commercial purpose is to enable safe, reliable control of power flow across building infrastructure, transportation systems, and industrial machinery. Rocker switches and push button switches retain the largest installed base in residential and commercial construction, though smart switches represent the fastest-expanding margin pool as interoperability demands under Matter and KNX protocols reshape procurement criteria. Mechanically operated switches face gradual displacement in premium building segments where touch and wireless technologies capture specification influence from architects and systems integrators.
The US DOE enforces standby power limits under appliance efficiency regulations, while the EU Ecodesign Directive and CE marking requirements under the Low Voltage Directive shape product compliance thresholds for switch exports into European markets. China's GB standards and compulsory CCC certification create parallel testing burdens for manufacturers serving domestic construction projects. Stakeholders must monitor divergence between regional cybersecurity mandates for connected switches and the pace at which legacy electromechanical specifications get grandfathered out of green building codes.
Market Dynamics
The EU Ecodesign Directive's tightening standby power limits are forcing semiconductor-based designs into legacy electromechanical sockets, compressing replacement cycles across commercial real estate portfolios and industrial facilities.
Growth Catalysts
- US DOE appliance standards:Federal standby power regulations are accelerating semiconductor switch adoption in residential and commercial building retrofits.
- Smart building automation:Matter and KNX protocol interoperability requirements are expanding specification influence for connected switch platforms in new construction.
- Yangtze River Delta:Concentrated electronics manufacturing in this Chinese cluster is reducing component lead times for global switch OEMs.
Market Restraints
- Silver-nickel alloy costs:Contact material price volatility is squeezing margins on high-cycle electromechanical switch production.
- CCC certification burden:China's compulsory product testing creates parallel compliance costs for exporters serving domestic construction projects.
- Solid-state substitution:Semiconductor-based alternatives threaten mechanical switch volumes in premium building segments.
Strategic Opportunities
- India's Gujarat-Maharashtra corridor:Underpenetrated industrial automation creates white space for IEC-certified switchgear assemblies.
- Predictive maintenance bundling:Building automation integrators are unbundling legacy replacement revenue into service contracts anchored by smart switch deployments.
- EU Green Deal alignment:Energy performance contracting mandates in European public buildings are creating specification pull for efficiency-optimized designs.
Industry Challenges
- Cybersecurity certification timelines:Divergent regional mandates for connected switch security are fragmenting product development roadmaps.
- Legacy system integration:Electromechanical specification grandfathering in green building codes is complicating smart retrofit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical Switches Market |
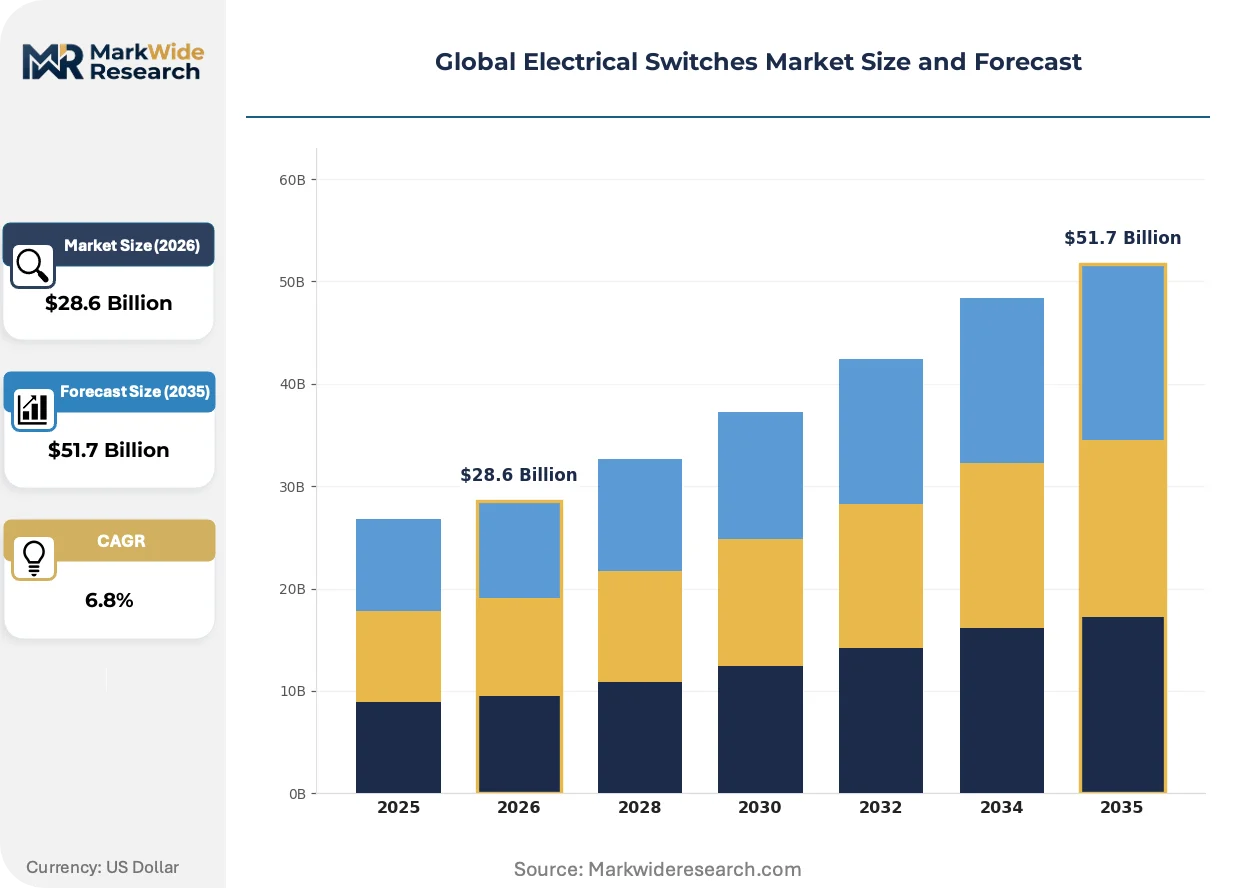
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle Switches, Rocker Switches, Slide Switches, Push Button Switches Technology: Smart Switches, Mechanically Operated, Wireless Switches, Touch Switches End User: Residential, Commercial, Industrial, Automotive Application: Lighting Control, Power Distribution, HVAC Systems, Home Automation |
| Companies Covered | Panasonic Corporation, Eaton Corporation, Legrand, TE Connectivity, Honeywell International, Schneider Electric, ABB Ltd., Amphenol Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical Switches Market Emerging Trajectories
Touch and wireless control technologies are capturing specification influence from architects and systems integrators, compressing the addressable market for mechanically operated switches in premium construction segments.
Capacitive touch sensing technology is digitizing user interfaces across residential and commercial switch installations. High-end residential developers and hospitality operators are specifying glass-panel touch controls at accelerating rates. This transition is digitizing procurement criteria and marginalizing traditional rocker and push-button formats in design-forward projects.
REACH substance restrictions on heavy metals in electrical contacts are reshaping material sourcing across European supply chains. Manufacturers are reformulating silver-cadmium oxide alternatives to maintain arc-quenching performance under tightened chemical thresholds. Healthcare and data center verticals in Germany and France are responding fastest, driven by LEED-equivalent certification requirements.
Specification influence is migrating from electrical contractors to building automation integrators and facilities management platforms. Traditional distribution through wholesale electrical supply houses is giving way to direct procurement by systems integrators bundling switches with BMS deployments. This channel compression is most visible in US commercial office retrofits and European public sector energy performance contracts.
Global Electrical Switches Market Segmentation
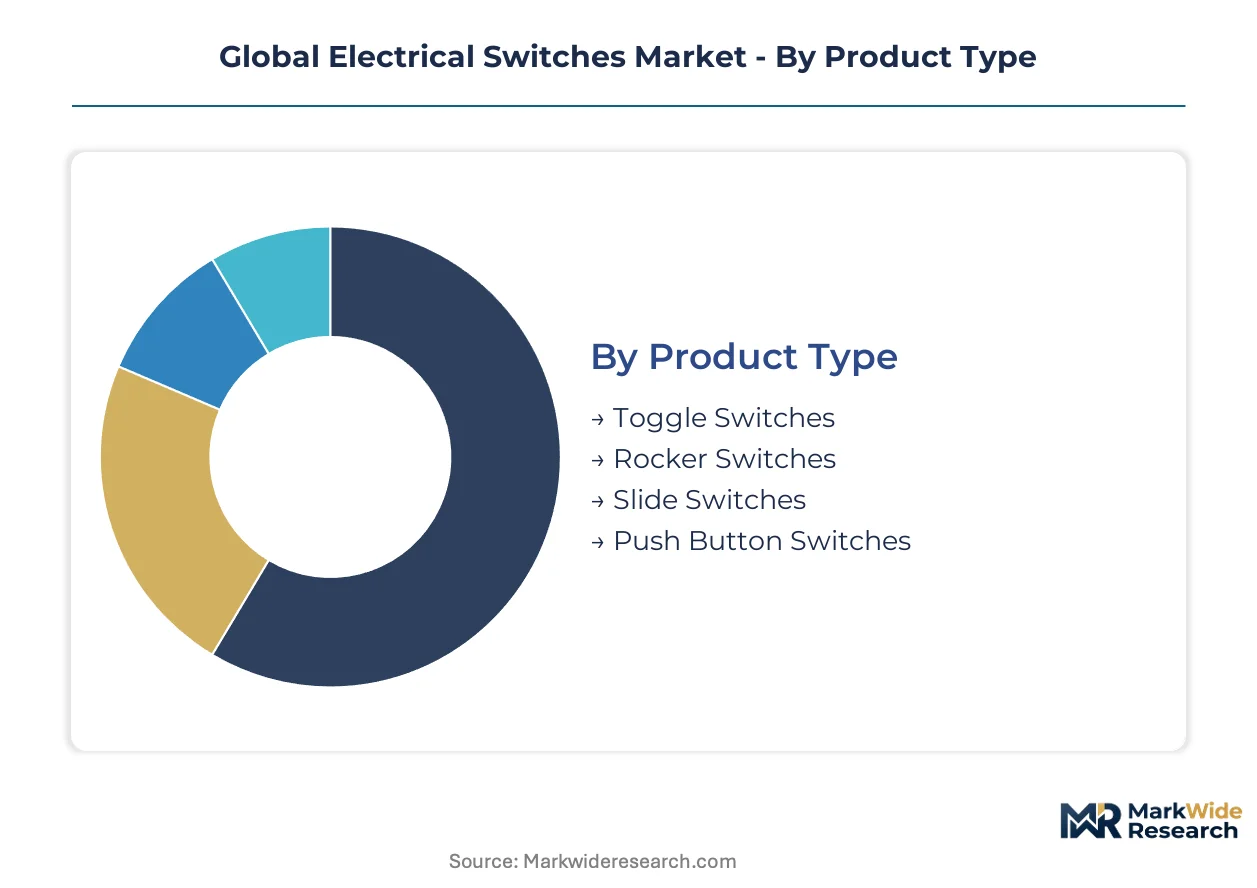
Switch procurement criteria diverge sharply across building types and control architectures. Specification influence migrates from electrical contractors to systems integrators as smart building protocols reshape purchasing workflows.
Product Type:
Mature formats dominate installed bases while emerging variants capture retrofit and premium new construction specifications.
- Rocker Switches:Plastic or metal actuators pivot around a central axis to complete circuits, with contact ratings typically spanning 10-20 amps at 250V AC. Residential builders in India's Gujarat-Maharashtra corridor specify rockers for cost-sensitive multi-unit housing, though Matter protocol compatibility is becoming a baseline requirement even in this segment.
- Push Button Switches:Momentary or latching mechanisms using spring-return plungers suit high-cycle industrial applications. German automotive suppliers and Japanese railway OEMs specify IEC 61373-certified push button assemblies for vibration-resistant control panels.
- Toggle Switches:Lever-actuated designs with bat-handle profiles persist in marine, aviation, and heavy equipment applications where positive mechanical feedback prevents accidental actuation.
- Slide Switches:Compact linear-motion mechanisms occupy minimal panel depth, serving consumer electronics and appliance sub-assemblies where space constraints override cycle-life requirements.
Rocker switches handle the majority of throughput; push button switches are the fastest mover on specification value.
Technology:
Cost tiers separate semiconductor-based platforms from electromechanical legacy, with wireless connectivity bridging the gap in mid-market retrofits.
- Smart Switches:Microcontroller-equipped devices with Wi-Fi, Zigbee, or Thread radios enable remote scheduling and energy monitoring. US DOE standby power regulations under appliance efficiency standards are accelerating semiconductor adoption in commercial building retrofits across California and Texas.
- Mechanically Operated:Pure electromechanical contact assemblies using silver-nickel or silver-cadmium oxide alloys face margin compression from raw material volatility. China's Yangtze River Delta manufacturers dominate high-volume production for export markets.
- Touch Switches:Capacitive sensing behind glass or polymer panels eliminates moving parts. Hospitality developers in Dubai and Singapore specify touch controls for design-forward hotel lobbies and guest room renovations.
- Wireless Switches:Battery-free kinetic harvesting or low-power radio designs eliminate wiring runs in historic building retrofits where conduit installation is prohibited.
Mechanically operated switches retain volume leadership; smart switches are expanding most quickly on margin contribution.
End User:
Customer type determines certification burden and procurement channel, with industrial buyers prioritizing cycle life and residential buyers emphasizing aesthetic integration.
- Residential:Single-family and multi-unit housing drives volume demand for standardized wall-box formats. Indian urban housing schemes and US suburban development are pulling specification influence toward app-configurable platforms.
- Commercial:Office, retail, and hospitality facilities prioritize interoperability with building management systems. EU Green Deal energy performance contracting mandates in French and German public buildings are creating specification pull for efficiency-optimized designs.
- Industrial:Factory automation and process control applications demand IP-rated enclosures and high-current contact ratings. Siemens AG and ABB dominate railway and heavy industrial segments through IEC-certified switchgear assemblies.
- Automotive:EV charging infrastructure and cabin electronics are shifting switch specifications toward sealed, vibration-resistant semiconductor alternatives.
Commercial end users generate the highest specification value per unit; residential maintains the steepest expansion trajectory in absolute volume.
Application:
Functional use case determines technical requirements, with lighting control serving as the entry point for smart building upgrades while power distribution demands higher electrical ratings.
- Lighting Control:Dimmer compatibility and scene programming capabilities define premium positioning. Legrand's modular wiring devices capture specification in European healthcare and data center verticals where lighting integration with emergency systems is mandatory.
- Power Distribution:Load-breaking and isolation functions in panelboards and switchgear require arc-quenching contact materials. REACH substance restrictions on heavy metals are forcing European manufacturers to reformulate silver-cadmium oxide alternatives.
- HVAC Systems:Fan speed selection and compressor control switches face replacement by solid-state relays in variable-frequency drive applications.
- Home Automation:Whole-house control platforms bundle lighting, climate, and security through unified interfaces. Schneider Electric's EcoStruxure platform anchors service revenue in European commercial retrofit programs.
Lighting control commands the largest installed base; home automation is gaining share fastest on new construction specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's Gujarat-Maharashtra corridor exhibit extreme price sensitivity for bulk electromechanical rockers, while German industrial purchasers prioritize IEC-certified cycle life over unit cost. China's Yangtze River Delta manufacturers serve both extremes through tiered output.
United States
Commercial building retrofits in California and Texas are pulling smart switch specifications under DOE standby power regulations. The US DOE appliance efficiency standards are compressing replacement cycles across multi-site real estate portfolios. Austin and Dallas manufacturing clusters are expanding semiconductor switch assembly capacity for domestic retrofit demand.
Germany
Railway OEMs and automotive suppliers specify IEC 61373-certified push button assemblies for vibration-resistant control panels. The EU Ecodesign Directive and REACH substance restrictions on heavy metals are forcing contact material reformulation. Bavarian industrial automation integrators are bundling predictive maintenance contracts with smart switch deployments.
China
Yangtze River Delta electronics manufacturing is reducing component lead times for global switch OEMs serving both premium and economy tiers. GB standards and compulsory CCC certification create parallel testing burdens for domestic construction projects. Shanghai and Suzhou clusters dominate high-volume electromechanical production for export markets.
India
Urban housing schemes in Maharashtra and Gujarat specify cost-sensitive rockers for multi-unit residential construction, though Matter protocol compatibility is becoming baseline. The Bureau of Indian Standards and CEA regulations shape product compliance for infrastructure projects. Ahmedabad and Mumbai industrial corridors are attracting IEC-certified switchgear assembly investments for underpenetrated automation markets.
Japan
Automotive cabin electronics and EV charging infrastructure are shifting specifications toward sealed, vibration-resistant semiconductor alternatives. METI energy efficiency guidelines and JIS standards govern product performance thresholds. Nagoya and Osaka manufacturing bases are concentrating on high-reliability touch and wireless control modules for premium export markets.
Global Electrical Switches Market Vendor Landscape
Capability concentration sits with European industrial specialists; scale advantage sits with Asian electronics manufacturers. The market structures around three tiers: diversified electrical conglomerates with building automation platforms, component specialists focused on contact materials and cycle life, and contract manufacturers serving private-label residential demand. Strategic moves center on predictive maintenance service bundling and backward integration into semiconductor switch assembly.
Within the diversified conglomerate tier, Schneider Electric and Siemens AG exemplify platform-centric positioning anchored by building management system integration. Legrand occupies a position among specialized wiring device manufacturers with deep vertical focus on healthcare and data center certifications. These three entities represent contrasting archetypes: ecosystem orchestration, industrial heavy-duty certification, and modular vertical specialization.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Eaton Corporation |
| Legrand |
| TE Connectivity |
| Honeywell International |
| Schneider Electric |
| ABB Ltd. |
| Amphenol Corporation |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Silver-nickel alloy cost volatility determines both margin compression in electromechanical tiers and the geographic sourcing strategies of contract manufacturers across the Yangtze River Delta. This commodity exposure widens pricing spreads between semiconductor-based smart switches and legacy mechanical formats while forcing procurement teams toward long-term offtake agreements with Chinese smelters.
Pricing Analysis
Aftermarket service contracts anchored to predictive maintenance platforms drive lifetime value capture for building automation integrators. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified industrial assemblies from residential rockers and commodity private-label units. Pricing pressure stems from REACH substance restrictions forcing contact material reformulation in European supply chains. Indian bulk buyers in Gujarat-Maharashtra industrial corridors exhibit extreme price sensitivity, while German railway OEMs prioritize cycle-life certification over unit cost.
Supply Chain Analysis
Tariff exposure between China and North American end markets dominates strategic planning for global switch OEMs. Manufacturing concentrates in China's Yangtze River Delta, South Korea's component clusters, and Mexico's nearshoring zones for US commercial retrofits. Raw material flows draw from Chilean copper smelters, Indonesian nickel processors, and German silver refiners. Single-source vulnerability in microcontroller silicon from Taiwan creates chokepoint risk for smart switch production lines. Distribution runs through building automation integrators and direct BMS procurement channels rather than traditional electrical wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Matter protocol ecosystem represents a platform-economics inflection that collapses proprietary control architectures into unified interoperability standards, reshaping competitive moats around data-layer integration rather than hardware lock-in.
For Market Incumbents: Build predictive maintenance service moats through EcoStruxure-type platform bundling that anchors recurring revenue against semiconductor substitution threats. Deepen backward integration into microcontroller assembly within Austin and Dallas manufacturing clusters to deflect tariff exposure. Invest in IEC 61373 vibration certification for railway verticals where Chinese contract manufacturers lack testing infrastructure. For New Entrants and Emerging Players: Pursue white-space penetration in India's underautomated Gujarat-Maharashtra industrial corridor where IEC-certified switchgear assembly capacity remains scarce. Target hospitality retrofit specifications in Dubai and Singapore for glass-panel touch controls where design-forward procurement bypasses incumbent electrical contractor channels. Lead with wireless kinetic-harvesting formats in historic European building retrofits where conduit prohibition creates specification pull. For Investors and Strategic Acquirers: The market sits at a protocol-consolidation phase that favors platform-orchestrator archetypes over component specialists. Long-term viability over the next decade hinges on data-layer integration capabilities rather than contact-material expertise. Watch Matter certification timelines as the inflection signal indicating which hardware players successfully migrate from electromechanical legacy to software-defined switching platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | Schneider Electric's EcoStruxure bundling anchors recurring service revenue in European commercial retrofits. |
| Backward Integration into Semiconductor Assembly | Austin and Dallas clusters expand domestic capacity to serve US DOE standby power compliance mandates. |
| IEC 61373 Vibration Certification Investment | Siemens AG defends railway switchgear positioning through testing infrastructure Chinese rivals cannot replicate. |
| Matter Protocol Compatibility Development | Interoperability certification becomes baseline specification for US and European smart building procurement. |
| REACH-Compliant Contact Material Reformulation | Legrand and ABB reformulate silver-cadmium oxide alternatives to maintain European market access under tightened chemical thresholds. |
Methodological Framework
Operator-level perspectives from building automation integrators, facilities management platform directors, electrical contractor procurement leads, and semiconductor switch design engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, EU Ecodesign Directive implementation reports, and China customs trade data for silver-nickel alloy flows. Bottom-up segment sizing triangulated against top-down macroeconomic overlays across product type, technology tier, end-user vertical, and regional regulatory cluster dimensions.
Scenario bracketing around EU Green Deal implementation pace, Matter protocol adoption curves, and China-US tariff trajectories shaped the analytical framework. Segmentation modeling spanned electromechanical versus solid-state technology, residential-commercial-industrial end-use, and lighting-power distribution-home automation applications. CAGRs derived from fitted growth curves applied to baseline installed base estimates and replacement cycle compression factors under tightening standby power regulations. Industry-specific inputs included REACH substance restriction timelines and CCC certification processing durations.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, copper and silver commodity price bands, or semiconductor fab capacity expansion would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and protocol interoperability adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Disconnect Switch Market
Switches
Global Switchgear Market
Switches
UK Reed Sensors Switches Market
Switches
5G Electromechanical RF Switch Market
Switches
Smart Circuit Breaker Market
Switches
DC Switchgear Market
Switches
Smart Plugs and Switches Market
Switches
Electromechanical Microwave Switch Market
Switches
Smart Dimmer Switch Market
Switches
Push Button Dropper Market
Switches
Electric Switch Market
Switches
Analog Switches Market
Switches
United States Circuit Breaker Market
Switches
North America Low Voltage Switchgear Market
Switches
South Korea Reed Sensors Switches Market
Switches
Smart Home Switches Market