
 Reed Switches Sensors Market | 2026-2036
Reed Switches Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Reed Switches Sensors Market Analytics
Magnetic sensing miniaturization is rewriting component placement strategies across safety-critical electronics. Standex Electronics leverages captive reed relay manufacturing to sustain pricing power in aerospace and medical niches. Littelfuse anchors its portfolio with fused reed switch assemblies that compete directly with Hall-effect alternatives in automotive position sensing. TE Connectivity dominates high-volume automotive programs through integrated sensor module platforms that extend beyond discrete components.
Reed switches sensors are electromechanical devices hermetically sealed in glass envelopes containing ferromagnetic reeds that close under magnetic field influence, typically rated for millions of switching cycles with contact resistances below 100 milliohms; they serve primarily as position detectors, level sensors, and safety interlocks where galvanic isolation and zero standby power prove essential. Normally open configurations occupy the largest volume share due to ubiquity in door, lid, and proximity detection roles, while medical device applications command premium pricing tiers owing to sterilization compatibility and failure-rate requirements. Electromechanical technology leads unit shipments though solid-state alternatives are displacing reed switches in high-frequency counting applications.
EU RoHS and REACH frameworks restrict mercury and cadmium in contact plating, pushing manufacturers toward ruthenium and rhodium alternatives that alter cost structures. FDA 21 CFR Part 820 quality system regulations govern medical device integration, creating compliance barriers for unqualified suppliers. Japan's METI enforces JIS standards on electromagnetic compatibility that shape export qualification protocols. Stakeholders must monitor contact material substitution timelines and evolving automotive functional safety certifications to preserve market access.
Market Dynamics
Magnetic sensing miniaturization is compressing component footprints while EU RoHS and REACH directives force contact material substitutions that ripple through cost structures and supplier qualification timelines.
Growth Catalysts
- EU RoHS mercury restrictions:Manufacturers pivoting to ruthenium and rhodium plating alternatives are capturing premium positioning in medical and aerospace niches where failure-rate tolerance sits near zero.
- Automotive position sensing:Door, lid, and proximity detection applications in electric vehicles are pulling normally open reed switch configurations into high-volume safety-critical programs.
- Japan METI JIS standards:Electromagnetic compatibility enforcement is shaping export qualification protocols that favor hermetically sealed glass envelope architectures over solid-state alternatives in certain frequency bands.
Market Restraints
- Precious metal cost volatility:Ruthenium and rhodium contact plating inputs expose margins to commodity swings that discrete component manufacturers struggle to pass through in automotive contract structures.
- Hall-effect substitution:Solid-state magnetic sensors are capturing high-frequency counting applications where reed switch mechanical cycle limits create performance ceilings.
- Supply concentration:Hermetic glass envelope production clusters in Germany and Japan, creating geographic vulnerability for qualified medical-grade component sourcing.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory alignment with FDA 21 CFR Part 820 frameworks is opening qualification pathways for sterilization-compatible reed switch integration in diagnostic equipment.
- Wireless sensor convergence:Reed switch position detectors paired with low-power RF modules are creating battery-free safety interlock systems for industrial IoT deployments.
- US IRA clean energy incentives:Battery storage and EV charging infrastructure buildouts are generating demand for galvanic-isolated level sensors in thermal management systems.
Industry Challenges
- FDA 21 CFR Part 820 compliance timelines:Medical device quality system certification stretches 18-24 months, freezing out unqualified suppliers from premium pricing tiers regardless of technical capability.
- Legacy system integration friction:Replacement of electromechanical switches in existing industrial control architectures requires signal conditioning redesigns that compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reed Switches Sensors Market |
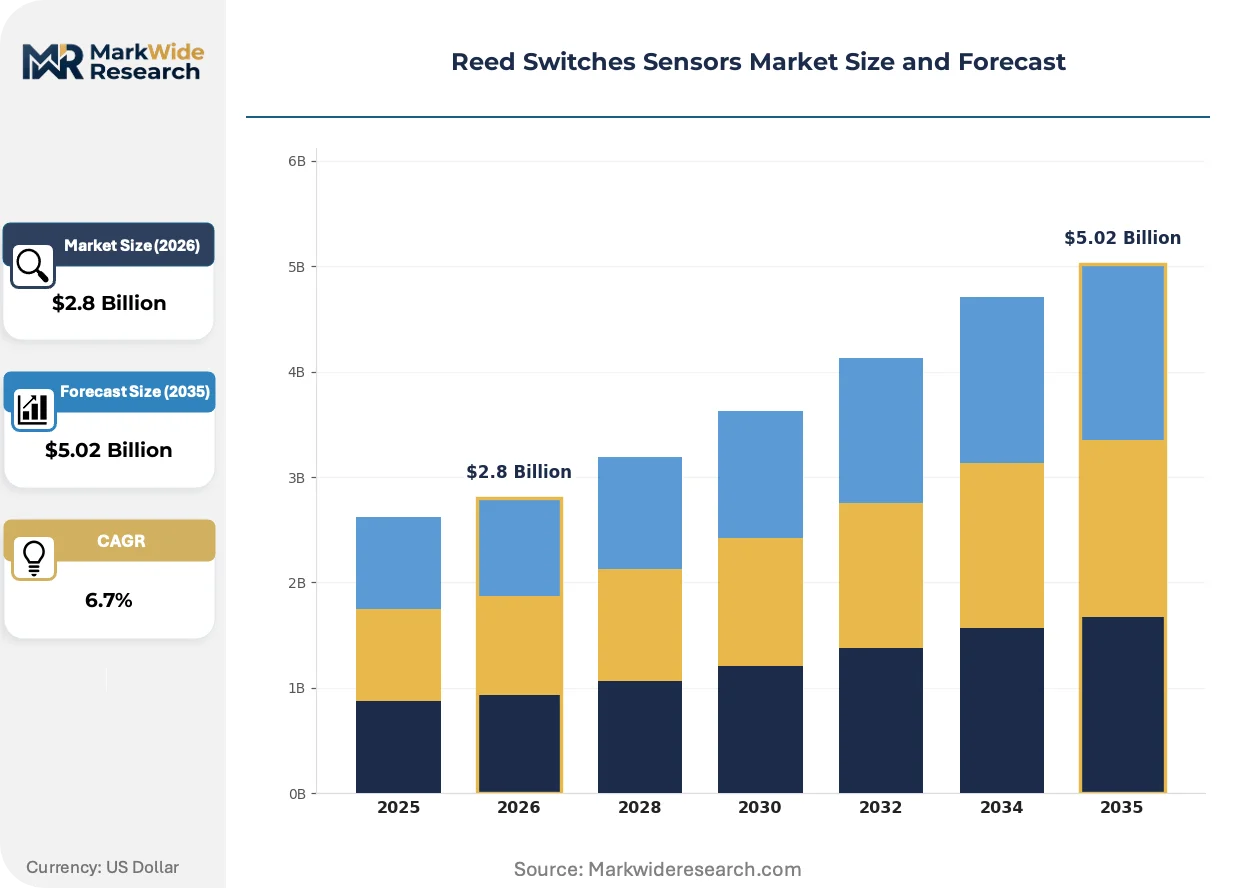
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Normally Open, Normally Closed, Form A, Form C Application: Automotive, Industrial Automation, Consumer Electronics, Medical Devices Technology: Magnetic, Hall Effect, Electromechanical, Solid State End User: Manufacturers, OEMs, Distributors, Aftermarket Providers |
| Companies Covered | Standex Electronics, Littelfuse, TE Connectivity, Coto Technology, HSI Sensing, Nippon Aleph, PIC GmbH, OKI Sensor Device, RMCIP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reed Switches Sensors Market Evolving Landscape
Reed switch architecture is evolving through material science advances, regulatory pressure on contact chemistry, and buyer consolidation in automotive tier-one supply chains.
Surface-mount reed relay packaging is digitizing placement strategies across printed circuit board assemblies. Medical device manufacturers in Switzerland and Germany are adopting tape-and-reel formats at accelerating rates. This transition is digitizing inventory management and automated assembly line configurations that previously handled through-hole components exclusively.
REACH authorization list expansions are restricting cadmium and mercury in contact plating across European manufacturing. Industrial consequence includes accelerated qualification of ruthenium-rhodium alloys that alter electrical contact resistance profiles. Automotive sensor module suppliers in Germany are responding with dual-source material strategies to preserve program access.
Buyer consolidation among automotive tier-one integrators is compressing supplier qualification cycles. Discrete component vendors face direct negotiation with integrated sensor module platforms that internalize switching functions. This concentration is most visible in United States and German automotive programs where TE Connectivity and similar platforms dominate high-volume awards.
Reed Switches Sensors Market Segmentation
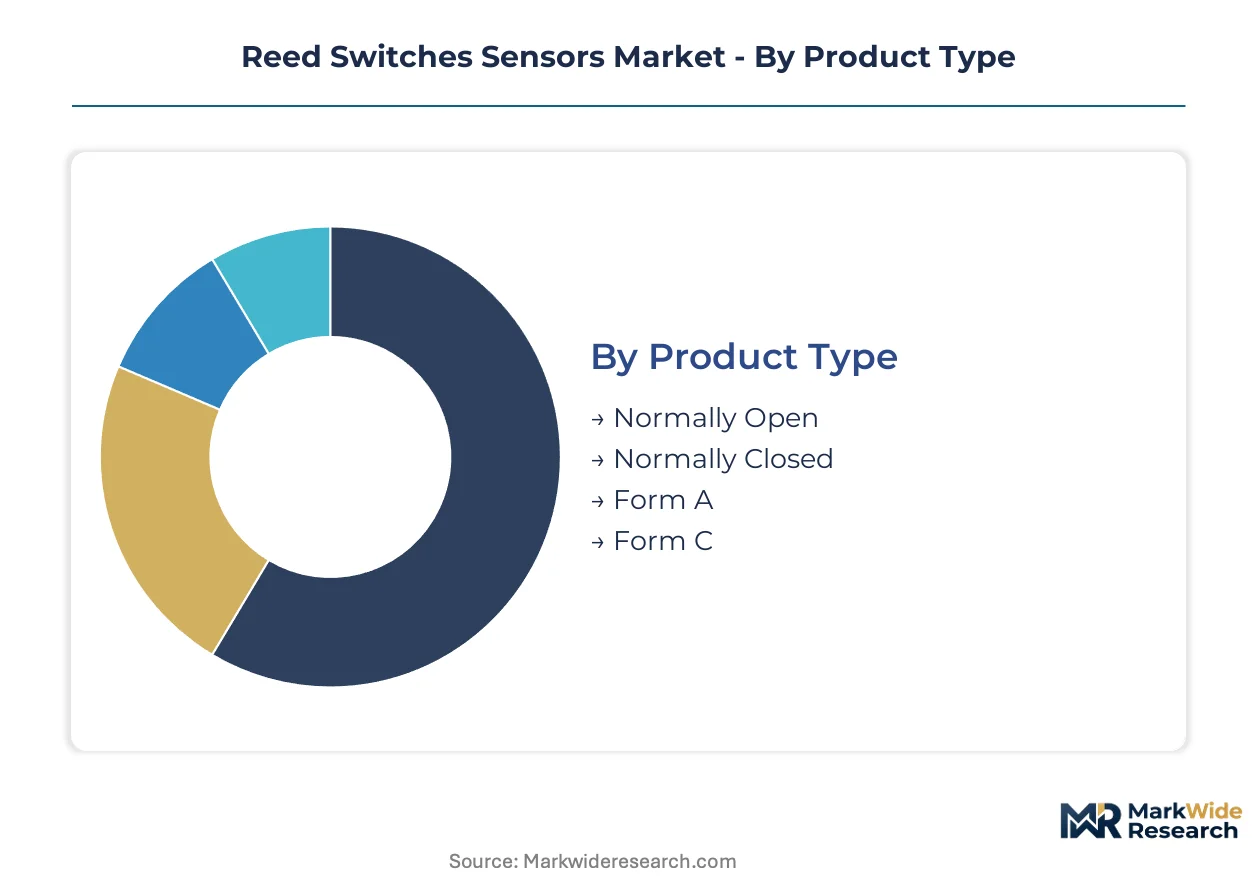
Reed switch sensor procurement cycles vary dramatically across contact configurations, end-use safety requirements, and channel structures. Understanding these velocity differences enables suppliers to align inventory positioning with qualification timelines.
Product Type:
Cycle times compress from millions of switching operations in industrial position sensing to sterilization-limited replacement schedules in medical devices, creating distinct inventory turnover profiles across contact configurations.
- Normally Open:Ferromagnetic reeds remain separated until magnetic field closure, achieving contact resistances below 100 milliohms across millions of cycles. Door, lid, and proximity detection in electric vehicle safety systems pulls this configuration into the highest-volume automotive programs where contract structures favor annual price-down trajectories.
- Form C:Single-pole double-throw architecture enables both normally open and normally closed circuits within one hermetic glass envelope. Industrial control architectures in Germany and Japan specify Form C for redundant safety interlocks where signal conditioning redesigns extend project timelines but command premium positioning.
- Normally Closed:Reeds maintain contact until magnetic field separation, serving fail-safe applications where power loss triggers circuit continuity. Emergency stop systems and security contact loops represent core demand clusters.
- Form A:Basic single-pole single-throw normally open variant dominates cost-sensitive consumer electronics where cycle life requirements sit below industrial thresholds.
Normally Open anchors the volume base while Form C gains share at the steepest rate on safety-critical industrial automation demand.
Application:
Margin structures stratify sharply across end-use certification burdens, with FDA-regulated medical tiers commanding multiples over consumer electronics where Hall-effect substitution pressure intensifies.
- Automotive:Position sensing modules for door, trunk, and charge port detection require AEC-Q100 qualification and zero-defect ppm targets. TE Connectivity and similar integrated platform suppliers dominate high-volume awards through Germany and United States electric vehicle programs.
- Medical Devices:Sterilization-compatible glass envelope architectures face FDA 21 CFR Part 820 quality system certification stretching 18-24 months. Diagnostic equipment manufacturers in Switzerland and Germany absorb premium pricing for ruthenium-plated contacts that survive autoclave cycles.
- Industrial Automation:Hermetic sealing proves essential in chemical processing and oilfield environments where galvanic isolation prevents ground loop failures. METI JIS electromagnetic compatibility standards shape export qualification for Japanese industrial OEMs.
- Consumer Electronics:Lid detection in laptops and tablets faces direct displacement from solid-state magnetic sensors in high-frequency counting roles where reed switch mechanical limits create performance ceilings.
Automotive represents the largest revenue pool while Medical Devices climbs fastest on regulatory barrier pricing.
Technology:
Architecture selection hinges on the frequency-cycling tradeoff, with electromechanical durability competing against solid-state speed in buyer technical specifications.
- Electromechanical:Glass-encapsulated ferromagnetic reed contacts achieve hermetic isolation with zero standby power draw. EU RoHS mercury restrictions push manufacturers toward ruthenium-rhodium plating alternatives that alter electrical resistance profiles and cost structures.
- Hall Effect:Solid-state magnetic sensing captures high-frequency counting applications in consumer and industrial segments where reed switch cycle limits impose performance ceilings. Silicon-based alternatives lack galvanic isolation but eliminate mechanical wear mechanisms.
- Magnetic:Broad category encompassing reed-based and other magnetic field detection principles, including GMR and AMR variants encroaching on traditional reed switch positioning.
- Solid State:Transistor-based switching eliminates moving parts entirely, favored in aerospace and military applications where vibration tolerance exceeds reed switch mechanical resonance limits.
Electromechanical retains the installed base while Hall Effect expands most quickly in frequency-sensitive applications.
End User:
Channel power concentrates in automotive tier-one integrators, compressing supplier negotiation leverage for discrete component vendors against integrated module platforms.
- OEMs:Original equipment manufacturers in automotive and medical device sectors specify reed switches at the sensor module design phase, locking in multi-year supply agreements with qualification barriers. Standex Electronics leverages captive reed relay manufacturing to sustain pricing power in aerospace and medical niches.
- Distributors:Arrow, Avnet, and regional specialists manage inventory for industrial automation and aftermarket replacement demand, absorbing precious metal cost volatility through buffer stock strategies.
- Manufacturers:Contract electronics manufacturers in India and Mexico perform subassembly integration for global OEMs, sourcing through authorized distribution to maintain traceability documentation.
- Aftermarket Providers:Independent service channels for automotive and industrial equipment require cross-reference compatibility with original specifications, limiting supplier switching flexibility.
OEMs dominate contract value while Distributors handle the widest SKU breadth across fragmented industrial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German glass envelope fabricators export sterilization-grade reed switches to Swiss medical device OEMs, establishing a precision-manufacturing corridor that concentrates high-margin component sourcing in Central Europe.
United States
Electric vehicle charging infrastructure and battery thermal management systems pull galvanic-isolated level sensors into high-volume deployment. NHTSA safety standards and IRA clean energy incentives accelerate qualification timelines for domestic sensor module integrators. Detroit-area automotive tier-one suppliers dominate contract awards for door and charge port detection programs.
Germany
Industrial automation and automotive safety systems sustain demand for hermetically sealed Form C configurations in redundant interlock architectures. EU REACH authorization expansions restrict cadmium contact plating, forcing ruthenium-rhodium alloy qualification across Bavarian manufacturing clusters. Munich and Stuttgart sensor module suppliers internalize switching functions to preserve program access against buyer consolidation.
Japan
High-frequency electromagnetic compatibility requirements in industrial equipment sustain glass envelope reed switch deployment against solid-state displacement. METI JIS standards shape export qualification protocols that favor hermetic architectures in specific frequency bands. Nagoya-area precision component manufacturers supply domestic robotics OEMs with sterilization-compatible position detectors.
Switzerland
Diagnostic equipment manufacturers absorb premium pricing for FDA 21 CFR Part 820 certified components with autoclave survivability. Swissmedic medical device regulations align with US quality system requirements, enabling dual-market qualification for Zürich and Basel-area sensor integrators. Tape-and-reel packaging adoption accelerates automated assembly line reconfiguration.
India
CDSCO regulatory alignment with FDA frameworks opens qualification pathways for sterilization-compatible reed switch integration in diagnostic equipment manufacturing. Maharashtra and Karnataka-based contract electronics manufacturers perform subassembly integration for global OEMs, sourcing through authorized distribution to maintain traceability documentation. PLI scheme incentives attract component packaging investments.
Reed Switches Sensors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure concentrates around integrated sensor module platforms that internalize switching functions, compressing negotiation leverage for discrete component vendors. Three archetypes dominate: captive reed relay manufacturers sustaining aerospace and medical pricing power; fused switch assembly specialists competing with Hall-effect alternatives; and high-volume automotive platform suppliers extending beyond discrete components. Dominant competitive moves include backward integration into contact material sourcing and strategic partnerships with automotive tier-one integrators.
Among US-based diversified electronics manufacturers, Standex Electronics and Littelfuse exemplify contrasting positioning strategies. Standex Electronics represents the captive manufacturing archetype, leveraging in-house reed relay production to defend margin structures in safety-critical niches. Littelfuse occupies a position bridging discrete components and fused assemblies, competing directly with solid-state alternatives in automotive position sensing applications. TE Connectivity anchors the integrated platform tier, dominating high-volume automotive programs through sensor module architectures that extend beyond standalone switch components.
| Leading Market Players |
|---|
| Standex Electronics |
| Littelfuse |
| TE Connectivity |
| Coto Technology |
| HSI Sensing |
| Nippon Aleph |
| PIC GmbH |
| OKI Sensor Device |
| RMCIP |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese contract electronics manufacturing is compressing component pricing across industrial automation tiers while simultaneously enabling buyers to extract annual price-down commitments from German and Japanese reed switch fabricators.
Pricing Analysis
Electromechanical-to-solid-state pricing gaps stratify procurement decisions across automotive safety systems, with legacy reed switch configurations commanding premium positioning in medical device tiers where FDA 21 CFR Part 820 certification creates qualification barriers. Pricing stratifies across premium, standard, and economy tiers based on contact material grade—ruthenium-plated medical-grade units absorb precious metal volatility while consumer electronics faces Hall-effect substitution pressure. Cost compression in automotive contract structures intensifies as TE Connectivity and similar integrated platforms internalize switching functions. Medical device OEMs in Switzerland and Germany exhibit lowest price sensitivity due to sterilization compatibility requirements, while consumer electronics manufacturers in India and Mexico drive hardest bargain on Form A variants.
Supply Chain Analysis
Arrow Electronics, Avnet, and regional authorized distributors hold dominant contract manufacturing coordination capacity for reed switch sensor subassembly integration. Hermetic glass envelope production concentrates in Germany, Japan, and select Bavarian precision manufacturing clusters. Supply chains draw from South African platinum group metals for ruthenium-rhodium plating, Japanese borosilicate glass for envelope fabrication, and Malaysian copper reeds for contact substrates. Single-source vulnerability concentrates in qualified medical-grade glass sealing equipment where German and Japanese OEMs control proprietary furnace architectures. Distribution runs through automotive tier-one integrators for high-volume programs, while industrial aftermarket demand fragments across authorized distributors maintaining buffer stocks against precious metal volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reed switch sensor procurement is consolidating around integrated module platforms that bundle position detection with signal conditioning, creating ecosystem lock-in effects as automotive OEMs standardize on TE Connectivity-style architectures.
For Market Incumbents: Insulate medical and aerospace pricing tiers through captive reed relay manufacturing investments that preserve sterilization-grade qualification barriers against Hall-effect displacement. Backward integration into ruthenium-rhodium contact material sourcing defends margin structures against commodity volatility. Prioritize FDA 21 CFR Part 820 certification maintenance as unqualified suppliers face 18-24 month exclusion from premium diagnostic equipment programs. For New Entrants and Emerging Players: India's CDSCO-aligned regulatory environment offers underpenetrated qualification pathways for sterilization-compatible reed switch integration in Maharashtra and Karnataka-based diagnostic equipment manufacturing. Target industrial IoT wireless sensor convergence applications where battery-free safety interlock systems pair reed switch position detectors with low-power RF modules. Pursue tape-and-reel packaging certification to access Swiss and German medical device automated assembly lines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive integrated sensor module sub-segments as TE Connectivity-style platforms internalize switching functions and compress discrete component vendor leverage. Long-term viability favors acquisition targets with captive glass envelope sealing capabilities and existing FDA quality system certifications. Monitor JIS electromagnetic compatibility standard enforcement timelines as signal for solid-state displacement acceleration in Japanese industrial equipment markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Material Sourcing | Ruthenium-rhodium alloy qualification preserves program access under EU REACH authorization expansions. |
| Automotive Tier-One Integrator Partnership | Direct negotiation with Detroit-area and Stuttgart-based sensor module suppliers secures high-volume electric vehicle awards. |
| Tape-and-Reel Packaging Certification | Swiss and German medical device OEMs accelerate automated assembly line reconfiguration for sterilization-compatible components. |
| Wireless Sensor Convergence Development | Battery-free industrial IoT safety interlocks pair reed switch position detection with low-power RF transmission modules. |
| CDSCO Regulatory Alignment Investment | India diagnostic equipment manufacturing opens qualification pathways for FDA 21 CFR Part 820 certified suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive Tier 1 procurement directors, medical device biomedical engineers, industrial automation maintenance directors, and authorized distribution channel managers. Secondary validation drew from FDA 510(k) filings, EU REACH authorization list updates, METI JIS standard publications, and customs trade data for precious metal contact plating inputs. Bottom-up unit shipment estimates triangulated against top-down sensor module revenue allocations across the analysis window.
Calibration anchored volume projections to observed electric vehicle program ramp schedules and diagnostic equipment manufacturing expansion timelines across the projection horizon. Segmentation modeling spanned contact configuration, end-use safety certification tier, technology architecture, and regional production cluster. CAGRs derived from weighted average of OEM contract pricing trajectories and distributor inventory turnover benchmarks. Industry-specific inputs included AEC-Q100 qualification cycle durations and autoclave survivability test protocols for medical-grade variants.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Hall-effect sensor specialists or accelerated solid-state displacement in high-frequency counting applications would shift outcomes. Quarterly review of EU REACH authorization list expansions, METI JIS electromagnetic compatibility enforcement actions, and automotive Tier 1 supplier consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
North America Switchgear Market
Switches
North America Low Voltage Switchgear Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
High-Voltage Disconnect Switch Market
Switches
Low Voltage Disconnect Switch Market
Switches
Timer Switch Socket Market
Switches
Brazil Switchgear Market
Switches
Differential Pressure Switches Market
Switches
Campus Switches Market
Switches
Zero Speed Switch Market
Switches
India Switchgear Market
Switches
Touchpad Market
Switches
Smart Pole-Mounted Switch Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
UK Reed Sensors Switches Market
Switches
Carrier Router Switch Market