
 North America Medium Voltage Switchgear Market | 2026-2036
North America Medium Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medium Voltage Switchgear Market Insights
The skilled electrical technician labor pool across the United States and Canada is collapsing, forcing utilities and industrial buyers toward switchgear designs that minimize field assembly and commissioning complexity. Eaton Corporation leverages its broad service network to sustain aftermarket revenue streams as equipment lifecycles extend. Powell Industries anchors its position through heavy-engineered custom switchgear for oil and gas and petrochemical facilities along the Gulf Coast.
North America medium voltage switchgear encompasses electrical apparatus rated between 1 kV and 52 kV that controls, protects, and isolates power circuits using vacuum interrupters or SF6-based arc quenching, with primary functions including fault interruption and load switching in distribution networks. Metal-enclosed assemblies dominate utility procurement for their compact footprint and standardized safety interlocks, while gas-insulated variants capture share in coastal and contaminated environments where maintenance access proves costly. Air-insulated platforms retain volume in commercial and light industrial settings where capital constraints favor simpler designs over sealed-system premiums.
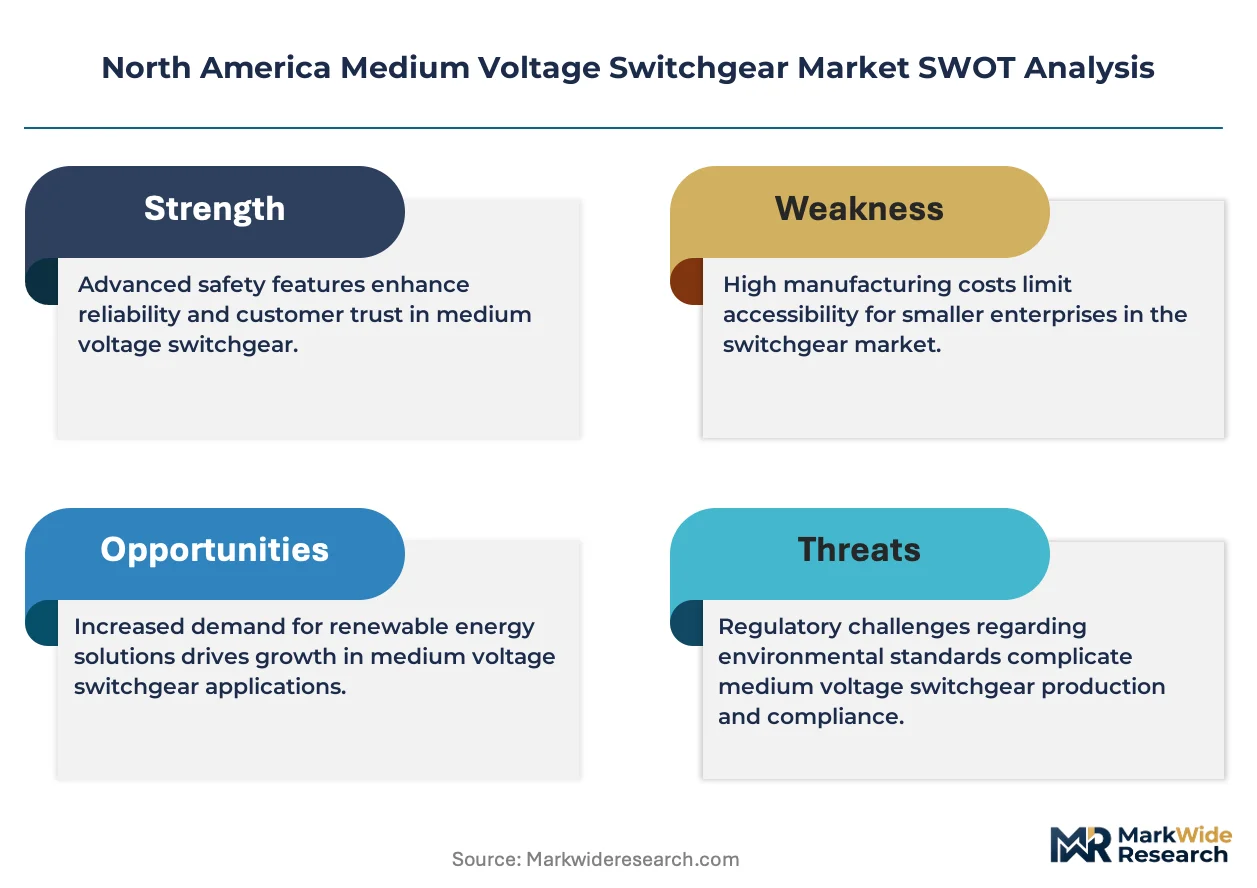
The EPA regulates sulfur hexafluoride emissions under mandatory greenhouse gas reporting rules, compelling manufacturers to certify leak rates and accelerate vacuum interrupter and clean-air insulation development. NEMA and IEEE standards govern short-circuit withstand ratings and seismic qualification, creating compliance barriers for non-domestic suppliers seeking project qualification. Stakeholders must weigh the capital cost of SF6-free platforms against emerging state-level procurement preferences and utility decarbonization commitments that increasingly exclude fluorinated gases from approved vendor lists.
Market Dynamics
The EPA's mandatory greenhouse gas reporting rules for sulfur hexafluoride are compressing design cycles across the North American medium voltage switchgear market, forcing simultaneous retooling of arc quenching technologies and supply chain qualification protocols.
Growth Catalysts
- Grid Modernization Mandates:Utilities across Texas, California, and Ontario are accelerating replacement of aging distribution infrastructure to accommodate data center load growth and renewable interconnection projects.
- SF6 Phase-Down Pressure:The EPA's tightened emission regulations are compelling manufacturers toward vacuum interrupter and clean-air insulation platforms with lower global warming potential.
- Industrial Electrification:Petrochemical and oil and gas facilities along the Gulf Coast are expanding medium voltage distribution capacity to support process electrification and carbon reduction targets.
Market Restraints
- Copper and Steel Volatility:Raw material cost swings in conductive metals and enclosure-grade steel are compressing margin visibility for fabricators of metal-enclosed switchgear assemblies.
- Specialized Component Concentration:Vacuum interrupter manufacturing concentrates among a limited supplier base in Japan and Germany, creating single-source exposure for North American OEMs.
- Seismic Qualification Burden:IEEE 693 compliance requirements for high-risk zones add engineering cost and test cycle duration that air-insulated platforms struggle to absorb.
Strategic Opportunities
- Canadian Renewable Integration:Ontario and Alberta transmission expansion projects are creating procurement windows for gas-insulated switchgear in contaminated and coastal environments.
- Digital Twin Convergence:Integration of switchgear condition monitoring with utility asset management platforms is opening recurring revenue streams for predictive maintenance services.
- Buy America Preferences:Domestic content requirements in federal infrastructure funding are tilting procurement toward US-based fabrication and assembly operations.
Industry Challenges
- Field Technician Scarcity:The collapsing skilled electrical labor pool across the United States and Canada is forcing designs that minimize on-site assembly and commissioning complexity.
- Legacy System Interoperability:Utilities operating mixed-vintage substations face integration friction when deploying smart grid communications protocols across electromechanical and microprocessor-based protection schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medium Voltage Switchgear Market |
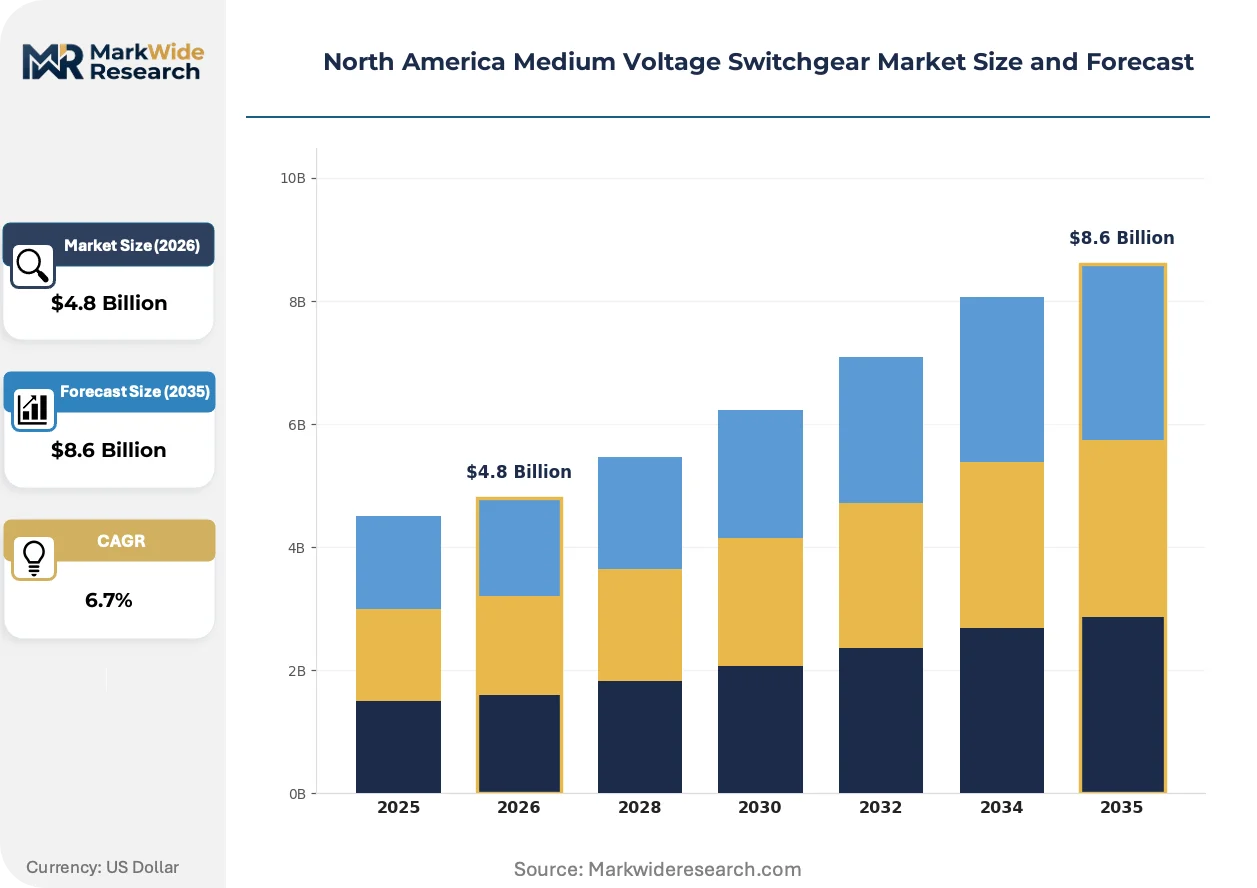
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal-Enclosed, Gas-Insulated, Air-Insulated, Modular End User: Utilities, Industrial, Commercial, Infrastructure Installation Type: Indoor, Outdoor, Substation, Marine Voltage Rating: 11 kV, 15 kV, 24 kV, Others |
| Companies Covered | Eaton Corporation plc, Powell Industries, ABB Ltd, S&C Electric, G&W Electric, Siemens AG, General Electric (GE Vernova), Hubbell Incorporated, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medium Voltage Switchgear Market Trends and Innovations
Vacuum interrupter technology is actively displacing SF6-dependent arc quenching across the North American medium voltage switchgear market, compressing equipment footprints while eliminating fluorinated gas regulatory exposure.
Clean-air insulation is decomposing the traditional trade-off between environmental compliance and equipment compactness. Utilities in California and the Pacific Northwest are specifying dry-air or nitrogen-insulated metal-enclosed switchgear for urban substations where space constraints previously favored SF6. This technology is decomposing the market segmentation between coastal premium products and inland standard designs, enabling unified procurement specifications across climate zones.
The EPA's mandatory greenhouse gas reporting rules for sulfur hexafluoride are reshaping manufacturer certification obligations. Equipment suppliers must now document leak rates and lifecycle emissions across installed bases, accelerating R&D investment in alternative insulation media. Gas-insulated switchgear for contaminated environments faces the steepest compliance cost escalation, pushing buyers toward hybrid designs that isolate vacuum interrupters within sealed clean-air enclosures.
Utility procurement departments are consolidating vendor relationships and unbundling after-sales service contracts from equipment purchases. Large municipal utilities in Texas and Arizona are negotiating multi-year framework agreements with technical performance guarantees rather than transactional capital procurement. This pattern concentrates volume among suppliers with captive service networks and compresses margins for OEMs lacking regional maintenance infrastructure.
North America Medium Voltage Switchgear Market Segmentation
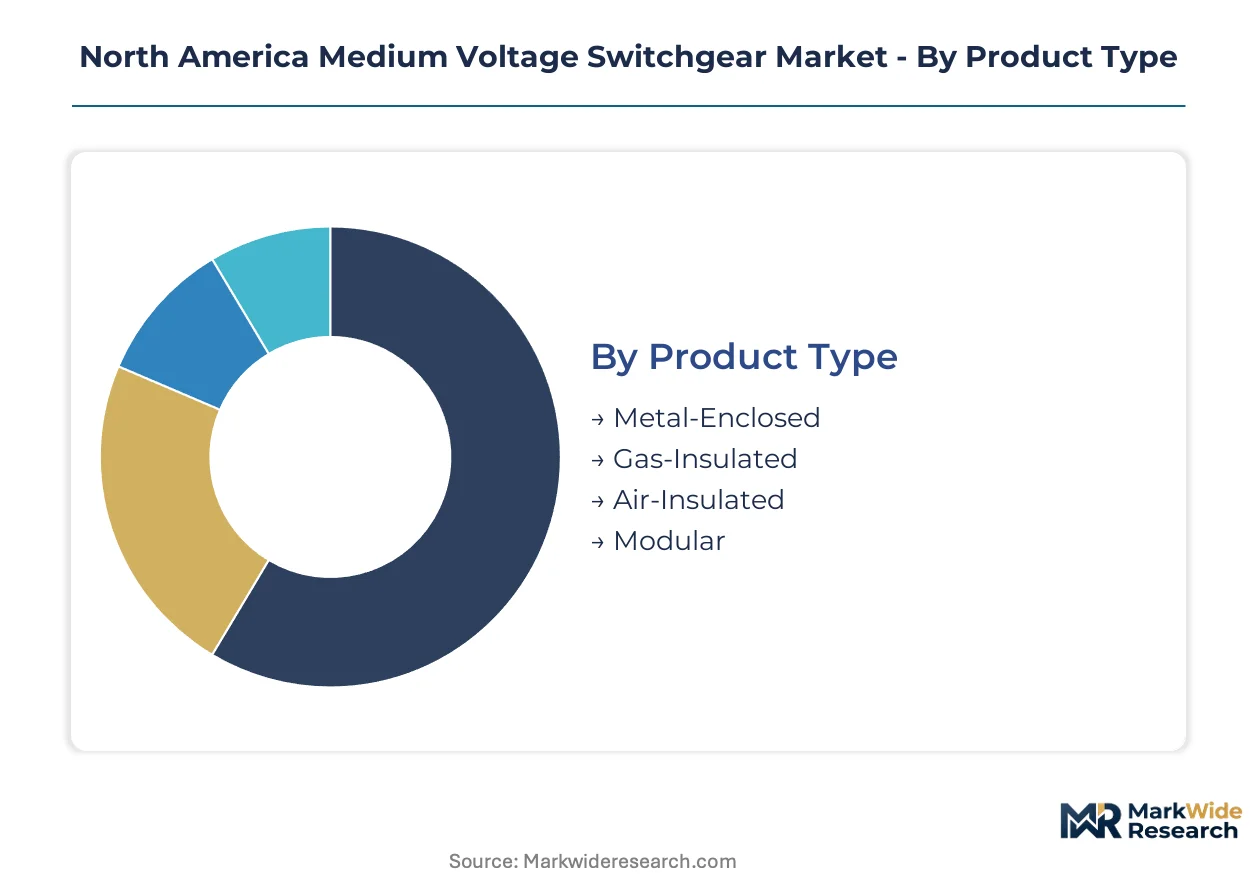
Medium voltage switchgear procurement patterns diverge sharply across product architectures and installation contexts. Channel preferences—direct utility contracts versus distributor-mediated industrial sales—shape how each segment captures value across the North American market.
Product Type:
Metal-enclosed platforms dominate utility direct procurement channels, while gas-insulated variants flow through specialized electrical contractors serving contaminated environments. Distributor networks handle air-insulated volume for commercial and light industrial buyers.
- Metal-Enclosed:These assemblies integrate vacuum interrupters, bus systems, and protection within grounded metal compartments with standardized safety interlocks. Texas and California utilities specify these for urban substations where footprint constraints and arc flash protection converge. Eaton Corporation and Powell Industries anchor this channel through captive service networks.
- Gas-Insulated:Sealed SF6 or clean-air enclosures compress equipment volume by 70% versus air-insulated equivalents, serving coastal petrochemical facilities and Ontario renewable interconnection projects. EPA emission reporting rules are accelerating migration toward dry-air alternatives in this premium tier.
- Air-Insulated:Open-frame designs with exposed bus and disconnect switches serve commercial buildings and light manufacturing where capital constraints override space limitations.
- Modular:Factory-assembled skid-mounted units minimize field wiring for data center expansions and temporary industrial power in the Permian Basin.
By volume, Metal-Enclosed leads. By growth pace, Gas-Insulated is climbing the fastest as coastal contamination and EPA compliance reshape procurement.
End User:
Cost tier segmentation separates capital-intensive utility frameworks from price-sensitive commercial procurement. Industrial buyers occupy the middle tier, balancing technical specification with total cost of ownership calculations.
- Utilities:Investor-owned and municipal operators in Texas, California, and Ontario negotiate multi-year framework agreements with technical performance guarantees. These buyers consolidate vendor relationships and unbundle service contracts from equipment purchases.
- Industrial:Petrochemical and oil and gas facilities along the Gulf Coast expand medium voltage distribution for process electrification. Heavy-engineered custom switchgear dominates this segment.
- Commercial:Office complexes, retail centers, and healthcare facilities prioritize first-cost minimization through distributor channels.
- Infrastructure:Airports, transit authorities, and water treatment plants specify seismic-qualified equipment under IEEE 693 for high-risk zones.
By revenue concentration, Utilities command the largest share. By expansion trajectory, Infrastructure is gaining share fastest as federal funding flows to grid-hardening projects.
Installation Type:
Volume patterns track geography and climate exposure. Indoor installations cluster in urban substations and controlled industrial environments, while outdoor and substation deployments concentrate in transmission expansion corridors.
- Indoor:Climate-controlled electrical rooms in data centers, hospitals, and manufacturing plants house metal-enclosed assemblies. California utilities specify these for urban density constraints.
- Outdoor:Pad-mounted and pole-top switchgear serves rural distribution networks across the Great Plains and Canadian prairies.
- Substation:Integrated high-voltage to medium-voltage transformation and switching complexes anchor renewable interconnection projects in Alberta and Texas ERCOT zones.
- Marine:Offshore platforms and port electrification demand corrosion-resistant gas-insulated platforms with sealed enclosures.
By deployment volume, Indoor leads. By project scale value, Substation is expanding most quickly.
Voltage Rating:
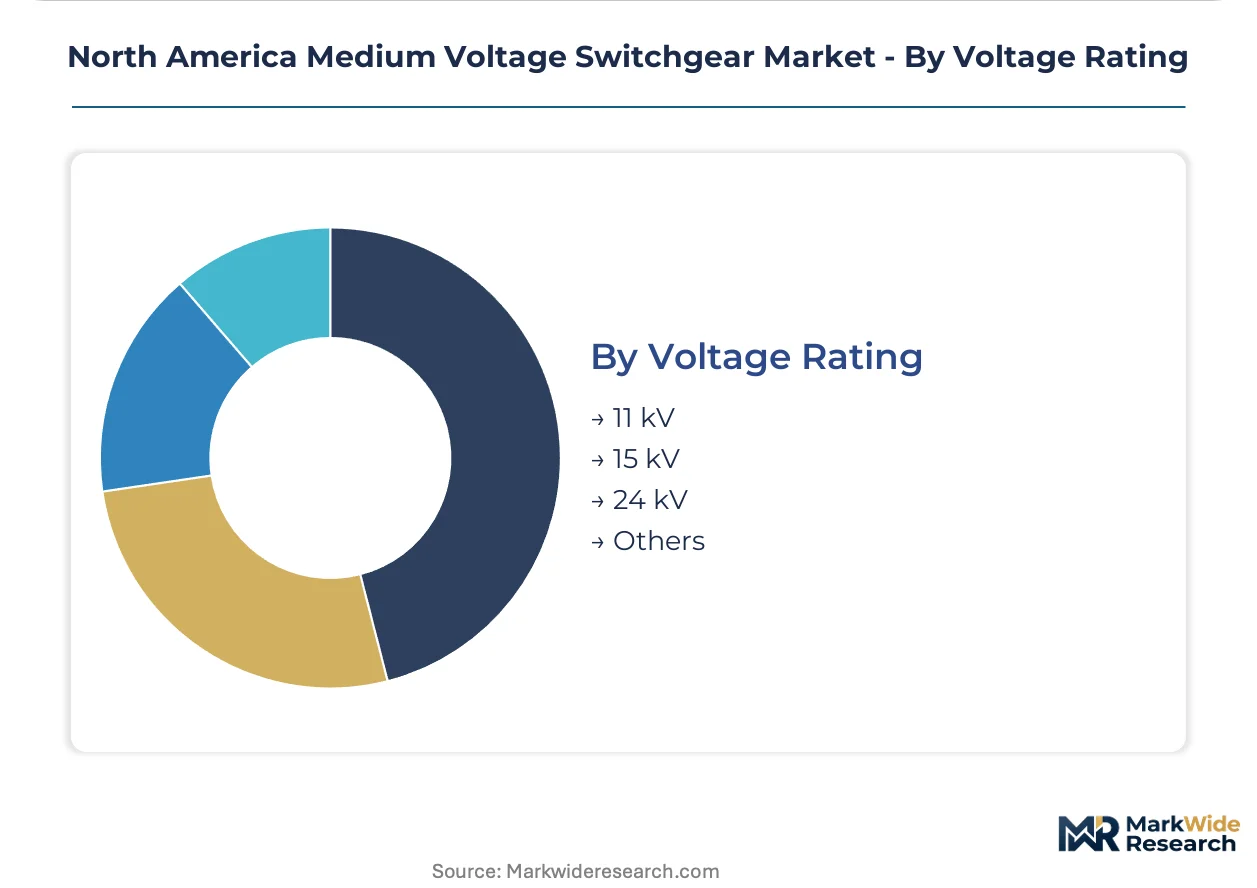
Maturity gradients separate established 15 kV infrastructure from emerging 24 kV specifications for higher-density renewable integration. Supply concentration in vacuum interrupter manufacturing shapes availability across tiers.
- 11 kV:Legacy distribution networks in older urban cores and light commercial applications retain this established standard.
- 15 kV:The dominant utility specification across North American distribution systems, with standardized short-circuit ratings and interchangeable components.
- 24 kV:Higher insulation levels accommodate renewable generation clustering and data center load density in California and Texas interconnection queues.
- Others:Specialized 27 kV and 38 kV ratings serve heavy industrial and primary distribution applications with custom engineering requirements.
By installed base, 15 kV dominates. By specification momentum, 24 kV shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America. The United States concentrates procurement in utility-scale grid modernization and data center infrastructure. Canada emphasizes renewable interconnection and harsh-environment equipment for remote locations. Mexico channels investment toward industrial electrification and cross-border manufacturing clusters.
United States
Texas and California utilities drive procurement volume through ERCOT grid expansion and renewable interconnection queues. The EPA's mandatory SF6 greenhouse gas reporting rules compress design cycles for manufacturers serving these markets. Data center load growth in Northern Virginia and Phoenix strains existing distribution networks, forcing accelerated switchgear deployment.
Canada
Ontario and Alberta transmission expansion projects create procurement windows for gas-insulated platforms in contaminated and coastal environments. Health Canada and provincial regulators align with federal decarbonization commitments that increasingly exclude fluorinated gases from approved vendor lists. Hydro One and provincial utilities prioritize factory-assembled modular units to minimize field commissioning in remote northern locations.
Mexico
Nuevo León and the Bajío Region anchor industrial electrification demand from automotive and aerospace manufacturing expansion. The Comisión Federal de Electricidad modernizes distribution infrastructure to support nearshoring manufacturing clusters. Gulf Coast petrochemical facilities specify corrosion-resistant sealed enclosures for salt-laden operating environments.
North America Medium Voltage Switchgear Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Diversified electrical equipment conglomerates leverage captive service networks and broad product portfolios to capture multi-year utility framework agreements. Engineering-intensive specialists anchor positions through heavy-customized solutions for oil and gas and petrochemical applications. Competitive moves concentrate on vertical integration into vacuum interrupter supply chains and geographic expansion of regional service infrastructure.
Within the integrated multinational tier, Eaton Corporation plc and Siemens AG exemplify archetypes combining broad product scope with dense North American service footprints. Powell Industries occupies a specialist position, anchoring Gulf Coast industrial demand through heavy-engineered custom fabrication. These three represent the dominant competitive vectors: diversified platform breadth, regional service density, and application-specific engineering depth.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Powell Industries |
| ABB Ltd |
| S&C Electric |
| G&W Electric |
| Siemens AG |
| General Electric (GE Vernova) |
| Hubbell Incorporated |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day lead times for vacuum interrupter procurement from Japanese and German suppliers concentrate pricing power among incumbent OEMs with captive service networks, compressing margin visibility for fabricators lacking long-term component offtake agreements.
Pricing Analysis
Long-term framework agreements dominate utility procurement, with Texas and California municipal operators negotiating multi-year contracts that unbundle equipment from aftermarket service. Price differentiation rests on IEEE certification tier and regional service density, with seismic-qualified platforms commanding premiums in high-risk zones. Cost compression in air-insulated tiers intensifies as copper and steel volatility erodes fabricator margins. Commercial buyers through distributor channels exhibit highest price sensitivity, while Gulf Coast petrochemical facilities prioritize total cost of ownership over first-cost minimization.
Supply Chain Analysis
Strait of Malacca transit risk for specialty steel alloys and copper cathodes from Chile and Peru elevates inventory carrying costs for enclosure fabricators. Vacuum interrupter manufacturing concentrates in Japan and Germany, creating single-source exposure for North American OEMs. Supply chain risk centers on tariff exposure for Chinese-sourced bus bar and insulation materials. Distribution runs through direct utility contracts for metal-enclosed assemblies, specialized electrical contractors for gas-insulated platforms, and broad-line distributors for commercial air-insulated volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat industry where EPA emission reporting requirements and IEEE certification barriers create entrenched switching costs for approved vendors, defending incumbent positions against import competition.
For Market Incumbents: Secure captive vacuum interrupter supply through backward integration or exclusive offtake agreements with Japanese suppliers, insulating margin structures from component scarcity. Expand regional service infrastructure in Texas and Ontario to capture unbundled maintenance contracts from framework agreement utilities. Threat of SF6 phase-down regulations demands accelerated clean-air platform R&D investment to maintain approved vendor status. For New Entrants and Emerging Players: IEEE 693 seismic certification fast-track offers entry path through infrastructure segment procurement windows, where federal grid-hardening funding creates qualification opportunities outside entrenched utility relationships. Target modular skid-mounted switchgear for data center expansions in Northern Virginia and Phoenix, where project velocity favors new suppliers over legacy framework incumbents. Go-to-market angle: factory-integrated digital twin condition monitoring as bundled value-add. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized North American fabrication assets and dormant IEEE certifications. Long-term viability favors suppliers with vertical integration into vacuum interrupter supply chains and dense regional service footprints. Signal to watch: Ontario and Alberta transmission expansion project award announcements as inflection indicator for gas-insulated platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Interrupter Supply Agreement | Captive sourcing from Japanese suppliers secures component availability for EPA-compliant platform rollout. |
| Seismic Qualification Investment | IEEE 693 certification opens federal infrastructure funding channels in high-risk seismic zones. |
| Digital Twin Integration | Condition monitoring convergence with utility asset management platforms creates recurring service revenue. |
| Clean-Air Platform Launch | Dry-air insulation development eliminates SF6 regulatory exposure for California and Pacific Northwest utilities. |
| Regional Service Expansion | captive maintenance infrastructure in Texas and Ontario captures unbundled aftermarket contracts from framework agreements. |
Research Methodology
Desk research of EPA regulatory filings, IEEE standards documentation, and utility procurement databases preceded structured interviews with utility planning officers, EPC contractors, switchgear procurement managers, and aftermarket service directors. Primary fieldwork across Texas, California, and Ontario markets combined with secondary validation from FERC interconnection queues, EIA grid infrastructure reports, and provincial utility capital expenditure disclosures. Bottom-up project pipeline analysis triangulated against top-down market sizing from equipment shipment tracking.
Variance decomposition across product architecture, voltage rating, installation type, and end-use sector shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EPA regulatory timeline assumptions, raw material cost trajectory projections, and utility capital commitment patterns from identified framework agreement holders.
The analysis sits within stated boundaries; outcomes outside sustained federal infrastructure funding flows or accelerated SF6 phase-down timelines would require recalibration. Forecasts reflect documented assumptions regarding vacuum interrupter supply availability and copper price stability. Revision becomes warranted when EPA emission rule stringency crosses implementation thresholds or seismic qualification requirements expand to additional state jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Miniature-Circuit Breaker Market
Switches
North America Switchgear Market
Switches
Residual Current Circuit Breaker Market
Switches
Membrane Switch Market
Switches
Ethernet Switch Market
Switches
Antenna Switch Module Market
Switches
Low Voltage Switchgear Market
Switches
Static Transfer Switches Market
Switches
Differential Pressure Switches Market
Switches
Low Voltage Disconnect Switch Market
Switches
Smart Plugs and Switches Market
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
South Korea Reed Sensors Switches Market
Switches
Europe Switchgear Market
Switches
KVM Switch Market
Switches
Electric Switch Market