
 Smart Energy Switch Market | 2026-2036
Smart Energy Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Energy Switch Market Insights
Germany's manufacturing base for smart home components is fragmenting as Asian competitors enter with lower-cost Zigbee modules. Schneider Electric leverages its European distribution network to sustain premium positioning in three-phase industrial installations. Legrand anchors its position through backward integration into proprietary cloud-connected firmware stacks. TP-Link competes aggressively on price in the Wi-Fi switch segment across Southeast Asian export markets.
A smart energy switch is an electromechanical or solid-state device equipped with wireless communication protocols, typically operating at 120-240V AC with load ratings between 10-20 amps, designed to enable remote or automated control of electrical circuits while capturing real-time consumption data for demand-side management. Wi-Fi switches currently dominate residential retrofit volumes due to router compatibility, yet Zigbee switches capture disproportionate margin pools in multi-device commercial deployments where mesh reliability matters. Cloud-connected technology leads R&D allocation as vendors race to integrate utility-grade demand response APIs directly at the switch level.
The US Inflation Reduction Act directs consumer tax credits toward qualifying smart panel upgrades, while the EU F-Gas Regulation indirectly pressures building managers to adopt precise HVAC switching controls that minimize refrigerant leakage events. India's BIS certification mandates for IoT devices create compliance friction for imported standalone units. Stakeholders must weigh the capital intensity of cloud platform ownership against the margin compression from white-label hardware commoditization.
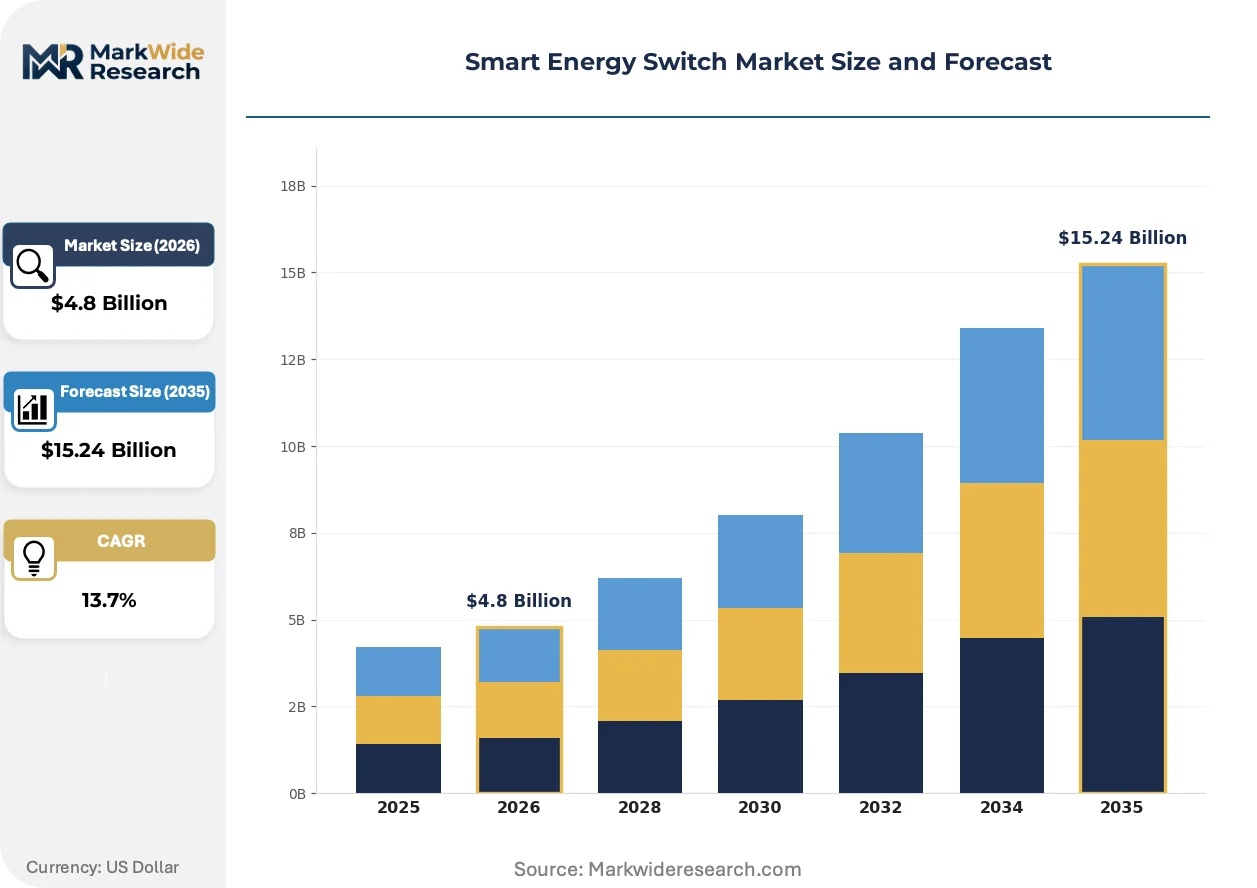
Market Dynamics
The smart energy switch market pivots on utility-grade demand response API integration at the device level, compressing hardware margins while elevating firmware and cloud platform ownership as the primary value capture mechanism.
Growth Catalysts
- US Inflation Reduction Act:Tax credits for building electrification retrofits accelerate residential smart panel procurement across single-family and multifamily housing stock.
- Germany's energy transition mandate:Residential smart metering rollout requirements by decade's end create installed-base obligations for Zigbee-enabled switches in new construction and renovation.
- Mesh protocol reliability:Commercial building automation systems prioritize Zigbee over Wi-Fi for multi-device deployments where network resilience determines operational uptime.
Market Restraints
- Semiconductor input volatility:Power management ICs and RF modules face allocation constraints from concentrated foundry capacity in East Asia, pressuring bill-of-materials stability.
- India BIS certification friction:IoT device mandates create compliance timelines and testing costs that disadvantage imported standalone units against domestic assembly operations.
- Wi-Fi protocol saturation:Residential retrofit segments face price compression as router-compatible hardware commoditizes, eroding margin pools for non-differentiated suppliers.
Strategic Opportunities
- Southeast Asian export manufacturing:Vietnam and Indonesia offer tariff-advantaged production bases for Wi-Fi switch assembly serving Australian and Middle Eastern markets.
- EU F-Gas Regulation:HVAC switching control precision requirements create specification pull for switches with sub-second response capabilities in commercial refrigeration and climate systems.
- Cloud-native firmware stacks:Backward integration into proprietary connectivity platforms enables recurring revenue models and customer lock-in beyond hardware shipment economics.
Industry Challenges
- Embedded systems engineering scarcity:Demand for engineers with simultaneous competence in power electronics, RF protocols, and cybersecurity outstrips supply in European and North American labor markets.
- Legacy electrical infrastructure interoperability:Three-phase industrial installations require backward compatibility with decades-old control voltage standards, complicating product architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Energy Switch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Switches, Wi-Fi Switches, Zigbee Switches, Bluetooth Switches End User: Residential Users, Commercial Buildings, Industrial Facilities, Utility Providers Installation Type: Single Phase, Three Phase, Integrated Systems, Standalone Units Technology: IoT-Based, Cloud-Connected, Energy Monitoring, Remote Control |
| Companies Covered | Schneider Electric, Legrand, Leviton, TP-Link, GE, Eaton, Honeywell, Belkin, Lutron Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Energy Switch Market Trends and Innovations
Edge-native intelligence is redistributing computational load from cloud servers to switch-level processors, enabling sub-second demand response without persistent internet connectivity while reshaping supplier R&D allocation.
Solid-state relay technology is collapsing the functional boundary between electromechanical switching and power electronics. Industrial facility managers in Germany and the US are specifying silicon carbide-based switches for motor control applications where arc elimination reduces maintenance intervals. This displacement is compressing the addressable market for traditional relay suppliers while expanding margins for semiconductor-integrated module vendors.
The EU F-Gas Regulation is mandating precise HVAC switching controls to minimize refrigerant leakage events in commercial buildings. Facility operators in France and the Netherlands are retrofitting existing climate systems with API-connected switches that log cycle counts and pressure transitions for compliance documentation. The regulation is elevating switch specification from commodity procurement to environmental risk management.
Buying patterns among North American electrical contractors are fragmenting as distributor consolidation meets direct-to-installer e-commerce platforms. Contractors in Texas and California are increasingly sourcing Wi-Fi switches through Amazon Business and specialized trade marketplaces rather than traditional wholesale electrical supply houses. This channel rotation is compressing distributor margins while rewarding suppliers with logistics infrastructure capable of same-day fulfillment.
Smart Energy Switch Market Segmentation
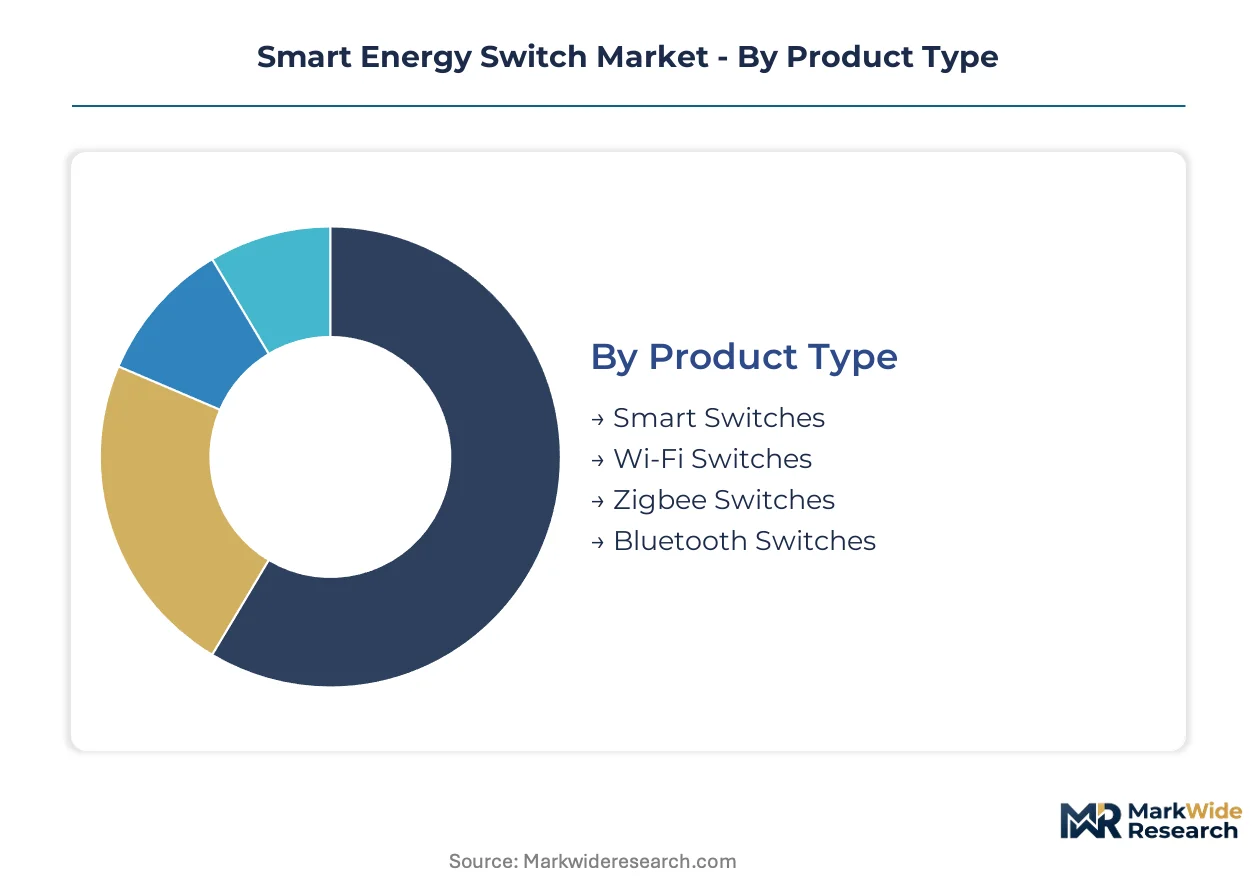
Smart energy switch segmentation reveals competing technology stacks battling for installation preference across retrofit and new construction workflows. Protocol choice, phase configuration, and connectivity architecture each create distinct margin profiles and customer lock-in mechanisms.
Product Type:
Mature electromechanical designs coexist with emerging solid-state alternatives, fragmenting supplier specialization across residential and industrial voltage classes.
- Smart Switches:Encompasses programmable electromechanical and solid-state devices with embedded microcontrollers for scheduling and scene control. Demand concentrates in North American residential retrofits where the US Inflation Reduction Act tax credits reduce installed cost barriers for single-family electrification upgrades.
- Wi-Fi Switches:Router-native devices operating on 2.4GHz and 5GHz bands eliminate gateway requirements for consumer installations. Southeast Asian export manufacturing clusters in Vietnam and Indonesia supply price-competitive units for Australian and Middle Eastern markets where distributor consolidation has weakened traditional channel control.
- Zigbee Switches:Mesh-networked modules with sub-1GHz and 2.4GHz variants enabling multi-hop reliability in dense commercial deployments. Germany's residential smart metering mandates create specification pull for Zigbee-enabled units in new construction and renovation projects through decade's end.
- Bluetooth Switches:Point-to-point and mesh variants for localized control without internet dependency. Industrial facility managers in France specify Bluetooth LE for maintenance access points where cloud connectivity introduces cybersecurity exposure.
Wi-Fi switches retain volume leadership in residential retrofit channels; Zigbee switches hold the steepest expansion curve in multi-device commercial building automation.
End User:
Customer type determines specification rigor, with utility procurement imposing certification burdens that exclude consumer-grade suppliers.
- Residential Users:Homeowners and renters prioritizing smartphone control and voice assistant integration. US single-family and multifamily housing stock drives procurement acceleration through IRA-enabled smart panel upgrades.
- Commercial Buildings:Office, retail, and hospitality operators requiring centralized building management system integration. EU F-Gas Regulation compliance in France and the Netherlands elevates HVAC switching precision to environmental risk management procurement.
- Industrial Facilities:Manufacturing and logistics operations demanding three-phase compatibility and arc-flash mitigation. German and US facility managers specify silicon carbide-based solid-state relays for motor control applications where maintenance interval reduction justifies premium positioning.
- Utility Providers:Grid operators procuring IoT-enabled switches for demand response aggregation and voltage regulation. North American utilities accelerate edge-control modernization to manage distributed solar and EV charging load variability.
Residential users generate the highest unit volumes; utility providers command the most stringent certification requirements and longest contract cycles.
Installation Type:
Phase configuration and system architecture create distinct engineering competencies and field service requirements.
- Single Phase:120-240V AC devices for residential and light commercial circuits. Dominates North American retrofit volumes where existing electrical infrastructure requires minimal modification.
- Three Phase:208-480V AC configurations for industrial motor control and commercial HVAC. Schneider Electric sustains premium positioning through European distribution network depth in three-phase industrial installations.
- Integrated Systems:Pre-wired switch assemblies with embedded energy monitoring and communication modules. Legrand anchors market position through backward integration into proprietary cloud-connected firmware stacks.
- Standalone Units:Discrete replacement devices compatible with legacy electrical boxes. India's BIS certification mandates create compliance friction for imported units, advantaging domestic assembly operations.
Standalone units dominate residential replacement demand; integrated systems are climbing fastest in new commercial construction specifications.
Technology:
Connectivity architecture and computational location determine recurring revenue potential and cybersecurity exposure.
- IoT-Based:Devices with embedded sensors and wireless transceivers for networked operation. Mesh protocol reliability priorities in commercial building automation favor Zigbee and Thread implementations over Wi-Fi for operational uptime.
- Cloud-Connected:Switches with persistent internet connectivity for remote management and API integration. Vendors race to integrate utility-grade demand response APIs directly at the switch level, compressing hardware margins while elevating platform ownership value.
- Energy Monitoring:Sub-metering capabilities capturing real-time consumption data for demand-side management. Edge-native intelligence redistribution enables sub-second response without persistent connectivity, reshaping R&D allocation toward switch-level processors.
- Remote Control:Smartphone, web portal, and voice assistant interfaces for user-initiated operation. Texas and California electrical contractors increasingly source through Amazon Business and specialized trade marketplaces rather than traditional wholesale channels.
Cloud-connected technology commands the largest R&D allocation; edge-native energy monitoring is gaining share fastest as grid-edge intelligence requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act anchors demand acceleration through tax credits for building electrification retrofits, while utility-grade procurement specifications concentrate in North American and European markets where grid modernization mandates drive IoT-enabled switch adoption.
United States
Single-family and multifamily housing stock drives residential smart panel procurement through IRA-enabled upgrades. The US Department of Energy coordinates with FERC on demand response aggregation standards for distributed solar and EV charging load management. Texas and California electrical contractors increasingly source Wi-Fi switches through Amazon Business and specialized trade marketplaces rather than traditional wholesale channels.
Germany
The national energy transition mandates residential smart metering rollouts by decade's end, creating installed-base obligations for Zigbee-enabled switches in new construction and renovation. The KBA and federal network regulator enforce interoperability standards for grid-edge devices. Industrial facility managers in Bavaria and North Rhine-Westphalia specify silicon carbide-based solid-state relays for motor control applications where maintenance reduction justifies premium positioning.
France
Commercial building operators retrofit HVAC systems with API-connected switches to log cycle counts and pressure transitions for EU F-Gas Regulation compliance documentation. ANSM and environmental regulators mandate precise switching controls to minimize refrigerant leakage events in climate systems. Facility operators in Île-de-France and Auvergne-Rhône-Alpes elevate switch specification from commodity procurement to environmental risk management.
India
BIS certification mandates for IoT devices create compliance friction for imported standalone units, advantaging domestic assembly operations. The CEA and central electricity authority coordinate smart grid pilot programs in urban distribution networks. Manufacturing clusters in Maharashtra and Gujarat assemble price-competitive Wi-Fi switches for Middle Eastern and African export markets.
Vietnam
Tariff-advantaged production bases for Wi-Fi switch assembly serve Australian and Middle Eastern markets where distributor consolidation has weakened traditional channel control. The Ministry of Industry and Trade oversees electronics manufacturing incentives under national industrial development frameworks. Export-oriented facilities in Ho Chi Minh City and Hanoi supply router-compatible hardware for Southeast Asian residential retrofit volumes.
Smart Energy Switch Market Competitive Landscape
Electrical infrastructure incumbents and consumer electronics specialists split the market along voltage-class and protocol-specialization lines. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with three-phase installation expertise, residential connectivity specialists with cloud-native firmware stacks, and contract manufacturers competing on Southeast Asian export assembly economics. Consolidation pressure manifests through backward integration into proprietary connectivity platforms and geographic expansion into tariff-advantaged production jurisdictions.
Within the diversified industrial tier, Schneider Electric and Legrand occupy positions defined by European distribution network depth and integrated firmware development capabilities. TP-Link exemplifies the consumer-electronics archetype competing aggressively on Wi-Fi switch price positioning across Southeast Asian export markets. These three anchors illustrate how competitive advantage separates between premium three-phase industrial specifications and high-volume residential retrofit economics.
| Leading Market Players |
|---|
| Schneider Electric |
| Legrand |
| Leviton |
| TP-Link |
| GE |
| Eaton |
| Honeywell |
| Belkin |
| Lutron Electronics |
| Others |
Pricing and Supply Chain Analysis
Semiconductor input volatility from concentrated East Asian foundry capacity compresses hardware margins across all tiers while simultaneously forcing supply chain restructuring toward tariff-advantaged assembly jurisdictions. This dual pressure widens pricing spreads between premium three-phase industrial specifications and commoditized residential Wi-Fi units.
Pricing Analysis
Geographic price spreads separate German industrial installations from Southeast Asian export markets by a factor reflecting certification burden and phase complexity. Three-tier pricing structure across premium, standard, and economy levels tracks voltage class and protocol reliability, with Zigbee-enabled commercial units commanding substantial premiums over router-compatible Wi-Fi alternatives. Cost compression in the residential retrofit tier is intensifying because white-label hardware commoditization erodes non-differentiated supplier margins. Electrical contractors sourcing through Amazon Business exhibit the highest price sensitivity, while utility procurement officers prioritize interoperability certification over unit economics.
Supply Chain Analysis
Tariff exposure between Vietnam and Australia dominates supply chain risk calculations for Wi-Fi switch exporters serving Middle Eastern transit markets. Manufacturing concentration in Vietnam, Indonesia, and India draws from power management ICs and RF modules produced in Taiwan and South Korea, creating single-source vulnerability for semiconductor inputs. Distribution runs through consolidating electrical wholesale houses in North America and direct-to-installer e-commerce platforms in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart energy switch market sits in a cyclical recovery phase anchored by building electrification mandates and grid-edge modernization spending. Capital deployment should anticipate hardware margin compression reversing only as firmware platform ownership consolidates.
For Market Incumbents: Insulate premium positioning in three-phase industrial segments through captive supply of silicon carbide-based solid-state relay modules and exclusive distribution agreements with European electrical contractors. Backward integration into proprietary cloud-connected firmware stacks creates switching costs that resist Asian competitor encroachment on Zigbee commercial deployments. For New Entrants and Emerging Players: India's underpenetrated smart metering retrofit market offers white-space opportunity where BIS certification requirements disadvantage imported standalone units against domestic assembly operations. Target Maharashtra and Gujarat manufacturing clusters for tariff-advantaged production serving African and Middle Eastern export demand, leveraging direct e-commerce relationships with Australian electrical contractors to bypass distributor consolidation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform owners over pure-play hardware vendors. Five-to-ten-year viability hinges on recurring revenue from demand response API integration rather than transactional switch shipments. Acquisition targets should demonstrate utility-grade certification progress and embedded systems engineering depth. The signal to watch is FERC demand response aggregation standard finalization, which will determine platform economics for grid-edge control vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Firmware Stacks | Legrand's proprietary cloud connectivity enables recurring revenue models beyond hardware economics. |
| Tariff-Advantaged Manufacturing Expansion | Vietnam and Indonesia assembly bases serve Australian markets with weakened distributor channel control. |
| Utility-Grade Certification Investment | FERC interoperability standards determine eligibility for North American demand response procurement. |
| Solid-State Relay Technology Transition | Silicon carbide modules eliminate arc maintenance in German and US industrial motor control applications. |
| Direct E-Commerce Channel Development | Amazon Business relationships with Texas and California contractors compress traditional wholesale margins. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, electrical contractor procurement managers, building automation system integrators, and semiconductor supply chain specialists, then refined against secondary validation from FERC filings, EIA grid modernization databases, EU F-Gas Regulation implementation guidance, and customs trade data for Wi-Fi switch exports. Bottom-up segmentation modeling triangulated with top-down market sizing from utility procurement disclosures and residential retrofit incentive program tracking.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by protocol type, voltage class, connectivity architecture, end-use sector, and regional regulatory cluster. CAGRs derived from installed-base obligations under Germany's energy transition mandate and US IRA-enabled smart panel upgrade trajectories, cross-referenced against foundry capacity allocation forecasts for power management ICs.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, industrial capital expenditure cycles, or East Asian semiconductor allocation would shift the trajectory. Forecasts reflect assumptions about regulatory implementation timelines and interoperability standard adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
China Smart Grid Network Market
Smart Grid
Europe Automated Demand Response Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Demand Response Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
South Africa Smart Grid Network Market
Smart Grid
Smart Demand Response Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
Microgrid Controller Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Smart Grid Technology Market
Smart Grid
Smart Grid Market