
 Saudi Arabia Interior Design Market | 2026-2036
Saudi Arabia Interior Design Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Interior Design Market Analytics
A shift from single-source procurement to multi-source vendor engagement is realigning how Saudi developers contract interior fit-out work. Modassic leverages its project management capabilities to secure large-scale hospitality contracts across the Kingdom. Yasmeen Interiors anchors its position through specialized traditional design services targeting high-net-worth residential clients. Antonovich Group competes on the strength of its custom furniture manufacturing and in-house production capacity.
Interior design encompasses the planning, specification, and coordination of spatial environments, integrating furniture, fixtures, flooring, and wall coverings to achieve functional and aesthetic outcomes aligned with building codes and client requirements. The discipline applies material science, lighting design, and ergonomic principles to commercial, residential, hospitality, and retail settings where occupancy patterns and brand expression dictate spatial layouts. Furniture and fixtures capture the dominant share of project value given their centrality to space functionality and visual identity. Custom design services within the service type dimension command premium pricing as clients seek differentiated environments in Riyadh's competitive luxury residential market.
SFDA material safety standards and SASO technical regulations govern product compliance for interior finishes, while municipal building codes in Riyadh, Jeddah, and Dammam enforce fire-rated specifications and accessibility requirements that filter vendor eligibility. The Saudi Building Code, administered by the National Committee for Building Code, mandates structural and safety parameters that interior systems must accommodate during retrofit and new construction. Stakeholders must monitor how evolving green building criteria and energy performance standards will reshape material selection and design documentation requirements across upcoming megaproject developments.
Market Dynamics
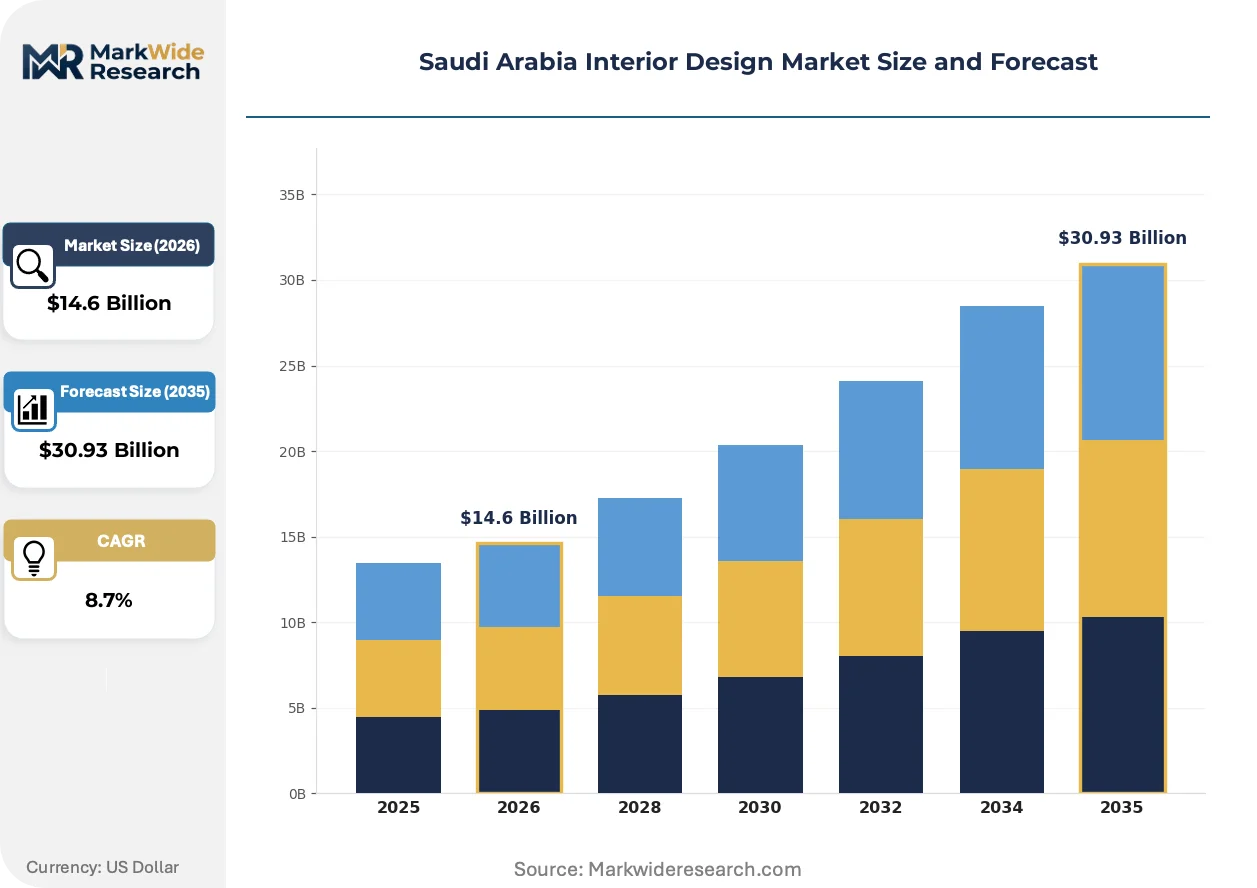
The Saudi Arabia Interior Design Market is experiencing structural pressure from megaproject-driven demand concentration, where Riyadh's giga-developments are compressing procurement timelines and forcing vendor consolidation among fit-out contractors.
Growth Catalysts
- SFDA Material Safety Protocols:The Saudi Food and Drug Authority's building material certification requirements are filtering out low-grade suppliers and creating premium positioning opportunities for compliant vendors serving hospitality and healthcare interiors.
- Hospitality Fit-Out Surge:Hotel and resort developments across Riyadh and Jeddah are generating concentrated demand for luxury fixtures, custom millwork, and integrated lighting systems.
- SASO Energy Efficiency Mandates:The Saudi Standards, Metrology and Quality Organization's tightening HVAC and lighting specifications are accelerating specification upgrades in commercial and residential projects.
Market Restraints
- Imported Fixture Dependency:High-end furniture and specialty lighting systems rely heavily on European and Asian manufacturing, exposing projects to currency volatility and extended lead times.
- Specialized Labor Scarcity:Certified interior project managers and BIM-capable designers remain concentrated in Riyadh and Jeddah, constraining execution capacity in secondary cities.
- Saudi Building Code Compliance Costs:Fire-rated materials and accessibility retrofit requirements add 15-25% to material specifications for older building conversions.
Strategic Opportunities
- NEOM and Red Sea Project Corridors:The Kingdom's western development zone offers first-mover positioning for design firms capable of delivering sustainable, tourism-oriented interiors at scale.
- Smart Home Integration:Convergence of IoT-enabled lighting controls with interior specification workflows creates service bundling opportunities for residential developers.
- Local Manufacturing Incentives:Saudi Industrial Development Fund financing for domestic furniture production reduces import dependency for standardized hospitality fixtures.
Industry Challenges
- BIM Implementation Gaps:Many mid-tier contractors lack Building Information Modeling capabilities, creating coordination failures between architects and interior execution teams.
- Certification Timeline Compression:SASO and SFDA approval processes for new material introductions frequently extend beyond project milestone deadlines.
- Subcontractor Coordination Complexity:Multi-trade fit-out projects involving MEP, flooring, and custom millwork generate interface disputes that delay handover schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Interior Design Market |
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $30.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Fixtures, Flooring, Wall Coverings End User: Residential, Commercial, Hospitality, Retail Design Style: Modern, Traditional, Minimalist, Eclectic Service Type: Consultation, Project Management, Custom Design, Installation |
| Companies Covered | Modassic, Yasmeen Interiors, Antonovich Group, Baumat, Echo Architecture, IDegree Design, A Interiors, Dewan Architects & Engineers, Nebras Aljoaib Creative Studio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Interior Design Market Evolving Landscape
Digital specification tools and sustainability mandates are compressing traditional design-to-delivery cycles across the Kingdom's interior fit-out sector. Three developments are restructuring how spaces are conceived, procured, and certified.
Parametric design software is overtaking manual drafting workflows in large-scale commercial and hospitality projects. Saudi developers in Riyadh's megaproject corridor are mandating generative design platforms that optimize spatial layouts against cost and material constraints. This technology is overtaking conventional 2D specification methods by compressing revision cycles from weeks to days.
SASO's expanded technical regulations for lighting efficacy and HVAC performance are forcing specification changes across commercial interiors. The standards mandate minimum energy performance coefficients that disqualify legacy fixture catalogs. Hospitality developments in Jeddah are responding fastest, embedding compliance checkpoints earlier in schematic design phases.
Developer procurement teams are consolidating vendor relationships from fragmented subcontractor networks to single-source design-build contracts. This concentration is displacing traditional architect-specifier-contractor chains in Riyadh luxury residential projects. The shift is most visible in giga-project developments where master developers demand consolidated accountability for interior outcomes.
Saudi Arabia Interior Design Market Segmentation
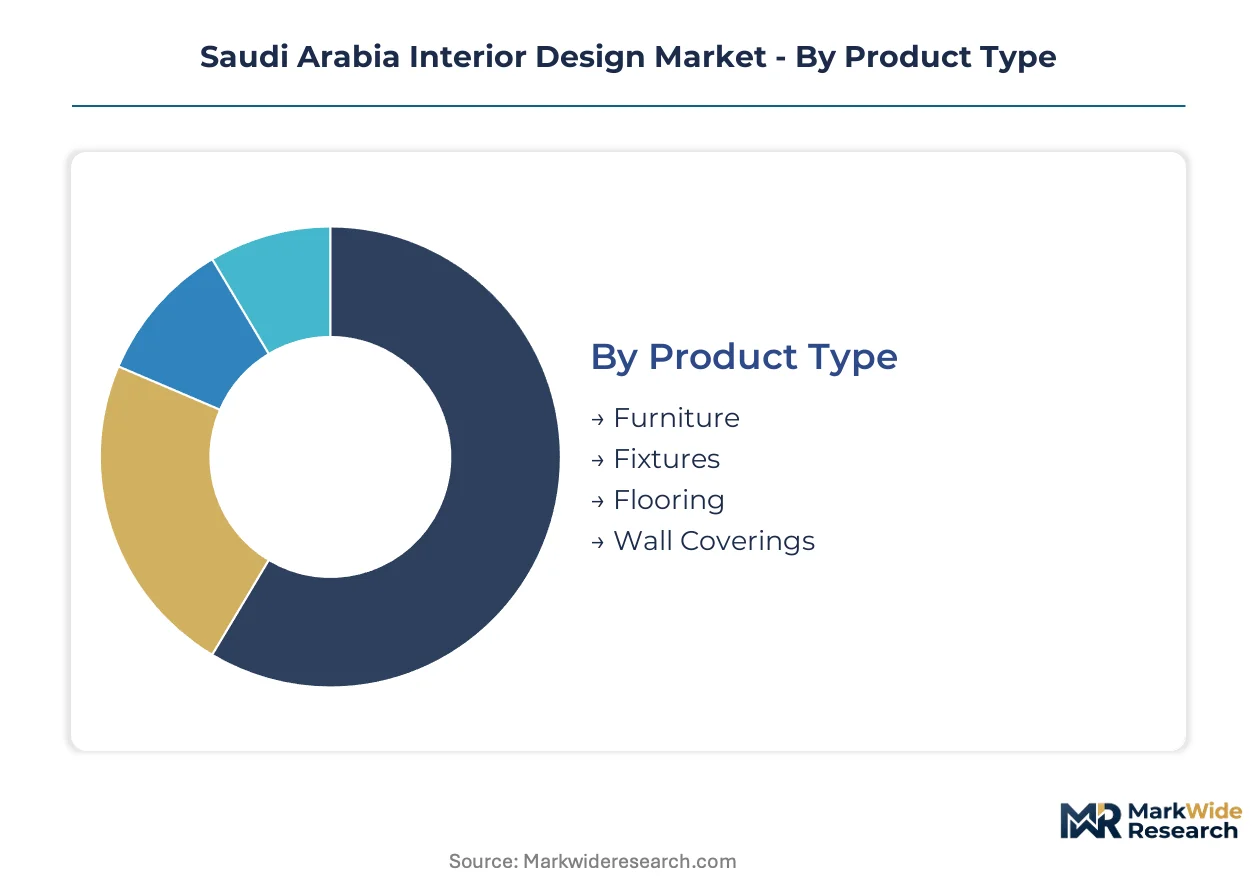
Segmentation reveals how procurement power concentrates across distinct product categories and service tiers in the Kingdom's fit-out sector. Vendor positioning strategies diverge sharply based on whether they target furniture-heavy hospitality contracts or service-intensive residential engagements.
Product Type:
Supply concentration clusters around furniture and fixtures, where manufacturing scale and import relationships determine competitive viability in Riyadh's megaproject corridor.
- Furniture:Custom millwork and loose furnishings absorb the dominant share of project value, particularly in luxury residential and hospitality settings where brand differentiation commands premium positioning. Riyadh's giga-developments are compressing lead times and forcing vendor consolidation among contractors with captive manufacturing or exclusive distribution agreements.
- Fixtures:Lighting systems, sanitary ware, and hardware integrate directly with SASO energy efficiency mandates and SFDA safety protocols. Jeddah hotel developments are driving specification upgrades as developers front-load compliance checkpoints to avoid certification delays.
- Flooring:Stone, tile, and engineered surfaces specified across commercial and retail environments.
- Wall Coverings:Textiles, paint systems, and decorative panels serving residential accent applications.
Today's leader: Furniture. Tomorrow's challenger: Fixtures.
End User:
Application intensity varies by occupancy patterns, with hospitality and luxury residential projects generating the highest specification complexity and vendor coordination requirements.
- Hospitality:Hotels and resorts demand integrated fit-out solutions spanning custom furniture, lighting controls, and fire-rated materials. Riyadh and Jeddah developments are accelerating procurement timelines as international brand operators enter the Kingdom.
- Residential:Luxury segments within Riyadh's megaproject corridor concentrate spending on bespoke interiors and smart home integration. High-net-worth clients are consolidating vendor relationships from fragmented subcontractor networks toward single-source accountability.
- Commercial:Office and institutional interiors governed by SASO HVAC and lighting efficiency standards.
- Retail:Branded environments requiring rapid installation cycles and standardized fixture systems.
Demand gravity centers on hospitality. Residential claims the steepest expansion trajectory as smart home convergence deepens service bundling opportunities.
Design Style:
Margin differentiation separates premium custom services from standardized specification catalogs, with traditional and modern styles anchoring opposite ends of the pricing spectrum.
- Traditional:Saudi heritage motifs and craftsmanship command premium positioning in high-net-worth residential segments. Specialized providers leverage artisan networks and regional material sourcing to defend margin against commoditized alternatives.
- Modern:Clean lines and international aesthetics dominate hospitality and commercial specifications where brand consistency across global portfolios drives standardization. Parametric design tools are compressing revision cycles for this segment.
- Minimalist:Reduced material palettes and spatial simplicity gaining traction in urban residential.
- Eclectic:Mixed-style approaches serving boutique hospitality and individual residential clients.
Traditional commands price premiums. Modern scales fastest across institutional procurement channels.
Service Type:
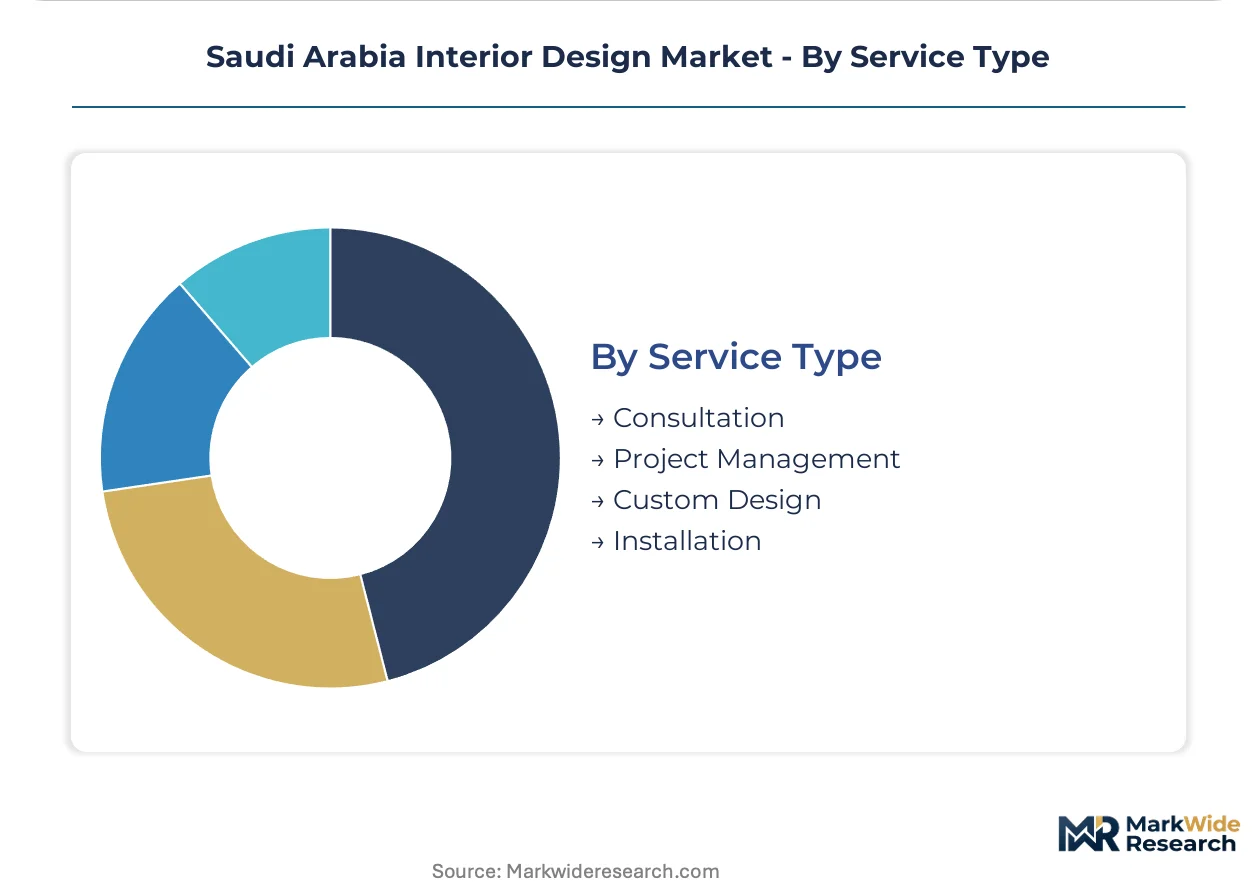
Customer type determines whether engagements center on discrete design deliverables or end-to-end project accountability, with implications for vendor capability requirements and contract structures.
- Custom Design:Bespoke spatial planning and furniture specification captures premium pricing as clients seek differentiated environments. Riyadh's competitive luxury residential market rewards firms with in-house production capacity and exclusive material sourcing relationships.
- Project Management:Coordination of multi-trade fit-out execution is displacing traditional architect-specifier-contractor chains in large-scale developments. Master developers are mandating consolidated accountability for interior outcomes.
- Consultation:Advisory services for material selection and spatial planning on smaller residential engagements.
- Installation:Execution-only contracts for standardized fixture and furniture deployment.
Project management anchors large-contract capture. Custom design gains share fastest as differentiation pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's megaproject corridor concentrates Saudi Arabia's interior design demand, with hospitality and luxury residential fit-outs driving specification intensity across the Kingdom's three primary economic zones.
Riyadh
Diriyah Gate and King Abdullah Financial District developments generate concentrated demand for custom millwork and integrated lighting systems. SASO energy efficiency mandates for HVAC and lighting filter vendor eligibility for commercial contracts. The Riyadh megaproject corridor compresses procurement timelines as master developers consolidate fit-out accountability under single-source contracts.
Western Region
Jeddah hotel developments accelerate specification upgrades for fire-rated materials and accessibility-compliant fixtures. SFDA building material safety protocols create premium positioning opportunities for certified suppliers serving hospitality interiors. Red Sea Project tourism zones offer first-mover positioning for design firms capable of delivering sustainable interiors at scale.
Eastern Province
Dammam commercial and corporate interiors follow municipal building codes enforcing fire-rated specifications and accessibility requirements. SASO technical regulations for lighting efficacy reshape fixture selection in office developments. Industrial city expansions generate secondary demand for standardized retail and institutional fit-outs.
NEOM Northwest
The Line and Oxagon developments mandate sustainable, tourism-oriented interior specifications aligned with green building criteria. NEOM procurement frameworks favor vendors with captive manufacturing capacity or exclusive material sourcing relationships. Design-build consolidation displaces traditional architect-specifier-contractor chains in this giga-development zone.
Saudi Arabia Interior Design Market Competitive Landscape
Global design networks compete with regional champions across project management capabilities and traditional craftsmanship specialization. The vendor base organizes into three tiers: integrated design-build operators, specialized traditional service providers, and custom manufacturing specialists. Strategic differentiation concentrates on single-source accountability consolidation and captive production capacity expansion.
Within the integrated project management tier, Modassic leverages its coordination capabilities to secure large-scale hospitality contracts. Yasmeen Interiors anchors the specialized traditional design segment, targeting high-net-worth residential clients through artisan networks. Antonovich Group occupies a position defined by custom furniture manufacturing and in-house production capacity, exemplifying the captive supply archetype in Riyadh's competitive luxury market.
| Leading Market Players |
|---|
| Modassic |
| Yasmeen Interiors |
| Antonovich Group |
| Baumat |
| Echo Architecture |
| IDegree Design |
| A Interiors |
| Dewan Architects & Engineers |
| Nebras Aljoaib Creative Studio |
| Others |
Value Network & Pricing Analysis
Sovereign-backed developers and family-owned fit-out specialists dominate procurement in Riyadh's megaproject corridor, compressing payment terms and forcing tiered pricing discipline across vendor networks. Their consolidated buying power extracts volume discounts while SASO certification requirements filter non-compliant suppliers from premium contract pools.
Pricing Analysis
Imported fixture costs pass through directly to project budgets, with European millwork and Asian lighting systems absorbing currency volatility. Pricing stratifies across premium custom, standard project-grade, and economy specification tiers, with certification grade and customization level as primary differentiation drivers. Cost compression in the economy tier intensifies as local manufacturing incentives reduce import dependency for standardized hospitality fixtures. Hospitality developers show least price sensitivity, while secondary city retail fit-outs face tightest budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from Riyadh master developers mandate qualified backup suppliers for all fire-rated materials and custom millwork categories. Manufacturing concentrates in Italy, China, and Turkey for high-end furniture, while lighting systems source primarily from Germany and South Korea. Raw material dependencies span engineered wood substrates, specialty metals, and LED driver components. Single-source vulnerability persists in artisan-crafted traditional elements. Distribution runs through project-based direct procurement rather than wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in SASO-compliant fixture upgrading and captive manufacturing scale-up as local financing reduces landed cost premiums for hospitality developers.
For Market Incumbents: Anticipate procurement consolidation by deepening captive production capacity in Riyadh's industrial zones to defend against emerging design-build operators from the UAE. Prioritize SFDA pre-certification for surface materials and finishes to lock out non-compliant rivals from healthcare and hospitality pipelines. For New Entrants and Emerging Players: SASO energy efficiency mandates in Saudi Arabia open a window for LED lighting specialists and smart controls integrators to capture share in Jeddah hotel developments. Target secondary cities like Dammam and Khobar where BIM-capable designers remain scarce. Lead with design-build bundling to bypass fragmented subcontractor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier project management specialists lacking captive manufacturing. Long-term viability favors vertically integrated operators with exclusive distribution agreements for European millwork brands. Watch NEOM procurement framework announcements as the inflection signal for sustainable interior specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing Scale-Up | Reduces import exposure and compresses lead times for Riyadh giga-developments. |
| SFDA Pre-Certification Investment | Locks vendor eligibility for healthcare and hospitality material specifications. |
| Design-Build Contract Consolidation | Displaces fragmented subcontractor chains with single-source accountability. |
| Smart Home Integration Partnership | Bundles IoT controls with interior specifications for luxury residential. |
| NEOM Sustainability Alignment | Positions vendors for green building criteria in the Kingdom's western development zone. |
Research Methodology
Coverage spans Riyadh, Jeddah, Dammam, and the NEOM development zone, with primary inputs from each. The analysis combines interviews with hospitality procurement directors, residential project managers, fit-out contractors, and SASO compliance officers with secondary validation from Saudi Building Code documentation, SFDA material safety registries, and municipal permitting databases. Bottom-up project pipeline tracking triangulates against top-down sector spending estimates.
Rate-of-change decomposition separates volume growth from specification mix shifts across the analysis window. Segmentation dimensions include product type, end-use sector, design style tier, and service delivery model. CAGRs derive from fitted trend extrapolation against megaproject completion schedules. Forecast inputs incorporate SASO regulatory phase-in timelines and Saudi Industrial Development Fund disbursement patterns for domestic manufacturing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under currency volatility spikes or certification timeline delays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Bifold Door Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
Wall Decor Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Pillow Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Middle East Revolving Doors Market