
 Soundproof Door Market | 2026-2036
Soundproof Door Market Size, Share, and Industry Trends Forecast 2026-2036
Soundproof Door Market Insights
Specialized distributor networks serving architects and acoustic consultants is reconfiguring how soundproof door specifications reach project owners. ASSA ABLOY AB leverages its broad access control portfolio to bundle acoustic solutions with integrated hardware systems. Masonite International Corporation anchors its position through sustained investment in engineered wood core technologies that dampen sound transmission. Vicoustic competes by specializing in studio-grade acoustic assemblies that combine doors with complementary wall treatments.
A soundproof door is an engineered barrier assembly designed to reduce airborne sound transmission between spaces, typically achieving sound transmission class ratings between 35 and 55 through multi-layer construction incorporating dense core materials, acoustic seals, and perimeter gasketing. Metal and composite material segments lead specification volume in commercial and institutional projects where fire resistance and acoustic performance must coexist. Glass-type soundproof doors represent the fastest-growing material category as corporate offices and conference rooms prioritize visual connectivity without sacrificing acoustic privacy. Application demand concentrates in recording studios and laboratories where precise decibel reduction requirements command premium pricing and technical compliance.
OSHA noise exposure standards in the United States and the EU Green Deal building renovation targets collectively shape product certification requirements and retrofit demand across developed markets. Germany's KBA and France's CNIL do not regulate this sector directly, but national building codes in both countries enforce acoustic performance minimums that manufacturers must meet for market access. Stakeholders should monitor evolving green building certification schemes that increasingly weight acoustic comfort alongside energy metrics in project scoring systems.
Market Dynamics
Acoustic building code enforcement is tightening across major construction markets, forcing specification upgrades from basic hollow-core doors to engineered assemblies that achieve STC 45+ ratings through multi-layer damping construction.
Growth Catalysts
- OSHA workplace noise standards:Industrial facilities in the United States face mandatory hearing conservation programs, driving installation of acoustic barriers in manufacturing floors and equipment rooms to limit employee exposure.
- Mixed-use development clustering:Urban construction corridors in New York, London, and Berlin generate concentrated demand for doors that isolate residential units from commercial noise sources below.
- Engineered wood core advancement:High-density particleboard and laminated strand technologies now deliver mass and damping properties previously requiring solid timber, expanding specification feasibility.
Market Restraints
- Steel and aluminum input volatility:Metal frame and cladding components face commodity price swings that compress margins on fixed-price construction contracts.
- Specialized sealant supply concentration:Acoustic perimeter gasketing relies on a narrow supplier base in Germany and Japan, creating vulnerability to logistics disruptions.
- Fire-acoustic rating incompatibility:Intumescent materials required for fire doors often degrade sound transmission performance, forcing costly dual-certification testing cycles.
Strategic Opportunities
- India commercial real estate expansion:Metro construction in Mumbai and Bangalore lacks mature acoustic specification standards, creating first-mover positioning for certified product lines.
- Healthcare privacy mandates:HIPAA-adjacent patient confidentiality requirements in US outpatient clinics drive demand for consultation room isolation without visual barrier trade-offs.
- Smart building integration:Convergence of acoustic assemblies with IoT-enabled access control and occupancy sensing opens bundled specification pathways.
Industry Challenges
- Acoustic testing capacity bottleneck:Certified laboratory availability for STC and OITC rating verification creates 8-12 week delays for new product introductions.
- Installer skill fragmentation:Proper perimeter seal compression and frame isolation require training that general carpentry crews often lack, degrading field performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soundproof Door Market |
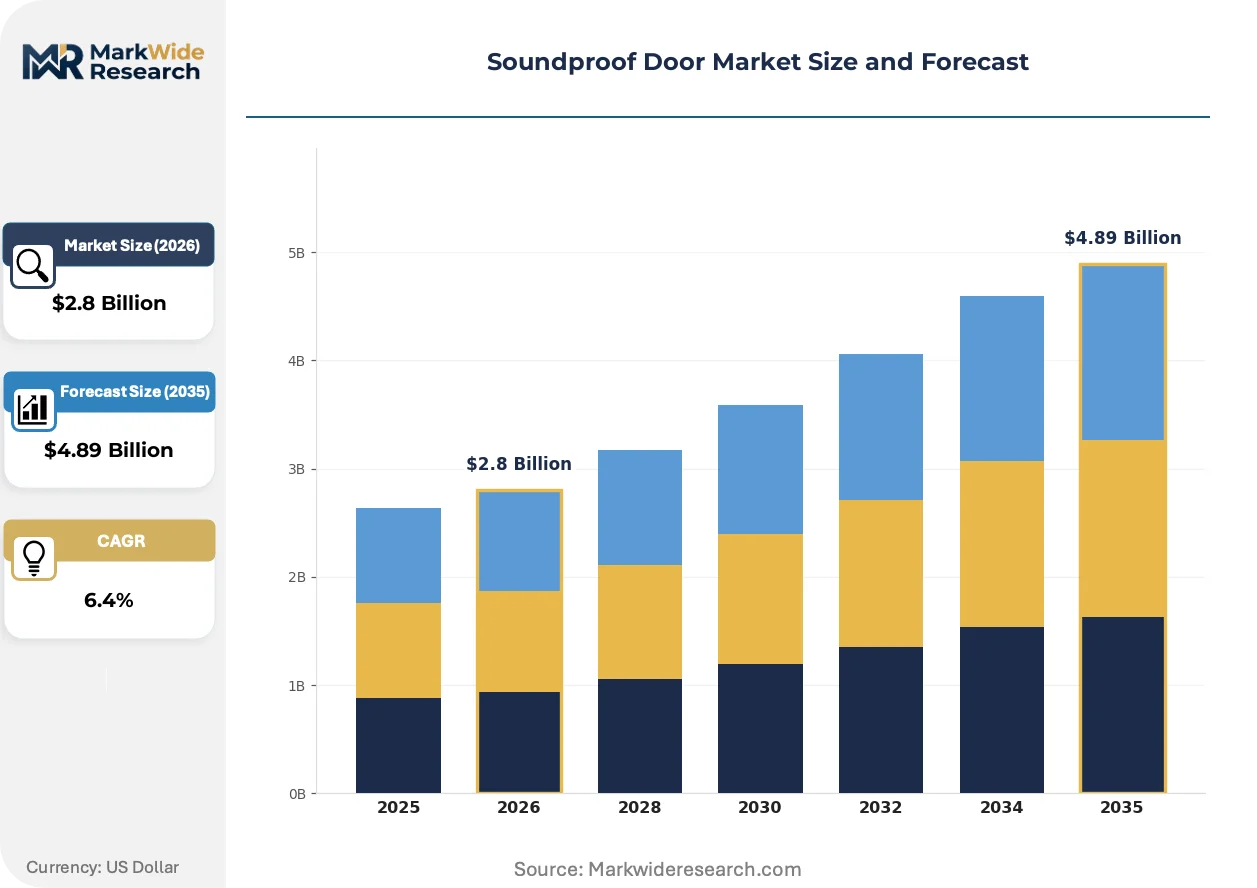
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Acoustic, Fire-Resistant, Security, Thermal Insulated Material: Wood, Metal, Composite, Glass Application: Recording Studios, Cinemas, Conference Rooms, Laboratories End User: Entertainment Venues, Corporate Offices, Research Facilities, Residential Complexes |
| Companies Covered | ALFATECO MADRID, Vicoustic, Bosco Italia SPA, Jansen Brandschutz-Tore GmbH, Wilcox Door Service, Rolflex Nederland BV, ASSA ABLOY AB, Masonite International Corporation, JELD-WEN Holding, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soundproof Door Market Trends and Innovations
Material science breakthroughs and regulatory pressure are compressing the gap between fire-rated and acoustic-rated assemblies, while procurement patterns shift toward performance-guaranteed specifications rather than component-based purchasing.
Glass-type soundproof door technology is hybridizing vacuum-insulated glazing with laminated interlayers to achieve STC 40+ ratings in transparent assemblies. Corporate headquarters and law firms in London and Singapore specify these for executive suites and deal rooms where visual openness must coexist with speech privacy. The technology is compressing the traditional trade-off between acoustic isolation and spatial connectivity that previously forced binary specification choices.
The EU Green Deal building renovation targets are mandating acoustic comfort alongside thermal performance in public building retrofits. Member state building codes now weight sound transmission metrics in energy efficiency scoring, redirecting public procurement toward certified assemblies. German federal construction projects have responded by embedding STC minimums into tender specifications, filtering uncertified suppliers from bid pools.
Architects and acoustic consultants are consolidating specification authority previously dispersed among general contractors and facilities managers. Large mixed-use developments in New York and Toronto now engage independent acoustic engineers during schematic design, front-loading door selection into performance contracts rather than late-stage value engineering. This pattern concentrates volume with distributors maintaining certified product portfolios and technical support capabilities.
Soundproof Door Market Segmentation
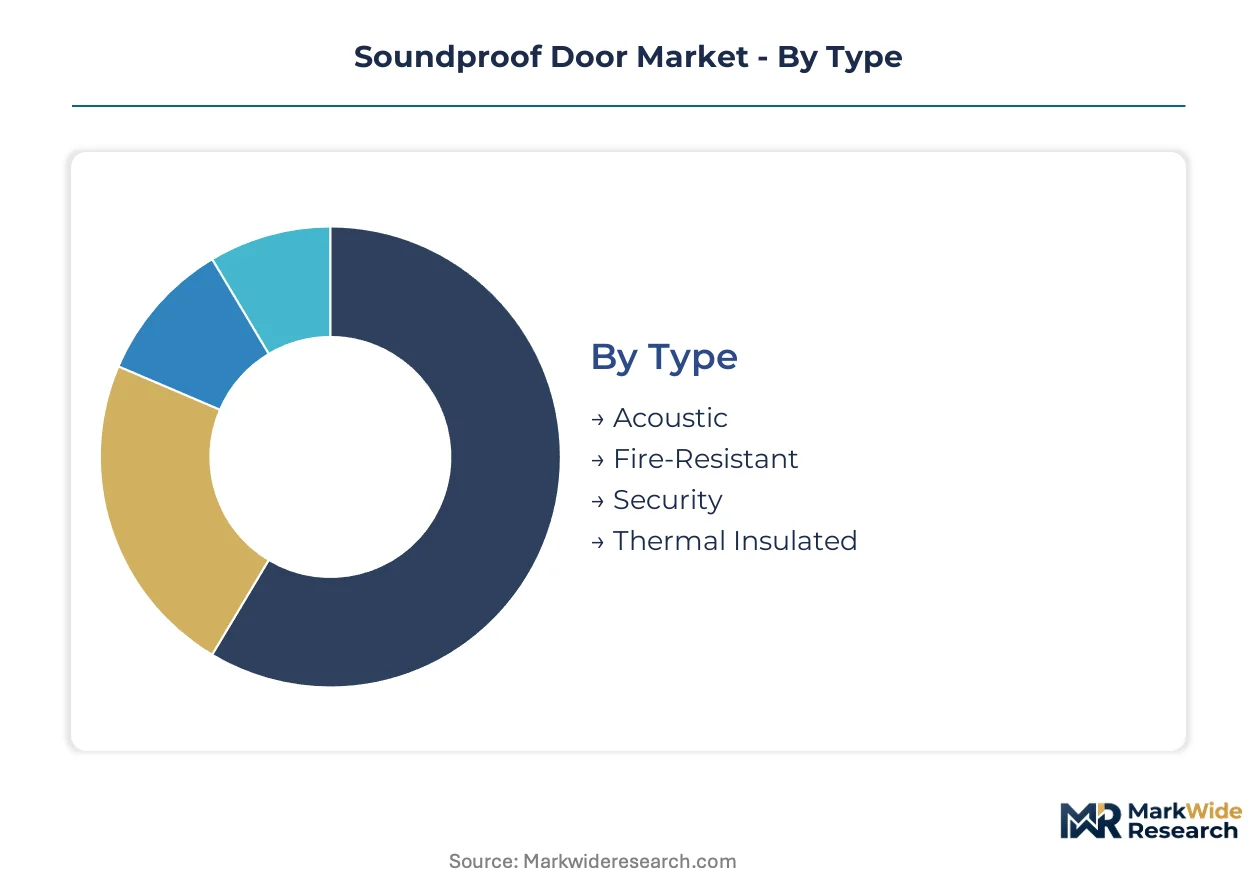
Soundproof door procurement splits across performance certifications, material engineering, and end-use acoustic requirements. Specification authority concentrates with architects and acoustic consultants who translate project decibel targets into certified product selections.
Type:
Performance certification tiers separate basic acoustic barriers from multi-hazard engineered assemblies, with cost and compliance complexity escalating across the spectrum.
- Acoustic:Engineered barriers achieving STC 35-55 ratings through multi-layer core construction and perimeter gasketing. Recording studios in New York and London specify these for isolation booths and control rooms where precise decibel reduction commands premium positioning.
- Fire-Resistant:Assemblies integrating intumescent materials with acoustic damping layers to satisfy dual-certification testing. Mixed-use developments in Berlin mandate these for residential-corridor interfaces where building codes enforce both containment and isolation.
- Security:Reinforced core designs combining acoustic performance with forced-entry resistance. Corporate headquarters and law firms specify these for executive suites requiring speech privacy alongside physical protection.
- Thermal Insulated:Hybrid assemblies addressing acoustic transmission and thermal bridging in climate-controlled environments. Laboratories and clean rooms deploy these where HVAC efficiency must coexist with noise isolation.
Acoustic doors command the established base. The steepest expansion runs through fire-resistant configurations as code enforcement tightens across commercial construction corridors.
Material:
Material selection trades off mass, damping coefficient, and architectural integration requirements, with specification patterns diverging sharply between institutional and commercial applications.
- Wood:High-density particleboard and laminated strand cores deliver mass properties through engineered wood technologies. Masonite International anchors this segment through sustained investment in proprietary core formulations that dampen resonance frequencies.
- Metal:Steel and aluminum frames with composite infill panels dominate institutional specifications where fire ratings and durability requirements converge. Metal input volatility from commodity markets compresses margins on fixed-price contracts.
- Composite:Hybrid constructions combining mineral cores with polymer facings optimize weight-to-performance ratios. These gain traction in retrofit applications where structural load limits constrain traditional heavy assemblies.
- Glass:Vacuum-insulated glazing with laminated interlayers achieves STC 40+ in transparent assemblies. Corporate offices in London and Singapore specify these for conference rooms where visual connectivity must coexist with speech privacy.
Metal and wood variants anchor volume. Glass configurations are climbing the fastest as architectural preferences shift toward spatial transparency without acoustic sacrifice.
Application:
Application-driven specification concentrates in environments with precise decibel targets, technical compliance mandates, and premium pricing tolerance for certified performance.
- Recording Studios:Isolation booths and control rooms demanding STC 50+ ratings with specialized bass trapping. Entertainment corridors in Los Angeles and Nashville concentrate demand for studio-grade assemblies.
- Cinemas:Auditorium isolation and lobby barriers preventing bleed between screening rooms. Multiplex construction in metropolitan India drives specification volume where acoustic standards are maturing.
- Conference Rooms:Executive suites and deal rooms requiring speech privacy without visual barriers. Financial services firms in New York and London prioritize these for client confidentiality.
- Laboratories:Clean rooms and equipment isolation with precise vibration and airborne transmission controls. Research facilities face OSHA noise exposure standards mandating acoustic barriers around high-decibel instrumentation.
Recording studios anchor premium positioning. Conference rooms are gaining share fastest as hybrid work patterns elevate acoustic privacy in corporate real estate.
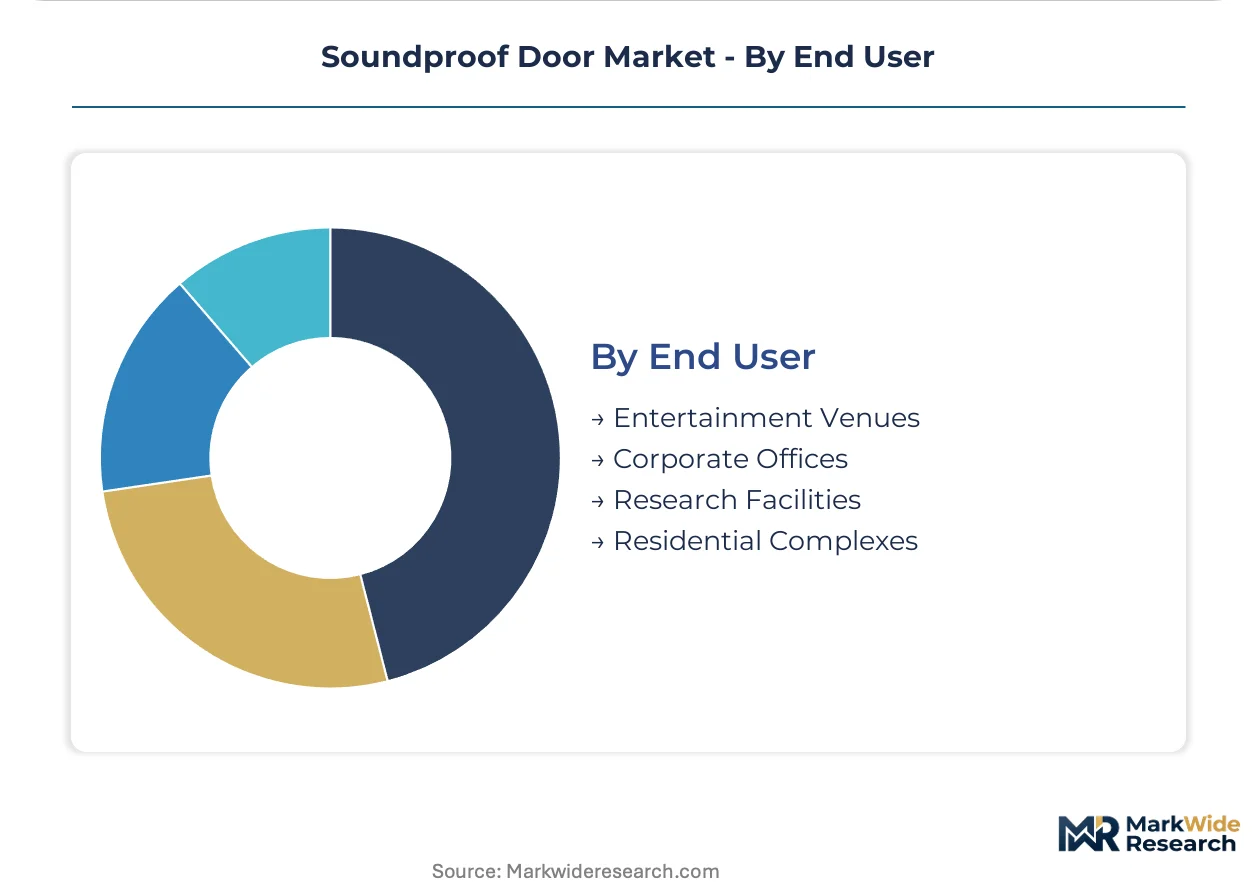
End User:
End-user categories reflect divergent procurement authority, with institutional buyers emphasizing compliance documentation and commercial buyers prioritizing architectural integration.
- Entertainment Venues:Concert halls, theaters, and broadcast facilities with specialized acoustic engineering requirements. These buyers engage acoustic consultants early in schematic design, front-loading specification into performance contracts.
- Corporate Offices:Headquarters and professional services firms balancing open-plan connectivity with private enclosure needs. Law firms and financial services drive demand for glass-type assemblies enabling visual transparency.
- Research Facilities:Universities, pharmaceutical labs, and government research centers with dual compliance mandates. HIPAA-adjacent patient confidentiality requirements in US outpatient clinics extend acoustic specifications beyond traditional laboratory boundaries.
- Residential Complexes:Mixed-use developments isolating residential units from commercial noise sources. Urban construction corridors in Berlin and London concentrate demand as building codes tighten STC minimums for multi-family housing.
Entertainment venues command specification authority through early acoustic consultant engagement. Residential complexes are expanding most quickly as urban mixed-use development accelerates across European and North American metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium specification authority concentrates in German and British construction corridors where acoustic code enforcement commands 15-20% price premiums over Mediterranean markets. North American metropolitan clusters offset higher labor costs through volume concentration in mixed-use developments.
United States
OSHA workplace noise standards mandate hearing conservation programs in industrial facilities across Michigan and Ohio manufacturing belts. The EPA coordinates with state building departments to embed STC minimums into commercial construction permits. New York City's Hudson Yards corridor and Los Angeles entertainment districts drive specification volume for studio-grade assemblies.
Germany
Federal construction projects embed STC minimums into tender specifications that filter uncertified suppliers from bid pools. The EU Green Deal building renovation targets mandate acoustic comfort alongside thermal performance in public retrofits. Berlin's mixed-use developments and Hamburg's port conversion projects concentrate demand for fire-acoustic dual certification.
United Kingdom
London law firms and financial services drive demand for glass-type assemblies enabling visual transparency with speech privacy. Building regulations in England and Wales enforce acoustic performance minimums for multi-family housing. The Birmingham and Manchester metropolitan expansion corridors generate retrofit volume as office-to-residential conversions accelerate.
India
Metro construction in Mumbai and Bangalore lacks mature acoustic specification standards, creating first-mover positioning for certified product lines. The Bureau of Indian Standards develops voluntary acoustic performance guidelines for commercial real estate. Hyderabad's pharmaceutical research clusters and Pune's automotive testing facilities drive laboratory-grade specification trials.
Japan
METI building efficiency standards increasingly weight acoustic comfort in commercial property valuations. Dense urban construction in Tokyo and Osaka forces specification of compact acoustic assemblies for mixed-use towers. Yokohama's media production districts and Kyoto's university research corridors concentrate entertainment and laboratory demand.
Soundproof Door Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and sealant supply. The vendor base stratifies between multinational access-control platforms, regional door fabricators, and acoustic engineering boutiques. Three archetypes dominate: hardware conglomerates bundling acoustic solutions with integrated systems, engineered-wood specialists leveraging proprietary core formulations, and studio-grade boutiques combining doors with complementary wall treatments. Competitive moves concentrate on distributor network expansion and certified product portfolio breadth.
Among European fabricators, Jansen Brandschutz-Tore GmbH exemplifies the fire-acoustic dual-certification specialist archetype. ASSA ABLOY AB anchors the platform-integrator tier through access-control portfolio breadth. Masonite International Corporation occupies a position within engineered-wood core technology development. These three represent distinct competitive positioning vectors rather than direct substitution rivals.
| Leading Market Players |
|---|
| ALFATECO MADRID |
| Vicoustic |
| Bosco Italia SPA |
| Jansen Brandschutz-Tore GmbH |
| Wilcox Door Service |
| Rolflex Nederland BV |
| ASSA ABLOY AB |
| Masonite International Corporation |
| JELD-WEN Holding, Inc. |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's acoustic sealant manufacturing cluster shapes downstream pricing power through specialized polymer formulation capacity that few alternative suppliers can replicate. German and Japanese gasketing specialists command 15-20% premia over commodity alternatives, forcing door fabricators to absorb cost volatility or pass through to project owners.
Pricing Analysis
The customization-premium spread separates configured-to-order STC 50+ studio assemblies from standard STC 35-40 commercial stock. Project-based pricing dominates, with certification level and acoustic performance tier as primary differentiation drivers. Cost compression in standard-grade metal doors intensifies as Chinese composite alternatives enter European distribution channels. Corporate office buyers exhibit highest price sensitivity, while recording studio operators prioritize performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates with Jansen Brandschutz-Tore GmbH and regional German fabricators holding certified fire-acoustic dual-production capacity. Germany, China, and the United States anchor geographic supply, drawing from high-density particleboard cores, mineral wool infill, and specialized acoustic polymers. Single-source vulnerability runs through Japanese silicone sealant suppliers. Distribution runs through architect-specified distributor networks rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soundproof door procurement fragments across performance tiers, creating niche positioning opportunities as hybrid work patterns elevate acoustic privacy to core real estate criteria.
For Market Incumbents: Harden certification portfolios against emerging composite specialists by investing in fire-acoustic dual-rating capacity that substitutes cannot easily replicate. Deepen backward integration into engineered wood core production to defend margin position against commodity metal price swings. For New Entrants and Emerging Players: Establish a beachhead in India's commercial real estate corridor before acoustic specification standards mature, partnering with local architects to embed STC minimums into emerging building codes. Target laboratory-grade applications in Hyderabad's pharmaceutical cluster where compliance documentation creates switching costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors studio-grade acoustic engineering boutiques with proprietary wall-door system integration over commodity metal fabricators. Long-term viability hinges on green building certification convergence where acoustic comfort scores weight project financing. Watch for EU member state adoption of acoustic performance in public procurement scoring as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Fire-acoustic dual-rating unlocks German federal construction tender access. |
| Backward Integration into Core Materials | Proprietary engineered wood formulations dampen metal commodity exposure. |
| Smart Building System Integration | IoT-enabled access control bundling captures specification authority from hardware distributors. |
| Geographic Manufacturing Footprint | Indian production presence reduces landed cost for Mumbai-Bangalore metro construction. |
| Healthcare Privacy Certification | HIPAA-adjacent compliance documentation extends laboratory specifications into outpatient clinic buildouts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with acoustic consultants, architect specification writers, door fabricator production managers, and facilities director procurement leads. Secondary validation drew from OSHA noise exposure databases, EU Green Deal building renovation filings, national building code amendments, and customs trade data for acoustic sealant imports. Bottom-up project pipeline tracking triangulated against top-down construction spend forecasts.
Calibration against historical STC rating adoption curves and mixed-use development permitting velocity anchored the analytical framework across the analysis window. Segmentation dimensions modeled include performance certification tier, material engineering category, end-use application, and regional regulatory cluster. CAGRs derived from installer capacity expansion plans and certified laboratory throughput constraints.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates and steel commodity indices would shift the trajectory. Forecasts reflect assumptions on acoustic code enforcement timing and green building certification weighting evolution. Quarterly review of municipal permitting data and STC testing laboratory backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
India Furniture Hardware Market
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
Stained Glass Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
Bamboo Panels Market
Homecare and Decor
Door Handles Market