
 Legal Technology Market | 2026-2036
Legal Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Legal Technology Market Intelligence
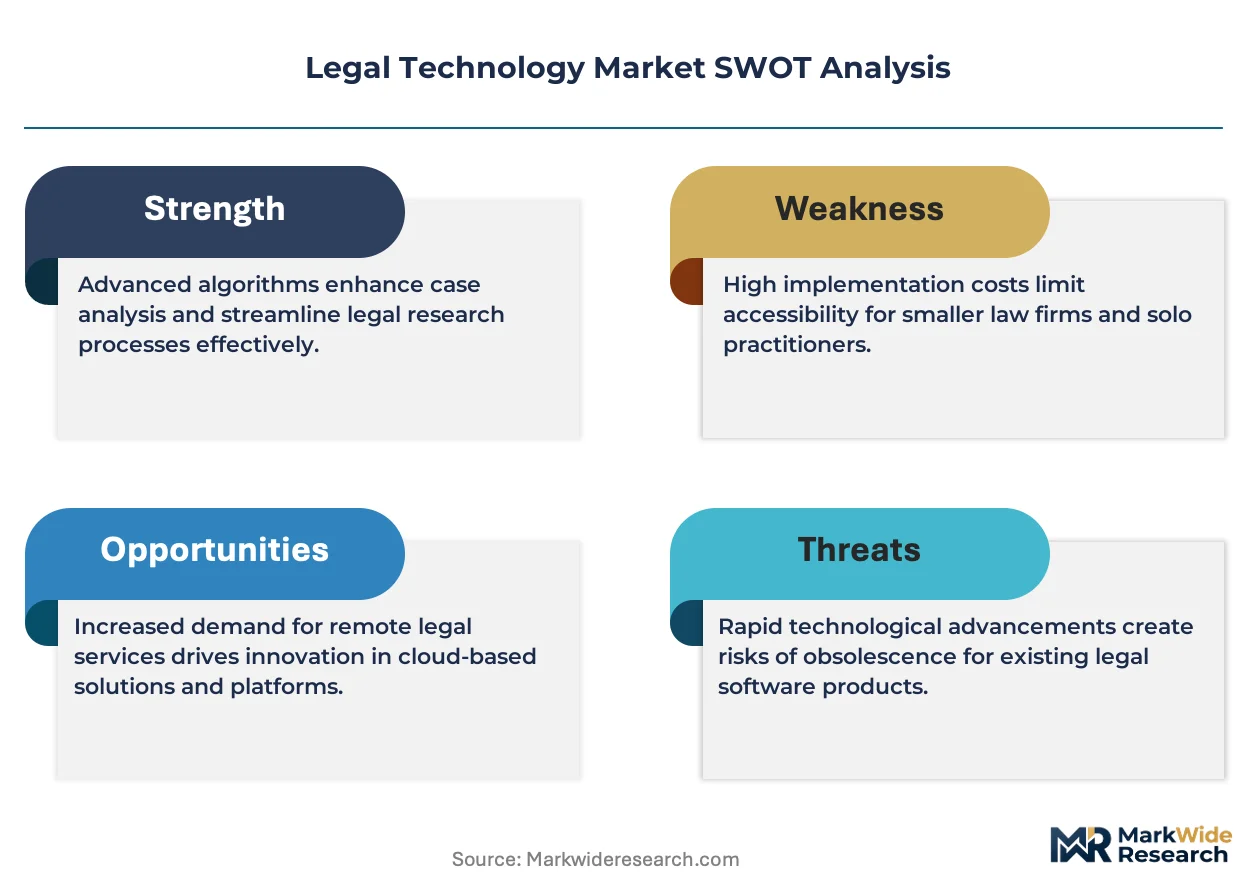
Mid-sized law firms are redrawing procurement patterns across the Legal Technology Market, shifting spend from traditional enterprise suites toward modular cloud platforms. Ironclad leverages contract lifecycle automation to anchor corporate legal department budgets. Harvey differentiates through generative AI trained on proprietary legal corpora. Clio sustains dominant channel control across North American solo and small-firm segments.
Legal technology encompasses software systems, artificial intelligence tools, and cloud infrastructure designed to automate legal workflows, manage electronic evidence, and enforce compliance protocols through structured data architectures. These solutions process contract clauses, discovery documents, and billing entries at throughput rates exceeding manual review by orders of magnitude. E-Discovery commands mature revenue pools as litigation volume stabilizes, while Contract Management captures expanding margin share through AI-powered negotiation analytics. Cloud-Based deployment grows fastest as law firms abandon on-premise server maintenance for SaaS subscription models with automatic security patching.
The EU AI Act imposes risk-tiered compliance obligations on automated legal decision systems, forcing vendors to reengineer algorithmic transparency features. HIPAA and state bar ethics committees in the United States impose parallel data confidentiality and unauthorized practice of law constraints on client-facing platforms. Stakeholders must monitor evolving regulator interpretations of AI-generated legal advice to anticipate product redesign cycles and geographic market access shifts.
Market Dynamics
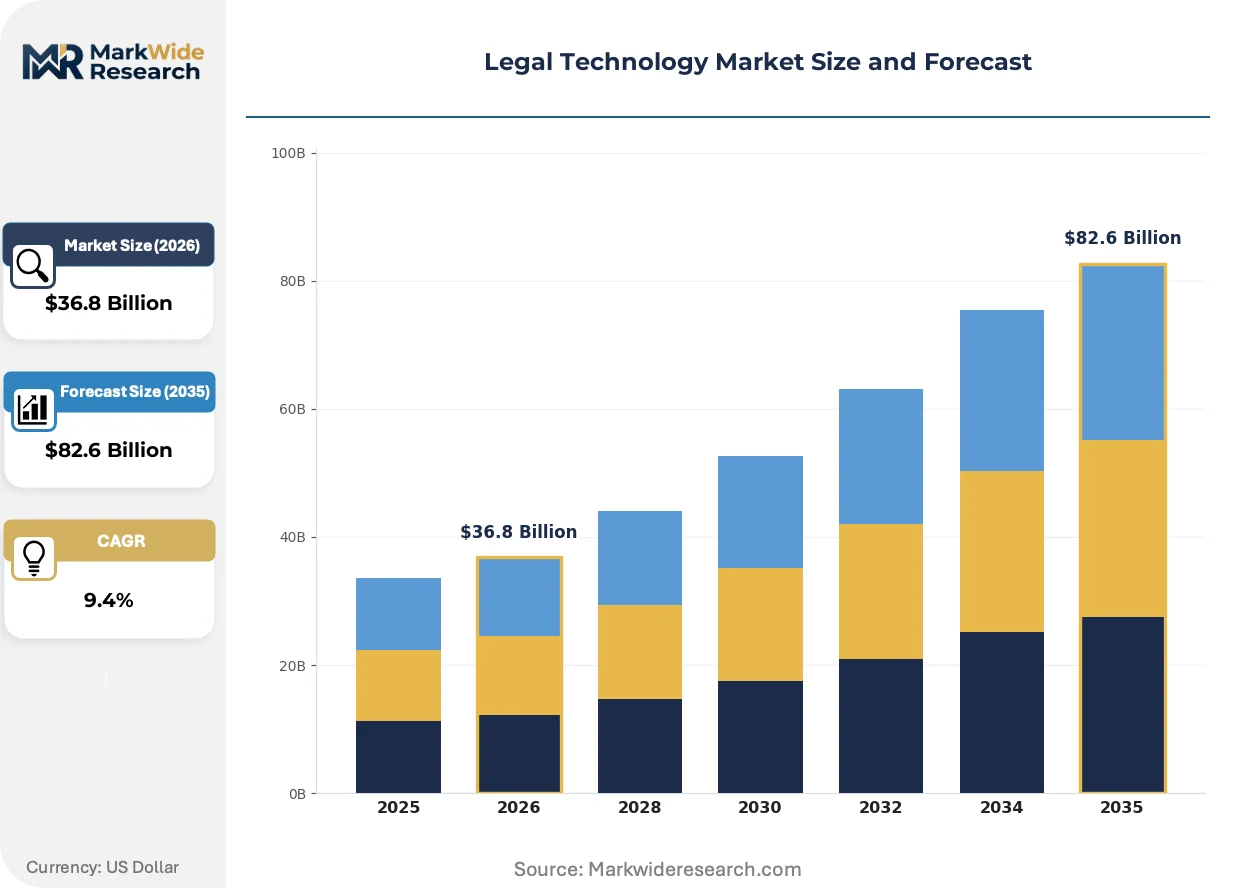
Mid-sized law firms now drive faster software procurement than large firms historically did, compressing vendor sales cycles and forcing modular pricing architectures. Cloud migration and GDPR-aligned data governance requirements in Europe accelerate platform replacements across corporate legal departments.
Growth Catalysts
- EU AI Act risk-tiered obligations:Automated legal decision systems face new algorithmic transparency mandates, creating retrofit demand for compliance modules.
- State bar ethics opinions in the United States:Automated legal workflows receive explicit professional blessing, reducing malpractice exposure for early adopters.
- E-Discovery volume stabilization:Litigation support teams standardize repeatable document review protocols, embedding software subscriptions into annual operating budgets.
Market Restraints
- HIPAA data confidentiality constraints:Client-facing platforms face parallel state and federal privacy enforcement, limiting cross-border data architecture options.
- Substitution by captive legal operations centers:Fortune 500 companies internalize contract analytics functions, bypassing external vendor relationships entirely.
- Technical limitation in explainable AI:Black-box negotiation models resist audit trails required by professional liability insurers, constraining deployment scope.
Strategic Opportunities
- Underpenetrated United Kingdom mid-market:Solicitors Regulation Authority guidance lags US state bar permissiveness, creating first-mover advantage for compliant entrants.
- Convergence of contract lifecycle management with carbon accounting:CSRD disclosure requirements pull ESG clause libraries into procurement software stacks.
- Alternative legal service provider channel expansion:Big Four accounting firms resell white-label platforms to corporate audit clients, bypassing traditional law firm gatekeepers.
Industry Challenges
- Integration complexity with legacy document management systems:On-premise iManage and NetDocuments installations resist API connectivity, extending implementation timelines.
- Certification timeline for GDPR representative arrangements:Non-EU vendors must establish EU-based data representatives before market access, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal Technology Market |
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $82.6 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Automation, E-Discovery, Contract Management, Time Tracking End User: Law Firms, Corporations, Government Agencies, Legal Service Providers Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Functionality: Case Management, Billing, Client Portal, Compliance Tracking |
| Companies Covered | Checkr, Ironclad, Harvey, Darrow, Everlaw, Relativity, Clio, LegalMation, Brightflag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal Technology Market Strategic Shifts & Innovations
Generative AI trained on proprietary legal corpora is decomposing traditional research billable hour models. Vendors race to embed negotiation analytics directly into email clients and word processors, collapsing the distance between legal work and software interface.
Large language models trained on case law and regulatory filings are decomposing associate-level research tasks. Am Law 200 firms pilot these tools for contract first drafts and deposition preparation, compressing the hours billed to clients. The technology is decomposing the traditional leverage model where junior attorneys performed routine document analysis.
The EU AI Act imposes risk-tiered compliance obligations on automated legal decision systems, forcing vendors to reengineer algorithmic transparency features. High-risk applications face conformity assessment requirements before market placement. European corporate legal departments delay procurement until vendor certification pathways clarify, creating temporary demand pauses in Germany and France.
Subscription pricing for practice management software displaces perpetual license models among solo practitioners. Clio and competitors now capture recurring revenue from attorneys who previously purchased on-premise desktop applications. This shift concentrates most visibly in United States state bar jurisdictions with mandatory technology competence requirements, where continuing education credits attach to platform training modules.
Legal Technology Market Segmentation
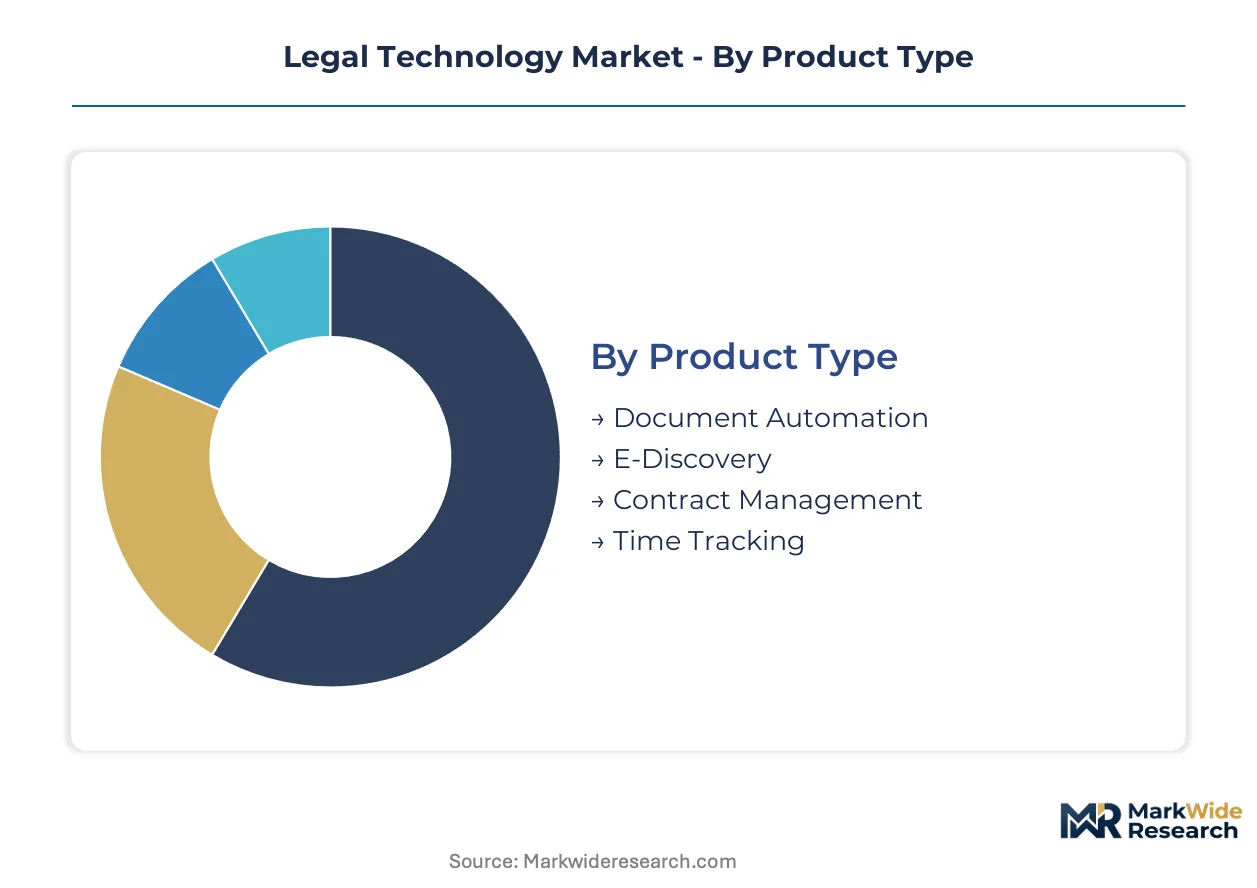
Legal technology procurement splits sharply across buyer sophistication tiers. Deployment choices determine data residency obligations. Functionality depth separates enterprise renewals from churn.
Product Type:
Substitution pressure concentrates in commoditized document assembly tools, while AI-augmented segments defend pricing power through proprietary training data.
- Document Automation:Template-driven assembly engines populate contracts, pleadings, and correspondence from structured intake forms. Demand clusters among United Kingdom mid-market solicitors seeking SRA-compliant efficiency gains. Clause libraries differentiate vendors; generic offerings face pressure from Microsoft Word native features.
- E-Discovery:Litigation support platforms process terabyte-scale document collections for privilege review and production. Corporate legal departments in the United States embed these subscriptions into annual operating budgets as litigation volume stabilizes. Predictive coding algorithms reduce attorney review hours by orders of magnitude.
- Contract Management:Lifecycle platforms with negotiation analytics command expanding budgets.
- Time Tracking:Billing capture tools face displacement by practice management suite bundling.
E-Discovery retains volume leadership; Contract Management holds the steepest expansion curve.
End User:
Customer type determines pricing architecture elasticity and sales cycle length.
- Law Firms:Partnership structures slow procurement decisions despite practitioner demand. Mid-sized firms now compress vendor sales cycles faster than large firms historically did. State bar ethics opinions in the United States reduce malpractice exposure for automated workflow adopters.
- Corporations:Fortune 500 legal operations centers internalize contract analytics, bypassing external vendors entirely. GDPR-aligned data governance requirements in Europe accelerate platform replacements. Procurement teams demand API connectivity to existing ERP systems.
- Government Agencies:Public sector tenders emphasize FedRAMP and equivalent security certifications.
- Legal Service Providers:ALSPs resell white-label platforms to corporate audit clients.
Corporations dominate current spend; Legal Service Providers are climbing the fastest.
Deployment:
Cost tier stratification separates maintenance-burdened legacy estates from automatic security patching.
- Cloud-Based:SaaS subscription models with automatic security patching displace on-premise maintenance. European corporate legal departments delay procurement until EU AI Act certification pathways clarify. Multi-tenant architectures reduce per-seat infrastructure costs below self-managed equivalents.
- SaaS:Pure subscription pricing captures recurring revenue from attorneys who previously purchased perpetual licenses. Mandatory technology competence requirements in United States state bar jurisdictions attach continuing education credits to platform training modules.
- On-Premise:Legacy iManage and NetDocuments installations resist API connectivity.
- Hybrid:Split architectures satisfy data residency requirements for cross-border matters.
SaaS captures the majority of new bookings; Cloud-Based deployment is gaining share fastest.
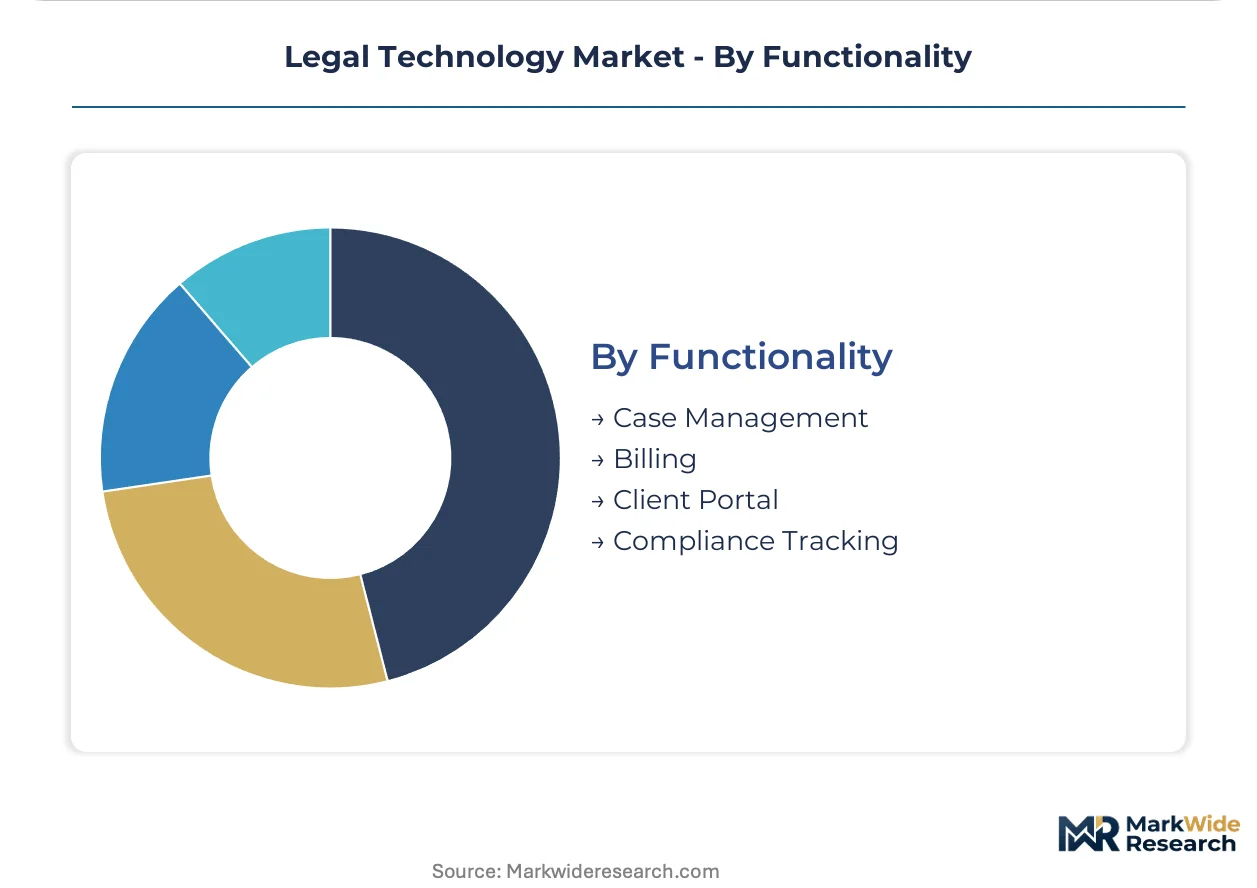
Functionality:
Maturity gradients separate table-stakes modules from differentiated workflow automation.
- Case Management:Matter-centric databases track deadlines, documents, and communications. Solo practitioners in North American state bar jurisdictions with mandatory technology competence requirements drive subscription conversions. Clio sustains dominant channel control through bar association partnerships.
- Compliance Tracking:EU AI Act risk-tiered obligations force algorithmic transparency retrofit demand. High-risk automated legal decision systems face conformity assessment requirements before market placement in Germany and France.
- Billing:Time and expense capture faces integration complexity with legacy accounting systems.
- Client Portal:Secure collaboration tools compete with generic file-sharing platforms.
Case Management retains installed base dominance; Compliance Tracking shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor headquarters cluster heavily in the United States and United Kingdom, with emerging development centers in Israel and Germany. SaaS delivery models reduce physical infrastructure requirements, yet talent acquisition and regulatory proximity still dictate geographic strategy.
United States
State bar ethics opinions in California, New York, and Texas explicitly bless automated legal workflows, compressing procurement cycles for mid-sized firms. HIPAA and SEC data confidentiality rules impose parallel constraints on client-facing platforms. Silicon Valley and New York City host the densest concentration of venture-backed legal AI startups, with Boston and Chicago emerging as secondary hubs for e-discovery vendors.
United Kingdom
Solicitors Regulation Authority guidance lags US state bar permissiveness, creating first-mover advantage for compliant entrants targeting mid-market solicitors. GDPR-aligned data governance requirements accelerate platform replacements in London-based corporate legal departments. The City of London and Manchester legal tech corridors attract vendor regional headquarters seeking proximity to Magic Circle and Silver Circle firms.
Germany
EU AI Act risk-tiered obligations force algorithmic transparency retrofits for automated legal decision systems entering the German market. Federal Bar Association technology competence standards create mandatory training attach points for SaaS vendors. Frankfurt and Munich legal departments delay procurement until vendor certification pathways clarify, creating temporary demand pauses in Europe's largest legal market.
Israel
Defense technology spillover feeds contract analytics and NLP engine development for export to US and European legal markets. The country's national cybersecurity regulator imposes strict data residency requirements that shape product architecture decisions. Tel Aviv hosts a cluster of legal AI startups leveraging military intelligence unit alumni for machine learning engineering talent.
Canada
Provincial law society technology competence requirements in Ontario and British Columbia mirror US state bar permissiveness, accelerating cloud platform adoption. Health Canada and federal privacy commissioner enforcement creates cross-border data architecture complexity for vendors serving US-Canada dual jurisdictions. Toronto and Vancouver legal tech ecosystems benefit from proximity to US customers combined with lower operational costs.
Legal Technology Market Key Industry Players
Concentration sits with venture-backed specialists rather than incumbent enterprise software conglomerates. The vendor base spans three tiers: well-funded AI-native startups, established practice management incumbents, and legacy e-discovery platforms. Dominant competitive moves include M&A for proprietary training data access and strategic partnerships with bar associations for distribution channel control.
Within the AI-native tier, Harvey and Darrow exemplify the archetype of generative legal models trained on proprietary corpora. Ironclad anchors the contract lifecycle automation segment with corporate legal department focus. Clio occupies a position of dominant channel control across North American solo and small-firm segments through bar association partnerships. Checkr, Everlaw, and Relativity represent specialized concentrations in background screening and e-discovery respectively.
| Leading Market Players |
|---|
| Checkr |
| Ironclad |
| Harvey |
| Darrow |
| Everlaw |
| Relativity |
| Clio |
| LegalMation |
| Brightflag |
| Others |
Cost & Logistics Intelligence
EU AI Act conformity assessment requirements gate both vendor qualification and price differentiation simultaneously, forcing non-EU suppliers to establish representative arrangements before market access while creating tiered certification premiums for compliant platforms.
Pricing Analysis
EU AI Act risk-tiered obligations dictate the pricing tier structure across automated legal decision systems, with high-risk applications commanding certification premiums before German or French procurement teams release budget. SaaS subscription models with automatic security patching displace perpetual licenses, compressing upfront revenue into recurring streams. Price differentiation hinges on proprietary training data depth and GDPR-aligned data residency guarantees. Mid-sized law firms in the United States exhibit highest price sensitivity as they compress vendor sales cycles, while Fortune 500 legal operations centers internalizing contract analytics functions show lowest sensitivity to per-seat costs.
Supply Chain Analysis
Software delivery eliminates physical inventory buffers, compressing implementation timelines to API integration schedules and EU representative certification lead times. Development talent concentrates in the United States, United Kingdom, and Israel, with Tel Aviv military intelligence alumni feeding NLP engine specialization. Cloud infrastructure draws from hyperscaler data centers in Ireland, Frankfurt, and Virginia, tethering latency performance to regional node proximity. Single-source vulnerability sits with proprietary legal corpora licensing from Magic Circle and Am Law 200 firms. Distribution runs through bar association partnerships and Big Four accounting firm white-label resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Legal technology presents a service-attach opportunity where training and compliance modules expand faster than core platform licenses, with EU AI Act certification pathways creating recurring retrofit demand.
For Market Incumbents: Consolidate proprietary training data access through exclusive corpus licensing with Am Law 200 firms, blocking Harvey-style generative AI entrants from matching negotiation analytics depth. Deepen API connectivity investments to displace legacy iManage and NetDocuments resistance, accelerating mid-sized law firm procurement cycles. Vertical integration into compliance tracking modules captures EU AI Act retrofit demand before certification pathways clarify.
For New Entrants and Emerging Players: Lead with underpenetrated United Kingdom mid-market solicitors where SRA guidance lags US state bar permissiveness, creating first-mover advantage for compliant contract lifecycle platforms. Target carbon accounting convergence with ESG clause libraries, embedding into CSRD disclosure-driven procurement software stacks. Channel through Big Four accounting firm audit relationships, bypassing traditional law firm gatekeepers entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract analytics specialists holding proprietary clause libraries but lacking SaaS delivery infrastructure. Five-to-ten year viability hinges on generative AI training data moats deepening faster than open-source legal models commoditize first-draft capabilities. Watch for state bar ethics opinion velocity as inflection indicator—accelerating permissiveness signals procurement cycle compression ahead.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Corpus Licensing | Exclusive training data agreements with Magic Circle firms block competitor AI model parity. |
| EU Representative Establishment | GDPR-aligned data residency arrangements unlock German and French corporate legal department budgets. |
| Bar Association Partnership | Continuing education credit attach points replicate Clio's channel control across state bar jurisdictions. |
| API-First Architecture | Native connectivity to ERP systems displaces legacy document management resistance in corporate procurement. |
| ESG Clause Library Integration | CSRD disclosure requirements pull carbon accounting modules into contract lifecycle management stacks. |
Research Approach
Desk research of SEC filings, state bar ethics opinions, and EU regulatory guidance preceded structured interviews with legal technology procurement officers, compliance directors at corporate legal departments, and bar association technology committee chairs. Primary fieldwork captured mid-sized law firm software procurement velocity and Fortune 500 legal operations center internalization trends. Secondary validation drew from vendor pricing disclosures, GDPR certification databases, and e-discovery volume statistics. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across deployment models, end-user sophistication tiers, and functionality maturity gradients shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type substitution pressure, buyer archetype pricing elasticity, and regional regulatory adoption patterns. CAGRs derived from historical procurement cycle compression rates and cloud migration trajectories, with inputs from EU AI Act implementation timelines and US state bar technology competence requirement diffusion curves.
The analysis sits within stated boundaries; outcomes outside EU AI Act certification pathway clarity or US state bar ethics opinion acceleration would require recalibration. Forecasts reflect documented assumptions about mid-sized firm procurement velocity and corporate legal department SaaS conversion rates. Regulatory enforcement intensity around HIPAA data confidentiality and algorithmic transparency mandates represents primary revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Communication Intelligence Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Smart Government Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Web Content Management Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Sales Acceleration Technology Market