
 Game Engines Market | 2026-2036
Game Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Game Engines Market Intelligence
Real-time ray tracing capability is rotating from premium tier to baseline expectation across commercial game engines. Epic Games anchors high-fidelity production pipelines through its Unreal Engine ecosystem. Unity Technologies leverages cross-platform deployment tools to sustain indie and mobile studio loyalty. Godot Engine competes on open-source architecture, differentiating through zero licensing friction.
A game engine is an integrated software framework providing rendering, physics simulation, audio processing, and scripting environments, typically supporting C++, C#, or visual node-based logic with target frame rates of 30-120 FPS across hardware profiles. Its primary commercial purpose is enabling interactive digital content production for entertainment, training, and spatial computing applications. 3D engines capture the dominant value pool as AAA and virtual production budgets expand, while VR engines represent the fastest-growing segment driven by headset hardware cycles and enterprise simulation demand. Cloud-based delivery models are gaining structural share as studios prioritize distributed collaboration and reduced local infrastructure overhead.
The Federal Communications Commission shapes US broadband infrastructure standards that underpin cloud engine latency requirements, while the EU AI Act imposes transparency obligations on procedural content generation tools embedded in European-deployed engines. South Korea's Ministry of Trade, Industry and Energy funds real-time graphics R&D through national digital content initiatives, directing domestic engine adoption patterns. Stakeholders must monitor how hardware-software co-evolution between GPU manufacturers and engine developers redefines performance baselines and licensing economics.
Market Dynamics
Real-time ray tracing maturation is compressing the premium-to-baseline fidelity gap across commercial game engines, forcing pricing and licensing model recalibration throughout the developer ecosystem.
Growth Catalysts
- South Korea's Digital Content Initiative:The Ministry of Trade, Industry and Energy directs public R&D funding toward real-time graphics infrastructure, accelerating domestic engine adoption among Seoul-based studios.
- Cloud Rendering Pipelines:Distributed compute architectures enable small teams to access AAA-grade lighting and physics without local workstation investment.
- Enterprise Simulation Demand:Defense contractors and automotive manufacturers repurpose game engines for training environments, expanding addressable use cases beyond entertainment.
Market Restraints
- GPU Supply Concentration:Taiwan-based foundry capacity constraints create hardware procurement bottlenecks for ray tracing-enabled development kits.
- EU AI Act Compliance Costs:Procedural content generation tools face transparency documentation requirements that extend European deployment timelines.
- Skill Premium Inflation:Specialized shader programming and real-time optimization expertise command compensation multiples that strain indie studio burn rates.
Strategic Opportunities
- India's PLI Scheme Extension:Production-linked incentives for digital content creation attract engine localization investments and training center establishment.
- Spatial Computing Convergence:Mixed reality headset cycles create demand for lightweight, low-latency rendering stacks optimized for untethered devices.
- Node-Based Visual Scripting:Non-programmer creative teams adopt no-code logic tools, expanding the buyer base beyond traditional engineering profiles.
Industry Challenges
- Cross-Platform Optimization Complexity:Fragmented console, mobile, and PC hardware profiles multiply QA and performance tuning workloads.
- Legacy Codebase Integration:Established studios face friction migrating proprietary tools and asset pipelines to modern engine architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Game Engines Market |
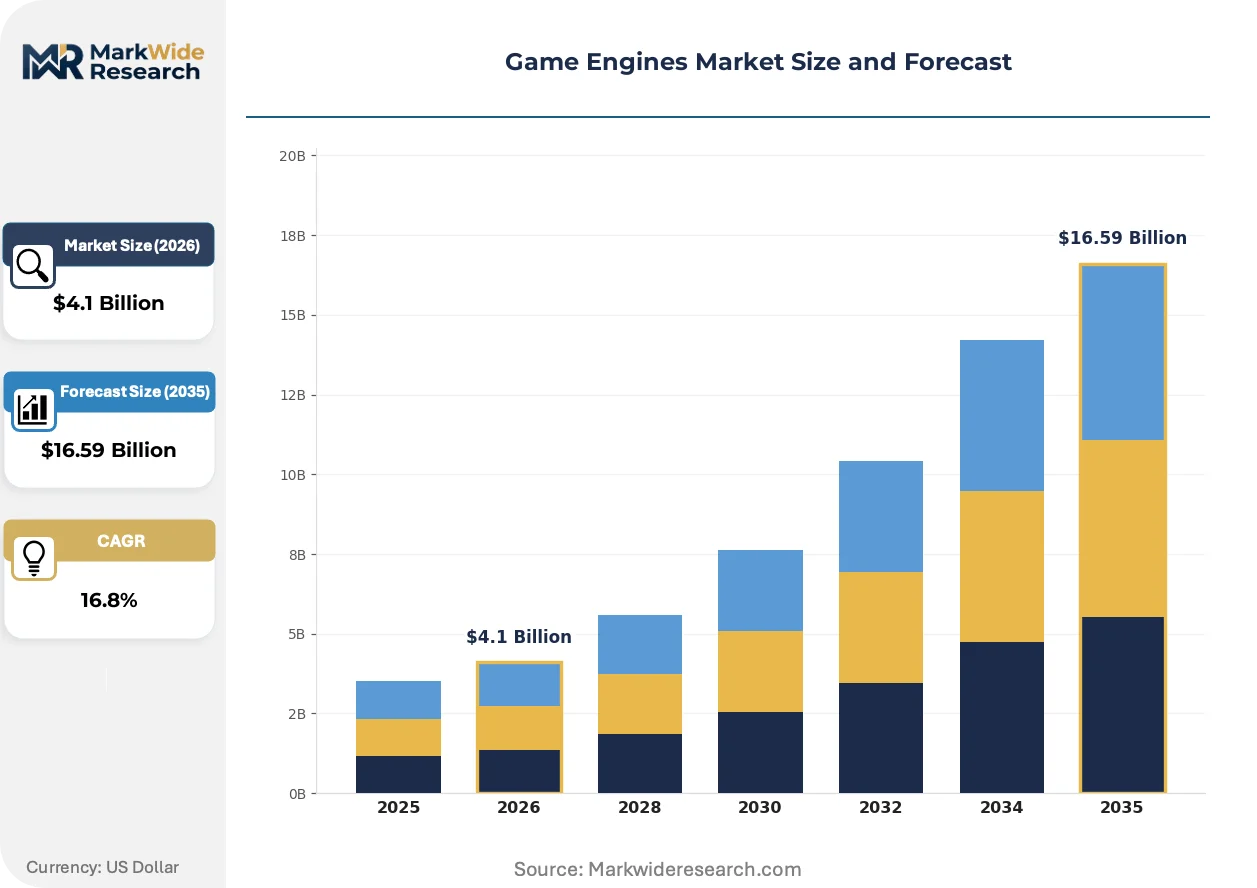
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $16.59 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Engines, 3D Engines, Hybrid Engines, VR Engines Delivery Model: Cloud-Based, On-Premises, Subscription-Based, Open-Source End User: Indie Developers, Large Studios, Education Institutions, Hobbyists Industry Vertical: Gaming, Film Production, Simulation, Virtual Reality |
| Companies Covered | YoYo Games Ltd., Godot Engine, Unity Technologies, GameSalad, Clickteam, Epic Games, Crytek GmbH, Stencyl LLC, Cocos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Game Engines Market Strategic Shifts & Innovations
Neural rendering techniques and hardware-software co-design are collapsing traditional production timelines, enabling real-time iteration workflows that reshape how interactive content reaches market.
Neural radiance fields (NeRF) and Gaussian splatting are decomposing conventional photogrammetry and manual asset creation pipelines. Indie studios and virtual production houses adopt these tools for rapid environment prototyping, compressing pre-production cycles from months to days.
The EU AI Act imposes documentation and audit requirements on procedural generation systems embedded in European-deployed engines. Developers must now maintain transparency logs for AI-assisted content creation, affecting tool design priorities and compliance staffing. German and French studios are responding by segregating AI-dependent features into optional modules.
Subscription-based engine access is displacing perpetual licensing among mid-size studios. Monthly or per-seat arrangements reduce upfront capital requirements and align costs with project phases. This pattern concentrates in the United States and United Kingdom, where cash-flow-sensitive teams prioritize operational flexibility over long-term asset ownership.
Game Engines Market Segmentation
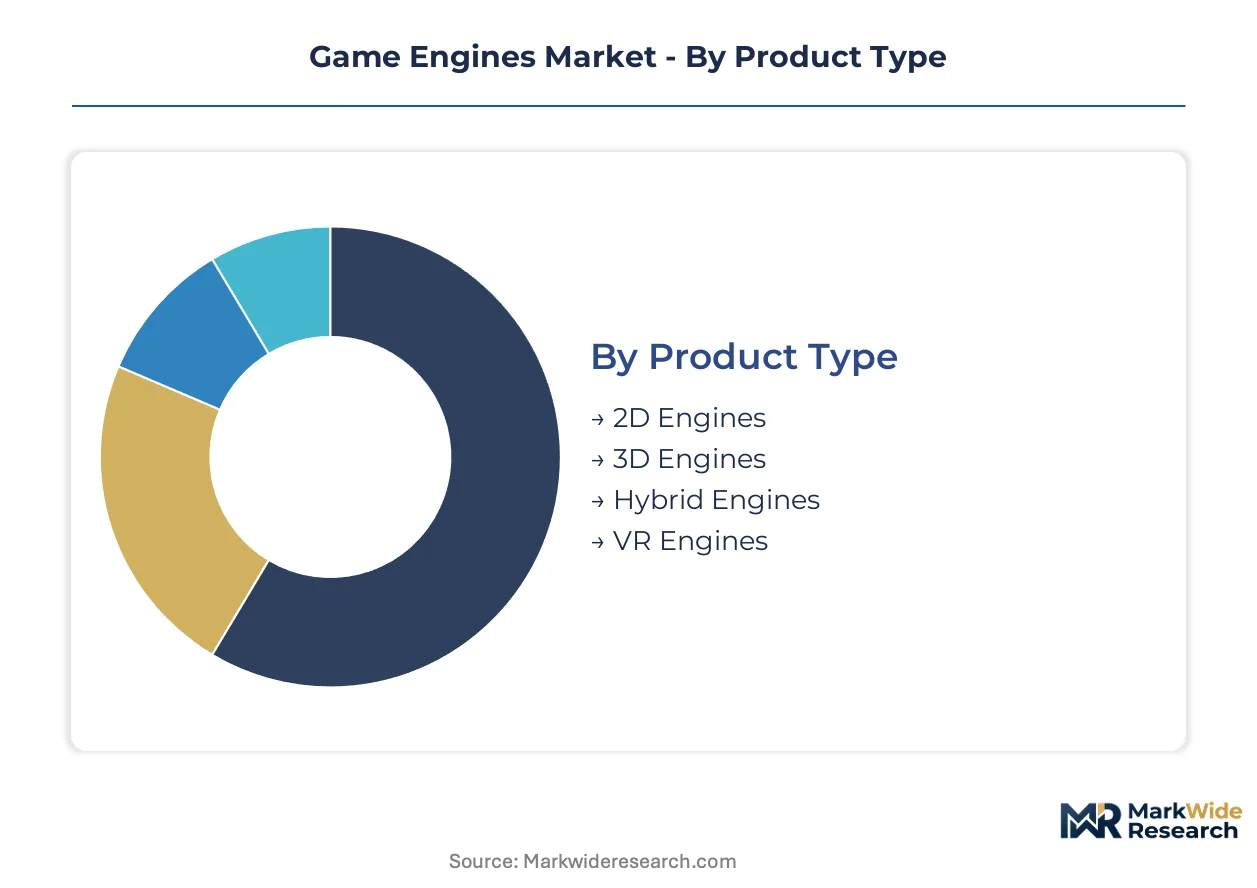
Engine architecture and deployment economics create distinct margin pools that reshape how vendors allocate R&D and pricing power. Segment boundaries are blurring as cloud delivery and neural rendering compress traditional technical distinctions between indie and enterprise toolsets.
Product Type:
Margin concentration sits with engines that amortize development costs across the widest addressable developer base while maintaining premium-tier feature differentiation.
- 3D Engines:Full-featured rendering stacks supporting real-time ray tracing, physics simulation, and cinematic post-processing pipelines. AAA studios in the United States and South Korea anchor demand as virtual production budgets expand and government digital content funds flow toward high-fidelity infrastructure.
- VR Engines:Lightweight architectures optimized for sub-20ms motion-to-photon latency and foveated rendering on untethered headsets. Enterprise simulation contracts from defense contractors and automotive manufacturers in the United Kingdom are compressing development cycles and validating new compression algorithms.
- 2D Engines:Sprite-based frameworks with minimal GPU dependency, serving mobile-first indie teams and retro aesthetic projects. Pixel-art revival trends and Nintendo Switch porting workflows sustain niche loyalty.
- Hybrid Engines:Modular architectures allowing runtime switching between 2D and 3D rendering contexts. Cross-platform mobile studios value the single-codebase efficiency for games spanning multiple visual styles.
The dominant share belongs to 3D Engines, while VR Engines are expanding most quickly as headset hardware cycles accelerate.
Delivery Model:
Recurring revenue multiples and customer lifetime value diverge sharply based on how infrastructure ownership and compliance burdens distribute between vendor and user.
- Subscription-Based:Monthly or per-seat access with tiered feature gates and cloud build pipeline inclusion. Mid-size studios in the United States and United Kingdom prioritize cash-flow flexibility over perpetual license ownership.
- Cloud-Based:Fully managed rendering and collaboration environments with zero local workstation requirements. Distributed teams and remote indie collectives leverage this model to access AAA-grade lighting without capital expenditure.
- Open-Source:Zero-licensing-friction repositories with community-driven plugin ecosystems and optional commercial support contracts. Godot Engine anchors this segment through foundation-backed governance and transparency.
- On-Premises:Perpetual licenses with air-gapped deployment for defense and intelligence simulation contracts. EU AI Act documentation requirements and data sovereignty mandates preserve this model for sensitive European applications.
Subscription-Based arrangements command the highest revenue per seat, though Cloud-Based delivery is climbing the fastest as broadband infrastructure matures.
End User:
Customer acquisition cost and support burden scale inversely with technical sophistication, creating tension between volume and margin targets.
- Large Studios:Multi-hundred-seat deployments with custom source licensing and dedicated technical account management. Epic Games and Unity Technologies compete for these accounts through enterprise support tiers and co-development partnerships.
- Indie Developers:Small teams with revenue-share or low-cost subscription sensitivity, driving adoption of lightweight toolsets and no-code visual scripting. South Korea's Ministry of Trade, Industry and Energy funding accelerates domestic indie engine adoption.
- Education Institutions:Site-licensed academic programs with curriculum integration requirements and student certification pathways. Unreal and Unity dominate through accredited training programs and educator grants.
- Hobbyists:Non-commercial users with zero willingness-to-pay, serving as talent pipeline feeders and community content generators. Open-source engines capture disproportionate share in this segment.
Large Studios contribute the highest absolute revenue, yet Indie Developers are gaining share fastest as lightweight toolsets democratize production access.
Industry Vertical:
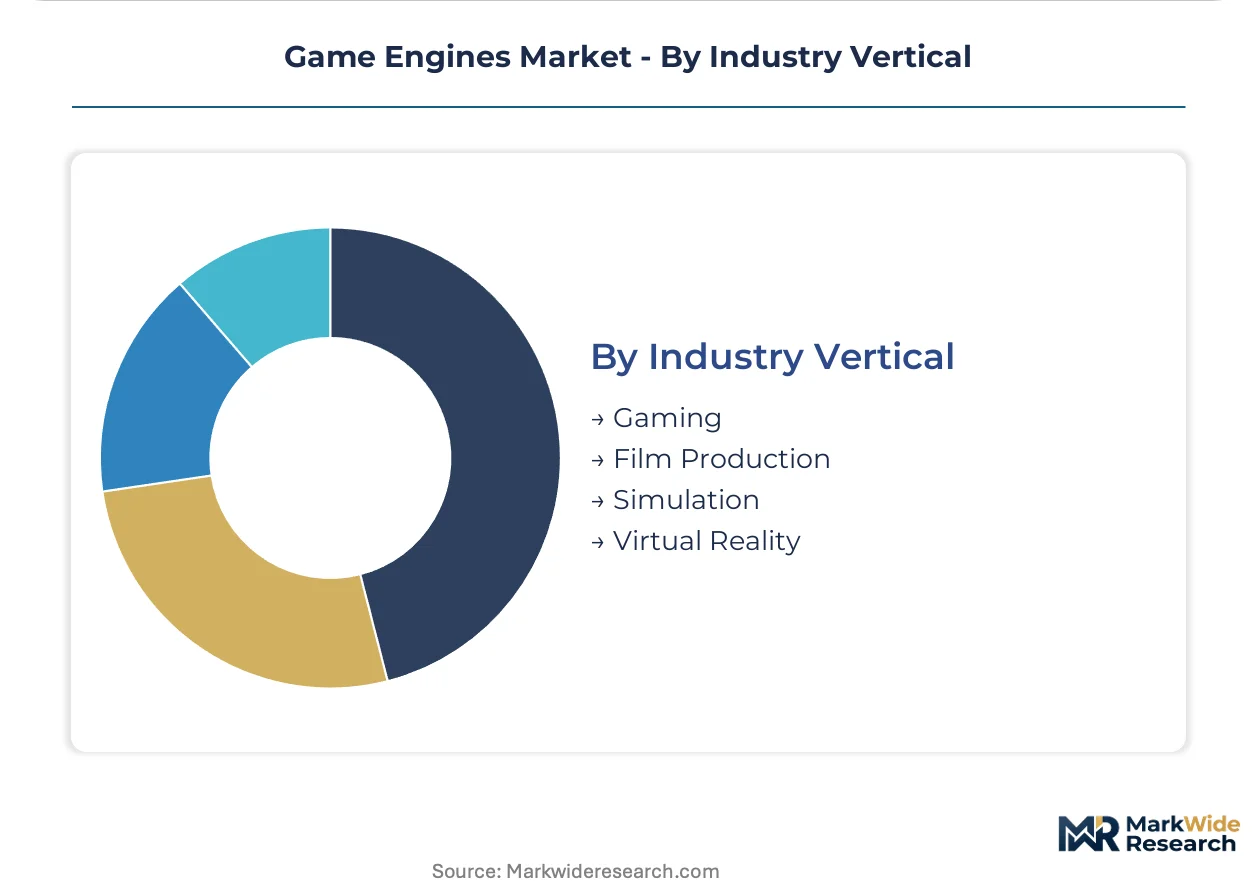
Application context dictates performance benchmarks, compliance exposure, and sales cycle length more than raw technical specifications.
- Gaming:Interactive entertainment with frame-rate targets from 30 FPS on mobile to 120 FPS on console and PC. The United States, South Korea, and United Kingdom cluster the densest studio ecosystems.
- Simulation:Defense, automotive, and medical training environments with deterministic physics and hardware-in-the-loop integration. The EU AI Act imposes transparency documentation on procedural content generation tools deployed in European simulation contracts.
- Film Production:Virtual production stages with LED volume synchronization and real-time camera tracking. Epic Games' Unreal Engine anchors this vertical through In-Camera VFX partnerships.
- Virtual Reality:Spatial computing applications spanning enterprise training and consumer entertainment. Mixed reality headset cycles from Meta and Apple are validating new engine architectures.
Gaming retains the dominant vertical position, while Simulation is closing the gap fastest as defense contractors repurpose entertainment engines for training environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine development talent and studio infrastructure cluster in jurisdictions with active digital content funding regimes and mature broadband ecosystems. The United States, South Korea, United Kingdom, Germany, and Japan anchor the supply base through distinct regulatory and investment frameworks.
United States
Epic Games and Unity Technologies anchor the commercial engine ecosystem through enterprise licensing and virtual production partnerships. The FCC shapes broadband infrastructure standards that underpin cloud-based engine delivery and distributed development workflows. Los Angeles and Seattle studio clusters drive demand for high-fidelity rendering pipelines and real-time cinematography tools.
South Korea
Seoul-based studios expand adoption of lightweight toolsets as government funding accelerates domestic engine development. The Ministry of Trade, Industry and Energy directs public R&D investment toward real-time graphics infrastructure through national digital content initiatives. Busan-Ulsan and Daegu-Gyeongbuk regions concentrate mobile-first indie teams leveraging cross-platform deployment capabilities.
United Kingdom
London and Manchester studio hubs repurpose entertainment engines for defense and automotive simulation contracts. UK regulators impose transparency documentation requirements on procedural content generation tools through EU AI Act alignment protocols. Scotland and Northern Ireland education institutions anchor accredited training programs feeding talent pipelines.
Germany
Frankfurt and Munich automotive manufacturers drive enterprise simulation demand for deterministic physics and hardware-in-the-loop integration. The KBA and federal digital infrastructure programs shape procurement standards for training environment software. Bavaria and Baden-Württemberg industrial clusters validate engine architectures for safety-critical applications.
Japan
Tokyo and Osaka console publishers sustain demand for proprietary toolset integration and legacy codebase migration services. METI funding channels support real-time graphics R&D and spatial computing headset development. Kansai and Chubu regions concentrate mobile and handheld game studios prioritizing optimization for fragmented hardware profiles.
Game Engines Market Key Industry Players
Concentration sits with integrated platform vendors controlling rendering pipeline standards and developer ecosystem lock-in. The competitive structure spans three tiers: enterprise-grade licensors with source code access, subscription-based cross-platform specialists, and open-source community-driven alternatives. Strategic moves center on co-development partnerships with hardware manufacturers and vertical integration into cloud build infrastructure.
Within the enterprise licensing tier, Epic Games and Unity Technologies exemplify platform-scale positioning through engine-agnostic service layers and virtual production toolchains. Crytek GmbH occupies a specialized position representing European-origin high-fidelity rendering specialists. Godot Engine anchors the open-source archetype through foundation-backed governance and zero-licensing-friction distribution.
| Leading Market Players |
|---|
| YoYo Games Ltd. |
| Godot Engine |
| Unity Technologies |
| GameSalad |
| Clickteam |
| Epic Games |
| Crytek GmbH |
| Stencyl LLC |
| Cocos |
| Others |
Cost & Logistics Intelligence
The EU AI Act gates both supply qualification and price differentiation simultaneously, forcing engine vendors to segregate procedural generation modules or absorb compliance staffing costs that stratify subscription tiers. This regulatory architecture compresses margins on entry-level offerings while enabling premium pricing for air-gapped, documentation-ready deployments. Pricing pressure feeds back into supply choices as studios prioritize cloud-based delivery to shift infrastructure overhead from capital to operational expenditure.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European-deployed engines, separating compliant documentation-ready tiers from standard cloud offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with enterprise source licensing commanding multiples above per-seat subscriptions. Cost compression in the indie tier intensifies because Godot Engine's zero-friction open-source model anchors price expectations at zero. Hobbyists and non-commercial users exhibit highest price sensitivity, while defense contractors and automotive manufacturers demonstrate lowest sensitivity due to deterministic physics requirements and air-gapped deployment mandates.
Supply Chain Analysis
Taiwan Strait transit underwrites GPU foundry access that anchors ray tracing-enabled development kit availability. Supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductor fabrication, with NVIDIA and AMD silicon feeding engine hardware requirements. Raw material dependencies span photoresist chemicals, high-purity silicon wafers, and specialized packaging substrates. Single-source vulnerability runs through TSMC's leading-edge node capacity, where any disruption would cascade through AAA studio procurement timelines. Distribution runs through direct OEM partnerships and cloud hyperscaler marketplaces, with Amazon Web Services and Microsoft Azure hosting managed engine instances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where interoperability standards and neural rendering toolchains determine ecosystem lock-in depth. The collapse of traditional asset creation pipelines toward real-time iteration workflows reshapes how vendors capture and retain developer relationships.
For Market Incumbents: Compound platform stickiness through deeper Unreal Engine-Unity source licensing tiers that embed custom technical account management. Defend against Godot Engine's zero-friction encroachment by accelerating visual scripting accessibility for non-programmer creative teams. Backward integration into cloud build infrastructure captures distributed collaboration demand and raises switching costs for mid-size studio accounts.
For New Entrants and Emerging Players: Lead with spatial computing convergence as mixed reality headset cycles validate lightweight, low-latency rendering architectures. India's PLI scheme extension for digital content creation offers the most penetrable geography for training center establishment and engine localization investment. Go-to-market should anchor in node-based visual scripting tools that expand the buyer base beyond traditional engineering profiles toward designer-dominated indie collectives.
For Investors and Strategic Acquirers: The EU AI Act reshapes the acquisition landscape by elevating compliance infrastructure and documentation tooling from cost center to competitive moat. Long-term viability over the coming decade hinges on capturing enterprise simulation contracts from defense and automotive verticals where deterministic physics requirements sustain pricing power. Acquisition targets should display hybrid engine architectures with runtime 2D-3D switching capability. The signal to monitor is South Korea's Ministry of Trade, Industry and Energy funding disbursement velocity, which indicates real-time graphics R&D commitment and domestic engine adoption momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Pipeline Expansion | Amazon Web Services and Microsoft Azure partnerships enable AAA-grade access without workstation capital expenditure. |
| Neural Rendering Toolchain Integration | NeRF and Gaussian splatting adoption compresses pre-production cycles from months to days for virtual production houses. |
| Spatial Computing Optimization | Meta and Apple headset validation cycles demand sub-20ms motion-to-photon latency architectures for untethered devices. |
| EU AI Act Compliance Modularization | Segregating procedural generation into optional modules preserves European deployment timelines and documentation transparency. |
| India Training Center Establishment | PLI scheme extension attracts localization investment and builds certified talent pipelines for regional studio ecosystems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and government digital content initiative budgets. Primary interviews engaged game engine CTOs, indie studio technical directors, platform integration specialists, and cloud infrastructure procurement officers. Secondary validation drew from FCC broadband infrastructure standards, EU AI Act implementation guidance, and South Korean Ministry of Trade, Industry and Energy funding disclosures. Bottom-up triangulation across individual studio deployment patterns converged with top-down analysis of vendor licensing revenue disclosures.
Segmentation dimensions modeled span engine architecture type, delivery model, end-user scale, and industry vertical application across the projection horizon. Deployment model segmentation captures subscription-based, cloud-based, open-source, and on-premises arrangements. End-user scale differentiates large studios, indie developers, education institutions, and hobbyists. CAGRs were derived from installed base growth rates and revenue-per-seat trajectories, incorporating neural rendering adoption curves and spatial computing headset shipment forecasts as industry-specific inputs.
Forecasts assume regulatory continuity in EU AI Act implementation and South Korean digital content funding regimes; material policy shifts would require re-modeling compliance cost burdens and R&D incentive availability. Specific risks include Taiwan-based foundry capacity constraints affecting ray tracing hardware availability, and skill premium inflation in shader programming expertise that could compress indie studio formation rates. Revision becomes warranted when GPU supply concentration indicators or broadband infrastructure deployment velocity cross thresholds that alter cloud-based delivery economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
G2P Systems Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Poland ICT Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Data Governance Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Utility Cases Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Enterprise Search Market