
 Force Gauge Market | 2026-2036
Force Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Force Gauge Market Analysis
Calibration-as-a-service and cloud-connected validation protocols are realigning how force gauge vendors monetize hardware. Ametek Inc. leverages its global service infrastructure to bundle recertification with instrument sales. Imada Inc. anchors its competitive position through deep specialization in handheld digital gauges for assembly line environments. Mecmesin Ltd. differentiates via software-defined test automation that extends hardware utility beyond standalone measurement.
A force gauge is an instrument that quantifies tensile or compressive force, typically employing strain gauge transducers with resolutions down to 0.1% of full scale and sampling rates exceeding 1,000 Hz for dynamic capture. It serves industrial quality assurance, material characterization, and regulatory compliance verification across production environments. Digital force gauges now dominate unit shipments due to embedded data logging and USB output compatibility, while wireless variants represent the fastest-expanding category as shop-floor IoT architectures proliferate. Mechanical force gauges retain niche positions in explosive atmospheres where electrical ignition risks exclude electronic alternatives. Strain gauge technology commands the largest installed base, though piezoelectric architectures capture premium applications requiring microsecond response times.
ISO 376 calibration standards, NIST traceability protocols, and FDA 21 CFR Part 11 electronic records requirements shape product design and market access for force gauge suppliers serving regulated industries. OSHA workplace safety mandates in US manufacturing plants drive periodic load verification, while CE marking under EU MDR pressures medical device manufacturers toward documented force validation. Stakeholders must monitor how evolving cybersecurity frameworks for connected instruments reshape software update obligations and liability exposure.
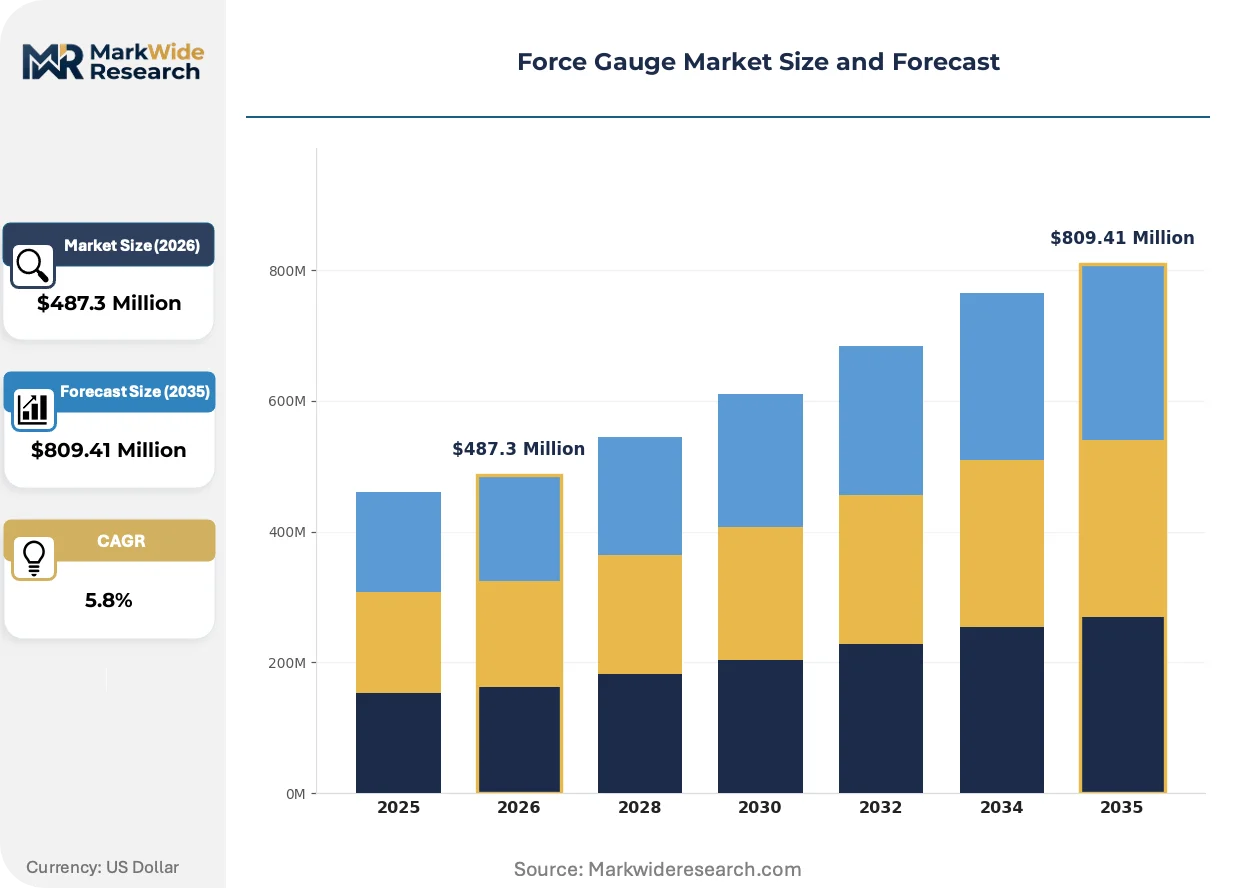
Market Dynamics
Cloud-connected validation protocols are consolidating purchasing power among tier-one manufacturers while fragmenting demand across mid-tier suppliers who cannot absorb recurring software subscription costs. This structural tension between hardware commoditization and service monetization defines competitive positioning.
Growth Catalysts
- ISO 376 Calibration Mandates:Tighter traceability requirements in European medical device manufacturing are forcing replacement cycles for legacy mechanical gauges. Laboratories in Germany and Switzerland now demand documented NIST-equivalent validation for cross-border shipments.
- Strain Gauge Resolution Improvements:Transducer manufacturers have achieved 0.05% full-scale accuracy at industrial price points. Automotive seat assembly lines in Japan and South Korea are retrofitting stations with these sensors to eliminate destructive testing of safety-critical components.
- OSHA Load Verification Enforcement:US manufacturing plants face intensified workplace safety inspections. Third-party calibration contracts now bundle force gauge recertification with crane and hoist inspections, expanding addressable service revenue.
Market Restraints
- Semiconductor Input Volatility:ADC chip shortages disrupt digital gauge production schedules. Taiwanese foundry concentration creates 16-24 week lead time variability for high-sampling-rate instruments.
- Piezoelectric Substitution Ceiling:Ceramic sensor elements capture dynamic testing above 10 kHz but remain cost-prohibitive for static quality control. Price gaps exceeding 400% block adoption outside aerospace and munitions testing.
- CE Marking Documentation Burden:EU MDR technical file requirements extend product launch timelines by 8-14 months for wireless-connected gauges. Small manufacturers lack regulatory affairs capacity to navigate notified body backlogs.
Strategic Opportunities
- India PLI Manufacturing Incentives:Production-linked subsidy schemes for electronics and medical devices are attracting gauge vendors to establish local calibration laboratories. BIS certification requirements create captive demand for traceable force measurement infrastructure.
- Battery Cell Stack Compression Monitoring:Lithium-ion assembly lines require real-time force feedback during electrode pressing and cell stacking. This application segment lacks standardized sensor integration protocols, opening white space for system-level solution providers.
- 5G-Enabled Predictive Maintenance:Ultra-reliable low-latency communication allows force gauges to feed edge-computing platforms for tool-wear prediction. German automotive suppliers are piloting this convergence to reduce unplanned stamping press downtime.
Industry Challenges
- Metrology Technician Scarcity:ISO 17025-accredited calibration laboratories report 18-month vacancy cycles for force-specific metrologists. Vocational training programs emphasize dimensional measurement over mechanical force traceability.
- Legacy System Integration Friction:Shop-floor MES architectures built on 1990s-era PLC protocols lack native digital gauge communication handlers. Middleware development costs consume 15-25% of instrument project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Force Gauge Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Force Gauges, Mechanical Force Gauges, Wireless Force Gauges, Portable Force Gauges End User: Aerospace, Automotive, Electronics, Manufacturing Application: Quality Control, Research & Development, Material Testing, Calibration Technology: Strain Gauge, Load Cell, Piezoelectric, Hydraulic |
| Companies Covered | Shimpo Instruments, Mark-10 Corporation, Imada Inc., Mecmesin Ltd., Ametek Inc., Instron, Sauter GmbH, PCE Instruments, Extech Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Force Gauge Market Emerging Trajectories
Wireless force gauge architectures are compressing installation timelines and enabling density of measurement points that wired infrastructure cannot economically support. This connectivity shift is reshaping how vendors package hardware, software, and service components.
Digital force gauges with embedded edge-computing capabilities are overtaking basic USB-output models in unit economics for high-volume assembly environments. Tier-one electronics contract manufacturers in Mexico and Vietnam now specify onboard statistical process control algorithms as standard procurement criteria. The technology is overtaking traditional gauge-plus-PC configurations by eliminating cabling failure modes and reducing per-station footprint by 60%.
FDA 21 CFR Part 11 electronic records requirements are forcing medical device manufacturers to validate software update processes for connected gauges. This regulatory pressure is compressing vendor liability exposure and driving consolidation toward suppliers with documented quality management systems. Pharmaceutical packaging lines in Ireland and Puerto Rico now require audit trails for every force measurement touchpoint, favoring vendors with pre-validated software stacks.
After-sales service unbundling is fragmenting purchasing decisions between capital equipment committees and operational technology budgets. Japanese automotive suppliers increasingly lease calibration capacity rather than owning gauge assets, forcing vendors to restructure revenue recognition and field service organizations. This behavioral shift is most visible in Toyota and Honda supply chain clusters where total cost of ownership models dominate supplier scorecards.
Force Gauge Market Segmentation
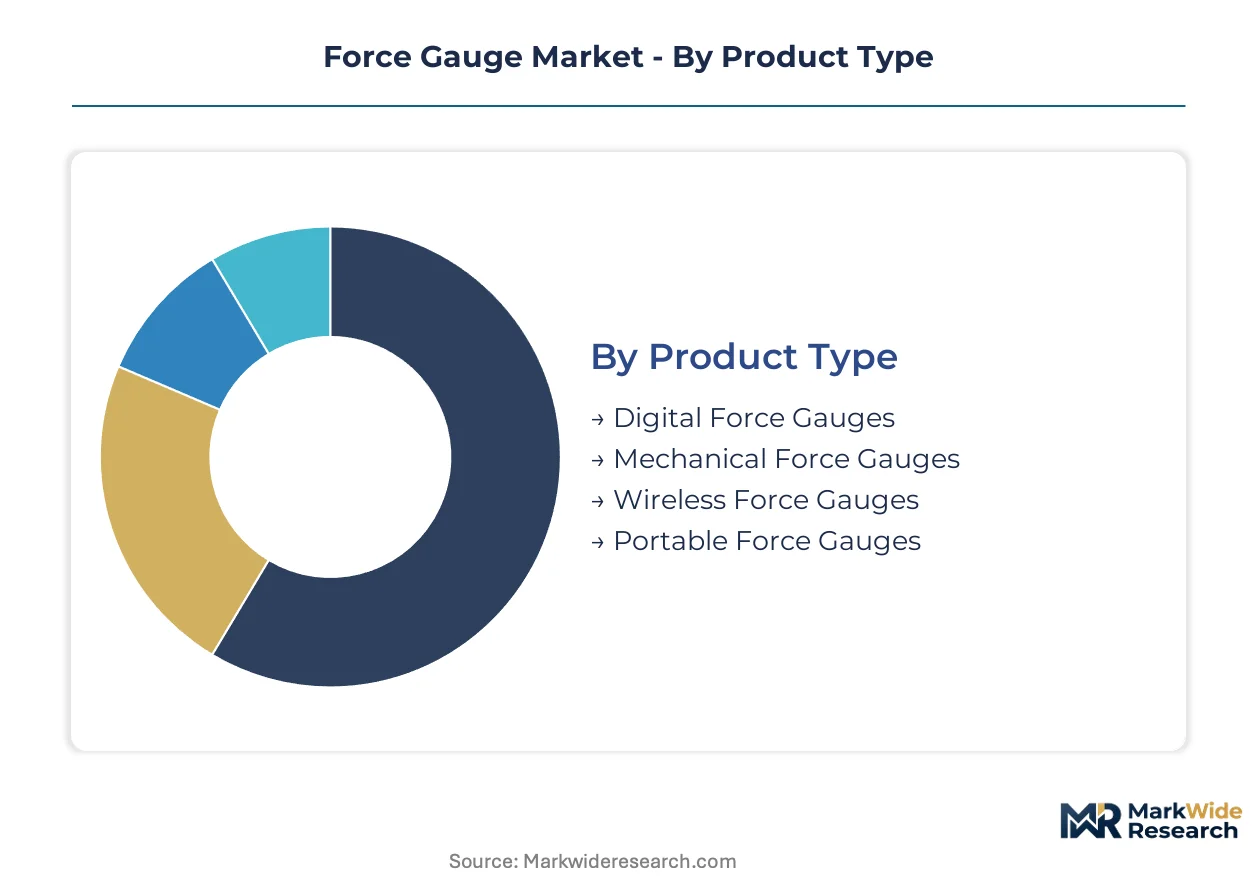
Force gauge segmentation reveals divergent technology lifecycles and pricing architectures. Product type splits between mature mechanical units and digitally connected platforms, while end-user concentration in precision manufacturing drives specification requirements.
Product Type:
Digital variants dominate unit shipments through embedded data logging, while wireless architectures command premium positioning through shop-floor IoT integration.
- Digital Force Gauges:Strain gauge transducers with 0.1% full-scale resolution and USB output compatibility anchor industrial quality assurance. Electronics contract manufacturers in China and Mexico specify these for assembly line torque verification, with automotive seat suppliers in Japan retrofitting stations to eliminate destructive testing protocols.
- Wireless Force Gauges:Bluetooth and Wi-Fi-enabled architectures eliminate cabling failure modes and reduce per-station footprint by 60%. Tier-one electronics manufacturers in Vietnam and Mexico now require onboard statistical process control algorithms as standard procurement criteria, compressing installation timelines for dense measurement point deployments.
- Mechanical Force Gauges:Spring-based analog instruments retain explosive atmosphere applications where electrical ignition risks exclude electronic alternatives, per OSHA workplace safety mandates.
- Portable Force Gauges:Battery-powered handheld units serve field calibration and maintenance operations in distributed manufacturing footprints.
Today's leader: Digital Force Gauges. Tomorrow's challenger: Wireless Force Gauges.
End User:
Application intensity varies sharply by sector, with automotive and electronics driving specification tightening while aerospace maintains certification-driven replacement cycles.
- Automotive:Seat assembly lines and stamping press monitoring require real-time force feedback with millisecond response times. German automotive suppliers pilot 5G-enabled predictive maintenance to reduce unplanned downtime, feeding edge-computing platforms for tool-wear prediction.
- Electronics:Lithium-ion battery cell stack compression monitoring demands standardized sensor integration protocols for electrode pressing operations. Electronics manufacturers in South Korea and Japan expand quality control programs as precision manufacturing scales.
- Aerospace:Munitions and structural testing above 10 kHz sustain piezoelectric gauge demand despite 400% price premiums over strain gauge alternatives.
- Manufacturing:General industrial quality assurance spans OSHA-mandated load verification and ISO 376 calibration compliance across US and European plants.
Procurement intensity concentrates in Automotive and Electronics; specification authority resides with Aerospace certification engineers.
Application:
Quality control absorbs the majority of installed base, while calibration services reshape vendor revenue recognition toward recurring subscription models.
- Quality Control:Real-time pass/fail determination on assembly lines with statistical process control integration. Digital gauges with embedded edge-computing overtake basic USB-output configurations in high-volume environments.
- Calibration:NIST traceability and ISO 17025-accredited laboratory services bundle recertification with instrument sales. Japanese automotive suppliers increasingly lease calibration capacity rather than owning gauge assets.
- Material Testing:Destructive and non-destructive characterization of composites, metals, and polymers for R&D and production validation.
- Research & Development:Prototype validation and new product introduction testing with configurable sampling rates and custom fixture integration.
Quality Control maintains installed base dominance; Calibration is gaining share fastest through service monetization.
Technology:
Strain gauge architectures hold cost-performance advantages for static measurement, while piezoelectric systems capture dynamic testing premiums.
- Strain Gauge:Metal foil or semiconductor strain elements achieve 0.05% full-scale accuracy at industrial price points. Resolution improvements to 0.05% are eliminating destructive testing in safety-critical automotive components.
- Load Cell:Dedicated force transducers with wheatstone bridge configurations for precision weighing and force measurement integration.
- Piezoelectric:Ceramic sensor elements deliver microsecond response times for impact testing and dynamic force capture above 10 kHz, limited to aerospace and munitions applications by cost structure.
- Hydraulic:Fluid-based force multiplication for high-capacity testing beyond electrical transducer limits, retaining niche positions in heavy machinery validation.
Strain Gauge commands volume leadership; Piezoelectric defends premium tier through performance differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing force gauge demand as manufacturers relocate production to jurisdictions with streamlined calibration compliance. Cost-of-compliance gaps between mature and emerging markets are accelerating facility migrations across precision manufacturing sectors.
China
Electronics contract manufacturers in Shenzhen and Dongguan are expanding quality control programs as precision manufacturing scales. GB standards and MIIT regulations mandate documented force validation for medical device exports. Yangtze River Delta automotive suppliers retrofit assembly lines with high-resolution strain gauge systems to eliminate destructive testing protocols.
Germany
Automotive seat assembly lines and stamping press operations demand real-time force feedback with millisecond response times. CE marking under EU MDR pressures medical device manufacturers toward documented force validation, extending product launch timelines. Bavarian automotive suppliers pilot 5G-enabled predictive maintenance to reduce unplanned downtime through edge-computing platforms.
United States
OSHA workplace safety mandates drive periodic load verification across manufacturing plants, bundling force gauge recertification with crane and hoist inspections. FDA 21 CFR Part 11 electronic records requirements shape product design for medical device suppliers. Midwest automotive clusters and Southeast electronics manufacturers concentrate procurement authority for digital gauge platforms.
Japan
Automotive seat assembly lines in Toyota and Honda supply chain clusters retrofit stations with 0.05% full-scale accuracy sensors. METI industrial standards and JIS calibration protocols tighten product requirements for cross-border shipments. Kanto region electronics manufacturers specify onboard statistical process control algorithms as standard procurement criteria.
India
Production-linked incentive schemes for electronics and medical devices attract gauge vendors to establish local calibration laboratories. BIS certification requirements create captive demand for traceable force measurement infrastructure. Maharashtra and Karnataka pharmaceutical packaging lines require audit trails for force measurement touchpoints, favoring vendors with pre-validated software stacks.
Force Gauge Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with calibration-as-a-service capabilities consolidating purchasing power among tier-one manufacturers. The vendor base organizes around three strategic archetypes: diversified instrumentation conglomerates with global service infrastructure, handheld gauge specialists with deep assembly line expertise, and software-defined test automation providers. M&A activity concentrates on acquiring calibration laboratory networks, while geographic expansion targets PLI-subsidized manufacturing zones in South Asia.
Within the diversified instrumentation tier, Ametek Inc. and Instron exemplify scale-driven positions anchored by global service networks. Among handheld specialists, Imada Inc. and Shimpo Instruments occupy positions defined by assembly line deployment density. Mecmesin Ltd. represents the software-defined automation archetype, extending hardware utility beyond standalone measurement through test protocol integration. These three groupings capture distinct value pools: service-annuity revenue, high-volume unit economics, and system-level solution premiums respectively.
| Leading Market Players |
|---|
| Shimpo Instruments |
| Mark-10 Corporation |
| Imada Inc. |
| Mecmesin Ltd. |
| Ametek Inc. |
| Instron |
| Sauter GmbH |
| PCE Instruments |
| Extech Instruments |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO 17025-accredited laboratory instruments and uncertified field units manifests in parallel supply chain configurations. Premium-tier vendors bundle NIST-traceable calibration services with hardware sales, while commodity channels move basic digital gauges through industrial distributors in Shenzhen and Chicago.
Pricing Analysis
Distributor margins of 25-35% separate factory pricing from end-user acquisition cost across most channels. Three-tier pricing structure across premium, standard, and economy levels tracks calibration pedigree and sampling rate performance. Pricing pressure stems from Taiwanese ADC chip shortages that compress margins on high-sampling-rate instruments. Electronics contract manufacturers in Vietnam exhibit highest price sensitivity; aerospace qualification engineers show least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Toyota and Honda supply clusters, while distributor networks serve fragmented maintenance-repair-overhaul demand. Component manufacturing concentrates in China, Japan, and Germany. Strain gauge transducers, ADC chipsets, and calibration weights constitute critical input dependencies. Single-source vulnerability in Taiwanese semiconductor foundries threatens production schedules. Distribution runs through authorized service centers for regulated industries and broad-line industrial distributors elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The force gauge market functions as a regulatory compounder where ISO 376 calibration mandates and FDA 21 CFR Part 11 electronic records requirements generate replacement demand regardless of economic cycles.
For Market Incumbents: Anticipate piezoelectric substitution threats in dynamic testing above 10 kHz by deepening strain gauge resolution investments. Secure calibration laboratory accreditation in India before PLI scheme maturation crowds service capacity. Backward integration into transducer manufacturing insulates against ADC chip shortage volatility. For New Entrants and Emerging Players: Wireless edge-computing architectures with onboard statistical process control algorithms offer the clearest technology-first wedge. Battery cell stack compression monitoring in South Korean and Japanese lithium-ion facilities presents the most penetrable white space. Pursue system-level solution partnerships with electrode press OEMs rather than standalone gauge sales. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration-as-a-service capabilities determine purchasing power among tier-one manufacturers. Five-to-ten year viability favors vendors with pre-validated software stacks for pharmaceutical packaging lines. Acquisition targets should display ISO 17025 laboratory networks and documented quality management systems. Watch for 5G-enabled predictive maintenance pilot conversions in German automotive supply chains as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Captures recurring revenue from ISO 376 and FDA 21 CFR Part 11 compliance mandates. |
| Wireless Edge-Computing Integration | Eliminates cabling failure modes and reduces per-station footprint for dense measurement deployments. |
| Backward Integration into Transducer Manufacturing | Insulates margin structure from ADC chip shortage volatility in Taiwanese foundries. |
| 5G-Enabled Predictive Maintenance Partnership | Feeds edge-computing platforms for tool-wear prediction in German automotive stamping operations. |
| India PLI Zone Calibration Infrastructure | Captures captive demand from BIS certification requirements in Maharashtra pharmaceutical packaging. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews and secondary validation. Conversations with calibration laboratory directors, OEM procurement managers, metrology technicians, and aftermarket service heads informed demand-side dynamics. Secondary sources included OSHA enforcement records, FDA 510(k) filings, EU MDR technical documentation, and customs trade data. Bottom-up gauge shipment estimates triangulated against top-down industrial quality assurance spending.
Granularity-level modeling distinguished product type, end-use industry, application intensity, and technology architecture across the projection horizon. Strain gauge, piezoelectric, and load cell categories were modeled separately with resolution and sampling rate tiers. CAGRs derived from segment-level growth rate reconciliation against macro industrial production indices. Battery cell manufacturing expansion and automotive seat assembly retrofit cycles served as industry-specific demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization and regulatory harmonization between NIST and EU notified bodies. Forecasts reflect documented assumptions regarding calibration mandate enforcement intensity and wireless IoT adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market