
 Mixing Vessels Market | 2026-2036
Mixing Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Mixing Vessels Market Analytics
A capital-intensity divergence between stainless-steel fabrication specialists and modular plastic-vessel assemblers is reorganizing competitive tiers in mixing equipment. SPX FLOW Inc. leverages its vertical integration into precision welding and surface finishing to command premium positioning in pharmaceutical-grade batch systems. Alfa Laval Corporate AB anchors its position through hygienic design leadership and dominant share of aseptic processing installations across Nordic dairy and beverage corridors. EKATO Holding GmbH specializes in agitator-engineering depth, differentiating on computational fluid dynamics capabilities that reduce scale-up risk for specialty chemical clients.
Mixing vessels are enclosed process containers engineered to combine, disperse, emulsify, or homogenize multiphase materials under controlled temperature, pressure, and shear conditions, typically constructed with surface finishes below 0.8 micrometers Ra for hygienic service. Stainless steel dominates pharmaceutical and food-grade demand due to ASME-BPE compliance and clean-in-place compatibility, while carbon steel retains cost advantage in bulk chemical processing where corrosion resistance requirements moderate. Batch mixers occupy the largest installed base across end-use sectors, though continuous mixers are gaining traction in high-volume chemical processing lines where throughput consistency reduces labor and utility costs per ton. High-shear mixers capture concentrated margin pools in cosmetics and active pharmaceutical ingredient manufacturing, where particle-size distribution directly determines product efficacy and regulatory submission success.
The U.S. FDA enforces current Good Manufacturing Practice requirements that mandate material certificates, weld documentation, and surface-roughness validation for vessels in drug-contact service, while the EU MDR extends similar traceability demands to medical-device precursor manufacturing. REACH and RoHS frameworks from ECHA constrain coating and sealant chemistries, pushing vessel suppliers toward compliant elastomer portfolios and welded rather than gasketed construction. China's NMPA alignment with ICH Q7 guidelines for active pharmaceutical ingredient equipment qualification is reshaping export certification requirements for Western fabricators. Stakeholders must monitor evolving harmonization between FDA process analytical technology initiatives and EU GMP Annex 15 qualification standards to anticipate retrofit demand and certification-driven replacement cycles.
Market Dynamics
Pharmaceutical manufacturers are accelerating vessel replacement cycles to accommodate single-use bioprocessing and continuous manufacturing platforms, forcing fabricators to recalibrate welding protocols and surface-finish certifications.
Growth Catalysts
- Biologics capacity expansion:Contract development and manufacturing organizations are commissioning stainless-steel trains for monoclonal antibody production, driving demand for ASME-BPE compliant vessels with automated clean-in-place systems.
- EU MDR traceability mandates:Medical-device precursor manufacturers must now document material certificates and weld logs, compelling vessel upgrades across German and Swiss pharmaceutical clusters.
- High-shear emulsification:Cosmetics formulators require particle-size control below 10 microns for active ingredient stability, concentrating procurement among agitator-engineering specialists with computational fluid dynamics capabilities.
Market Restraints
- Nickel alloy price volatility:316L and 904L stainless steel constitute 35-45% of finished vessel cost, exposing fabricators to London Metal Exchange fluctuations that compress quoted margins.
- Specialized welder scarcity:ASME Section IX-certified orbital welders concentrate in Upper Silesian and Ruhr industrial basins, creating bottlenecks for pharmaceutical-grade surface-finish work.
- Electropolishing capacity limits:Ra sub-0.4 micrometer finishes require dedicated electrolyte baths and wastewater treatment infrastructure that few mid-tier fabricators maintain.
Strategic Opportunities
- Modular plastic-vessel assemblers:Polypropylene and fluoropolymer systems are penetrating vaccine adjuvant and cell-therapy applications where batch-size flexibility outweighs thermal durability requirements.
- India's PLI scheme for active pharmaceutical ingredients:Domestic fermentation capacity expansion under production-linked incentives is generating qualified demand for hygienic-design mixing systems with Indian-language HMI interfaces.
- Process analytical technology integration:FDA guidance on real-time release testing is creating specification pull for vessels with embedded Raman spectroscopy ports and automated sampling manifolds.
Industry Challenges
- Computational fluid dynamics talent gap:Scale-up validation for specialty chemical clients requires simulation engineers capable of modeling multiphase turbulence, a skill set concentrated among German and Swiss academic pipelines.
- Legacy DCS integration friction:Brownfield pharmaceutical sites operate Siemens PCS7 or Emerson DeltaV architectures that resist seamless handshaking with modern vessel-mounted sensors and actuators.
- Dual certification timelines:Simultaneous FDA pre-approval inspection and EU GMP Annex 15 qualification stretches validation schedules, delaying revenue recognition for custom-fabricated trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixing Vessels Market |
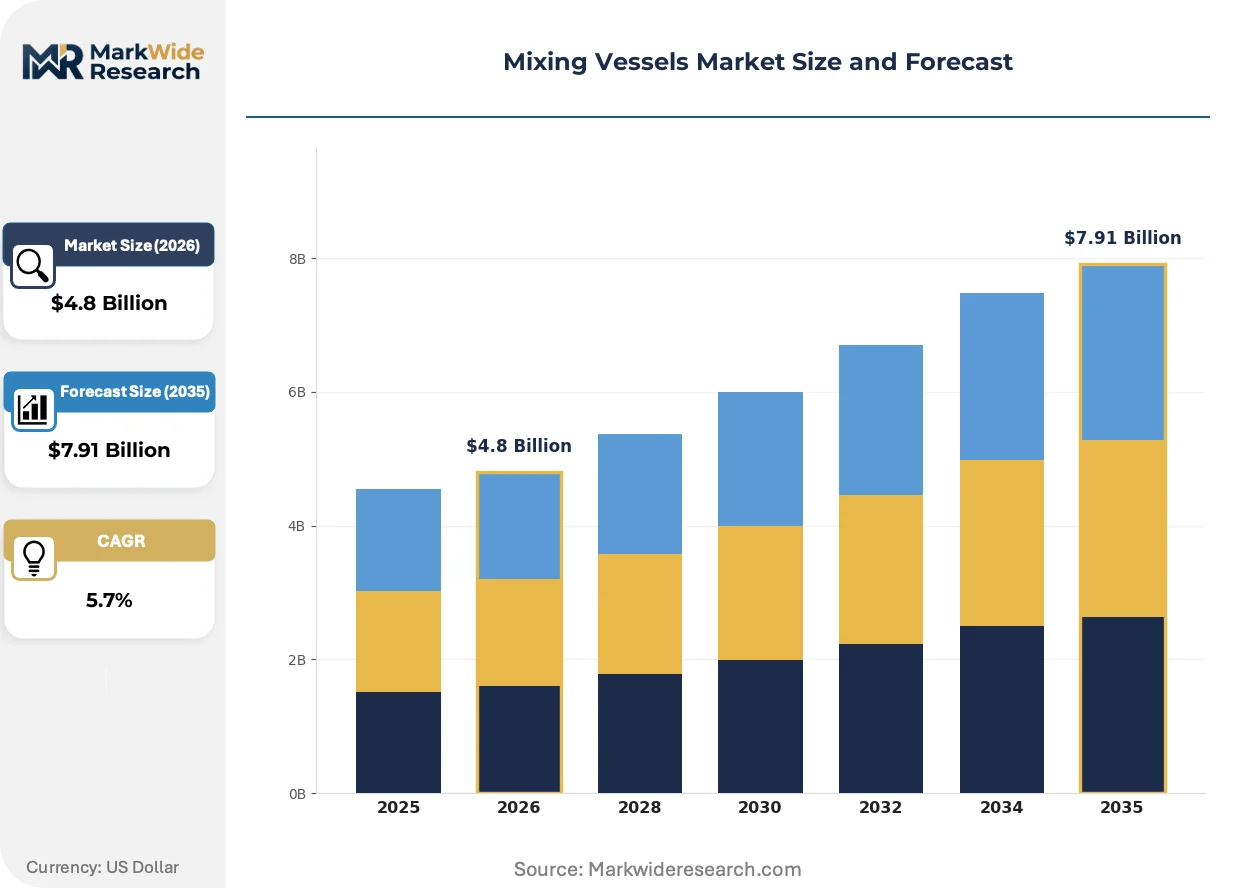
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Batch Mixers, Continuous Mixers, High-Shear Mixers, Planetary Mixers Material: Stainless Steel, Glass, Plastic, Carbon Steel End User: Pharmaceutical, Chemical Processing, Food & Beverage, Cosmetics Application: Emulsification, Homogenization, Suspension, Blending |
| Companies Covered | SPX FLOW Inc., Sulzer Ltd., Alfa Laval Corporate AB, Xylem Inc., GEA Group AG, EKATO Holding GmbH, Gebr. NETZSCH GmbH & Co. Holding KG, Charles Ross & Son Company, Foures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixing Vessels Market Evolving Landscape
Digital twin deployment and additive manufacturing are compressing design-to-commissioning timelines while regulatory convergence between FDA process analytical technology and EU GMP Annex 15 is reshaping specification standards.
Single-use mixing technology is bifurcating the installed base in bioprocessing applications. Vaccine and cell-therapy manufacturers are adopting gamma-irradiated polymeric liners for campaign-based production, eliminating cleaning validation burdens. This shift is bifurcating competitive tiers between precision stainless fabricators and disposable-system assemblers.
REACH and RoHS frameworks from ECHA are constraining elastomer and coating chemistries in sealing applications. Vessel suppliers are migrating toward welded diaphragm valves and compliant fluoroelastomer portfolios to maintain European market access. Specialty chemical processors in Ludwigshafen and Leverkusen are prioritizing suppliers with documented SVHC-free material declarations.
Equipment-as-a-service contracting is displacing capital purchase models among mid-tier pharmaceutical manufacturers. Monthly per-liter processing fees bundle maintenance, calibration, and regulatory documentation, transferring obsolescence risk to OEMs. This arrangement concentrates among Nordic CDMOs seeking operational expenditure alignment with milestone-based client payments.
Mixing Vessels Market Segmentation
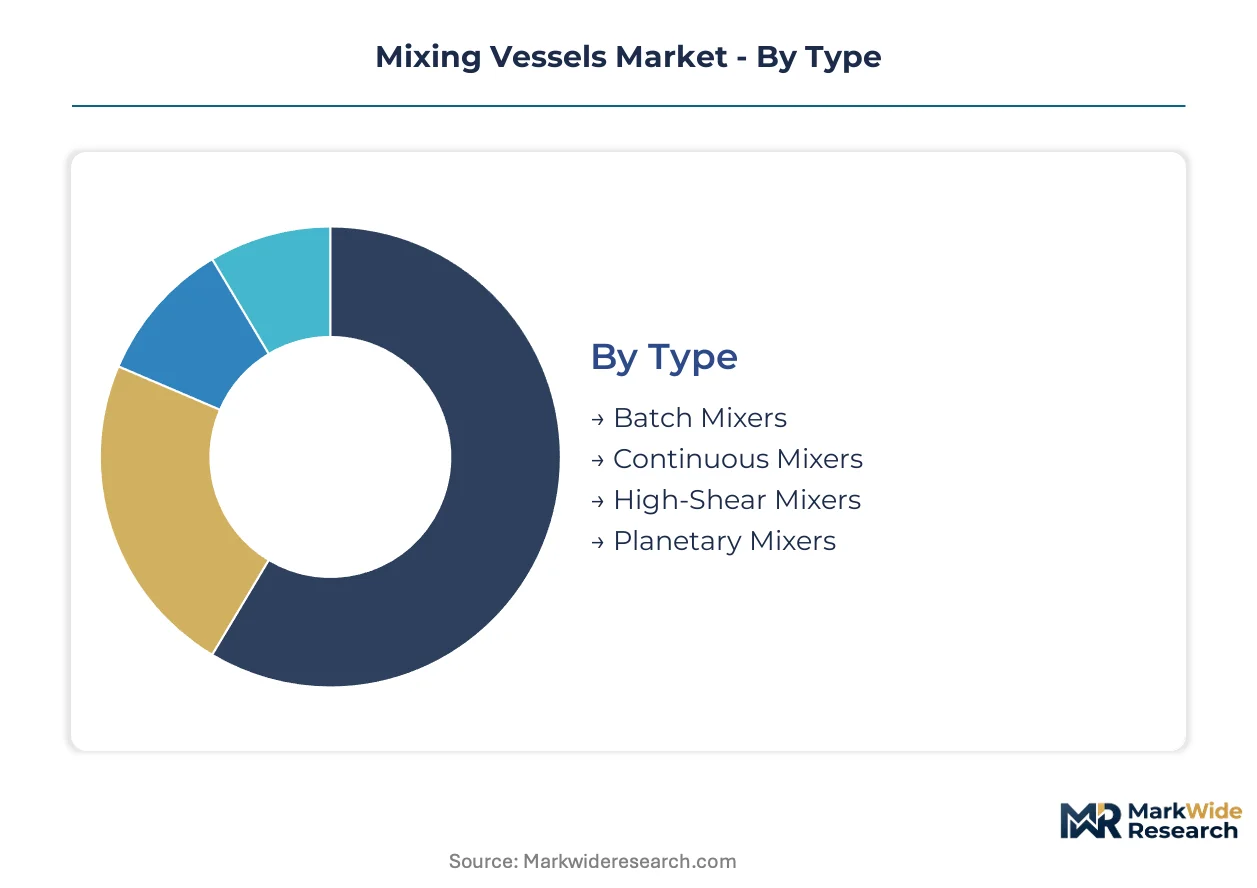
Mixing vessel procurement patterns diverge sharply across operating modes, material specifications, and regulatory exposure. Fabricators must align welding protocols, surface finishes, and agitator engineering with segment-specific validation requirements to capture margin pools.
Type:
Continuous mixers face the most acute substitution pressure from plug-flow reactor alternatives in bulk chemical processing, while batch systems defend installed base through regulatory lock-in.
- Batch Mixers:Enclosed vessels with discrete charge-discharge cycles dominate pharmaceutical and specialty chemical installations. FDA cGMP validation requirements and documented cleaning protocols sustain replacement demand across New Jersey and North Carolina biomanufacturing corridors.
- Continuous Mixers:Inline rotor-stator and static mixer configurations reduce utility costs per ton in high-volume polymer and petrochemical lines. German chemical clusters around Ludwigshafen are retrofitting continuous trains to align with EU ETS carbon accounting frameworks.
- High-Shear Mixers:Rotor-stator systems achieving tip speeds above 25 m/s concentrate in cosmetics and API manufacturing where particle-size distribution determines regulatory submission success.
- Planetary Mixers:Dual-axial agitation serves high-viscosity adhesives and sealants in automotive supply chains.
Batch mixers anchor the volume base while continuous systems gain share at the steepest rate.
Material:
Cost tier stratification separates alloy-grade fabricators from commodity metal suppliers, with electropolishing capability determining access to pharmaceutical premium pools.
- Stainless Steel:ASME-BPE compliant 316L and 904L grades with Ra sub-0.8 micrometer finishes command specification pull in aseptic drug manufacturing. Electropolishing capacity constraints in Upper Silesian and Ruhr basins create supply bottlenecks for sub-0.4 micrometer pharmaceutical-grade work.
- Carbon Steel:Unlined or rubber-lined vessels retain cost advantage in corrosive chemical bulk processing where cleanability requirements moderate. Gulf Coast petrochemical expansions sustain procurement of heavy-wall carbon steel reactors.
- Glass:Borosilicate-lined systems serve laboratory-scale and pilot-plant applications requiring visual batch monitoring.
- Plastic:Gamma-irradiated polypropylene and fluoropolymer vessels penetrate vaccine adjuvant and cell-therapy applications where single-use flexibility outweighs thermal durability.
Stainless steel dominates value capture while plastic alternatives expand most quickly in bioprocessing niches.
End User:
Regulatory stringency varies dramatically across customer types, with pharmaceutical qualification timelines stretching revenue recognition for custom fabricators.
- Pharmaceutical:Vessel systems in drug-contact service require material certificates, weld logs, and surface-roughness validation per FDA cGMP and EU GMP Annex 15. CDMOs are commissioning stainless-steel trains for monoclonal antibody production with automated clean-in-place systems.
- Chemical Processing:Specialty chemical manufacturers in Leverkusen and Ludwigshafen prioritize agitator-engineering depth with computational fluid dynamics scale-up validation.
- Food & Beverage:Hygienic design standards from EFSA and national food safety authorities drive clean-in-place compatibility in dairy and beverage corridors.
- Cosmetics:High-shear emulsification requirements for particle-size control below 10 microns concentrate procurement among specialized agitator suppliers.
Pharmaceutical end users anchor premium pricing while chemical processing sustains volume throughput.
Application:
Functional differentiation determines agitator specification, with multiphase turbulence modeling separating engineering-led suppliers from fabrication-only competitors.
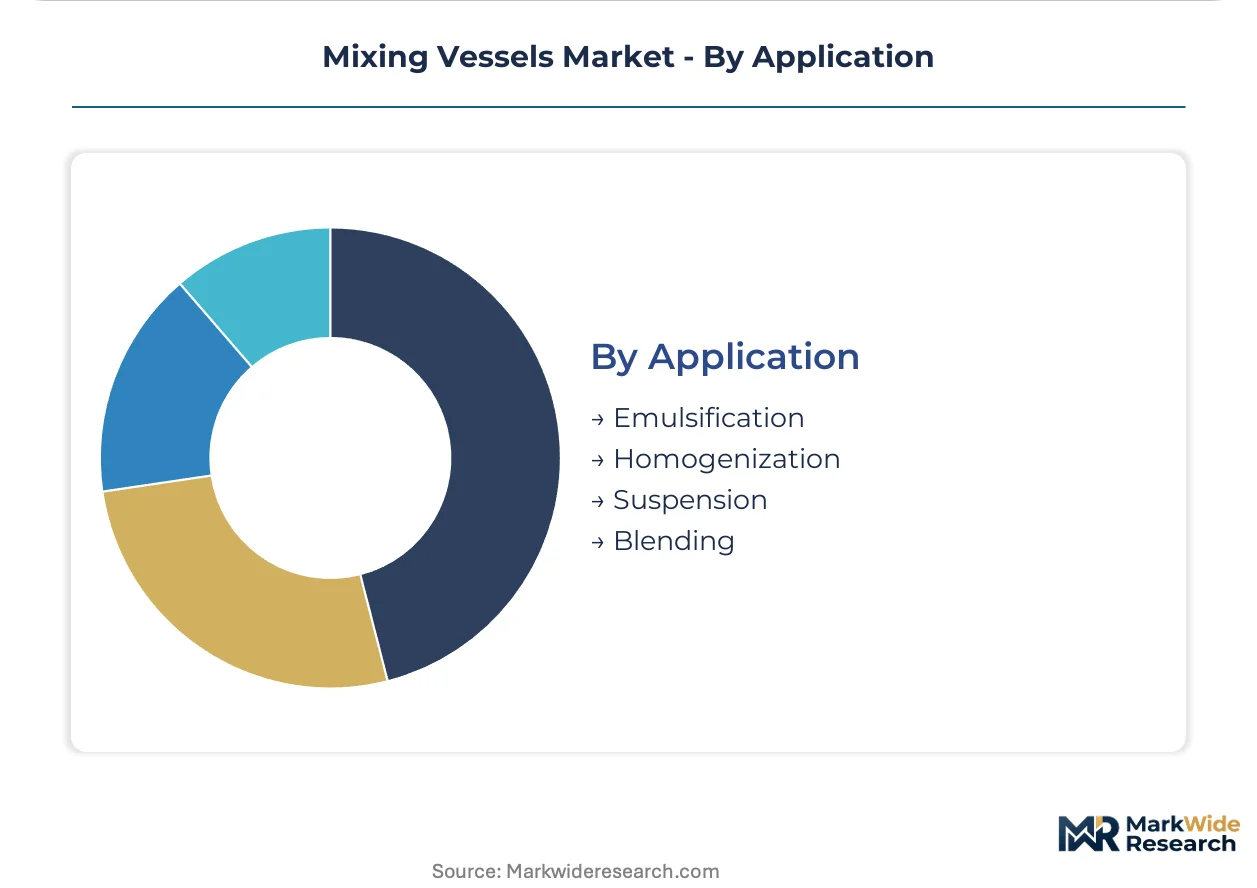
- Emulsification:Oil-in-water and water-in-oil dispersion requires controlled shear distribution to achieve droplet-size targets. Cosmetics formulators in France and Switzerland specify rotor-stator configurations with computational fluid dynamics validation.
- Homogenization:Pressure-driven or high-shear approaches reduce particle-size variance in dairy and pharmaceutical suspensions. Nordic dairy processors specify Alfa Laval installations with aseptic design leadership.
- Suspension:Solid-liquid systems with settling risk demand bottom-entry agitators or draft-tube configurations in mining and pigment applications.
- Blending:Low-shear liquid-liquid or solid-solid mixing serves intermediate compounding in chemical and food processing.
Emulsification commands the steepest engineering premiums while blending represents the most commoditized functional category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit the lowest price elasticity, prioritizing ASME-BPE certification and weld documentation over unit cost, while Indian and Chinese procurement teams negotiate aggressively on stainless steel tonnage pricing.
United States
Contract development and manufacturing organizations in New Jersey and North Carolina are commissioning stainless-steel trains for monoclonal antibody production. The FDA's process analytical technology guidelines mandate real-time release testing capabilities, forcing vessel upgrades with embedded spectroscopy ports. Boston-area biotech clusters concentrate demand for automated clean-in-place systems.
Germany
Specialty chemical manufacturers around Ludwigshafen and Leverkusen sustain above-average procurement of high-shear and planetary mixing systems. The EU MDR framework tightens material traceability standards for medical-device precursor manufacturing. Ruhr industrial basins face ASME Section IX-certified orbital welder scarcity, creating bottlenecks for pharmaceutical-grade surface-finish work.
China
Domestic fermentation capacity expansion under production-linked incentives generates qualified demand for hygienic-design mixing systems. The NMPA alignment with ICH Q7 guidelines reshapes export certification requirements for Western fabricators. Yangtze River Delta pharmaceutical clusters drive specification pull for vessels with Chinese-language HMI interfaces.
India
The PLI scheme for active pharmaceutical ingredients is accelerating domestic fermentation capacity buildout. CDSCO qualification requirements for drug-contact equipment mirror FDA cGMP standards, extending validation timelines. Maharashtra and Gujarat pharmaceutical corridors concentrate procurement of modular plastic-vessel systems for vaccine adjuvant applications.
Switzerland
Swissmedic oversight of medical-device manufacturing extends traceability demands to precursor chemical processing equipment. Basel-area pharmaceutical clusters prioritize suppliers with documented SVHC-free material declarations under REACH frameworks. Swiss academic pipelines supply computational fluid dynamics talent for specialty chemical scale-up validation.
Mixing Vessels Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the mixing vessels market. Precision stainless-steel fabricators with captive electropolishing capacity capture pharmaceutical premium pools, while modular plastic-vessel assemblers compete on batch-size flexibility and campaign economics. The vendor base stratifies across three tiers: integrated precision metalworkers, hygienic-design specialists, and agitator-engineering houses. Dominant competitive moves include backward integration into precision welding and surface finishing, plus geographic expansion through equipment-as-a-service contracting models.
Among European fabricators, Alfa Laval Corporate AB and EKATO Holding GmbH occupy distinct positioning vectors. SPX FLOW Inc. exemplifies the integrated precision metalworker archetype with vertical control over welding protocols. Alfa Laval anchors hygienic-design leadership across Nordic dairy and beverage corridors. EKATO Holding sits within the agitator-engineering specialist tier, differentiating on computational fluid dynamics capabilities that reduce scale-up risk.
| Leading Market Players |
|---|
| SPX FLOW Inc. |
| Sulzer Ltd. |
| Alfa Laval Corporate AB |
| Xylem Inc. |
| GEA Group AG |
| EKATO Holding GmbH |
| Gebr. NETZSCH GmbH & Co. Holding KG |
| Charles Ross & Son Company |
| Foures |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for 316L and 904L stainless steel tonnage lock in both supply access and price visibility for fabricators serving FDA-regulated pharmaceutical clients, insulating quoted margins from London Metal Exchange volatility while committing buyers to minimum volume thresholds across multi-year campaign cycles.
Pricing Analysis
After-sales service contracts and calibration subscriptions now drive lifetime value beyond initial vessel fabrication, with three-tier pricing structure across premium, standard, and economy levels separating ASME-BPE certified electropolished systems from commodity carbon steel reactors. Price differentiation hinges on surface-finish certification grade and captive welding capability. Cost compression in mid-tier stainless fabrication is intensifying because electropolishing capacity constraints in Upper Silesian and Ruhr basins create supply bottlenecks. Contract development and manufacturing organizations exhibit the lowest price sensitivity, while bulk chemical processors in Gulf Coast corridors negotiate aggressively on steel tonnage.
Supply Chain Analysis
Germany and Switzerland anchor precision welding and surface finishing for pharmaceutical-grade vessels, while China and India feed carbon steel fabrication and modular plastic-vessel assembly. Raw material flows draw from nickel alloy suppliers in Finland and South Africa, elastomer compounders in Italy, and precision agitator foundries in Bavaria. Single-source vulnerability concentrates in ASME Section IX-certified orbital welder pools. Distribution runs through direct OEM channels for custom-fabricated trains and regional distributor networks for standardized batch systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting expands faster than hardware sales, with monthly per-liter processing fees bundling maintenance, calibration, and regulatory documentation into recurring revenue streams that transfer obsolescence risk from pharmaceutical manufacturers to OEMs.
For Market Incumbents: Secure captive electropolishing capacity and ASME Section IX-certified welder pipelines to defend pharmaceutical premium pools against modular plastic-vessel assemblers. Backward integration into precision welding protocols and surface finishing insulates margin compression from nickel alloy price volatility. Channel control through equipment-as-a-service contracts locks out emerging competitors in Nordic CDMO corridors. For New Entrants and Emerging Players: Anchor in India's PLI-driven fermentation capacity buildout, where domestic procurement teams prioritize Indian-language HMI interfaces over established Western brands. Vaccine adjuvant and cell-therapy applications present the most penetrable white space, with gamma-irradiated polypropylene vessels displacing stainless steel in campaign-based production. Partner with regional system integrators to bypass legacy DCS integration friction. For Investors and Strategic Acquirers: Capital is best deployed toward agitator-engineering specialists with documented computational fluid dynamics capabilities and SVHC-free material declarations under REACH frameworks. Long-term viability over the next decade rests on regulatory convergence between FDA process analytical technology and EU GMP Annex 15 qualification standards. Watch for inflection signals in simultaneous dual-certification timeline compression for custom-fabricated trains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Welding | Captive ASME Section IX certification insulates margin pools from specialized welder scarcity in Ruhr basins. |
| Equipment-as-a-Service Contracting | Monthly per-liter fees align OEM revenue with CDMO milestone payments across Nordic pharmaceutical corridors. |
| Process Analytical Technology Integration | Embedded Raman spectroscopy ports satisfy FDA real-time release testing mandates for Boston-area biotech clusters. |
| Modular Plastic-Vessel Expansion | Gamma-irradiated polypropylene systems penetrate vaccine adjuvant applications where batch-size flexibility outweighs thermal durability. |
| Computational Fluid Dynamics Talent Acquisition | Swiss and German academic pipelines supply simulation engineers capable of multiphase turbulence modeling for specialty chemical scale-up validation. |
Research Methodology
Cross-validation between primary interviews with vessel fabrication executives, pharmaceutical plant engineers, and aftermarket service heads and secondary sources including FDA 483 observation databases, EMA GMP inspection records, and SEC 10-K filings anchors the qualitative findings. Bottom-up triangulation aggregates procurement patterns across New Jersey, North Carolina, Ludwigshafen, and Leverkusen industrial clusters. Top-down validation cross-checks installed base estimates against ASME-BPE certification registries and regional welding guild membership rolls.
Sensitivity analysis across operating mode, material grade, and end-user regulatory exposure informs the analytical framework over the projection horizon. Segmentation dimensions modeled include vessel type, surface-finish certification tier, agitator engineering depth, and geographic regulatory cluster. CAGRs were derived from time-series extrapolation of replacement cycle frequencies and capacity expansion announcements. Industry-specific forecast inputs incorporate nickel alloy price trajectory assumptions and ASME Section IX welder pipeline graduation rates.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA-EU regulatory convergence and stable specialty chemical capital expenditure patterns; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in pharmaceutical manufacturing platform transitions and regional production-linked incentive scheme maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Vacuum Frying Machine Market
Food Processing Equipment
Reflow Oven Market