
 EPO Biomarkers Market | 2026-2036
EPO Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
EPO Biomarkers Market Foresight
Multiplex immunoassay integration is reshaping how erythropoietin detection platforms are architected, compressing turnaround times while expanding analyte panels. Siemens Healthineers leverages its embedded analyzer installed base to lock in reagent pull-through across European hospital networks. Amgen Inc. anchors its biomarker strategy through vertical control over recombinant EPO reference standards used in assay calibration. Bio-Rad Laboratories, Inc. competes on open-system flexibility, targeting mid-tier diagnostics labs seeking modular instrument configurations.
Erythropoietin biomarkers are glycoprotein hormone indicators quantified through immunochemical or mass spectrometric methods to assess erythropoietic activity, with typical assay sensitivity thresholds reaching picogram-per-milliliter detection ranges to enable early-stage anemia and renal dysfunction screening. Their primary commercial purpose centers on supporting therapeutic decision-making in nephrology, oncology, and sports medicine contexts where endogenous EPO levels distinguish pathological from pharmacological states. Test kits and reagents together capture the dominant margin pool, driven by recurring consumable demand tied to installed analyzer bases, while mass spectrometry segments are expanding fastest as clinical labs pursue definitive quantification free from antibody cross-reactivity. Hospitals remain the anchor end-user channel, though diagnostics labs are gaining share through centralized regional testing contracts that consolidate specimen volume.
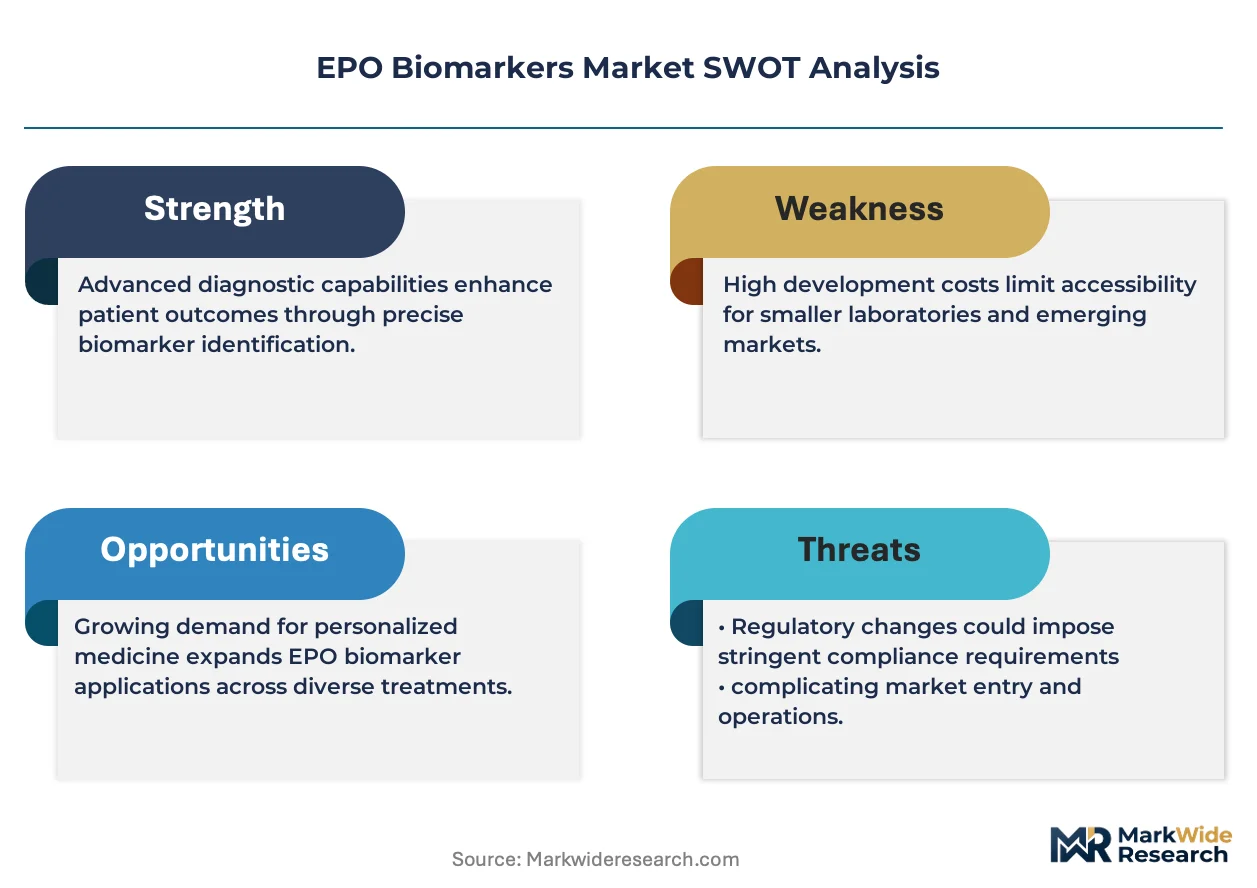
FDA 510(k) clearance pathways and CLIA proficiency standards govern commercial assay deployment in the United States, with the agency's biomarker qualification program increasingly conditioning market access on analytical validity demonstrations. EMA's IVD Regulation in Europe is raising conformity assessment barriers for EPO assay manufacturers, particularly around clinical evidence requirements for self-declared devices. Stakeholders must monitor how FDA-EMA convergence on biomarker-based companion diagnostic frameworks reshapes assay development priorities and partnership structures between platform vendors and pharmaceutical developers.
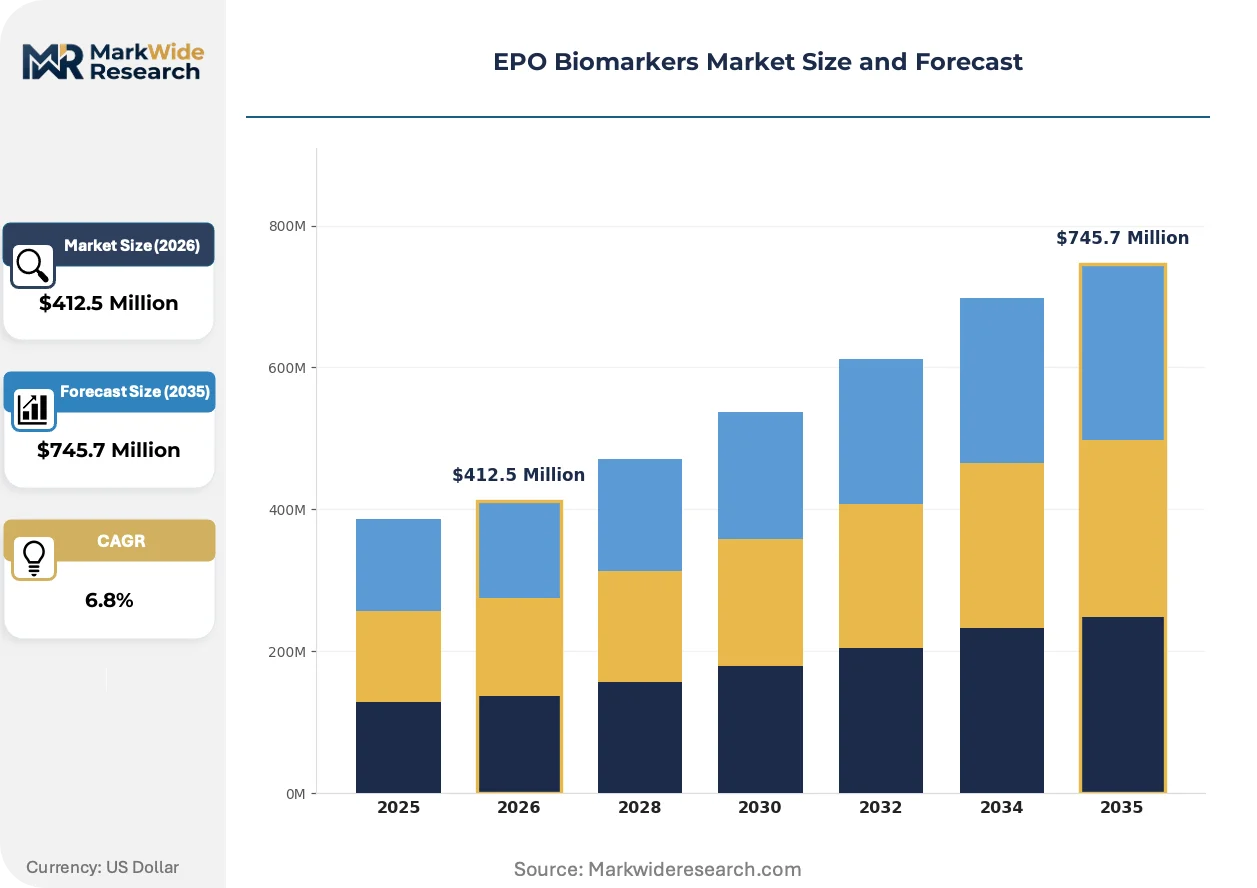
Market Dynamics
Multiplex immunoassay integration is compressing turnaround times while expanding analyte panels, forcing platform vendors to recalibrate R&D roadmaps around throughput density rather than single-analyte sensitivity alone. This technological inflection is redistributing margin capture from standalone EPO assays toward integrated anemia panels.
Growth Catalysts
- FDA Biomarker Qualification Program:The agency's evolving guidance on biomarker-based diagnostics is tightening quality benchmarks, accelerating consolidation around analytically validated platforms in United States hospital networks.
- Chronic Kidney Disease Monitoring:Rising patient volumes across integrated health systems are embedding erythropoietin testing into standardized anemia care protocols, creating recurring reagent demand.
- Mass Spectrometry Adoption:Clinical laboratories are pursuing definitive quantification free from antibody cross-reactivity, expanding the addressable base for high-sensitivity detection methods.
Market Restraints
- Reagent Cost Volatility:Specialized antibodies and recombinant protein standards face input cost pressure from limited qualified suppliers, compressing assay kit margins.
- European Conformity Barriers:EMA's IVD Regulation is raising clinical evidence requirements for self-declared devices, extending time-to-market for mid-tier manufacturers.
- Antibody Cross-Reactivity Limitations:Immunochemical methods struggle to distinguish endogenous from recombinant EPO in doping control applications, restricting sports medicine segment expansion.
Strategic Opportunities
- Centralized Regional Testing Contracts:Diagnostics labs in Germany and France are consolidating specimen volume through hub-and-spoke networks, displacing hospital-based testing.
- Companion Diagnostic Frameworks:FDA-EMA convergence on biomarker-based companion diagnostics is reshaping partnership structures between platform vendors and pharmaceutical developers.
- Point-of-Care Integration:Miniaturized electrochemical sensors are enabling near-patient testing in nephrology clinics, opening ambulatory channels previously served by central labs.
Industry Challenges
- CLIA Proficiency Compliance:United States clinical laboratories face escalating documentation burdens for assay validation under CLIA standards, extending implementation timelines.
- Legacy Analyzer Integration:Open-system flexibility demands from mid-tier diagnostics labs are forcing vendors to maintain backward compatibility with decade-old instrument footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPO Biomarkers Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Reagents, Analyzers, Consumables End User: Hospitals, Diagnostics Labs, Research Institutions, Clinics Technology: ELISA, Mass Spectrometry, Immunohistochemistry, PCR Application: Chronic Kidney Disease, Anemia Diagnosis, Sports Medicine, Cancer Research |
| Companies Covered | Siemens Healthineers, Pfizer Inc., Amgen Inc., Bio-Rad Laboratories, Inc., Novartis, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Merck KGaA, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPO Biomarkers Market Shifts & Advancements
Platform architecture is pivoting from discrete analyzers toward modular, multi-analyte systems that embed EPO detection within broader hematological workups. This reconfiguration is altering competitive positioning around software integration and reagent pull-through economics.
High-resolution mass spectrometry platforms are rendering obsolete traditional ELISA workflows in reference laboratories seeking definitive quantification. Large academic medical centers in the United States are adopting these systems at accelerating cadence. The shift is compressing addressable market share for antibody-dependent methods in high-complexity settings.
EMA's IVD Regulation is mandating expanded clinical evidence packages for commercially distributed assays. Manufacturers must now generate performance data across broader patient cohorts prior to CE marking. European hospital procurement committees are responding by consolidating vendor lists around established platform holders with regulatory infrastructure.
Centralized regional testing contracts are displacing hospital-based EPO testing in France and Germany. Diagnostics lab chains are capturing specimen volume through hub-and-spoke logistics networks that promise cost compression. This channel migration is most visible in nephrology networks where integrated health systems seek operational leverage through outsourcing.
EPO Biomarkers Market Segmentation
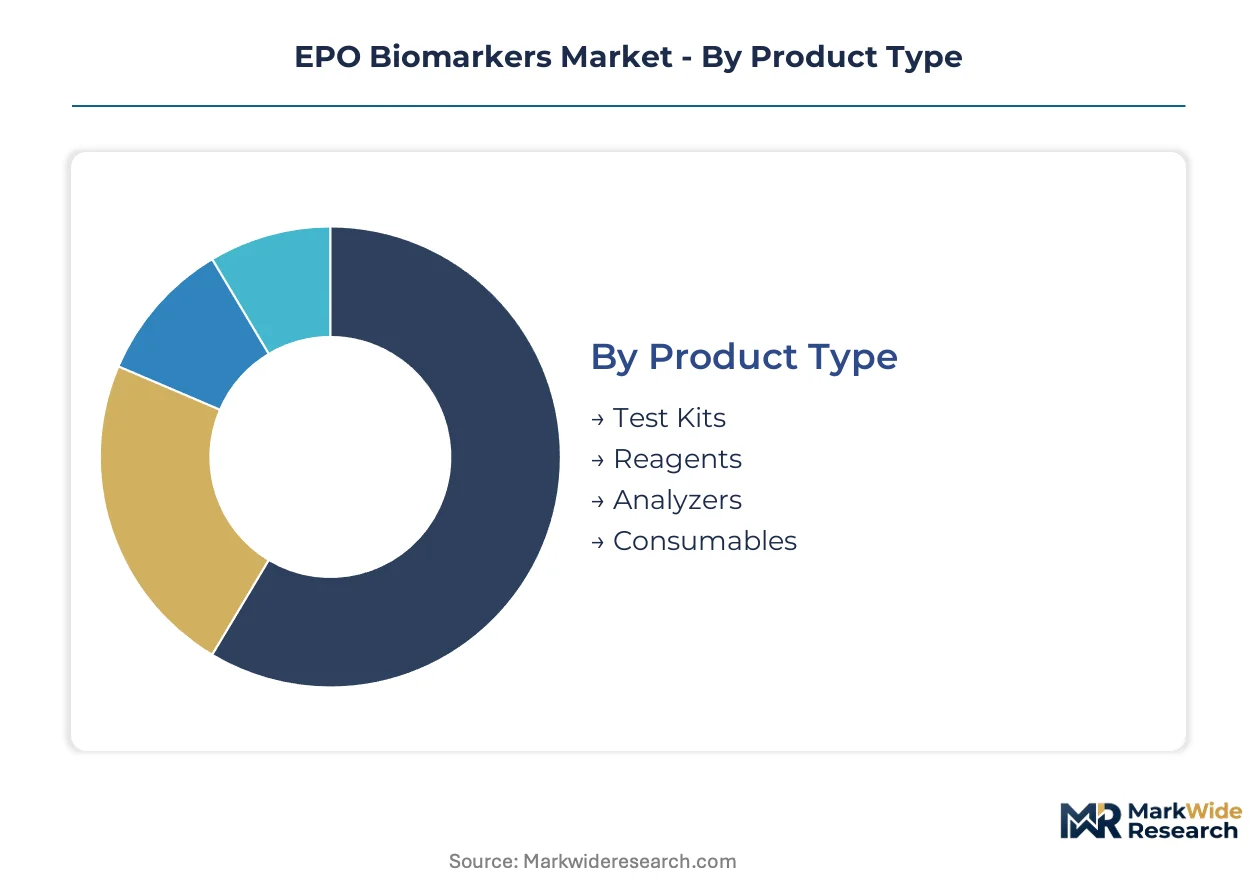
EPO biomarker segmentation reveals distinct margin architectures across product layers, with recurring consumables generating disproportionate lifetime value versus capital equipment. Technology and end-user fragmentation creates multiple entry points for specialized vendors versus integrated platform holders.
Product Type:
After-sales service intensity varies sharply across this category, with reagent-dependent systems demanding continuous technical support and calibration maintenance while standalone test kits require minimal ongoing vendor engagement.
- Test Kits:Pre-configured immunoassay panels packaged for single-use or limited-run EPO quantification, typically employing ELISA or chemiluminescent detection chemistry. Demand concentrates in mid-tier diagnostics labs across the United States seeking CLIA-compliant workflows without analyzer capital expenditure, constrained by per-test cost economics at volume scale.
- Reagents:Specialized antibodies, recombinant protein standards, and detection substrates constitute the highest-margin recurring revenue stream, with Siemens Healthineers leveraging installed analyzer bases to lock in multi-year supply contracts. European hospital networks embed these consumables into centralized procurement frameworks that prioritize vendor consolidation over unit cost minimization.
- Analyzers:Automated immunoassay and mass spectrometry platforms represent capital-intensive front-end equipment with extended sales cycles and substantial field service infrastructure requirements.
- Consumables:Disposable reaction vessels, pipette tips, and sample preparation cartridges capture steady replacement demand tied to test throughput rather than analytical performance differentiation.
Reagents hold the largest share; momentum sits with mass spectrometry-compatible consumables as clinical labs migrate toward definitive quantification methods.
End User:
Procurement authority and volume concentration diverge meaningfully across this category, with integrated health systems consolidating purchasing power while independent diagnostics labs compete on turnaround speed and specialized assay menus.
- Hospitals:Anchor channel for EPO biomarker deployment, embedding erythropoietin testing within standardized anemia care protocols in nephrology and oncology departments. United States integrated health systems concentrate demand through system-wide laboratory contracts that privilege vendors with multi-site service capabilities.
- Diagnostics Labs:Hub-and-spoke regional networks in France and Germany are consolidating specimen volume through centralized testing contracts, displacing hospital-based EPO analysis with cost-compressed outsourced alternatives.
- Research Institutions:Academic medical centers drive adoption of high-resolution mass spectrometry platforms for biomarker discovery and reference method development, though commercial volume remains limited.
- Clinics:Ambulatory nephrology and sports medicine practices represent emerging point-of-care channels where miniaturized electrochemical sensors are enabling near-patient testing outside traditional laboratory infrastructure.
Hospitals retain dominant volume; diagnostics labs are expanding most quickly through regional consolidation strategies.
Technology:
Capital intensity and regulatory validation burden separate legacy immunochemical methods from emerging mass spectrometric platforms, with CLIA and FDA 510(k) pathways imposing divergent time-to-market constraints.
- ELISA:Enzyme-linked immunosorbent assay remains the workhorse technology for routine EPO quantification, offering cost-effective batch processing with picogram-per-milliliter sensitivity thresholds sufficient for chronic kidney disease monitoring.
- Mass Spectrometry:High-resolution platforms enable definitive quantification free from antibody cross-reactivity, rendering these systems essential for sports medicine applications distinguishing endogenous from recombinant EPO; large academic medical centers in the United States are adopting these at accelerating cadence despite substantial capital and technical staffing requirements.
- Immunohistochemistry:Tissue-based EPO detection methods serve specialized research applications and localized erythropoietic activity assessment, with limited commercial clinical penetration.
- PCR:Nucleic acid amplification technologies target EPO gene expression analysis rather than protein quantification, occupying a niche role in pharmacogenomic and research contexts.
ELISA maintains installed base dominance; mass spectrometry demonstrates the steepest expansion trajectory as reference laboratories pursue analytical specificity.
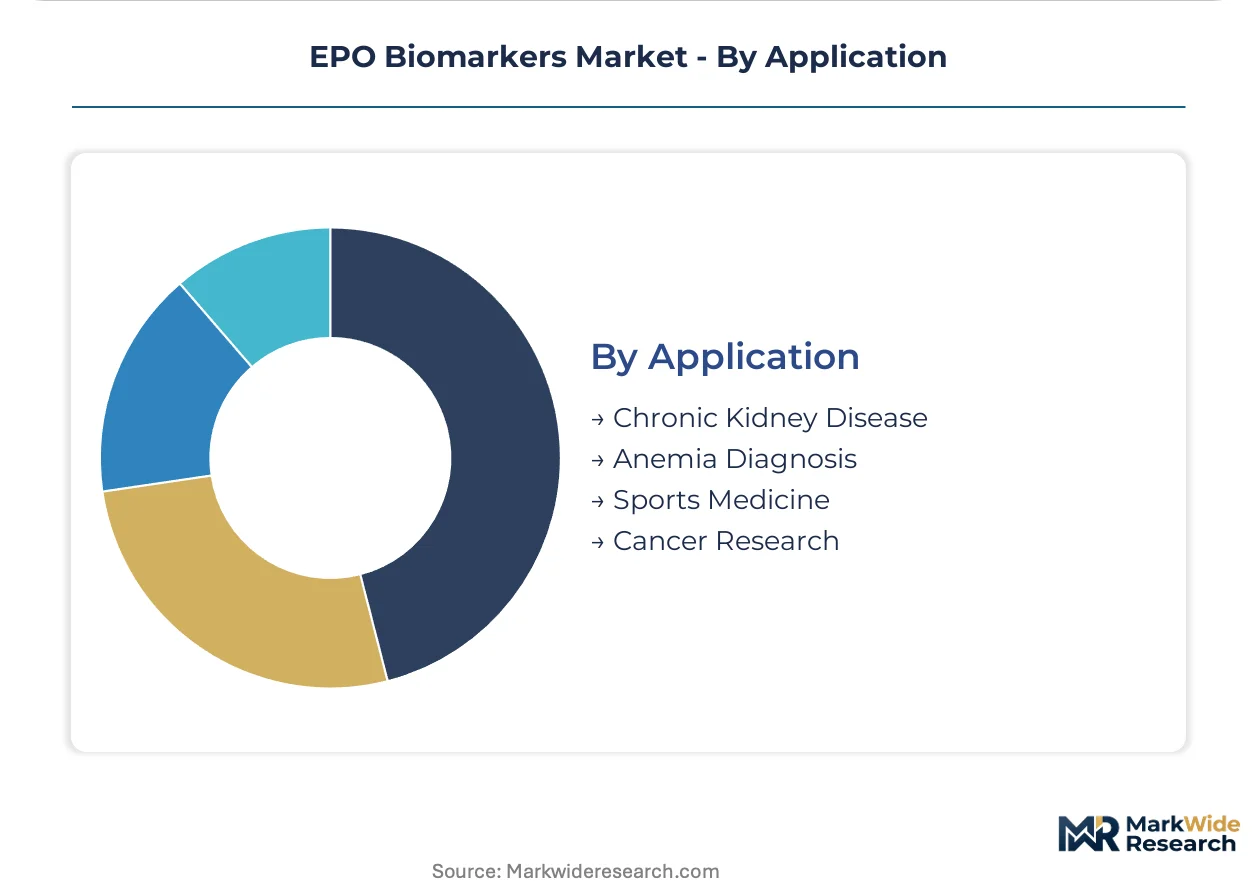
Application:
Clinical utility and reimbursement pathways vary substantially across indications, with nephrology offering established payment codes while sports medicine confronts methodological skepticism from regulatory bodies.
- Chronic Kidney Disease:Dominant commercial application driving standardized erythropoietin monitoring protocols across integrated health systems, with anemia management guidelines mandating regular EPO assessment to guide erythropoiesis-stimulating agent dosing.
- Anemia Diagnosis:Broad diagnostic category encompassing iron deficiency, bone marrow disorders, and inflammatory conditions where EPO levels distinguish appropriate from blunted erythropoietic responses; European hospital procurement committees prioritize assay accuracy in this high-decision-consequence setting.
- Sports Medicine:Anti-doping control applications face methodological constraints as immunochemical methods struggle to distinguish endogenous from recombinant EPO, restricting segment expansion despite substantial law enforcement and athletic federation budgets.
- Cancer Research:EPO biomarker deployment in oncology centers on chemotherapy-induced anemia management and investigational applications in tumor hypoxia research, with companion diagnostic frameworks emerging under FDA-EMA convergence.
Chronic kidney disease commands the largest share; cancer research is gaining share fastest through pharmaceutical partnership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports EPO biomarker reagents and analyzers to hospital networks across France and the Netherlands, anchoring European supply corridors while the United States maintains parallel import flows from Swiss and German manufacturers for high-complexity reference laboratories.
United States
FDA's biomarker qualification program and CLIA proficiency standards are tightening analytical validity requirements for commercial assay deployment. Integrated health systems in the Midwest and Southeast are consolidating laboratory contracts around vendors with multi-site service capabilities. The Mayo Clinic and Cleveland Clinic anchor reference method development for mass spectrometry-based EPO quantification.
Germany
Hub-and-spoke regional testing networks in North Rhine-Westphalia and Bavaria are displacing hospital-based EPO analysis through centralized diagnostics lab contracts. EMA's IVD Regulation is raising conformity assessment barriers for assay manufacturers seeking CE marking. Siemens Healthineers leverages its embedded analyzer installed base across German hospital networks to lock in reagent pull-through economics.
France
Diagnostics lab chains in Île-de-France and Auvergne-Rhône-Alpes are capturing specimen volume through outsourced anemia care protocols. ANSM oversight of in-vitro diagnostic devices is conditioning market access on expanded clinical evidence packages. Paris-based hospital procurement committees are consolidating vendor lists around established platform holders with regulatory infrastructure.
Switzerland
Swissmedic's stringent device conformity requirements are filtering mid-tier manufacturers from the commercial assay market. Basel and Zurich anchor pharmaceutical-biomarker partnership structures under converging FDA-EMA companion diagnostic frameworks. Roche's vertical control over recombinant EPO reference standards shapes assay calibration protocols exported to German and Austrian laboratories.
Japan
PMDA's evolving guidance on biomarker-based diagnostics is accelerating adoption of analytically validated platforms in Tokyo and Osaka metropolitan hospital networks. METI industrial policy supports domestic production of high-sensitivity detection substrates. The Kansai region's academic medical centers are piloting mass spectrometry workflows for definitive EPO quantification in sports medicine applications.
EPO Biomarkers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Siemens Healthineers and Roche leverage embedded analyzer installed bases to capture recurring reagent revenue through multi-year supply contracts. Three archetypes dominate: integrated diagnostics conglomerates with full-platform portfolios, specialized reagent manufacturers with antibody expertise, and pharmaceutical developers controlling reference standards. Competitive moves center on regulatory infrastructure investment and backward integration into recombinant protein production.
Among Germany-based diagnostics conglomerates, Siemens Healthineers exemplifies the channel-control archetype through its European hospital network penetration. Amgen Inc. and Bio-Rad Laboratories, Inc. represent contrasting specialists—one anchoring biomarker strategy through upstream control over recombinant EPO reference standards, the other competing on open-system flexibility for mid-tier diagnostics labs seeking modular instrument configurations. These three occupy positions spanning the value chain from assay calibration through platform deployment.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Pfizer Inc. |
| Amgen Inc. |
| Bio-Rad Laboratories, Inc. |
| Novartis |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Merck KGaA |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Overcapacity in European reagent manufacturing is compressing supplier margins while simultaneously enabling aggressive pricing postures for multi-year hospital supply contracts. This utilization imbalance feeds directly into how Siemens Healthineers and Roche structure their reagent pull-through economics across German and French hospital networks.
Pricing Analysis
Cost-plus contracts with antibody input indexation dominate procurement frameworks between European diagnostics conglomerates and hospital purchasing committees. Three-tier pricing structure across premium, standard, and economy levels separates mass spectrometry-grade reagents from routine ELISA consumables and private-label alternatives. Pricing pressure stems from centralized regional testing contracts in France and Germany consolidating volume around lowest-compliant bidders. Mid-tier diagnostics labs exhibit highest price sensitivity due to capital constraints and open-system flexibility demands, while academic medical centers prioritize analytical specificity over unit cost minimization.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard practice among German and Swiss reagent suppliers serving hospital networks across France and the Netherlands. Geographic supply concentration centers on Germany, Switzerland, and the United States for recombinant protein standards and high-affinity antibodies. Raw material dependencies include fetal bovine serum for cell culture, specialized chromatography resins, and isotopically labeled internal standards for mass spectrometry workflows. Single-source vulnerability around qualified antibody suppliers poses structural risk given EMA's IVD Regulation tightening clinical evidence requirements. Distribution runs through hub-and-spoke logistics networks anchored by Siemens Healthineers and Roche field service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where reagent recurring revenue expands faster than analyzer hardware sales, with multi-year calibration and technical support contracts generating disproportionate lifetime value per installed unit.
For Market Incumbents: Pre-empt mass spectrometry platform displacement by embedding EPO detection within broader anemia panel workflows before reference laboratories complete ELISA obsolescence. Deepen backward integration into recombinant protein production to secure antibody supply against single-source bottlenecks. Lock in diagnostics lab chains through centralized regional testing contracts before hub-and-spoke networks fully consolidate French and German specimen volume. For New Entrants and Emerging Players: Mid-market diagnostics labs in Spain and Italy seeking modular open-system configurations represent the most penetrable entry point given incumbent neglect of backward compatibility demands. Point-of-care electrochemical sensor deployment in ambulatory nephrology clinics offers white-space expansion outside hospital and central lab channels. Pursue regulatory qualification under FDA biomarker program or EMA IVD pathway as primary go-to-market credibility anchor. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among reagent-specialist manufacturers with captive antibody production and embedded analyzer install bases. Long-term viability across the five-to-ten year horizon favors vertically integrated platform holders with regulatory infrastructure spanning FDA and EMA jurisdictions. Watch for mass spectrometry adoption inflection signals at large academic medical centers as indicator of immunochemical method displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA's IVD Regulation mandates expanded clinical evidence packages before market access. |
| Hospital System Partnership | Integrated health systems in the United States consolidate laboratory contracts around multi-site service capabilities. |
| Reimbursement Strategy | Established nephrology payment codes drive standardized erythropoietin monitoring protocol adoption. |
| Software Companion Development | FDA-EMA convergence on companion diagnostic frameworks reshapes platform-pharmaceutical partnership structures. |
| Backward Integration into Recombinant Standards | Upstream control over reference materials secures assay calibration consistency and supplier independence. |
Research Methodology
Initial hypotheses were tested against primary input from clinical laboratory directors, hospital procurement managers, regulatory affairs specialists at diagnostics manufacturers, and biomedical engineers at academic medical centers and refined through secondary validation. Sources included FDA 510(k) clearance databases, EMA IVD Regulation conformity assessment documentation, hospital GPO contract repositories, and CLIA proficiency testing records. Bottom-up segmentation modeling triangulated against top-down market sizing from installed analyzer base estimates and reagent consumption rates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end-user channel, technology platform, and application indication. CAGRs were derived from regression analysis of historical volume trends and forward-looking capacity expansion announcements. Forecast inputs incorporated nephrology patient volume projections, EMA regulatory transition timelines, and mass spectrometry platform adoption curves at reference laboratories.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates, hospital capital expenditure cycles, or antibody input costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market