
 Fusion Protein and Biosimilars Market | 2026-2036
Fusion Protein and Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Fusion Protein and Biosimilars Market Analysis
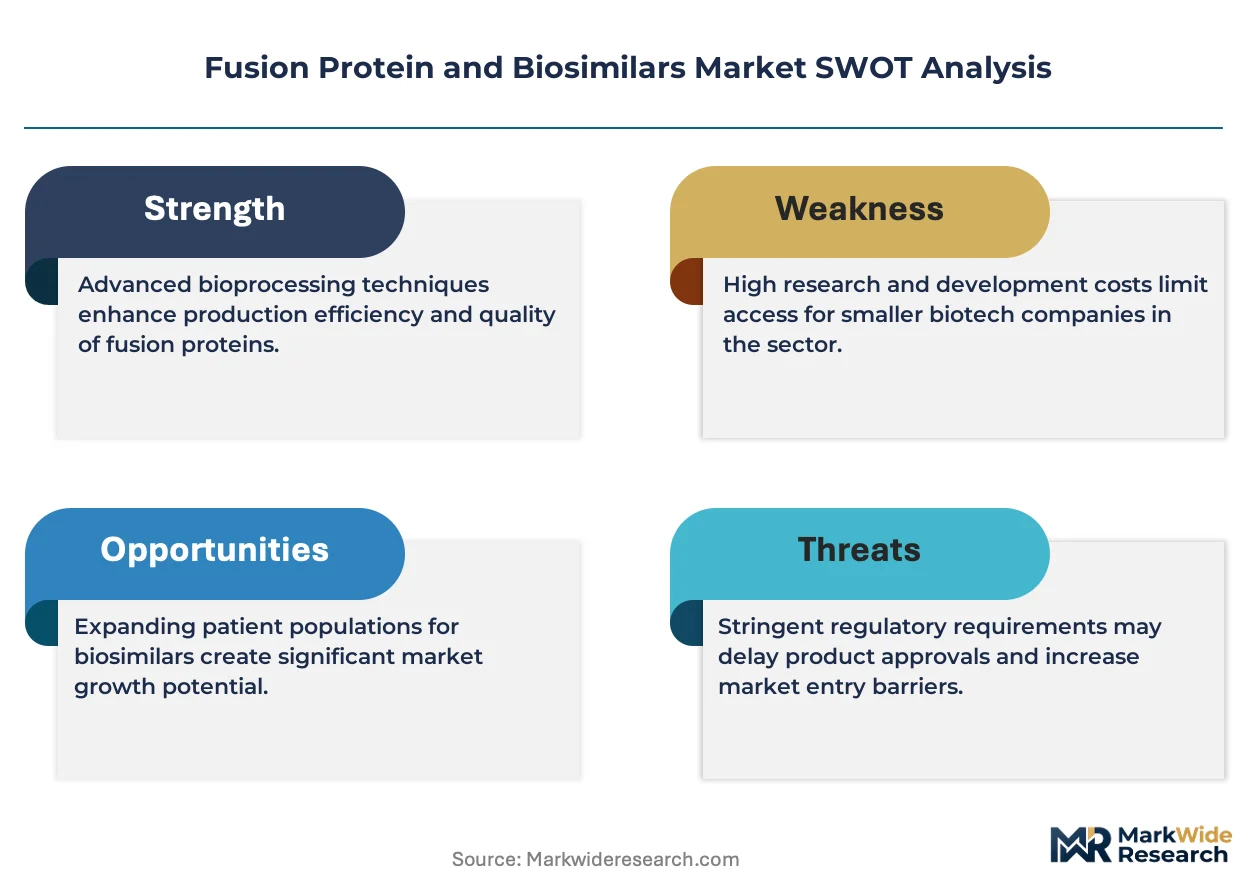
EMA biosimilar guidance is expanding the cost-of-entry calculus for developers seeking European market access. Pfizer Inc. leverages its established biologics infrastructure to sustain manufacturing scale across multiple therapy areas. Amgen Inc. anchors its competitive stance through deep specialization in autoimmune and oncology biologics. Samsung Bioepis competes aggressively on cost while maintaining compliance with stringent comparability standards.
Fusion proteins and biosimilars comprise recombinant protein therapeutics engineered by linking two or more protein domains to create multifunctional biologics, or highly similar copies of approved reference biologics manufactured through living cell cultures with demonstrated physicochemical and functional equivalence. Their primary purpose centers on delivering targeted immunomodulation, receptor blockade, or pathway inhibition for chronic and acute diseases with reduced development cost relative to novel biologics. Monoclonal antibodies occupy the largest revenue pool due to established clinical validation and broad oncology application, while fusion proteins represent the fastest-growing product category driven by next-generation cytokine traps and receptor constructs. Intravenous delivery dominates current volume but subcutaneous formulations are capturing disproportionate investment as self-administration models expand into homecare settings.
FDA biosimilar approval pathways, EMA scientific advice procedures, and WHO prequalification standards collectively shape product development timelines, interchangeability designations, and cross-border market access for manufacturers. These frameworks create divergent competitive conditions where US interchangeability rules demand switching studies while European automatic substitution policies accelerate uptake. Stakeholders must monitor evolving FDA guidance on extrapolation of indications and emerging state-level pharmacy substitution laws that will determine biosimilar penetration depth in hospital and retail channels.
Market Dynamics
Therapeutic substitution policies in Germany, Japan, and the United States are compressing decision timelines for hospital formulary committees, forcing manufacturers to demonstrate interchangeability through switching studies rather than relying on clinical equivalence alone.
Growth Catalysts
- FDA Interchangeability Pathway:The FDA's streamlined switching study requirements accelerate biosimilar uptake in retail pharmacy channels where automatic substitution is permitted.
- Cell Culture Productivity Gains:Continuous bioprocessing technologies reduce cost-per-gram of recombinant proteins by shortening manufacturing cycle times and improving yield consistency.
- Germany:The AMNOG early benefit assessment framework creates predictable pricing corridors that incentivize biosimilar entry while maintaining physician confidence.
Market Restraints
- Reference Product Patent Thickets:Process patents on cell lines and purification methods extend exclusivity periods beyond composition-of-matter expiration, delaying biosimilar launch.
- Plasma-Derived Protein Volatility:Fractionation capacity constraints and donor pool fluctuations create input cost instability for fusion protein manufacturers dependent on human serum components.
- EMA Extrapolation Limits:Restrictions on indication extrapolation without dedicated clinical trials force redundant study investments for biosimilar developers seeking broad label claims.
Strategic Opportunities
- Subcutaneous Formulation Expansion:Self-administration delivery systems open homecare channels for fusion proteins previously restricted to infusion centers, capturing patient convenience premiums.
- India:CDSCO's phased implementation of biosimilar guidelines creates first-mover advantages for manufacturers establishing local analytical testing infrastructure.
- Dual-Target Fusion Constructs:Bifunctional checkpoint inhibitors and cytokine traps address resistance mechanisms in oncology, commanding differentiated pricing against single-mechanism biologics.
Industry Challenges
- Analytical Biosimilarity Demonstration:Higher-order protein structure characterization requires mass spectrometry and nuclear magnetic resonance capabilities scarce among contract testing organizations.
- Cold Chain Integrity:Temperature excursion risks during international distribution of temperature-sensitive biologics necessitate redundant logistics infrastructure and real-time monitoring investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fusion Protein and Biosimilars Market |
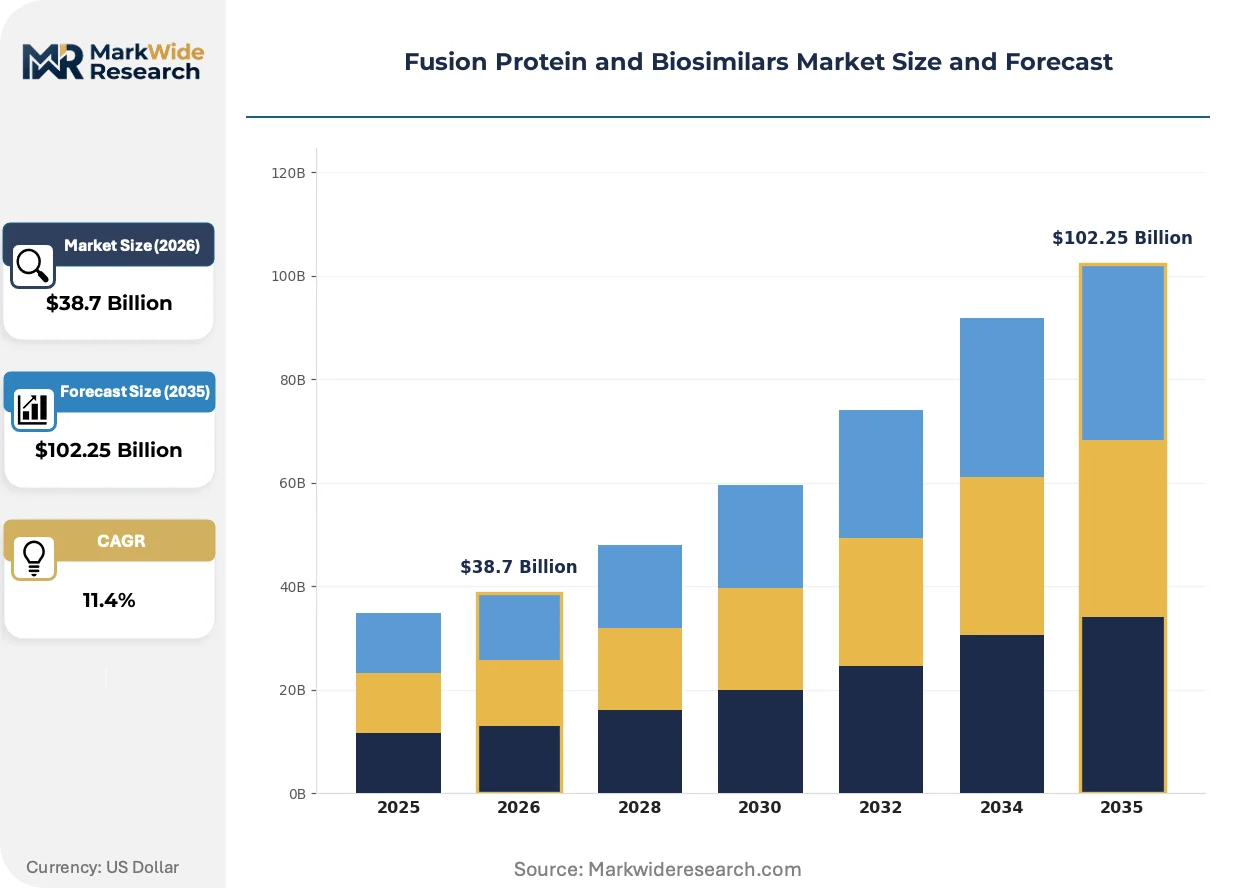
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Fusion Proteins, Biosimilar Injectables, Protein Therapeutics Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Neurology Delivery Mode: Subcutaneous, Intravenous, Oral, Intramuscular End User: Hospitals, Clinics, Research Institutions, Homecare |
| Companies Covered | Pfizer Inc., Amgen Inc., F. Hoffmann-La Roche Ltd., Sandoz International GmbH, AbbVie Inc., Samsung Bioepis, Teva Pharmaceutical Industries Ltd., Novartis AG, Regeneron Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fusion Protein and Biosimilars Market Emerging Trajectories
Manufacturing intelligence platforms and novel molecular formats are compressing development timelines while regulatory convergence around analytical comparability is reshaping competitive entry strategies across major markets.
Continuous bioprocessing is automating upstream cell culture operations through perfusion systems that maintain cells in steady-state production for weeks rather than batch-fed cycles of days. Contract development organizations in Switzerland and Singapore are adopting these platforms to reduce facility footprint and improve lot-to-lot consistency. This automation is compressing capital requirements for biosimilar entrants while raising the technical bar for quality control documentation.
The EMA's revised biosimilar guidance on immunogenicity assessment now mandates extended follow-up periods for novel fusion protein formats, extending development timelines by eight to fourteen months. Manufacturers must now submit anti-drug antibody data from at least twelve-month treatment exposure rather than the previous six-month standard. Oncology biosimilars targeting TNF-alpha pathways face the steepest compliance burden under these requirements.
Hospital procurement consortia in the United States are consolidating purchasing decisions through group purchasing organizations that negotiate exclusive biosimilar contracts across multiple therapeutic classes. These entities now mandate interchangeability designation as a threshold qualification, displacing physician-led formulary discretion. The Veterans Health Administration and several state Medicaid programs have adopted this consolidated sourcing model most aggressively.
Fusion Protein and Biosimilars Market Segmentation
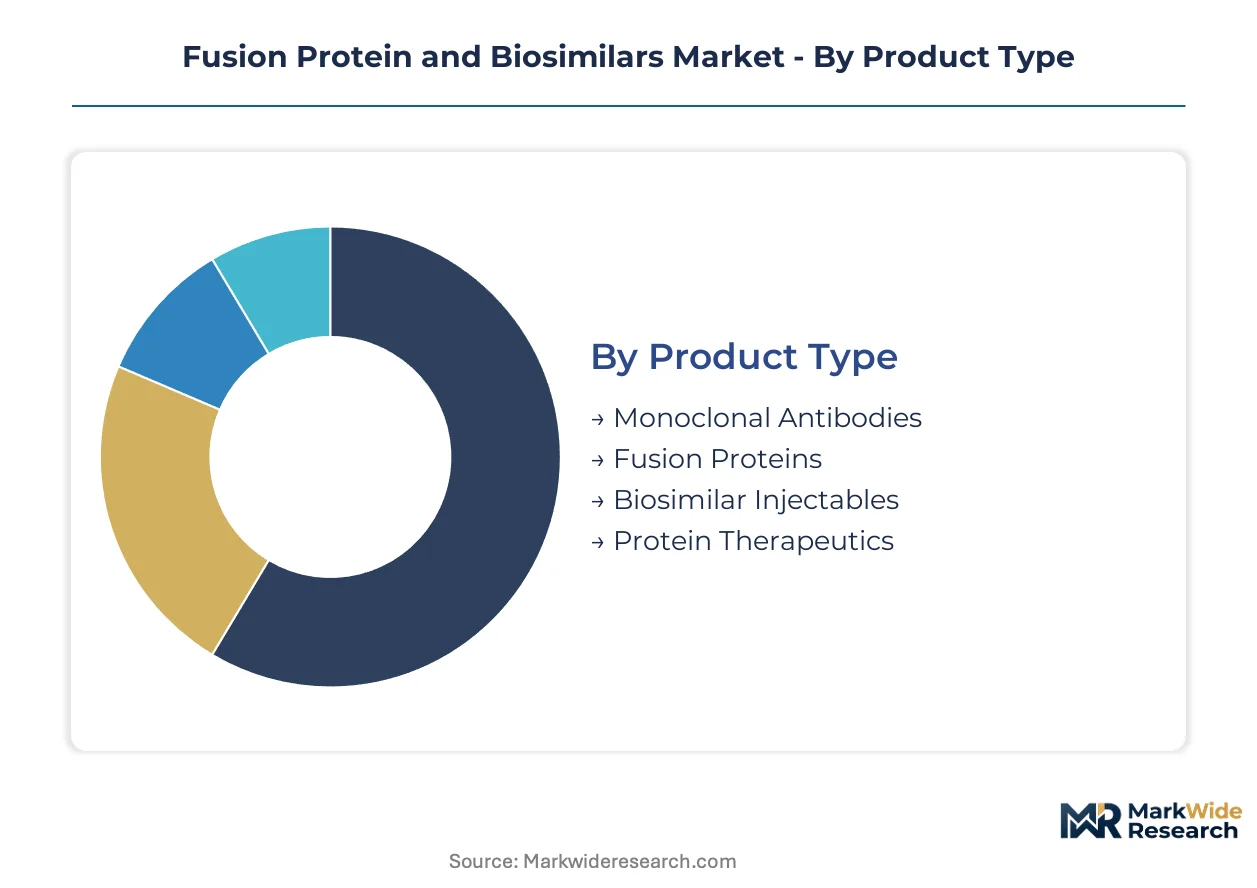
Fusion protein and biosimilar markets fragment across molecular format, clinical application, and care setting. Each dimension carries distinct regulatory, reimbursement, and manufacturing economics that shape competitive entry strategies.
Product Type:
Volume concentration favors established antibody platforms while premium pricing attaches to novel fusion constructs requiring specialized cell line development.
- Monoclonal Antibodies:These Y-shaped immunoglobulins bind single epitopes with high specificity, manufactured through Chinese hamster ovary cell cultures at industrial scale. Demand concentrates in United States hospital infusion centers where oncology protocols standardize on reference products. The FDA's interchangeability pathway creates substitution pressure that compresses margins for biosimilar entrants.
- Fusion Proteins:Engineered constructs link cytokine receptors, ligand traps, or antibody fragments to create bifunctional therapeutics. Germany's AMNOG framework rewards these with premium pricing when demonstrating outcome advantages over monoclonal alternatives. Cell line development timelines extend manufacturing investment recovery periods.
- Biosimilar Injectables:Highly similar copies of reference biologics demonstrate physicochemical equivalence through analytical comparability. CDSCO's phased guidelines in India attract manufacturers seeking emerging market volume.
- Protein Therapeutics:Encompasses recombinant enzymes, growth factors, and blood factors produced through microbial or mammalian expression systems. Japan's PMDA maintains stringent immunogenicity surveillance that elevates post-market commitment costs.
Mature deployment sits with monoclonal antibodies. Newer deployment is concentrated in fusion proteins.
Therapy Area:
Application concentration determines clinical trial investment scale and payer negotiation leverage across reimbursement systems.
- Oncology:Checkpoint inhibitors and cytokine traps target tumor microenvironment modulation. United States Medicare's episode-based payment bundles create price transparency pressure that favors biosimilar substitution in supportive care indications.
- Autoimmune Disorders:TNF-alpha pathway blockers dominate rheumatoid arthritis and psoriasis treatment. Germany's statutory health insurance funds mandate therapeutic substitution once interchangeability is established, accelerating volume shifts.
- Infectious Diseases:Neutralizing antibody cocktails and interferon fusions address viral and bacterial threats. Development timelines compress during public health emergencies through emergency use authorization pathways.
- Neurology:Blood-brain barrier penetration challenges limit fusion protein applicability in Alzheimer's and multiple sclerosis. Subcutaneous delivery formats are gaining share fastest in patient populations seeking reduced clinic visit burden.
Established revenue pools anchor oncology. Autoimmune disorders are climbing the fastest as interchangeability designations proliferate.
Delivery Mode:
Route of administration determines cold chain complexity, patient compliance economics, and site-of-care revenue allocation.
- Subcutaneous:Prefilled syringes and autoinjector devices enable self-administration outside clinical settings. Japan's aging population drives homecare channel expansion for rheumatoid arthritis patients.
- Intravenous:Infusion center administration dominates oncology and immunology biologics requiring precise dosing control. United States hospital outpatient departments capture administration fees that resist site-of-care migration.
- Oral:Limited applicability due to gastrointestinal degradation of protein structures. Research institutions in Switzerland pursue mucosal delivery technologies.
- Intramuscular:Depot formulations extend dosing intervals for chronic disease management. Manufacturing complexity elevates cost-per-dose relative to subcutaneous alternatives.
Infusion infrastructure anchors intravenous deployment. Subcutaneous formats represent the steepest expansion trajectory as patient convenience premiums justify formulation investment.
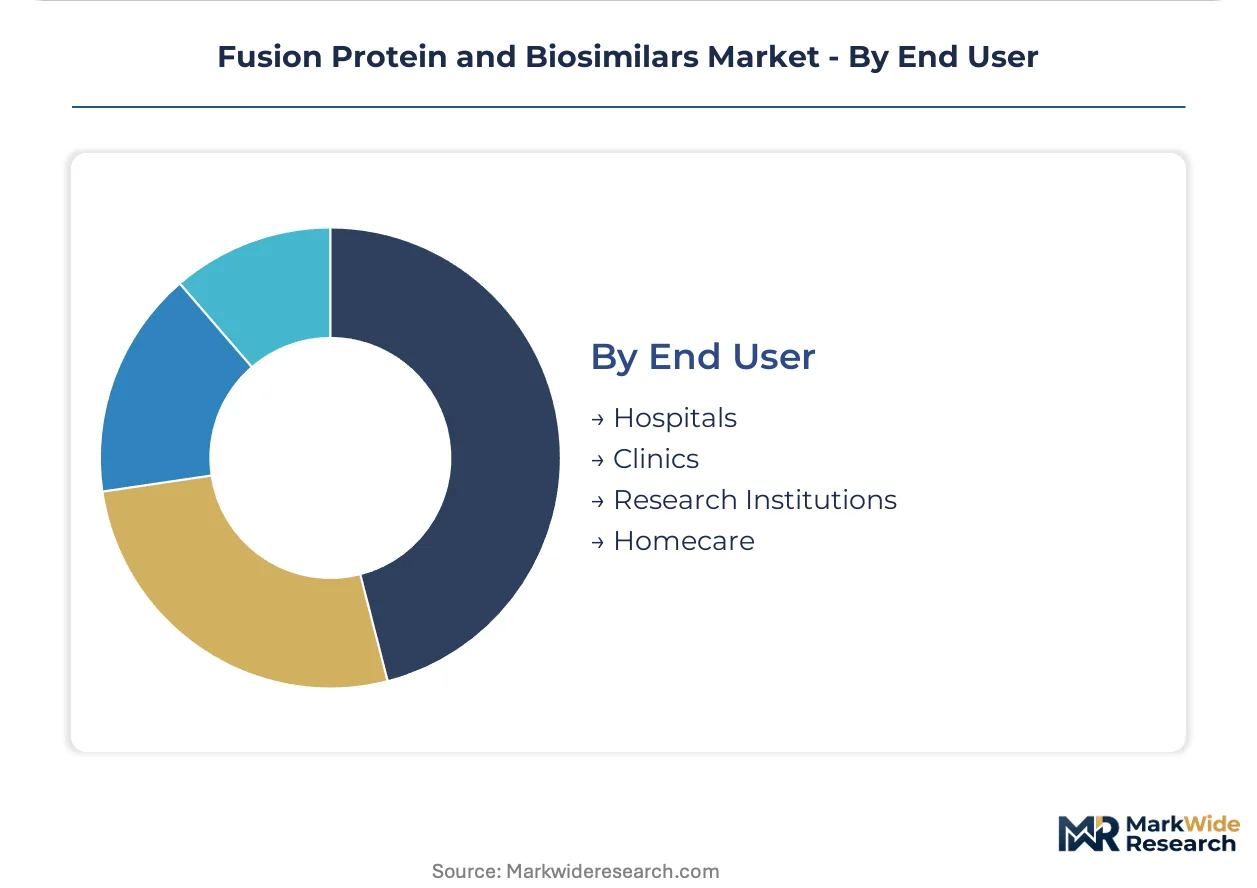
End User:
Procurement authority concentration varies across institutional settings, shaping contract negotiation dynamics and brand loyalty patterns.
- Hospitals:Group purchasing organizations consolidate biosimilar sourcing decisions across therapeutic classes in the United States. Formulary committees now mandate interchangeability designation as threshold qualification.
- Clinics:Physician-owned infusion centers balance patient preference with payer substitution requirements. Germany's regional physician associations coordinate therapeutic switching protocols.
- Research Institutions:Academic medical centers conduct head-to-head switching studies that inform regulatory interchangeability determinations. EMA scientific advice procedures guide trial design investments.
- Homecare:Specialty pharmacy distributors manage temperature-controlled logistics for self-administered biologics. Japan's home medical care expansion policy reimburses nursing support for injection training.
Institutional procurement dominates hospital channels. Homecare deployment is expanding most quickly as subcutaneous formulations penetrate chronic disease management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors North American concentration through Massachusetts Life Sciences Center tax incentives. Swiss and German precision clusters command European premium positioning. Korean and Indian manufacturing zones capture cost-sensitive volume expansion.
United States
Hospital group purchasing organizations concentrate demand through exclusive biosimilar contracts across therapeutic classes. The FDA's interchangeability pathway and state-level pharmacy substitution laws accelerate therapeutic switching in retail channels. Massachusetts and California biotech clusters host analytical testing infrastructure for higher-order protein characterization.
Germany
Statutory health insurance funds mandate therapeutic substitution once EMA interchangeability is established, compressing formulary decision timelines. The AMNOG early benefit assessment framework creates predictable pricing corridors that reward outcome advantages. Bavaria's Munich biotech cluster anchors manufacturing scale for autoimmune and oncology biologics.
Switzerland
Contract development organizations adopt continuous bioprocessing platforms to reduce facility footprint and improve lot-to-lot consistency. Swissmedic maintains stringent post-market surveillance that elevates compliance investment. Basel's pharmaceutical corridor concentrates analytical biosimilarity demonstration capabilities for European market access.
Japan
PMDA immunogenicity surveillance requirements and home medical care expansion policy drive subcutaneous formulation investment. The aging population shifts rheumatoid arthritis treatment toward self-administration models with nursing support reimbursement. Tokyo-Osaka corridor hosts reference product switching studies informing interchangeability designations.
India
CDSCO's phased biosimilar guidelines attract manufacturers establishing local analytical testing infrastructure for emerging market volume. Cost-sensitive procurement patterns favor manufacturers competing on manufacturing efficiency. Hyderabad and Bangalore biotech parks concentrate cell line development capabilities for export-oriented production.
Fusion Protein and Biosimilars Market Vendor Landscape
United States producers anchor one tier; Swiss and German specialists hold premium positioning through regulatory sophistication. The market exhibits tiered concentration with integrated pharmaceutical conglomerates, dedicated biologics manufacturers, and emerging contract specialists competing on manufacturing scale versus analytical depth. Strategic archetypes include reference product originators defending through patent thickets, biosimilar pure-plays competing on cost, and fusion protein innovators commanding differentiated pricing. Dominant competitive moves encompass vertical integration into cell line development and strategic partnerships for continuous bioprocessing technology access.
Within the integrated pharmaceutical tier, Pfizer Inc. and Amgen Inc. exemplify scale-driven competitive positioning, while Samsung Bioepis occupies a distinct archetype as a cost-focused biosimilar specialist. F. Hoffmann-La Roche Ltd. represents the reference product originator model. These entities collectively illustrate the competitive tension between manufacturing efficiency and clinical differentiation across regulatory jurisdictions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd. |
| Sandoz International GmbH |
| AbbVie Inc. |
| Samsung Bioepis |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Regeneron Pharmaceuticals, Inc. |
| Others |
Supply Flow & Price Mechanics
Continuous bioprocessing adoption simultaneously compresses manufacturing cost economics and concentrates supply among facilities with perfusion technology capabilities, reshaping how biosimilar manufacturers compete on price. This production-method transition favors entrants with capital access to automated upstream platforms while squeezing legacy batch-fed operations.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with manufacturers commanding premiums for rapid-turnaround analytical biosimilarity packages and spot-inventory discounts for standard-grade fusion proteins. Price differentiation hinges on FDA interchangeability designation and GMP certification tier, with Germany's AMNOG framework rewarding outcome-advantaged constructs. Cost compression in the biosimilar tier is intensifying because hospital group purchasing organizations consolidate sourcing decisions. Contract research organizations exhibit highest price sensitivity; reference product originators show least.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's biopharma self-sufficiency policies are reshaping sourcing patterns for cell line development and analytical testing services. Supply concentrates in Switzerland, Germany, and South Korea for precision manufacturing; India and China for cost-sensitive production. Raw material dependencies include fetal bovine serum, recombinant growth factors, and single-use bioreactor components. Single-source vulnerability in CHO cell line licensing elevates supply risk. Distribution runs through cold-chain specialty logistics with real-time temperature monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where continuous bioprocessing platforms displace batch-fed manufacturing, rewarding first movers with automated perfusion capabilities.
For Market Incumbents: Lock in analytical testing capacity through backward integration into mass spectrometry and nuclear magnetic resonance capabilities, scarce among contract testing organizations. Secure exclusive cell line licensing agreements to defend against biosimilar pure-plays competing on manufacturing efficiency. Patent thicket strategies around process patents extend exclusivity beyond composition-of-matter expiration.
For New Entrants and Emerging Players: Direct-to-clinic digital platforms for subcutaneous self-administration training open white-space in Japan's home medical care expansion. Target India's CDSCO-guided emerging market volume with local analytical testing infrastructure. Bifunctional checkpoint inhibitor formats represent the most penetrable segment for differentiated pricing against single-mechanism biologics.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated pharmaceutical conglomerates seeking biologics manufacturing scale. Long-term viability favors contract development organizations with continuous bioprocessing technology access and regulatory sophistication across FDA and EMA jurisdictions. Watch FDA guidance evolution on extrapolation of indications as the inflection signal for biosimilar penetration depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Perfusion systems reduce facility footprint and improve lot-to-lot consistency for biosimilar entrants. |
| FDA Interchangeability Pathway Investment | Switching study capabilities unlock automatic substitution in retail pharmacy channels. |
| Subcutaneous Formulation Development | Self-administration devices capture patient convenience premiums in homecare settings. |
| Dual-Target Fusion Construct Pipeline | Bifunctional cytokine traps command differentiated pricing against single-mechanism biologics. |
| Regional Analytical Testing Infrastructure | Local CDSCO-compliant facilities secure first-mover advantages in India's emerging market volume. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases provided secondary validation. Bottom-up patient-flow modeling and top-down therapeutic class sizing were reconciled through triangulation.
Data-stream reconciliation across volume, pricing, and regulatory approval timelines informed the analytical framework. Segmentation dimensions included molecular format, therapy area, delivery mode, and regional regulatory cluster. CAGRs were derived from patient population growth, biosimilar penetration assumptions, and pricing trajectory modeling. Continuous bioprocessing adoption curves and interchangeability designation timelines served as industry-specific forecast inputs.
The model holds under stable regulatory convergence between FDA and EMA guidance; deviation in patent litigation outcomes or immunogenicity surveillance requirements would shift biosimilar launch timelines. Forecasts reflect documented assumptions on therapeutic substitution policy evolution and manufacturing productivity gains. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Global Sirolimus Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Imatinib Drug Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
US Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Etanercept Market