
 Solid-State Battery Fast-Charge Degradation Test Systems Market | 2026-2036
Solid-State Battery Fast-Charge Degradation Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-State Battery Fast-Charge Degradation Test Systems Market Insights
Tier-1 battery suppliers and automotive OEMs are redrawing procurement priorities for validation equipment. Keysight Technologies leverages its precision measurement heritage to dominate high-frequency impedance analysis for solid-state cell characterization. Chroma ATE sustains competitive position through integrated power cycling and thermal management platforms tailored to Asian battery makers. Arbin Instruments specializes in multi-channel potentiostat architectures that serve research institutes scaling from coin-cell to pouch-cell testing protocols.
Solid-state battery fast-charge degradation test systems comprise integrated electrochemical instrumentation designed to apply controlled current and voltage profiles while monitoring capacity fade, impedance rise, and thermal runaway precursors in ceramic or glass-ceramic electrolyte cells operating at elevated current densities. These systems typically maintain temperature uniformity within ±0.5°C across multi-channel configurations to isolate degradation mechanisms under realistic fast-charge stress conditions. Electrical analyzers and impedance spectrometers command the largest share of product-type revenue, reflecting the complexity of separating interfacial resistance growth from bulk electrolyte degradation in sulfide and oxide chemistries. Pulse charging protocols represent the fastest-expanding technology segment, as manufacturers seek to replicate real-world DC fast-charging waveforms that trigger lithium metal dendrite propagation in solid-state architectures.
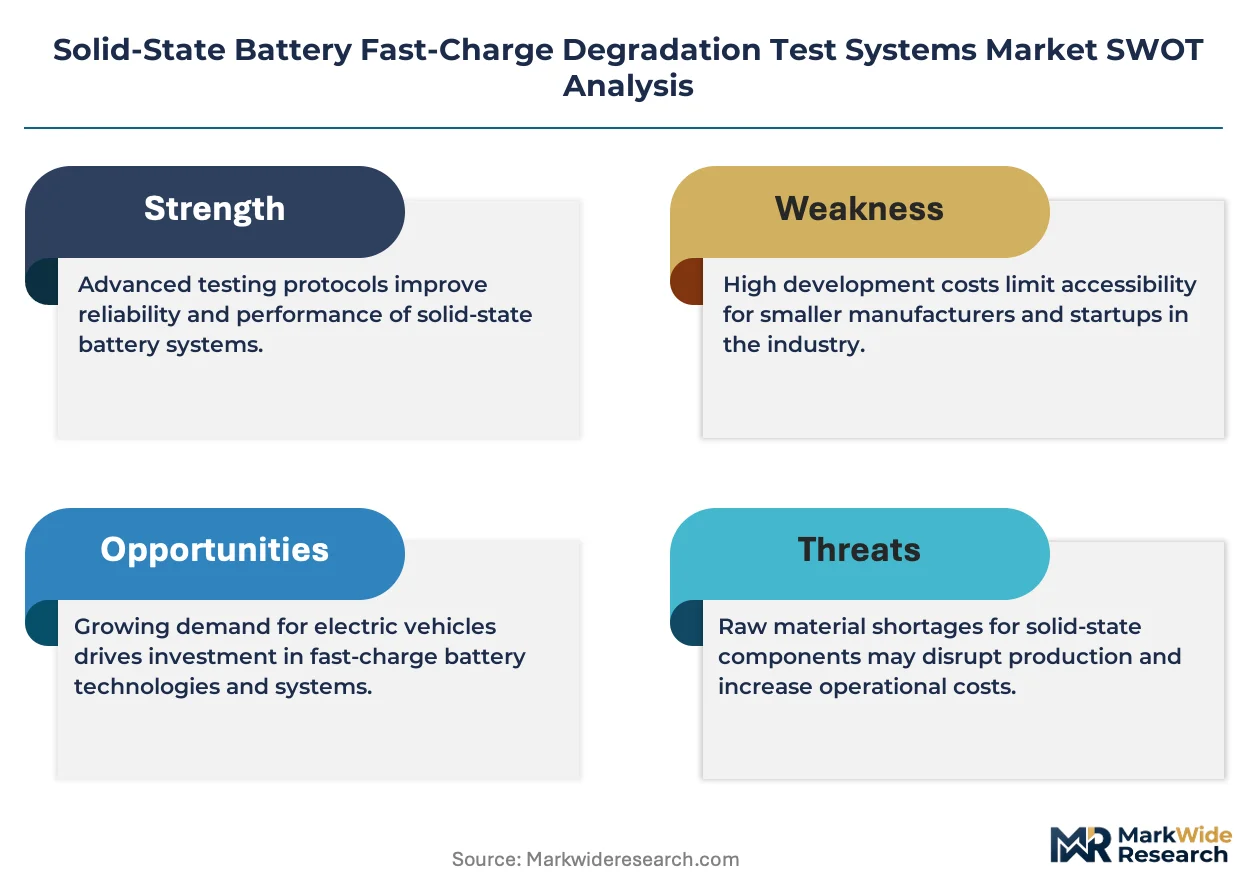
The EU Battery Regulation and REACH compliance frameworks are mandating standardized cycle-life testing and material disclosure, which forces equipment vendors to embed audit-ready data logging and chemical composition traceability. The US EPA and OSHA guidelines govern thermal chamber emissions and operator safety protocols for high-pressure cell testing environments. Stakeholders must monitor how evolving UN 38.3 transport testing amendments incorporate solid-state-specific abuse conditions, as this will determine whether existing test infrastructure requires retrofit or replacement.
Market Dynamics
The transition from liquid electrolyte to ceramic and glass-ceramic solid-state architectures is compressing validation timelines as automotive OEMs demand test systems capable of isolating lithium metal dendrite propagation at current densities exceeding 10 mA/cm².
Growth Catalysts
- EU Battery Regulation cycle-life mandates:The disclosure requirements for battery passports are compelling manufacturers to deploy accelerated degradation testing infrastructure that captures impedance rise across thousands of cycles.
- Sulfide electrolyte commercialization:Korean and Japanese battery makers are scaling pilot lines for sulfide-based cells, creating demand for thermal chambers that maintain sub-zero to 80°C stability during fast-charge protocols.
- Automotive OEM in-house validation:Volkswagen, BMW, and Toyota are building captive test facilities to reduce reliance on third-party certification labs and protect proprietary cell designs.
Market Restraints
- High-purity argon supply concentration:Sulfide electrolyte handling requires glovebox environments dependent on industrial gas suppliers concentrated in Germany and the United States, exposing test facilities to input cost volatility.
- Technical limitation in separator integration:Ceramic separator brittleness under thermal cycling creates false-positive failure modes that extend validation timelines and consume expensive prototype cells.
- REACH chemical disclosure friction:The requirement to document proprietary electrolyte compositions in European markets creates IP exposure that deters Asian manufacturers from deploying full-capability test systems in EU facilities.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:The production-linked incentive framework for 50 GWh of domestic battery capacity is creating first-mover opportunity for test system vendors to establish calibration and service infrastructure.
- Convergence of impedance spectroscopy and thermal imaging:Integrated platforms that correlate electrochemical signals with infrared hotspot detection are opening premium pricing tiers for abuse testing applications.
- Direct OEM procurement channels:Bypassing traditional distribution through Tier-1 battery suppliers allows equipment makers to capture service contract value and access proprietary test protocols.
Industry Challenges
- Electrochemical engineer scarcity:The specialized knowledge required to interpret solid-electrolyte interphase degradation signatures is concentrated in academic institutions, forcing equipment vendors to build internal training academies.
- UN 38.3 transport certification delays:The absence of solid-state-specific abuse test protocols in current lithium battery shipping regulations is creating uncertainty about whether existing thermal runaway chambers require retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid-State Battery Fast-Charge Degradation Test Systems Market |
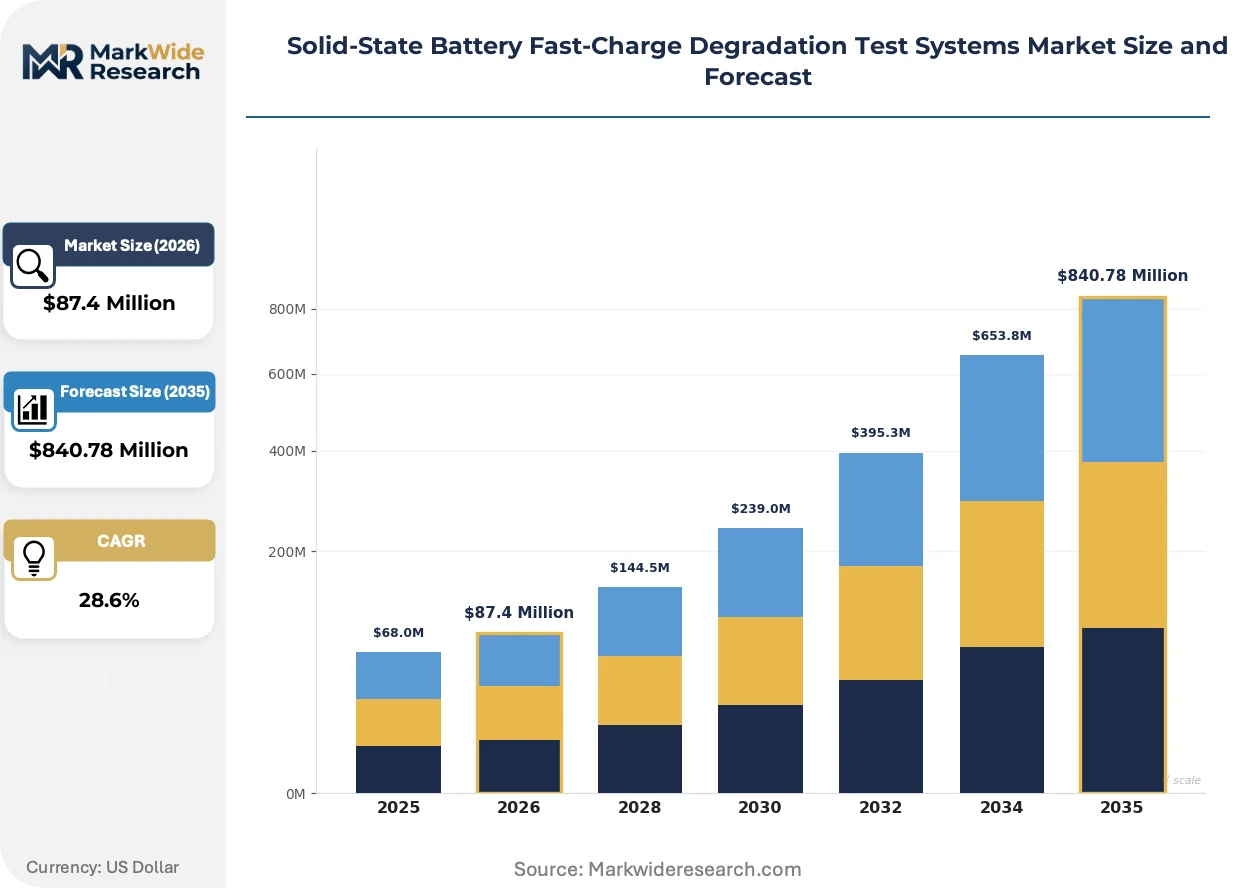
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $840.78 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Analyzers, Thermal Chambers, Voltage Monitors, Impedance Spectrometers Technology: Electrochemical Impedance Spectroscopy, Potentiostatic Methods, Galvanostatic Techniques, Pulse Charging Protocols Application: Electric Two-Wheelers, Drone Power Units, Grid Energy Storage, Portable Electronics End User: Battery Manufacturers, Research Institutes, Quality Assurance Labs, Tier-1 Suppliers |
| Companies Covered | Keysight Technologies, Chroma ATE, Arbin Instruments, BioLogic, NEWARE, Maccor, HIOKI, Bitrode, Digatron Power Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-State Battery Fast-Charge Degradation Test Systems Market Trends and Innovations
Test instrumentation architectures are bifurcating between high-throughput screening platforms for material discovery and precision diagnostic systems for production validation, with software-defined measurement engines enabling rapid reconfiguration between these modes.
Multi-physics simulation coupling is fragmenting the traditional hardware-centric test equipment market. Vendors including COMSOL and ANSYS are releasing battery-specific modules that predict dendrite growth from electrochemical-mechanical stress models, allowing virtual pre-screening before physical cell testing. Automotive validation teams at BMW and Hyundai are adopting these tools to reduce prototype consumption by 40-60% in early development phases. The resulting compression in physical test demand is forcing equipment makers to reposition as hybrid software-hardware solution providers.
REACH Article 33 substance disclosure requirements are mandating granular chemical composition logging across battery supply chains. Equipment vendors must now embed audit-ready data architectures that timestamp every measurement against material batch identifiers and supplier certificates. German test facilities are retrofitting existing systems with blockchain-traceable logging modules to satisfy downstream OEM compliance requirements. This regulatory layer is adding 15-25% to system integration costs but creating recurring revenue streams for software maintenance and audit support services.
Buyer consolidation among automotive OEMs is compressing vendor negotiation cycles and elevating technical specification authority to centralized procurement functions. Volkswagen Group's unified battery center in Salzgitter now dictates test protocol standards across its brand portfolio, displacing previously autonomous R&D site purchasing. Equipment makers are responding with configurable platform architectures that allow rapid reconfiguration between brand-specific validation requirements without hardware replacement. This shift is most visible in Germany, where OEM captive test facilities now represent the majority of new system installations.
Solid-State Battery Fast-Charge Degradation Test Systems Market Segmentation
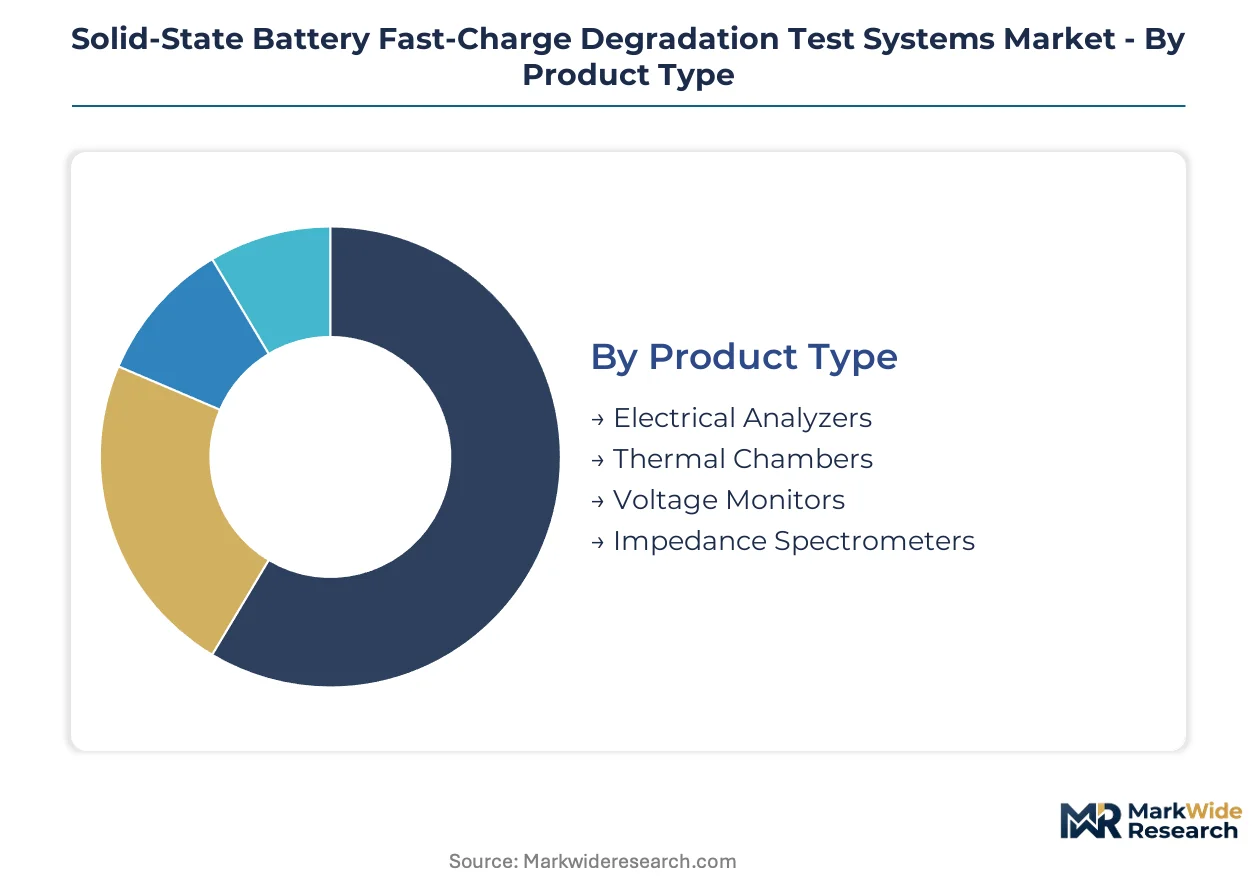
Solid-state battery validation demands highly specialized instrumentation where product architecture, measurement methodology, and end-use application each reshape procurement specifications. Equipment vendors must align technical capabilities with distinct degradation signatures across sulfide, oxide, and polymer electrolyte chemistries.
Product Type:
Premium margin pools concentrate in systems that integrate multi-physics measurement with sub-micron thermal stability control.
- Electrical Analyzers:These systems deliver precision current-voltage profiling with microsecond resolution to capture lithium metal plating dynamics during high-rate charging. Volkswagen's Salzgitter battery center and BMW's Munich validation facility have standardized procurement around 256-channel configurations that isolate interfacial resistance growth in sulfide electrolytes. The dominant share belongs to Electrical Analyzers, while Impedance Spectrometers is closing the gap fastest.
- Impedance Spectrometers:Frequency-domain analysis from millihertz to megahertz separates bulk electrolyte degradation from grain-boundary resistance accumulation in ceramic architectures. Korean battery makers including Samsung SDI and SK On are deploying these systems for pilot-line quality gates that screen cells before module assembly.
- Thermal Chambers:Multi-zone environmental control maintains ±0.5°C uniformity across 100+ cell positions during accelerated aging protocols.
- Voltage Monitors:High-impedance input stages track open-circuit voltage drift without loading effects during month-long calendar aging studies.
System integrators capture additional margin by bundling thermal management with electrochemical measurement in unified platforms.
Technology:
Measurement methodology selection determines whether validation teams can distinguish reversible polarization from permanent capacity loss mechanisms.
- Pulse Charging Protocols:Waveform synthesis replicates DC fast-charging profiles with 10 ms rise times to trigger dendrite nucleation under controlled conditions. Toyota's solid-state development program in Japan and QuantumScape's San Jose facility have adopted these methods to correlate pulse parameters with lithium metal filament growth. Electrochemical Impedance Spectroscopy holds the dominant share, while Pulse Charging Protocols is expanding most quickly.
- Electrochemical Impedance Spectroscopy:Broadband AC perturbation maps resistance contributions across electrode-electrolyte interfaces, grain boundaries, and bulk ceramic phases. German research institutes including Fraunhofer IKTS and Karlsruhe Institute of Technology rely on EIS for mechanistic degradation studies that inform next-generation electrolyte formulations.
- Potentiostatic Methods:Fixed-potential holds quantify leakage currents that indicate electronic conductivity degradation in solid electrolytes.
- Galvanostatic Techniques:Constant-current cycling generates capacity fade curves for cycle-life certification under EU Battery Regulation disclosure requirements.
Software-defined architectures now enable rapid switching between these measurement modes without hardware reconfiguration.
Application:
Application-driven specifications diverge sharply between consumer electronics tolerance for gradual degradation and automotive zero-failure requirements.
- Grid Energy Storage:Utility-scale systems demand 20-year calendar life validation with daily cycling stress, requiring test platforms that operate continuously for multi-year protocols. Fluence and Wartsila are procuring high-channel-count systems for solid-state cell qualification in their stationary storage product lines. Grid Energy Storage commands the dominant share, while Drone Power Units is gaining share fastest.
- Drone Power Units:Aerospace applications prioritize power density and rapid charge acceptance over absolute cycle count, with test protocols emphasizing 5C-rate capability verification. DJI and Skydio are driving demand for compact thermal chambers that validate cells under vibration and altitude simulation.
- Electric Two-Wheelers:Cost-sensitive validation programs focus on simplified pass-fail screening rather than mechanistic degradation analysis.
- Portable Electronics:Smartphone and laptop OEMs require small-format coin-cell test fixtures that accelerate material down-selection before pouch-cell scale-up.
Automotive OEMs are consolidating procurement authority for grid storage and mobility applications under centralized battery centers.
End User:
End-user category determines whether equipment purchases prioritize throughput volume or diagnostic precision.
- Battery Manufacturers:Cell producers including CATL, BYD, and LG Energy Solution operate 24/7 validation floors with 10,000+ channel capacities that screen every production batch for fast-charge degradation susceptibility. These facilities demand equipment with 99.5% uptime guarantees and 4-hour service response commitments. Battery Manufacturers hold the dominant share, while Research Institutes is climbing the fastest.
- Research Institutes:Academic and national laboratory users prioritize measurement flexibility and publication-grade data integrity over throughput. Max Planck Institute for Solid State Research and MIT's Materials Research Laboratory are acquiring systems with open software architectures that enable custom algorithm development for novel electrolyte characterization.
- Quality Assurance Labs:Third-party certification bodies require audit-ready data logging that satisfies EU Battery Regulation and UN 38.3 transport testing documentation standards.
- Tier-1 Suppliers:Automotive subsystem integrators including Bosch and Continental are building captive test capabilities to validate solid-state cells within module and pack architectures.
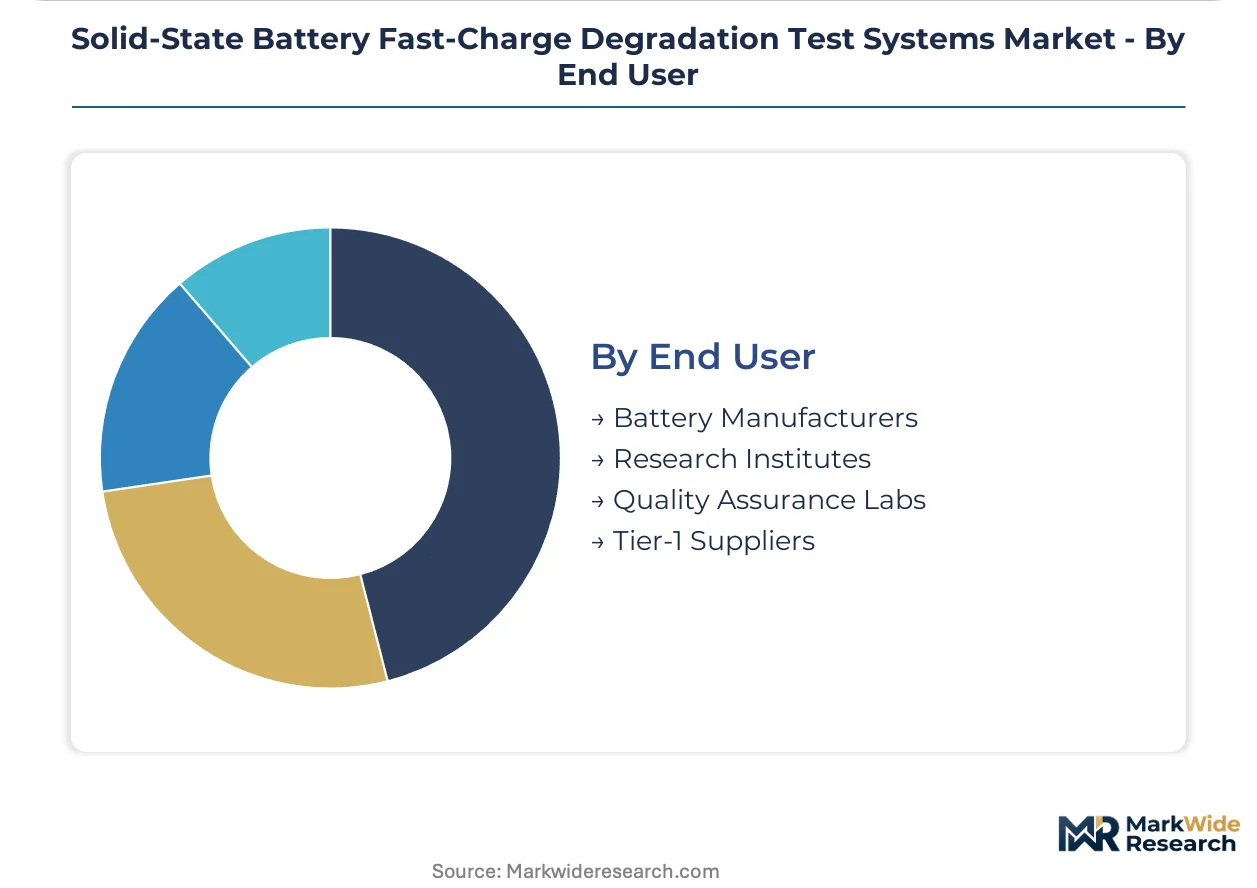
Direct OEM procurement is displacing traditional distribution channels as Volkswagen, BMW, and Toyota establish technical specification authority over their supplier networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German test equipment exports supply automotive OEM validation centers across Asia and North America, while Korean and Japanese battery makers import precision impedance systems for sulfide electrolyte pilot lines.
Germany
Automotive battery R&D clusters in Salzgitter and Munich drive procurement of high-throughput degradation test systems. The EU Battery Regulation mandates cycle-life disclosure through battery passports, compelling Volkswagen and BMW to deploy accelerated testing infrastructure. Fraunhofer IKTS in Dresden anchors mechanistic degradation research for next-generation ceramic electrolytes.
South Korea
Samsung SDI and SK On scale sulfide-based solid-state pilot lines requiring thermal chambers with sub-zero to 80°C stability. The national industrial regulator enforces strict cell certification protocols for EV export markets. Incheon and Gwangju host concentrated procurement of pulse charging protocol systems for dendrite detection.
Japan
Toyota's solid-state development program in Aichi Prefecture validates lithium metal anode compatibility at current densities exceeding 10 mA/cm². METI funding supports domestic test equipment manufacturers serving automotive and consumer electronics applications. Tsukuba research corridors integrate electrochemical impedance spectroscopy with thermal imaging for abuse testing.
United States
QuantumScape's San Jose facility and Ford's Dearborn battery center drive demand for multi-channel potentiostat architectures. OSHA guidelines govern thermal chamber emissions for high-pressure cell testing environments. Michigan and California clusters concentrate procurement from research institutes scaling coin-cell to pouch-cell protocols.
China
CATL and BYD operate 24/7 validation floors with 10,000+ channel capacities screening production batches for fast-charge degradation. GB standards and MIIT regulations shape equipment specifications for domestic and export markets. Shenzhen and Ningbo industrial zones concentrate system integration and calibration service infrastructure.
Solid-State Battery Fast-Charge Degradation Test Systems Market Competitive Landscape
Listed leaders compete with private specialists across measurement precision and software-defined architectures. The market structure concentrates around precision instrumentation heritage players and Asian system integrators with captive battery maker relationships. Three archetypes dominate: precision measurement heritage firms, integrated power cycling platform specialists, and multi-channel potentiostat architects. Competitive moves center on direct OEM procurement channel development and hybrid software-hardware solution repositioning.
Within the precision measurement tier, Keysight Technologies and HIOKI occupy positions anchored in frequency-domain analysis heritage. Chroma ATE and NEWARE exemplify the integrated platform archetype serving high-volume Asian battery manufacturers. Arbin Instruments represents the multi-channel specialization segment addressing research institute scalability requirements. These anchors illustrate how vendor positioning diverges between diagnostic precision and throughput optimization.
| Leading Market Players |
|---|
| Keysight Technologies |
| Chroma ATE |
| Arbin Instruments |
| BioLogic |
| NEWARE |
| Maccor |
| HIOKI |
| Bitrode |
| Digatron Power Electronics |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation cycle-life disclosure mandates gate both supplier qualification and price differentiation simultaneously, compelling test system vendors to embed audit-ready data architectures that separate certified premium tiers from standard offerings. This regulatory layer adds system integration costs while creating recurring software maintenance revenue streams that protect margin pools.
Pricing Analysis
Next-generation pulse charging protocol systems command substantial premiums over legacy galvanostatic cycling platforms, while current-generation electrical analyzers with integrated thermal management occupy the mid-tier. Pricing stratifies across premium, standard, and economy tiers based on channel count scalability and REACH-compliant data logging certification. Cost compression in economy-tier voltage monitors is intensifying because Asian battery manufacturers are internalizing basic cycling infrastructure. Research institutes exhibit lowest price sensitivity due to grant-funded procurement, while electric two-wheeler OEMs drive hardest bargain for simplified pass-fail screening systems.
Supply Chain Analysis
Component lead times for precision impedance measurement modules have extended substantially, forcing test system assemblers to carry elevated inventory of field-programmable gate arrays and cryogenic-rated thermal sensors. Manufacturing concentrates in Germany, South Korea, and China, with German facilities specializing in high-frequency spectrometers and Asian plants dominating multi-channel potentiostat volume production. The supply chain draws from concentrated industrial gas suppliers for high-purity argon glovebox environments, exposing facilities to input cost volatility. Single-source vulnerability in ceramic heater elements for thermal chambers represents the dominant structural risk. Distribution runs through direct OEM procurement channels that displace traditional Tier-1 battery supplier intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates sticky customer relationships. EU Battery Regulation compliance requirements embed switching costs that protect incumbent positions.
For Market Incumbents: Shield installed base profitability by embedding blockchain-traceable logging modules that deepen regulatory compliance dependencies. Pursue backward integration into precision thermal sensor manufacturing to secure supply continuity against ceramic heater element shortages. Prioritize certification investment in UN 38.3 solid-state-specific abuse test protocols before amendments finalize, locking out retrofit-dependent competitors.
For New Entrants and Emerging Players: After-sales service infrastructure gaps in India's PLI scheme zones offer immediate white-space capture opportunity. Target research institute procurement with open-architecture software platforms that enable custom algorithm development, the most penetrable segment given academic budget fragmentation. Pursue geographic expansion through calibration and service hub establishment in Gwangju and Ningbo industrial corridors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated electrochemical-thermal platforms, favoring scaled players with captive manufacturing. Long-term viability hinges on software-defined measurement engine differentiation rather than hardware commoditization. Target acquisition candidates with hybrid physics simulation coupling capabilities that reduce prototype consumption for automotive validation teams. Monitor UN 38.3 amendment timing as inflection signal for retrofit-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Measurement Engine Development | Enables rapid reconfiguration between high-throughput screening and precision diagnostic modes for Volkswagen and BMW validation centers. |
| Blockchain-Traceable Data Logging Integration | Satisfies REACH Article 33 substance disclosure requirements for German test facility retrofit contracts. |
| Multi-Physics Simulation Coupling Partnership | Reduces prototype cell consumption by automotive OEMs adopting COMSOL and ANSYS battery-specific modules. |
| Direct OEM Procurement Channel Establishment | Captures service contract value and proprietary test protocol access bypassing Tier-1 battery supplier distribution. |
| India PLI Zone Calibration Infrastructure Deployment | Positions first-mover service presence for 50 GWh domestic advanced chemistry cell capacity incentive framework. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with test equipment procurement officers at automotive OEM battery centers, electrochemical instrumentation product managers, and solid-state cell validation engineers; alongside secondary validation through SEC filings of precision measurement heritage firms, EU Battery Regulation implementation guidance documents, and Korean industrial regulator cell certification protocols. Bottom-up channel count and system pricing estimates triangulated against top-down market size projections derived from gigafactory project announcements and R&D facility expansion disclosures.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture, measurement methodology, end-use application, and geographic production cluster. CAGRs were computed from annualized growth trajectories anchored to disclosed validation floor capacities and pilot line scaling timelines. Industry-specific forecast inputs included sulfide electrolyte commercialization schedules and automotive OEM in-house facility buildout commitments.
Forecasts assume regulatory continuity in EU Battery Regulation and REACH frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Compression Testers Market
Test and Measurement
Dosimeter Market
Test and Measurement
RFID Tester Market
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Battery Testing and Inspection Equipment Market