
 Fat Free Pasta Market | 2026-2036
Fat Free Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Pasta Market Analytics
The EU Green Deal's farm-to-fork sustainability targets are shifting procurement criteria across European retail chains, mandating cleaner ingredient decks and reduced fat profiles in private-label pasta ranges. Barilla Holding SpA leverages its vertically integrated durum wheat supply chain to sustain cost discipline in fat-free SKUs. Banza competes through its chickpea-flour specialization, anchoring the alternative-ingredient tier with strong shelf presence in North American health food channels.
Fat free pasta denotes wheat-based or legume-based noodles formulated with negligible lipid content, typically achieving below 2% fat by weight through modified extrusion temperatures and the exclusion of egg yolks or oil-enriched semolina; the product serves consumers pursuing caloric restriction, cardiovascular health management, or macronutrient-controlled diets. Spaghetti and penne dominate volume due to their manufacturing scalability and broad recipe compatibility across home and foodservice settings. Chickpea flour and lentil flour variants represent the fastest-expanding ingredient segment, commanding premium positioning as protein-fortified alternatives to conventional semolina.
FDA nutrition labeling requirements and the EU's FIC Regulation govern fat-content claims and serving-size disclosures, compelling manufacturers to standardize analytical testing protocols before market entry. Health Canada and EFSA guidelines on glycemic index labeling further shape product development priorities for brands targeting diabetic and metabolic-health segments. Stakeholders must monitor evolving front-of-pack scoring systems and emerging genome-edited wheat varieties that could redefine the cost structure of low-fat traditional pasta.
Market Dynamics
The EU Green Deal's farm-to-fork sustainability targets are mandating cleaner ingredient decks across European retail chains, forcing manufacturers to reformulate private-label pasta ranges with reduced fat profiles and traceable wheat sourcing while competing with legume-based alternatives.
Growth Catalysts
- EU Front-of-Pack Labeling:Traffic light schemes and Nutri-Score mandates in France, Belgium, and Germany are accelerating retail shelf allocation toward fat-reduced SKUs with cleaner nutritional credentials.
- Meal-Kit Subscriptions:Urban millennials in Berlin, London, and Amsterdam are driving recurring demand through direct-to-consumer channels that prioritize macronutrient transparency and recipe-compatible formats.
- Chickpea Flour Extrusion:Modified low-temperature processing technology is enabling protein-fortified pasta production without lipid enrichment, opening premium positioning in health food retail.
Market Restraints
- Durum Wheat Price Volatility:Input cost fluctuations for high-protein semolina constrain margin stability for traditional fat-free wheat pasta manufacturers dependent on North African and Canadian supply.
- Italian Mill Concentration:Three major durum processors control over sixty percent of EU semolina supply, creating procurement bottlenecks for mid-tier brands seeking certified low-fat raw material streams.
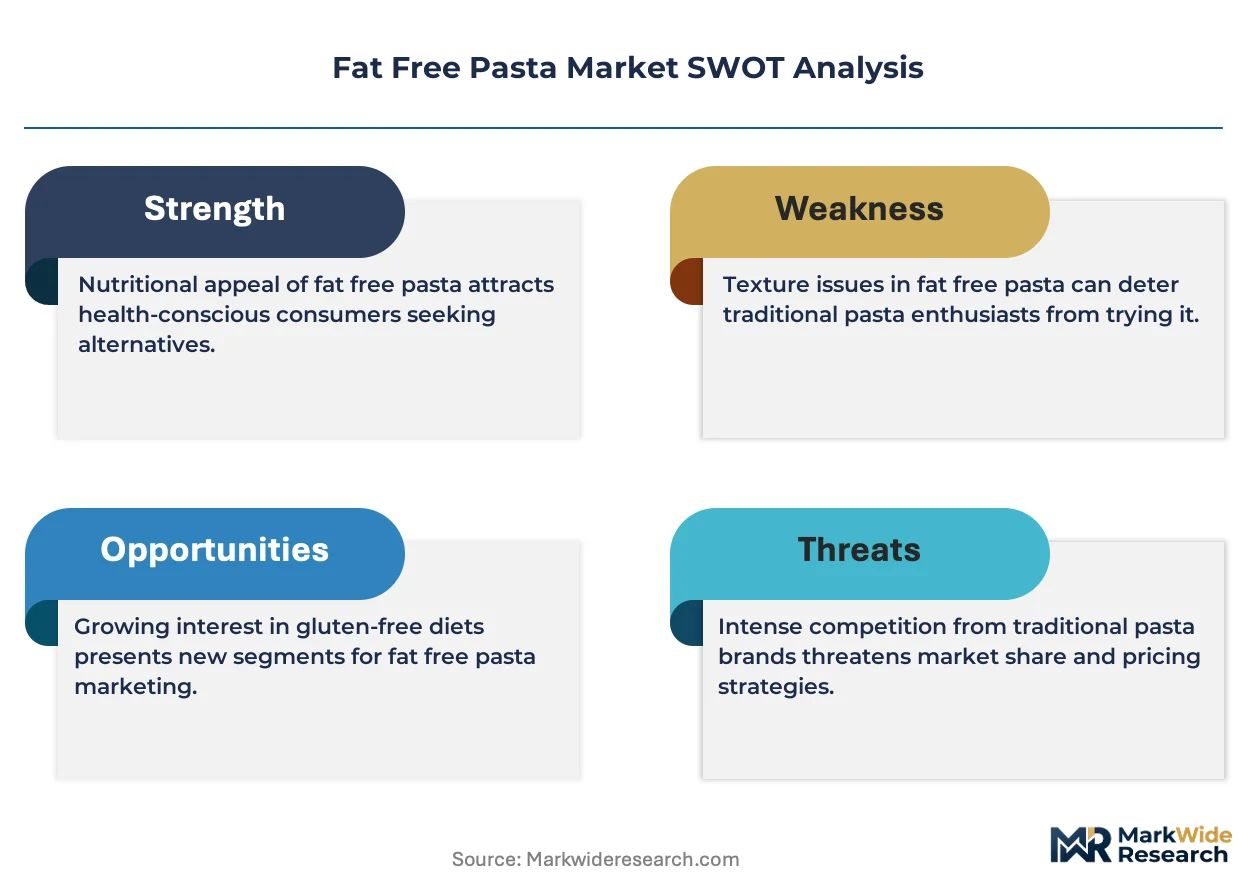
- Texture Limitations:Egg yolk exclusion in fat-free formulations produces reduced mouthfeel and sauce adhesion compared to conventional pasta, limiting foodservice adoption in premium Italian restaurants.
Strategic Opportunities
- EFSA Glycemic Index Claims:Pending regulatory guidance on low-GI labeling creates first-mover advantage for brands targeting diabetic and metabolic health segments with lentil-flour variants.
- Chickpea-Lentil Blends:Converging alternative protein processing with modified extrusion technology enables hybrid formulations that balance cost and nutritional density for mass-market penetration.
- Quick-Commerce Channels:Fifteen-minute grocery delivery platforms in Paris, Milan, and Madrid are expanding shelf space for functional pasta SKUs among time-constrained urban households.
Industry Challenges
- Analytical Testing Standardization:FDA and EU FIC Regulation divergence on fat-content claim thresholds forces manufacturers to maintain dual certification protocols for transatlantic distribution.
- Extrusion Equipment Retrofit Costs:Legacy semolina production lines require capital-intensive temperature-control modifications to achieve sub-two-percent fat targets without product degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Pasta Market |
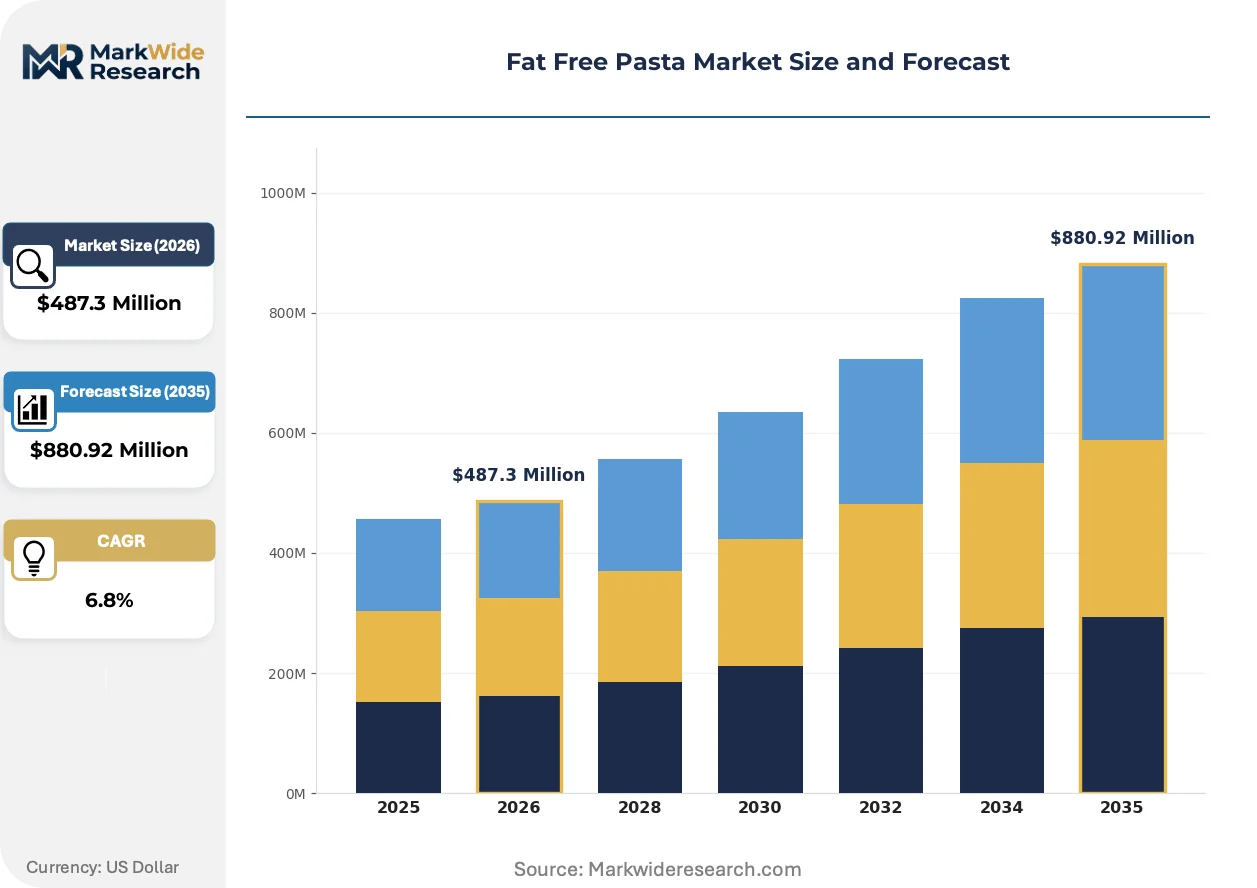
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Penne, Fusilli, Macaroni Ingredient Type: Whole Wheat, Lentil Flour, Chickpea Flour, Rice Flour Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores Consumer Type: Health-Conscious Individuals, Fitness Enthusiasts, Gluten-Free Consumers, Vegetarians |
| Companies Covered | Barilla Holding SpA, Banza, Nestlé SA, Campbell Soup Company, Ebro Foods SA, Nissin Foods Holdings Co., Ltd., Miracle Noodle, Veggiecraft Farms, Palmini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Pasta Market Evolving Landscape
Reformulation science and procurement transparency are converging to reshape competitive positioning in functional pasta, with alternative ingredients and regulatory compliance emerging as the primary vectors of differentiation.
Modified low-temperature extrusion technology is overtaking conventional high-heat processing in premium fat-free pasta manufacturing. Health-conscious households in German urban centers are adopting these products at accelerating rates through subscription channels. This shift is compressing the cost premium between wheat-based and legume-based alternatives while enabling cleaner label claims.
REACH-compliant food contact material standards are tightening migration limits for processing equipment lubricants and packaging films used in pasta production. Manufacturers serving EU retail chains must now certify entire production lines against updated substance restrictions. Italian and Spanish private-label suppliers are responding by accelerating equipment replacement cycles ahead of enforcement deadlines.
Direct sourcing relationships between retail chains and durum wheat cooperatives are displacing traditional commodity procurement through spot markets. Discounters in Germany and France are negotiating multi-year supply agreements that embed fat-content specifications and sustainability certifications. This pattern is most visible in Bavaria and Rhône-Alpes, where regional millers are capturing volume previously held by trading houses.
Fat Free Pasta Market Segmentation
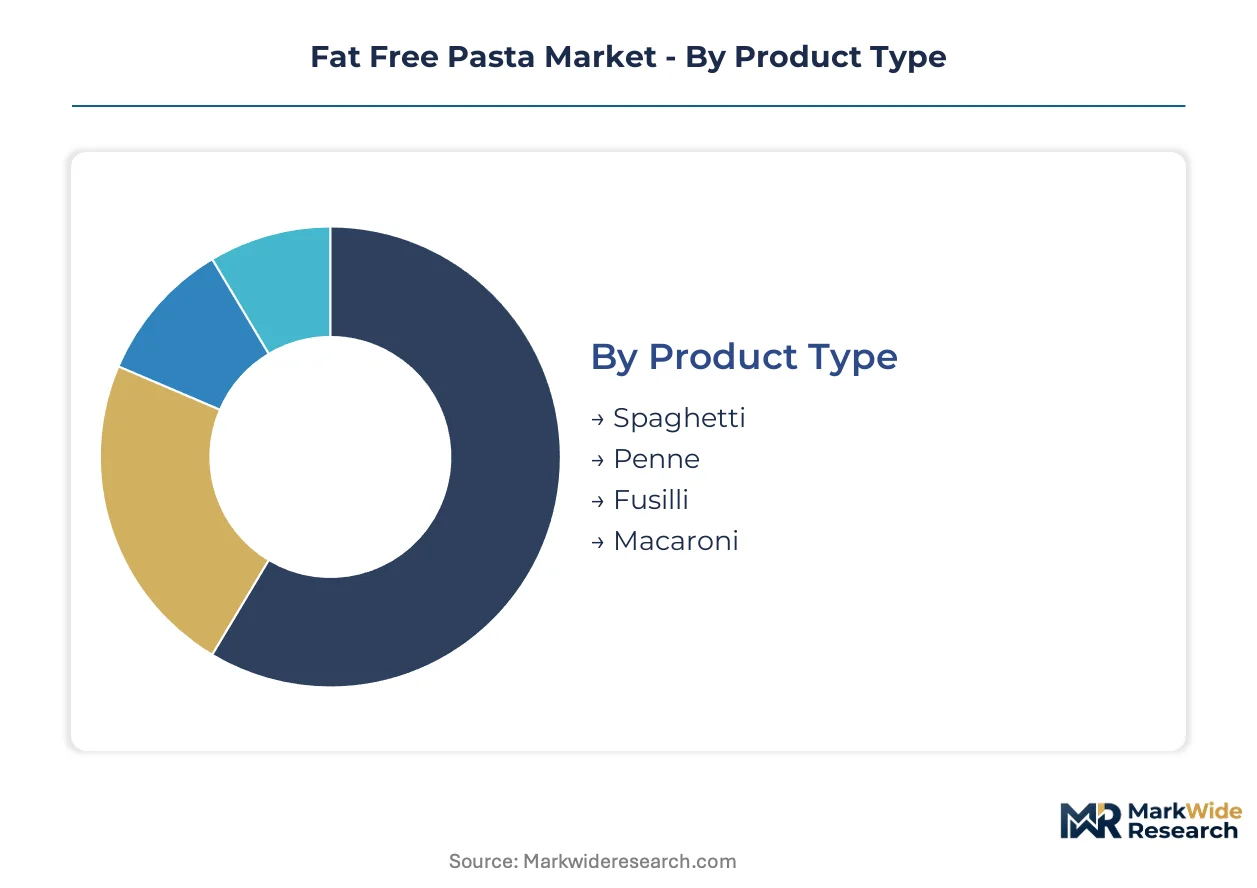
Segmentation in fat free pasta reveals how capital deployment, ingredient sourcing, and channel access create divergent margin profiles across the value chain. Manufacturers must align extrusion technology investments with specific segment requirements to capture sustainable positioning.
Product Type:
Capital intensity varies sharply by shape complexity, with long-cut formats demanding precision temperature control and short-cut varieties requiring multi-die extrusion systems.
- Spaghetti:Continuous extrusion through bronze dies achieves the sub-two-percent fat target with modified drying curves. German retail chains allocate disproportionate shelf space to this format in response to Nutri-Score labeling mandates.
- Penne:Diagonal cutting and ridged surface formation require secondary forming stations that elevate equipment costs. Urban millennial households in Berlin and London drive recurring demand through meal-kit subscriptions prioritizing sauce adhesion.
- Fusilli:Helical shaping demands specialized rotating dies that increase maintenance overhead.
- Macaroni:Curved elbow forms suit foodservice portioning but face texture limitations in egg-free formulations.
Spaghetti absorbs the bulk of installed capacity; penne is expanding most quickly.
Ingredient Type:
Raw material processing costs stratify segments, with legume flours requiring dehulling and protein isolation stages that wheat semolina avoids.
- Whole Wheat:High-fiber bran retention in durum semolina achieves fat reduction without ingredient substitution. Italian mill concentration in the EU creates procurement bottlenecks for certified low-fat streams.
- Chickpea Flour:Protein fortification through low-temperature extrusion enables premium positioning in North American health food channels. Modified processing technology eliminates lipid enrichment while maintaining structural integrity.
- Lentil Flour:Pending EFSA glycemic index guidance positions this segment for diabetic-targeted claims.
- Rice Flour:Hypoallergenic properties serve gluten-free consumers but require starch pre-gelatinization.
Whole wheat dominates current volume; chickpea flour is climbing the fastest.
Distribution Channel:
Channel selection determines working capital requirements, with direct-to-consumer models demanding inventory velocity that traditional retail avoids.
- Supermarkets:Front-of-pack labeling compliance and traffic light schemes in France and Belgium accelerate shelf reallocation toward fat-reduced SKUs. Discounters negotiate multi-year supply agreements embedding sustainability certifications.
- Online Retailers:Direct-to-consumer channels in urban centers prioritize macronutrient transparency and subscription mechanics. Fifteen-minute grocery delivery platforms in Paris and Milan expand functional pasta visibility among time-constrained households.
- Health Food Stores:Premium positioning depends on clean-label verification and alternative protein credentials.
- Specialty Stores:Italian and Spanish private-label suppliers face REACH-compliant packaging migration deadlines.
Supermarkets retain the largest revenue share; online retailers are gaining share fastest.
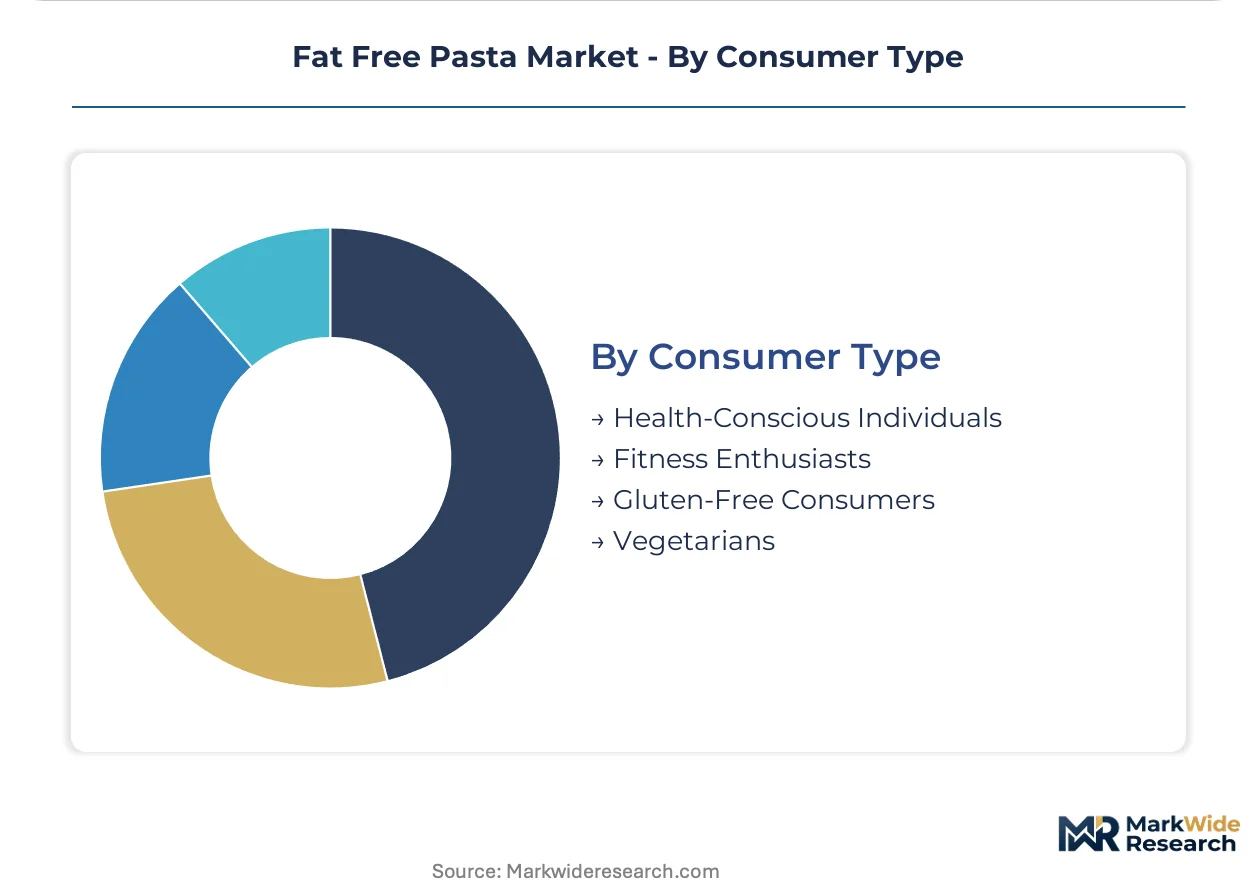
Consumer Type:
Targeting precision shapes product development priorities, with metabolic health segments driving analytical testing investments that general wellness consumers do not require.
- Health-Conscious Individuals:Caloric restriction and cardiovascular management priorities align with fat-free claims below two-percent lipid content. FDA and EU FIC Regulation divergence forces dual certification protocols for brands serving transatlantic demand.
- Fitness Enthusiasts:Protein-to-carbohydrate ratio optimization drives uptake of chickpea-lentil hybrid formulations. Meal-kit subscriptions in Amsterdam and Madrid emphasize post-workout macronutrient targets.
- Gluten-Free Consumers:Rice and legume bases substitute for wheat but require separate production line certification.
- Vegetarians:Plant-protein completeness influences ingredient blending decisions.
Health-conscious individuals represent the largest addressable base; fitness enthusiasts show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin's urban millennial clusters drive recurring demand through meal-kit subscriptions that prioritize macronutrient transparency and fat-reduced SKUs.
Germany
Health-conscious households in Bavaria and Berlin accelerate uptake through direct-to-consumer channels. The EU's Nutri-Score front-of-pack labeling mandates shelf reallocation toward fat-reduced pasta ranges. Discounters in Bavaria negotiate multi-year supply agreements embedding sustainability certifications and traceable wheat sourcing.
United States
FDA nutrition labeling requirements govern fat-content claims and serving-size disclosures for brands targeting caloric restriction segments. Health Canada guidelines on glycemic index labeling shape product development for diabetic-targeted offerings. Chicago and New York metro areas show concentrated demand through health food retail channels prioritizing clean-label verification.
France
Traffic light schemes and Nutri-Score mandates in Paris accelerate retail shelf allocation toward fat-reduced SKUs with cleaner nutritional credentials. The EU Green Deal's farm-to-fork sustainability targets mandate cleaner ingredient decks across Rhône-Alpes retail chains. Lyon-based private-label suppliers face REACH-compliant packaging migration deadlines for quick-commerce channels.
Italy
Three major durum processors control over sixty percent of EU semolina supply, creating procurement bottlenecks for certified low-fat raw material streams. Italian mill concentration in Emilia-Romagna constrains margin stability for mid-tier brands. Milan's fifteen-minute grocery delivery platforms expand shelf space for functional pasta SKUs among time-constrained urban households.
United Kingdom
Urban millennials in London drive recurring demand through subscription mechanics prioritizing recipe-compatible formats. The EU FIC Regulation divergence from FDA protocols forces dual certification for brands serving transatlantic distribution. Health food channels in Greater Manchester emphasize alternative protein credentials for chickpea-lentil hybrid formulations.
Fat Free Pasta Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ingredient sourcing and extrusion technology dimensions. The vendor base stratifies between vertically integrated durum wheat processors and specialized legume-flour innovators. Three strategic archetypes dominate: traditional semolina specialists with captive supply chains, alternative-ingredient disruptors leveraging modified low-temperature processing, and private-label suppliers serving retail discounters. Competitive moves concentrate on equipment retrofit investments for sub-two-percent fat targets and direct sourcing relationships displacing spot market procurement.
Within the integrated supply chain tier, Barilla Holding SpA exemplifies backward integration into durum wheat sourcing. Among alternative-ingredient specialists, Banza occupies a position anchoring the chickpea-flour segment in North American health food channels. Ebro Foods SA sits within the private-label supplier archetype serving European retail discounters with certified low-fat raw material streams.
| Leading Market Players |
|---|
| Barilla Holding SpA |
| Banza |
| Nestlé SA |
| Campbell Soup Company |
| Ebro Foods SA |
| Nissin Foods Holdings Co., Ltd. |
| Miracle Noodle |
| Veggiecraft Farms |
| Palmini |
| Others |
Value Network & Pricing Analysis
Modified low-temperature extrusion technology is compressing the cost premium between wheat-based and legume-based fat-free pasta while concentrating production capability among equipment-retrofitted manufacturers. This shift simultaneously elevates capital barriers for new entrants and reshapes procurement power toward buyers with multi-year supply commitments.
Pricing Analysis
Value-based pricing anchored to glycemic index certification and clean-label verification stratifies across premium, standard, and economy tiers. Price differentiation rests on EFSA-compliant testing protocols and REACH-certified packaging migration limits. Cost compression in mid-tier wheat pasta is intensifying because Italian mill concentration constrains certified low-fat semolina availability. Discounters in Germany exhibit highest price sensitivity; health food channels in North America show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, Italy, and France coordinate hub-and-spoke patterns for EU retail chains. Raw material streams draw from Canadian and North African durum wheat cooperatives, Italian semolina processors, and North American chickpea flour isolators. Single-source vulnerability concentrates in Emilia-Romagna's three major durum processors controlling sixty percent of EU supply. Distribution runs through direct sourcing agreements displacing spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semolina milling capacity concentration in Italy props pricing power for integrated processors while constraining margin recovery for mid-tier brands dependent on certified low-fat raw material streams.
For Market Incumbents: Deploy captive durum wheat supply agreements to lock in certified low-fat streams before REACH enforcement deadlines tighten equipment replacement cycles. Barilla's backward integration into durum sourcing exemplifies this lever against chickpea-flour disruptors eroding wheat-based volume share. For New Entrants and Emerging Players: Enter via quick-commerce channels in Paris, Milan, and Madrid where fifteen-minute grocery platforms expand shelf space for functional pasta SKUs among time-constrained urban households. Target fitness enthusiasts through meal-kit subscriptions emphasizing post-workout macronutrient targets and chickpea-lentil hybrid formulations. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of alternative-ingredient specialists with modified extrusion patents and EFSA pre-submission glycemic index dossiers. Long-term viability hinges on regulatory clearance for diabetic-targeted claims. Watch EFSA guidance publication as inflection signal for lentil-flour segment repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment Retrofit for Sub-2% Fat Targets | Modified temperature-control extrusion enables REACH-compliant production without product degradation. |
| Direct Sourcing with Durum Cooperatives | Multi-year agreements embedding sustainability certifications displace commodity spot procurement. |
| EFSA Glycemic Index Pre-Submission | First-mover positioning for diabetic-targeted claims on lentil-flour variants awaits regulatory clarity. |
| Quick-Commerce Channel Expansion | Fifteen-minute delivery platforms in Paris and Milan elevate functional pasta visibility among urban households. |
| Chickpea-Lentil Hybrid Formulation | Converging alternative protein processing balances cost and nutritional density for mass-market penetration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with extrusion equipment manufacturers, retail category buyers, durum mill procurement leads, and foodservice distribution heads combined with EFSA guidance documents, FDA nutrition labeling databases, and EU FIC Regulation compliance records. Bottom-up volume modeling and top-down value triangulation validated segment-level outputs.
Granularity extended to ingredient type, product format, distribution channel, and consumer health segment across the analysis window. CAGRs derived from weighted average of historical trajectory and forward-looking capacity deployment patterns. Wheat price volatility assumptions and regulatory timeline scenarios shaped sensitivity bounds for lentil-flour adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under durum supply disruption or accelerated EFSA glycemic index guidance. Forecasts reflect documented assumptions on extrusion technology diffusion and retail shelf reallocation mechanics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Tortilla Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Europe Ready-To-Eat Food Market