
 Raisins Market | 2026-2036
Raisins Market Size, Share, and Industry Trends Forecast 2026-2036
Raisins Market Intelligence
The proliferation of high-speed optical sorting technology is narrowing the quality variance between different raisin grades. Sun-Maid Growers of California leverages its extensive grower network and brand recognition in the retail channel. Olam International Limited competes on a global scale through its vast sourcing and logistics infrastructure. Mariani Packing Company differentiates with a focus on both conventional and organic product lines for private label and branded sales.
Raisins are grapes that have been dried, a process which concentrates their sugars and nutrients. A critical quality parameter is a final moisture content typically below 16 percent to ensure shelf stability and prevent mold growth. Thompson Seedless varieties continue to dominate production volume due to their versatility and wide consumer acceptance. The snack foods and bakery applications represent the largest end-use segments, with food manufacturers procuring large volumes for inclusion in their products.
Regulatory frameworks, including USDA grading standards and FDA food safety rules in the United States, define quality and market access. In Europe, EFSA regulations on contaminants such as ochratoxin A impose strict controls on imported and domestic products. Producers must now focus on water management strategies and crop diversification to mitigate climate-related supply chain risks.
Market Dynamics
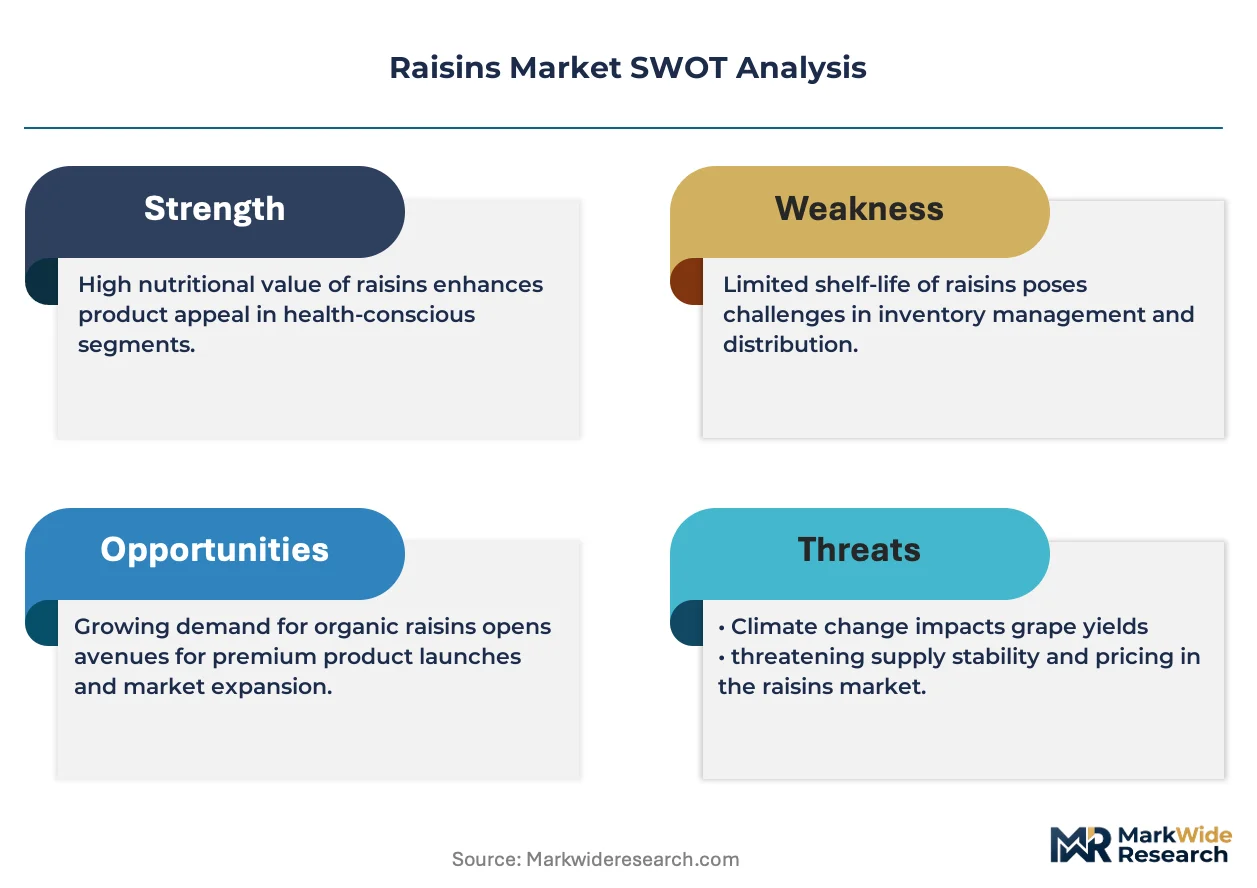
The central force shaping the raisin market is the collision between rising consumer demand for natural, minimally processed snacks and increasing agricultural volatility driven by climate change. This dynamic places immense pressure on water management strategies and supply chain resilience, defining the competitive landscape for growers and processors alike.
Growth Catalysts
- Clean Label Snacking:Food manufacturers are increasing raisin procurement for snack bars and cereals, meeting consumer demand for natural ingredients.
- Health-Conscious Demographics:In markets like the United States and Germany, health-focused consumers are boosting retail demand for nutrient-dense snacks.
- Water Management Technology:The adoption of drip irrigation in arid growing regions is essential for maintaining crop yields and ensuring supply chain stability.
Market Restraints
- Labor Cost Volatility:Heavy reliance on manual harvesting exposes producers to wage inflation and workforce shortages, directly impacting input costs.
- Geographic Concentration Risk:Supply is vulnerable to localized weather events, with production heavily concentrated in climate-sensitive regions like California and Turkey.
- Ingredient Substitution:Raisins face competition from other dried fruits like dates and cranberries, and from processed sweeteners in industrial food applications.
Strategic Opportunities
- Asia-Pacific Market Entry:Targeting middle-class consumers in Southeast Asia where Western snacking trends create new demand for natural food products.
- Product Formulation Innovation:Developing raisin pastes and powders creates new industrial uses as binders in savory and plant-based foods.
- Premium Certification Lines:Expanding organic and fair-trade certified products captures value from ethically-minded consumers in Europe and North America.
Industry Challenges
- Contaminant Regulation Compliance:Producers face the operational challenge of consistently meeting stringent international standards, such as EFSA limits on ochratoxin A, requiring significant testing and process control.
- Moisture Control Management:Achieving and maintaining a final moisture content below the critical threshold for shelf stability requires precise control throughout drying, processing, and logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Raisins Market |
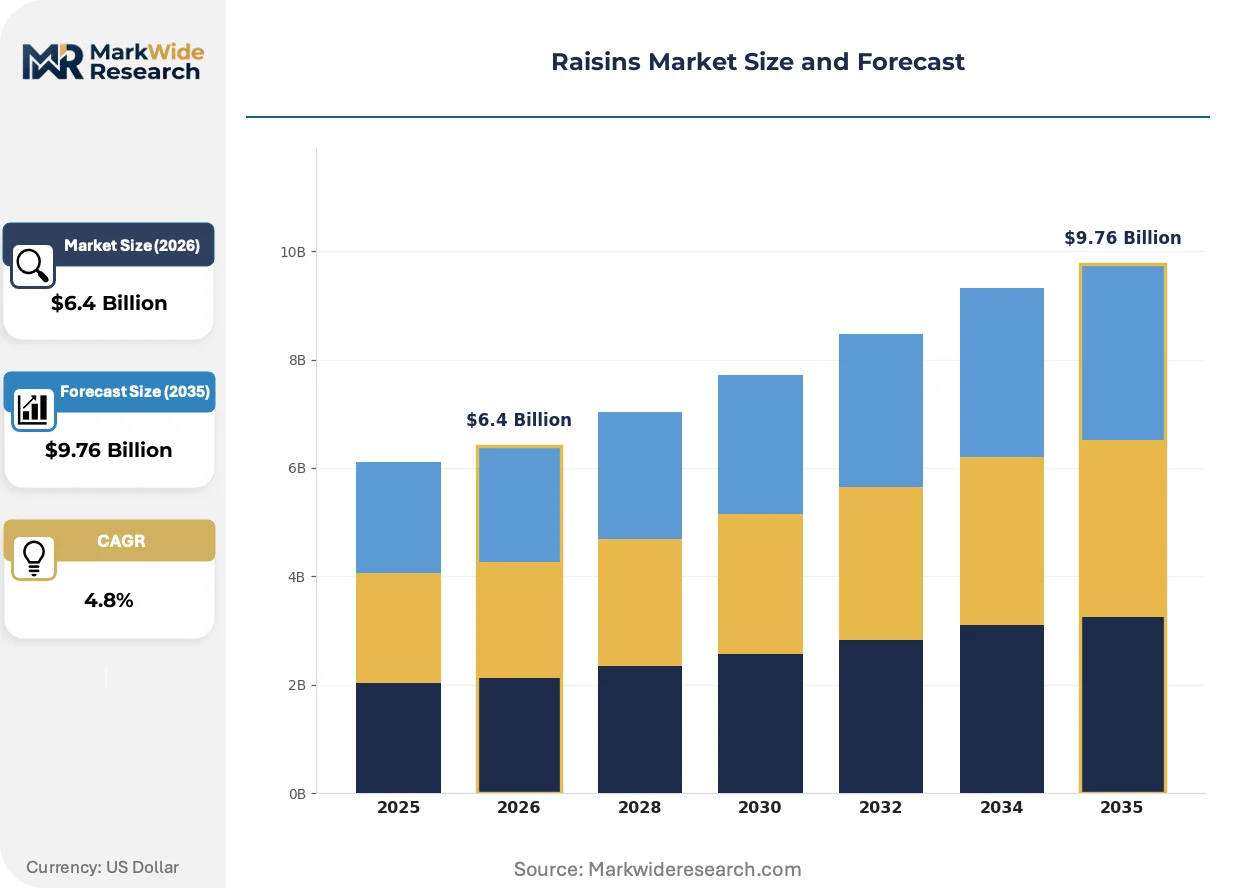
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sultanas, Thompson Seedless, Muscat, Flame Seedless, Golden, Black Corinth Packaging Type: Bulk Bags, Pouches, Clamshell Containers, Boxes, Vacuum Packs Application: Bakery, Confectionery, Breakfast Cereals, Snack Foods, Beverage Industry Customer Type: Food Manufacturers, Retail Chains, Wholesalers, Exporters, Foodservice Providers |
| Companies Covered | Mariani Packing Company, Made In Nature, Sun-Maid Growers of California, Olam International Limited, SunOpta, Dole Food Company, Bergin Fruit and Nut, Traina Foods, Del Monte Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Raisins Market Strategic Shifts & Innovations
Technology-driven quality improvements and stricter food safety regulations are converging with evolving consumer preferences for specific product attributes. This intersection is compelling growers and processors to enhance traceability and redefine quality standards across the supply chain.
High-speed optical sorting technology utilizes advanced cameras and sensors to identify and remove defects based on color, size, and foreign material. Large-scale processors are adopting this equipment to meet strict specifications from industrial food manufacturers and retailers. The proliferation of this technology is collapsing the quality variance between raisin grades, shifting competitive differentiation toward other attributes like origin or moisture control.
European Food Safety Authority (EFSA) regulations enforce stringent maximum levels for mycotoxins such as ochratoxin A in dried vine fruit. This framework requires comprehensive testing and process controls, effectively setting a high bar for market access into the EU. Producers targeting the European market are most impacted, investing heavily in post-harvest management and advanced sorting to ensure full compliance.
A notable behavioral shift involves consumers and industrial buyers moving from generic bulk purchasing towards products with specific, verifiable attributes. This pattern disrupts traditional commodity channels, favoring suppliers who can offer certified organic or sustainably sourced raisins with documented traceability. The trend is most visible in the health food and premium snack segments within North American and European markets.
Raisins Market Segmentation
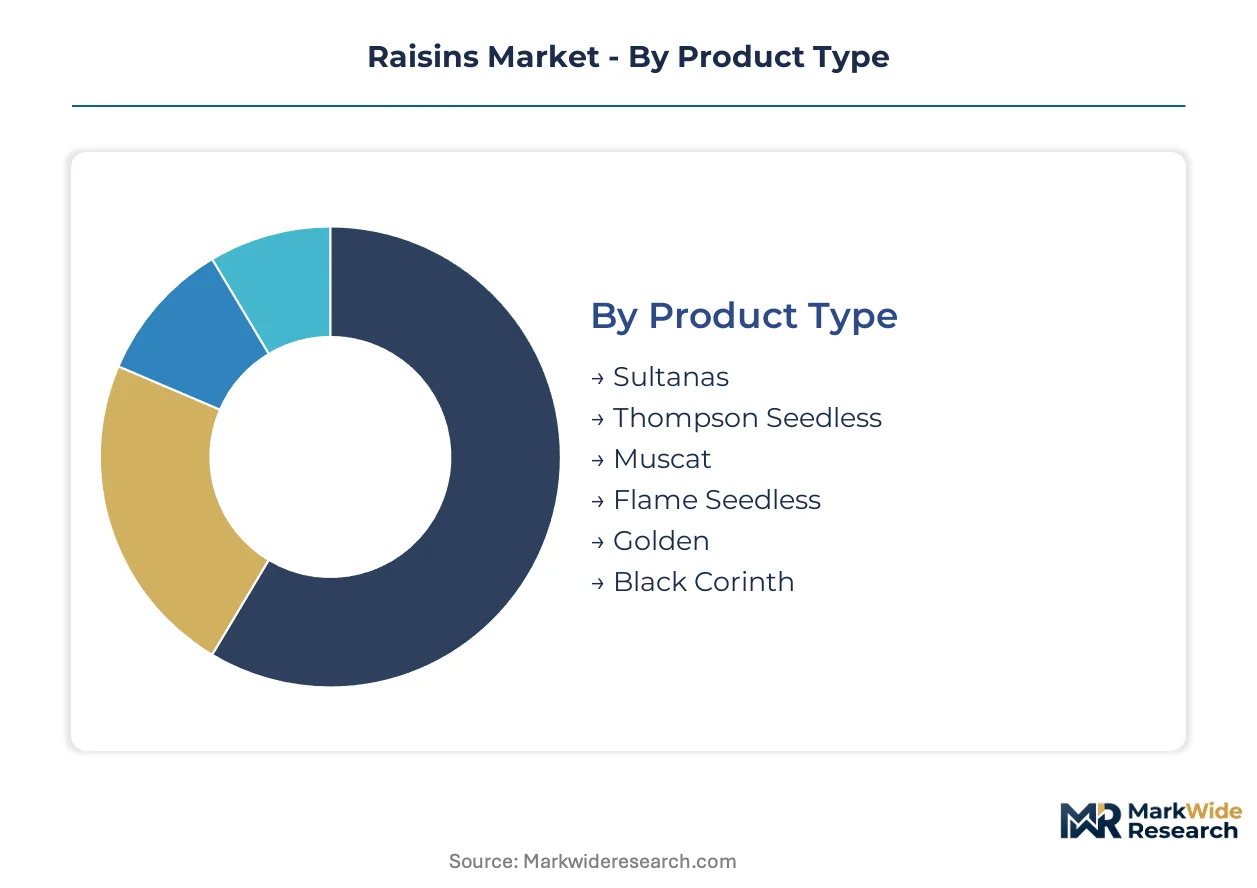
Segmentation reveals how different product forms, packaging, applications, and customer types interact within the raisin market. Understanding these divisions helps stakeholders identify specific growth vectors and address evolving consumer preferences. This detailed breakdown informs strategic decisions for producers and processors.
Product Type:
The volume of production and consumer preference primarily define the product type segmentation within the raisin market.
- Thompson Seedless:These small, oval, seedless grapes are dried to produce a versatile raisin widely used in various food applications. Demand concentrates in both snack foods and bakery segments due to their neutral flavor and consistent texture.
- Sultanas:These golden-colored, seedless raisins are often treated with a vegetable oil solution before drying, resulting in a lighter color and softer texture. Health-conscious consumers in Europe and North America drive demand for Sultanas in breakfast cereals and trail mixes.
- Muscat:These large, aromatic raisins retain a distinct grape flavor, often favored in gourmet baking and confectionery applications.
- Flame Seedless:Known for their dark red color and sweet taste, Flame Seedless raisins are popular in snack mixes and as a standalone treat.
- Golden:Processed with sulfur dioxide to maintain their light color, Golden raisins are valued for their aesthetic appeal in baked goods and salads.
- Black Corinth:Also known as Zante currants, these tiny, dark, tart raisins are used in specialty baked goods and savory dishes.
Thompson Seedless commands the established base. The steepest expansion runs through Sultanas.
Packaging Type:
Customer type and handling requirements dictate the various packaging formats adopted across the raisin supply chain.
- Bulk Bags:These large-capacity industrial packages, typically 25kg or more, facilitate efficient transport and storage for food manufacturers. Demand is concentrated among large-scale bakery and cereal producers requiring high volumes for ingredient integration.
- Pouches:Flexible, resealable bags offer convenience and portion control for consumers, protecting raisins from moisture and spoilage. Retail chains in the United States and Germany observe high demand for pouches in the snack food aisle.
- Clamshell Containers:Rigid, transparent plastic containers provide product visibility and protection, often used for premium or organic raisin offerings.
- Boxes:Traditional cardboard boxes remain a cost-effective option for both retail and smaller bulk sales, particularly in established markets.
- Vacuum Packs:Removing air from packaging extends shelf life and preserves freshness, primarily targeting export markets and specialty food segments.
Bulk Bags remain essential for industrial procurement. Pouches are gaining share fastest in direct-to-consumer sales.
Application:
The diverse functional roles and consumer trends determine the primary application segments for raisins.
- Snack Foods:Raisins are consumed directly as a healthy snack or incorporated into trail mixes, fruit bars, and nut blends. Health-conscious demographics in markets like the United States increasingly seek minimally processed, nutrient-dense options.
- Bakery:Used extensively in breads, muffins, cookies, and pastries, raisins contribute natural sweetness, moisture, and texture to baked goods. Food manufacturers procure large volumes for inclusion in their product lines, driven by consumer demand for natural ingredients.
- Confectionery:Raisins are coated in chocolate or yogurt, providing a natural fruit center for various candy and sweet treats.
- Breakfast Cereals:Raisins add natural sweetness and fiber to hot and cold breakfast cereals, appealing to health-focused consumers.
- Beverage Industry:Raisin extracts and concentrates find niche applications in specialty beverages, contributing flavor and natural sugars.
Bakery applications sustain consistent demand for raisins. The snack foods segment exhibits the fastest-growing trajectory.
Customer Type:
Procurement patterns and distribution channels delineate the customer type segmentation within the raisin market.
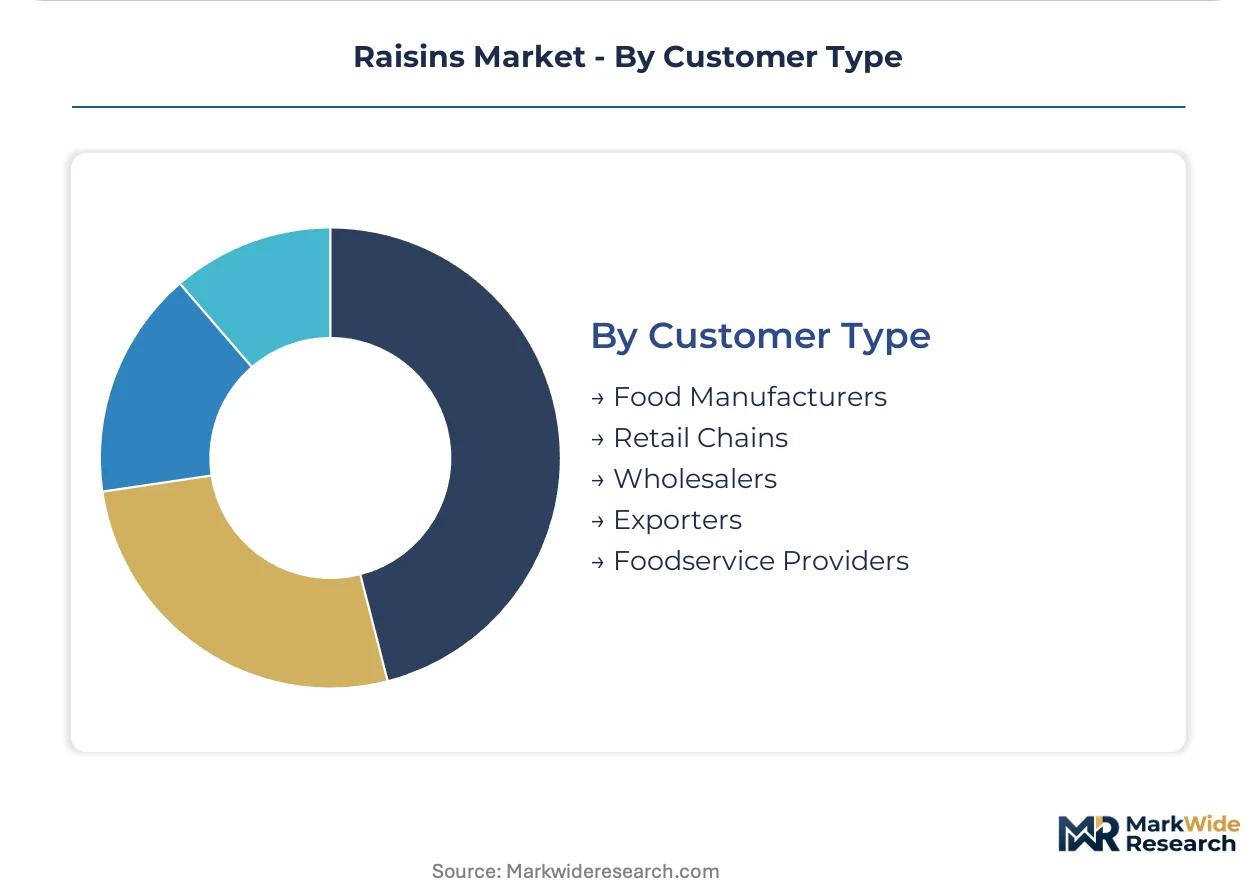
- Food Manufacturers:These entities purchase large volumes of raisins as ingredients for processed foods, including cereals, snack bars, and baked goods. Their demand is driven by product formulation requirements and consumer preference for natural additives.
- Retail Chains:Supermarkets, hypermarkets, and convenience stores stock packaged raisins for direct consumer purchase, catering to household consumption. Health-conscious consumers in Germany and the United States frequently drive retail sales for nutrient-dense snacks.
- Wholesalers:These intermediaries distribute raisins in bulk to smaller food businesses, independent retailers, and institutional buyers.
- Exporters:Companies specializing in international trade facilitate the movement of raisins from producing regions to global markets, managing logistics and compliance.
- Foodservice Providers:Restaurants, cafes, and catering companies utilize raisins in various culinary preparations, from desserts to savory dishes.
Food Manufacturers represent the largest volume buyers. Retail Chains are experiencing the most dynamic growth in consumer-facing sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumer demographics drive demand across key geographies, influencing regional procurement patterns. The concentrated buyer archetypes in North America and Europe specifically seek nutrient-dense snack options. Asia-Pacific markets represent a significant growth frontier, fueled by increasing disposable incomes and evolving dietary preferences.
United States
Consumer demand for natural, minimally processed snacks boosts retail sales for raisins. USDA grading standards define quality parameters for domestic and imported products. California remains the dominant production region, with growers focusing on advanced water management strategies to maintain yields.
Germany
Health-focused consumers drive retail demand for nutrient-dense snacks like raisins. EFSA regulations on contaminants, such as ochratoxin A, impose strict import controls. Major food manufacturers in cities like Hamburg procure large volumes for their bakery and breakfast cereal lines.
Turkey
Turkey is a significant global producer, with strong export volumes to European markets. The Turkish Ministry of Agriculture and Forestry oversees quality and export standards. Production concentrates in the Aegean region, especially around Izmir, where sun-drying methods are prevalent.
India
Rising middle-class incomes and Western snacking trends accelerate demand for natural food products. The Food Safety and Standards Authority of India (FSSAI) regulates food quality and safety. Nashik in Maharashtra stands as a major processing hub, handling large volumes for domestic consumption.
China
Evolving dietary habits and a preference for natural ingredients stimulate the market for dried fruits. China's General Administration of Customs (GACC) sets import and export regulations. Xinjiang province is the primary production area, known for its extensive grape cultivation and drying facilities.
Raisins Market Key Industry Players
Channel-controlling players compete with product-specialist players across the raisin market. The industry exhibits a tiered structure, with large-scale processors alongside niche organic producers. Dominant competitive moves include geographic expansion into high-growth consumer markets and continuous investment in optical sorting technology.
Scale-driven processors like Olam International Limited leverage extensive global sourcing and logistics infrastructure. Sun-Maid Growers of California represents a vertically integrated model, benefiting from its established grower network and strong brand recognition in retail channels. Mariani Packing Company exemplifies a product-differentiated strategy, focusing on both conventional and organic product lines for private label and branded sales.
| Leading Market Players |
|---|
| Mariani Packing Company |
| Made In Nature |
| Sun-Maid Growers of California |
| Olam International Limited |
| SunOpta |
| Dole Food Company |
| Bergin Fruit and Nut |
| Traina Foods |
| Del Monte Foods |
| Others |
Cost & Logistics Intelligence
Seasonal oversupply from key producing regions like Turkey and California influences global raisin prices. This capacity utilization directly impacts grower profitability and processor inventory strategies.
Pricing Analysis
Cost-plus contract patterns, often indexed to global commodity prices, define pricing for bulk raisin procurement. Price differentiation stems from quality grade, adhering to USDA or EFSA standards, and specific certifications like organic or fair-trade status. Pricing softness reflects competition from other dried fruits and processed sweeteners. Food manufacturers exhibit high price sensitivity for conventional bulk volumes, while ethically-minded consumers show less sensitivity for premium certified products.
Supply Chain Analysis
Upstream grape cultivation in California, Turkey, and India forms the foundation of the global raisin supply chain. This production relies heavily on water management strategies and agricultural labor. Supply chain vulnerability arises from localized weather events in these climate-sensitive regions. Distribution runs through large-scale wholesalers and exporters for industrial buyers, while retail channels increasingly feature direct-to-consumer packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The raisin market increasingly reflects a buyer-power shift, driven by the consolidation of large food manufacturers and retail chains. These buyers demand stringent quality and traceability, reshaping supplier strategies.
For Market Incumbents:Entrench market position by deepening backward integration into grape cultivation, securing long-term supply agreements with growers. Invest in advanced optical sorting technology to consistently meet strict international quality standards, mitigating the threat from contaminant regulations. Expand branded product lines in health-conscious consumer segments to counter ingredient substitution pressure. Control over the supply chain and brand recognition remain critical levers.
For New Entrants and Emerging Players:Pursue niche opportunities in premium certified segments like organic or fair-trade, targeting ethically-minded consumers in Europe. Focus on product formulation innovation, developing raisin pastes for plant-based food applications. The Asia-Pacific market represents the most penetrable geography for natural snack products. A direct-to-consumer e-commerce model can establish brand presence efficiently.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among processors with strong brand equity and direct retail channel access. Long-term viability favors entities capable of navigating climate risks and regulatory complexities. Seek acquisition targets possessing advanced processing capabilities or established organic product lines. The signal to watch is the increasing adoption of water-saving agricultural technologies by growers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Optical Sorting | Reduces quality variance across raisin grades, meeting strict specifications from industrial food manufacturers. |
| Develop Organic and Fair-Trade Product Lines | Captures value from ethically-minded consumers in European and North American premium snack segments. |
| Expand into Asia-Pacific Markets | Addresses evolving dietary preferences and rising middle-class demand for natural food products in Southeast Asia. |
| Diversify Product Formulations | Creates new industrial uses for raisins as binders in savory and plant-based food applications. |
| Implement Drip Irrigation Technology | Maintains grape crop yields in arid regions, mitigating climate-related supply chain risks for growers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, validated by extensive secondary research. Stakeholders included food manufacturers' procurement leads, retail category managers, agricultural extension experts, and logistics providers. Secondary data sources comprised USDA and EFSA regulatory documents, trade association reports, and company annual filings. This approach ensured robust bottom-up and top-down triangulation of market data.
The calibration approach integrated historical market performance with projected growth trajectories across the analysis window. Segmentation dimensions modeled included product type, application, packaging type, customer type, and regional consumption patterns. Compound Annual Growth Rates were derived from a regression analysis of market drivers and restraints. Key forecast inputs included global grape harvest volumes and consumer spending on snack foods.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large-scale processors or new market entrants would shift outcomes. Forecasts reflect assumptions regarding climate stability and labor availability, which present significant risks. Cross-checking against international trade data and agricultural output reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Guava Puree Market