
 Global Papaya Puree Market | 2026-2036
Global Papaya Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Global Papaya Puree Market Outlook
Multi-source procurement from tropical contract farms is expanding as beverage and baby food manufacturers diversify supply away from single-origin dependencies. Dohler Group leverages its ingredient technology platform to sustain long-term contracts with plantation cooperatives across India and Brazil. Nestlé S.A. anchors its puree sourcing through backward integration into Central American processing facilities. ABC Fruits competes on aseptic packaging scale, while Shimla Hills Offerings Pvt. Ltd. differentiates through organic certification depth.
Papaya puree is a smooth, homogenized fruit preparation typically processed from Carica papaya pulp with controlled Brix levels between 12 and 18 degrees, pasteurized or aseptically packed for industrial food manufacturing. It functions primarily as a natural sweetener, colorant, and flavor base in beverages, infant foods, and confectionery applications. The organic product type commands premium positioning as clean-label formulations displace conventional alternatives in European and North American retail channels. Beverage applications lead volume consumption, while bakery and sauces segments capture higher margin pools through specialized viscosity grades and customized acidity profiles.
FDA enforcement of the Food Safety Modernization Act shapes import requirements for foreign puree suppliers entering United States distribution. EU organic labeling regulations and EFSA contaminant thresholds determine market access for Indian and Mexican exporters. India's FSSAI fortification guidelines and BIS processing standards influence domestic quality benchmarks that ripple through export-oriented supply chains. Stakeholders must monitor how dual carbon goals in China and evolving pesticide maximum residue limits across importing jurisdictions reshape cultivation and processing investment priorities.
Market Dynamics
EU organic labeling regulations are tightening ingredient traceability requirements, forcing infant nutrition manufacturers to restructure procurement relationships and pushing supply chain control deeper into Mexican and Indian growing belts.
Growth Catalysts
- Clean-label beverage reformulation:North American juice and smoothie brands are replacing artificial colorants with papaya puree as a natural orange-pink hue source, expanding industrial volume offtake.
- FDA Food Safety Modernization Act enforcement:Stricter import documentation for foreign puree suppliers is advantaging aseptically packed products with validated kill-step records over conventional alternatives.
- Irrigation modernization in Colima:Drip-system upgrades across Mexican contract farms are reducing post-harvest microbial contamination, improving lot consistency for export-oriented processing clusters.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings in tropical growing regions compress processor margins during contract renegotiation windows.
- Supply concentration risk:Heavy reliance on monsoon-dependent Indian harvests creates volume uncertainty for European buyers during El Niño cycles.
- Technical limitation in viscosity stability:Enzymatic browning in long-shelf ambient storage restricts papaya puree adoption in certain confectionery applications.
Strategic Opportunities
- Underpenetrated bakery segment:Specialized viscosity grades for cake fillings and glazes remain undersupplied relative to beverage applications, offering margin expansion potential.
- China dual carbon goals:Carbon-neutral processing incentives are creating entry pathways for solar-powered puree facilities with verified emission reductions.
- Direct-to-manufacturer e-procurement platforms:Digital sourcing channels are compressing distributor layers, enabling mid-sized processors to access institutional buyers previously gated by volume minimums.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods for conventional farmland strain supply continuity for brands racing to meet EU organic labeling deadlines.
- Aseptic packaging capex intensity:Tetra Pak and bag-in-drum filling lines require seven-figure capital commitments that exclude smaller cooperatives from premium contract pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Papaya Puree Market |
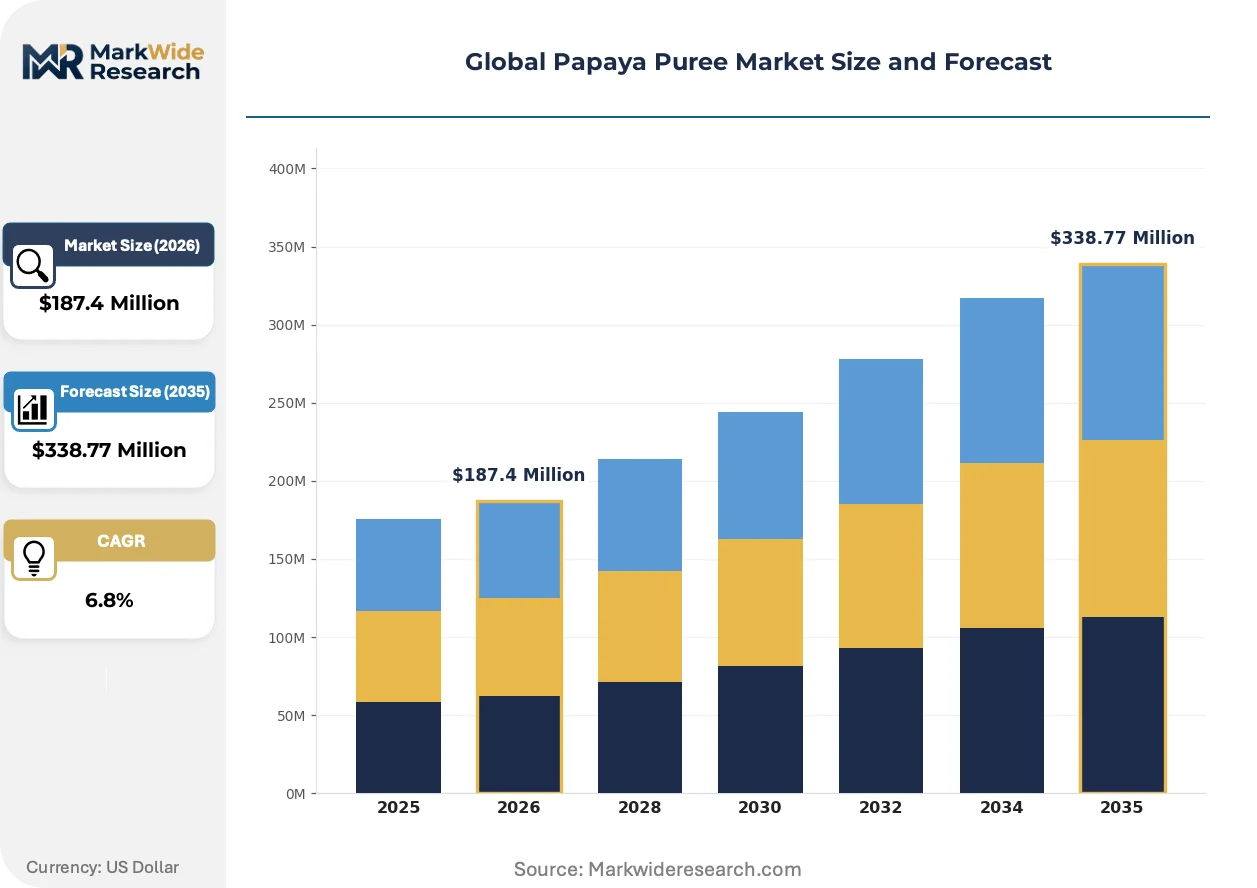
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Frozen, Fresh Application: Bakery, Beverages, Jams, Sauces End User: Food Industry, Catering Services, Retailers, Households Packaging Type: Tetra Packs, Glass Jars, Bottles, Pouches |
| Companies Covered | Nestlé S.A., The Kraft Heinz Company, Dohler Group, Shimla Hills Offerings Pvt. Ltd., Galla Foods, ABC Fruits, Jain Irrigation Systems Ltd., Allanasons Pvt Ltd, Ariza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Papaya Puree Market Strategic Shifts
Processing technology and procurement models are converging to reshape competitive positioning in papaya puree supply chains, with sustainability verification and digital traceability emerging as non-negotiable buyer requirements.
High-pressure processing is overtaking conventional thermal pasteurization for premium organic lines, preserving heat-sensitive vitamin content and native enzyme activity. Infant formula manufacturers in Germany and the United States are specifying HPP-treated puree for clean-label positioning, compressing demand for standard aseptic alternatives in the premium tier.
EU Green Deal farm-to-fork traceability mandates are requiring blockchain-linked documentation from tropical suppliers, with EFSA contaminant thresholds now enforced through digital lot tracking rather than spot-testing alone. Indian and Mexican exporters are retrofitting processing facilities with integrated data-capture systems to maintain market access, with compliance costs filtering smaller operators from EU-bound supply chains.
Ingredient buyers are consolidating supplier relationships around multi-year framework agreements with embedded sustainability audits, displacing spot-market purchasing for core volume requirements. Beverage manufacturers in North America are locking three-to-five-year contracts with plantation cooperatives to secure organic-certified supply, with price volatility risk transferred to processors through fixed-base, variable-premium structures.
Global Papaya Puree Market Segmentation
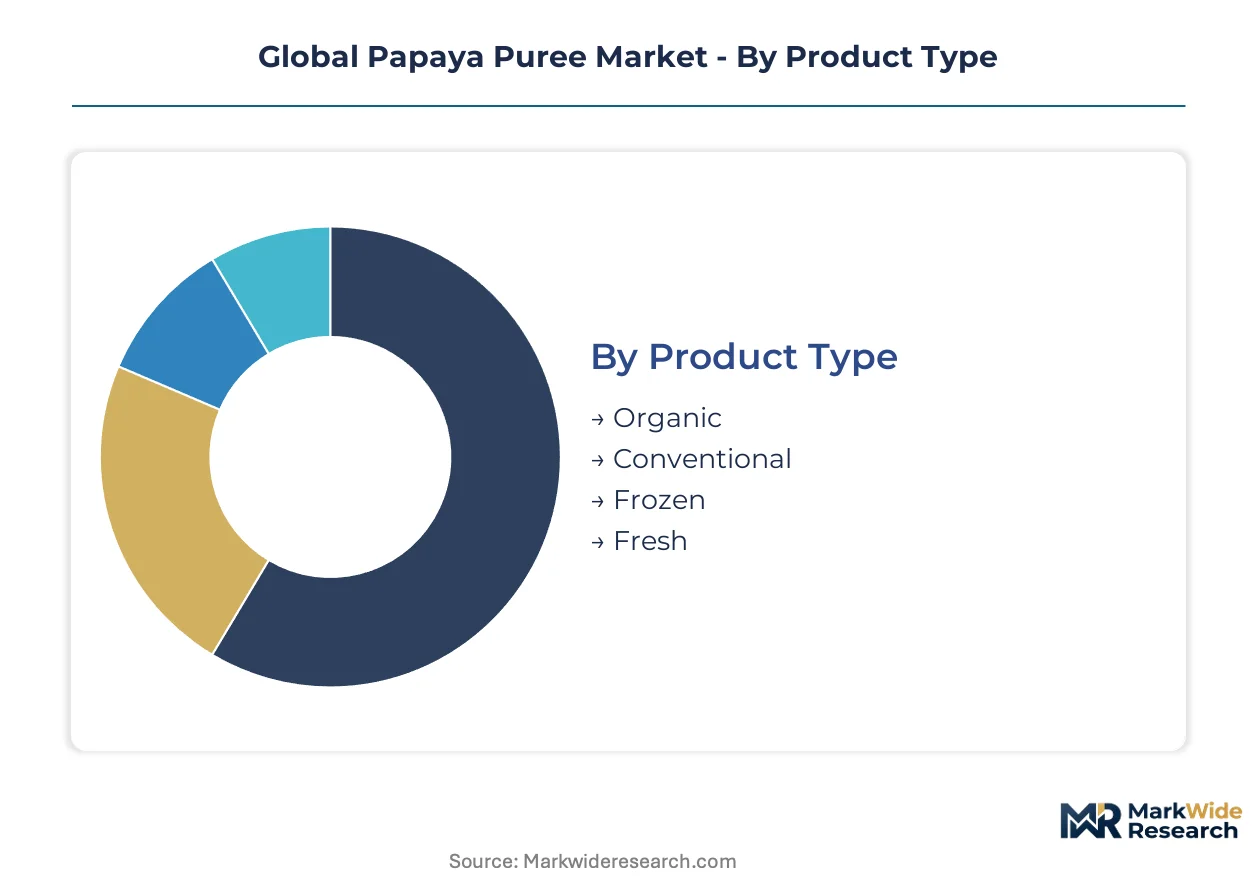
Papaya puree buyers segment procurement by certification grade, viscosity specification, and shelf-life requirements. Manufacturers configure production lines around these distinctions to capture margin pools in infant nutrition, beverage, and industrial food channels.
Product Type:
Certification depth separates segments that command standalone premium positioning from those embedded as commodity inputs in processed foods.
- Organic:Farm-to-fork traceability documentation meets EU organic labeling regulations and EFSA contaminant thresholds. German and US infant nutrition manufacturers specify this grade for clean-label formulations, absorbing three-year farmland conversion timelines into contract pricing.
- Conventional:Standard pasteurization without certification overlay serves high-volume beverage applications where colorant replacement drives procurement. Mexican processors in Colima and Veracruz anchor export supply for this tier.
- Frozen:Blast-frozen pulp at minus eighteen degrees Celsius preserves enzyme activity for industrial bakery applications requiring controlled thaw behavior.
- Fresh:Refrigerated distribution with seven-day shelf life supplies foodservice channels and regional dairy processors in India and Brazil.
Conventional leads volumes today; organic is gaining share fastest.
Application:
End-use viscosity requirements and acidity profiles dictate processing investment and contract minimums across manufacturing customers.
- Beverages:Standardized Brix levels between twelve and eighteen degrees serve juice, smoothie, and functional drink formulations. North American brands specify this segment for natural orange-pink hue replacement of artificial colorants.
- Bakery:Specialized viscosity grades for cake fillings and glazes command premium positioning through customized pectin content and water-binding capacity.
- Jams:High-solids formulations with controlled sugar-acid ratios target spreadable consistency in artisanal and industrial production lines.
- Sauces:Low-acid variants for savory applications require adjusted thermal processing to meet FDA Food Safety Modernization Act kill-step documentation.
Beverage applications dominate volume; bakery captures the steepest margin expansion trajectory.
End User:
Customer scale and specification stringency create tiered procurement relationships from spot-market foodservice to multi-year framework agreements.
- Food Industry:Large-scale manufacturers of infant formula, beverages, and confectionery drive bulk contract structures with embedded sustainability audits.
- Catering Services:Foodservice distributors purchase frozen and fresh grades in pallet quantities with seasonal demand fluctuation.
- Retailers:Private-label grocery chains specify aseptic packaging formats for shelf-stable puree lines in organic and conventional tiers.
- Households:Direct-to-consumer channels through e-procurement platforms serve small-batch buyers previously excluded by volume minimums.
Food industry procurement anchors contract volumes; retailer private-label expansion is climbing the fastest.
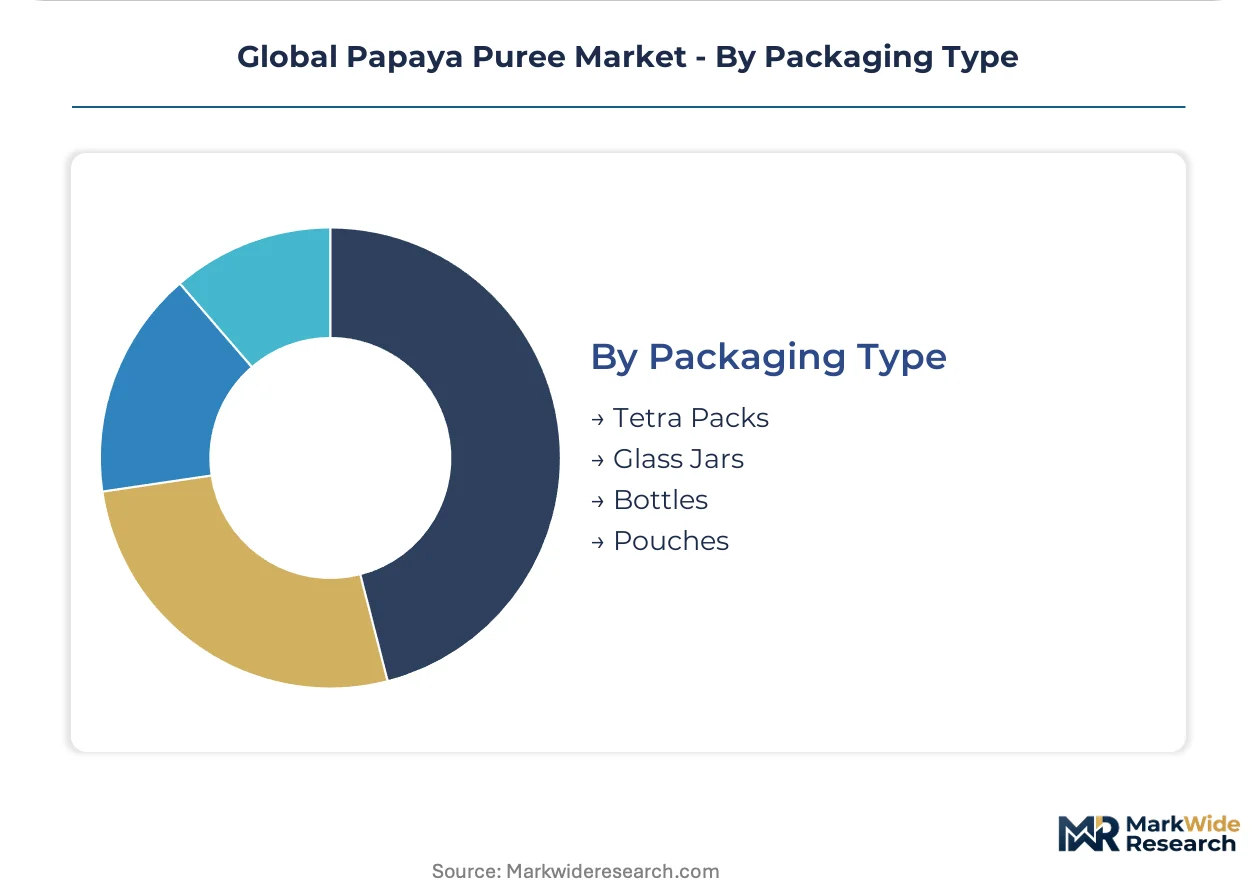
Packaging Type:
Capital intensity and shelf-life extension separate formats accessible to cooperatives from those requiring seven-figure filling line investments.
- Tetra Packs:Aseptic carton systems enable twelve-month ambient shelf life for export-oriented supply chains serving EU and North American buyers.
- Glass Jars:Hot-fill pasteurization in transparent containers targets premium retail positioning with visible color quality assurance.
- Bottles:PET and HDPE formats with tamper-evident closures serve foodservice dispensing and industrial bulk transfer.
- Pouches:Flexible spouted formats reduce shipping cube for e-commerce distribution and single-serve household consumption.
Tetra Pack aseptic formats lead industrial volumes; pouch formats are expanding most quickly in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting papaya puree production toward jurisdictions where compliance costs remain manageable while export access stays intact. Mexico and India capture volume migration from higher-cost origins as EU organic traceability mandates intensify.
Mexico
Infant formula manufacturers in the United States and Germany source heavily from Colima and Veracruz growing belts. The country's national agricultural regulator enforces export-grade phytosanitary certification aligned with FDA Food Safety Modernization Act documentation requirements. Irrigation modernization clusters around Tecomán, Colima are reducing post-harvest microbial loads for aseptic processing lines.
India
Beverage and confectionery buyers in Europe specify Indian organic puree for clean-label formulations. FSSAI fortification guidelines and BIS processing standards shape domestic quality benchmarks that propagate through export supply chains. Contract farming networks in Maharashtra and Karnataka are retrofitting facilities with blockchain-linked traceability systems for EU Green Deal compliance.
United States
Domestic beverage brands drive demand for natural colorant replacement in juice and smoothie formulations. FDA enforcement of import documentation requirements advantages aseptically packed products with validated kill-step records over conventional alternatives. California-based ingredient distributors are consolidating procurement relationships around multi-year framework agreements with embedded sustainability audits.
Germany
Organic infant nutrition manufacturers anchor European demand for farm-to-fork traceable puree. EU organic labeling regulations and EFSA contaminant thresholds determine market access for tropical suppliers. Processing technology providers near Hamburg are deploying high-pressure processing systems for premium organic lines serving clean-label formulations.
Brazil
Industrial food manufacturers in South America and Europe source conventional puree for high-volume beverage applications. The national health surveillance agency enforces processing standards that align with Mercosur trade bloc requirements and EU import protocols. Northeastern growing regions around Bahia are expanding export-oriented processing capacity for North American and European buyers.
Global Papaya Puree Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue organic certification depth and aseptic packaging scale as differentiation vectors. The market structures around three tiers: multinational food conglomerates with backward integration into Central American processing, mid-scale regional processors competing on certification breadth, and cooperative-based suppliers concentrated in Indian and Mexican growing belts. Dominant competitive moves include multi-year procurement framework agreements with embedded sustainability audits and capital deployment into high-pressure processing technology for premium organic lines.
Within the multinational tier, Nestlé S.A. and The Kraft Heinz Company exemplify archetypes of downstream brand owners with captive supply chain control. Among specialized ingredient technology platforms, Dohler Group occupies a position representing the contract-manufacturing archetype serving beverage and confectionery formulators. At the India-based processing end, Shimla Hills Offerings Pvt. Ltd. and ABC Fruits sit within competitive territory defined by organic certification depth versus aseptic packaging scale.
| Leading Market Players |
|---|
| Nestlé S.A. |
| The Kraft Heinz Company |
| Dohler Group |
| Shimla Hills Offerings Pvt. Ltd. |
| Galla Foods |
| ABC Fruits |
| Jain Irrigation Systems Ltd. |
| Allanasons Pvt Ltd |
| Ariza |
| Others |
Value Chain & Pricing Dynamics
Specialized aseptic packaging technicians concentrated in Colima, Veracruz, and Maharashtra drive labor-cost differentials that widen spreads between premium organic and conventional puree tiers, with EU-bound organic lines absorbing three-year farmland conversion premiums while beverage-grade conventional supply competes on volume scale.
Pricing Analysis
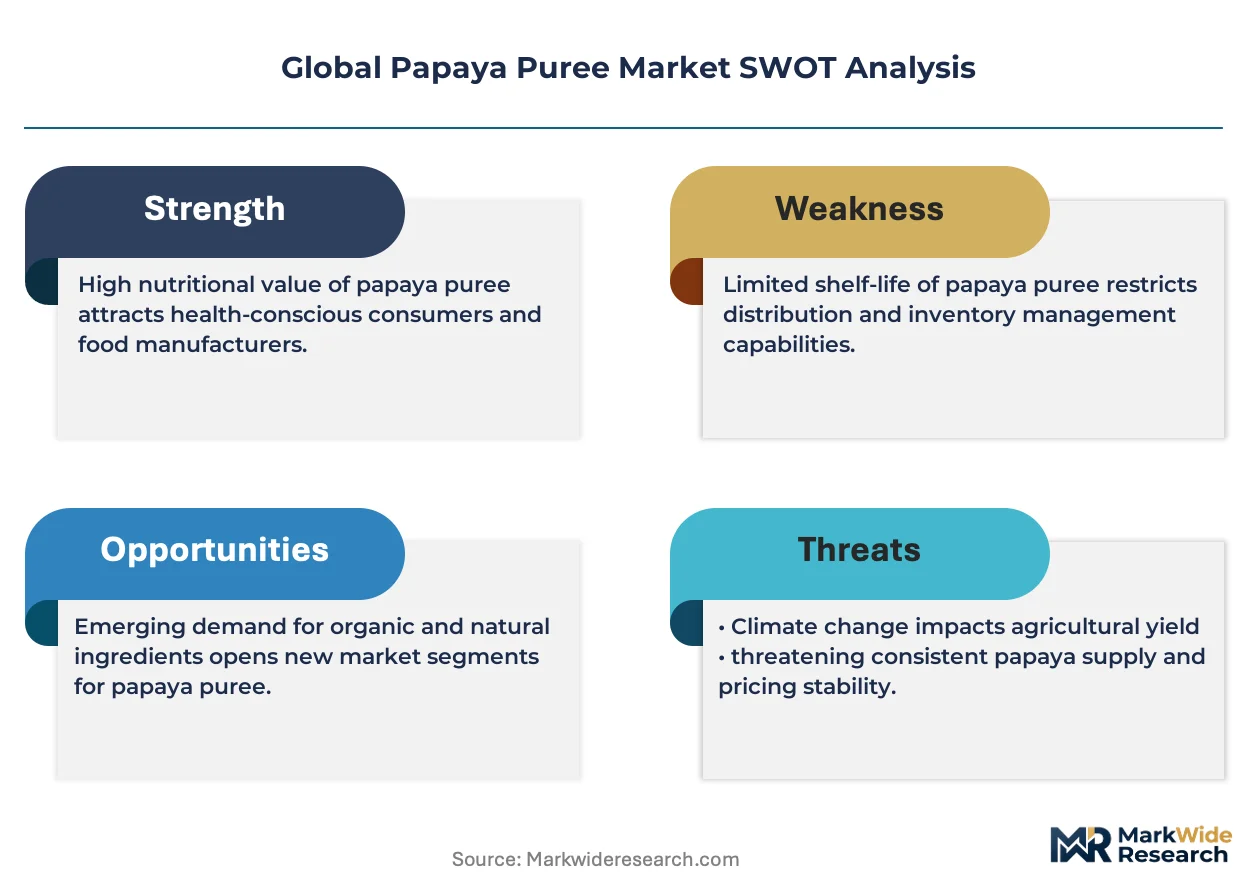
Distributor margin compression in North American and European channels is reshaping contract structures toward direct-to-manufacturer procurement. Three-tier pricing structure across premium organic, standard aseptic, and economy frozen levels separates EU-certified infant nutrition supply from beverage colorant replacement volumes. Pricing pressure stems from fertilizer and fuel volatility in tropical growing regions, with food industry buyers least sensitive due to multi-year framework agreements and retailer private-label segments most exposed to spot-market swings.
Supply Chain Analysis
Workforce availability for high-pressure processing and blockchain-linked traceability systems concentrates in Maharashtra, Karnataka, and Colima, constraining premium organic capacity expansion. Raw material flows draw from Carica papaya plantations, aseptic packaging substrates, and organic certification audit services. Single-source vulnerability runs through monsoon-dependent Indian harvests exposed to El Niño disruption. Distribution runs through plantation cooperative networks into export-oriented processing clusters, then onward to ingredient distributors and direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through clean-label premium tier shifts as infant nutrition manufacturers absorb organic certification premiums and high-pressure processing technology unlocks vitamin-preservation value capture.
For Market Incumbents: Acquire aseptic packaging capacity in Colima and Veracruz to anchor North American supply security against emerging Indian organic competitors. Secure backward integration into drip-irrigation plantation networks to control microbial load consistency and reduce post-harvest contamination risk. Lock multi-year framework agreements with embedded sustainability audits before EU Green Deal traceability mandates filter smaller operators from premium contract pools.
For New Entrants and Emerging Players: Enter via specialized viscosity grades for bakery cake fillings and glazes, the most penetrable segment where beverage-grade oversupply has not compressed margins. Target direct-to-manufacturer e-procurement channels to bypass distributor volume minimums that previously gated mid-sized processors. Lead with solar-powered processing facilities aligned with China dual carbon goals to differentiate in carbon-neutral ingredient sourcing.
For Investors and Strategic Acquirers: Beverage and infant nutrition conglomerates are the most active acquirer in this space, consolidating cooperative networks for captive organic supply. Long-term viability centers on traceability infrastructure ownership and HPP technology deployment rather than commodity processing scale. Watch FDA enforcement intensity on Food Safety Modernization Act import documentation as the inflection signal for aseptic packaging premium expansion versus conventional pasteurization compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Networks | Nestlé and Kraft Heinz control Central American processing facilities to secure FDA-compliant kill-step documentation. |
| High-Pressure Processing Technology Deployment | German infant formula manufacturers specify HPP-treated puree for clean-label vitamin preservation claims. |
| Blockchain-Linked Traceability Retrofit | Indian exporters in Maharashtra integrate EU Green Deal farm-to-fork data capture to maintain market access. |
| Direct-to-Manufacturer E-Procurement Launch | Digital sourcing platforms compress distributor layers for mid-sized processors previously excluded by volume minimums. |
| Organic Certification Pipeline Investment | Three-year farmland conversion timelines strain supply continuity for brands racing to meet EU organic labeling deadlines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plantation cooperative managers, aseptic processing line engineers, infant nutrition procurement directors, and beverage brand formulation leads with secondary validation from FDA import refusal data, EU organic certification registries, FSSAI fortification guidelines, and BIS processing standards. Bottom-up volume modeling from export-oriented processing clusters in Colima, Veracruz, Maharashtra, and Karnataka triangulated against top-down demand estimates from North American and European ingredient distributors.
Historical reference periods anchored the projection horizon through verified production volumes and trade flow patterns across the analysis window. Segmentation dimensions modeled include certification grade, viscosity specification, packaging format, and end-use application channel. CAGRs derived from compound growth trajectory analysis incorporating irrigation modernization investment cycles, EU organic labeling regulatory phase-in schedules, and El Niño frequency patterns affecting Indian monsoon-dependent harvests.
Inputs from plantation cooperative disclosures and export processing facility records were available through the study window; gaps in real-time blockchain traceability adoption rates introduce uncertainty bands around premium organic supply forecasts. Material deviation in FDA Food Safety Modernization Act enforcement intensity or EU EFSA contaminant threshold revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Global Fresh Berries Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Fermented Cucumber Market