
 Cranberries Market | 2026-2036
Cranberries Market Size, Share, and Industry Trends Forecast 2026-2036
Cranberries Market Analysis
The FDA's updated Nutrition Facts labeling requirements is repositioning cost structures across cranberry processing, forcing reformulation investments that favor scaled operators. Ocean Spray Cranberries, Inc. leverages its cooperative structure to sustain year-round supply contracts with major retailers. Decas Cranberry Products, Inc. anchors its position through deep control over Massachusetts and New Jersey bogs. Fruit d'Or differentiates via organic certification density and European export channel specialization.
Cranberries are Vaccinium macrocarpon berries harvested from low-trailing evergreen shrubs in acidic bogs, containing proanthocyanidins that deliver shelf-stable natural preservation and urinary tract health functionality. The fruit serves food and beverage processors seeking clean-label colorants, acidulants, and antioxidant systems. Dried cranberries occupy the largest volume position within product type segmentation, though cranberry juice concentrates command superior per-unit margins in functional beverage applications. Dietary supplements represent the fastest-expanding end-use channel as standardized extract demand accelerates from nutraceutical brands.
The USDA enforces grading standards for fresh and processed cranberries that determine export eligibility and price tier placement, while the EPA regulates bog water discharge under Clean Water Act provisions that constrain expansion geography. Health Canada and EFSA both maintain active health claim review processes for cranberry proanthocyanidin content, creating asynchronous market access timelines. Stakeholders must monitor pending organic certification rule changes and dual carbon policy implementations in major producing jurisdictions to anticipate input cost trajectories.
Market Dynamics
Clean-label reformulation mandates from the FDA are compressing processor margins while concentrating procurement power among cooperative growers capable of year-round supply continuity. This regulatory pressure is restructuring competitive advantage toward scaled operators with backward integration into bog operations.
Growth Catalysts
- Functional beverage expansion:North American processors are elevating cranberry inclusion rates in immunity-positioned drinks as proanthocyanidin standardization improves. Clean-label demand from millennial and Gen-Z cohorts accelerates this channel pull.
- USDA grading alignment:Export eligibility tiering under federal standards is rewarding quality-density investments with premium price realization in European and Asian destination markets. This creates incentive for grading infrastructure modernization.
- Proanthocyanidin extraction advancement:Ultrafiltration concentration technology is improving PAC yield rates from press cake, transforming former waste streams into high-margin nutraceutical inputs. Massachusetts and Wisconsin processors lead adoption curves.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings tied to natural gas benchmarks create margin unpredictability for bog operators without forward-contract hedging programs. This cost structure pressure favors cooperative pooling arrangements.
- Supply concentration risk:Wisconsin and Massachusetts together account for the dominant share of North American output, exposing buyers to regional weather anomalies and concentrated disease pressure from monoculture practices.
- Substitution threat:Tart cherry and pomegranate extracts with comparable antioxidant positioning are capturing shelf space in supplement formulations, pressuring cranberry extract pricing in standardized PAC categories.
Strategic Opportunities
- Organic certification white space:USDA National Organic Program rule revisions are expanding eligible bog acreage, creating first-mover advantage for growers converting marginal land ahead of 2027 compliance deadlines.
- Direct-to-brand nutraceutical supply:Bypassing traditional ingredient distributors to contract directly with supplement brands enables PAC standardization co-development and multi-year offtake security.
- IRA clean energy incentives:Solar array deployment on bog peripheries qualifies for federal tax credits while reducing operational energy costs for cold storage and processing facilities.
Industry Challenges
- Skilled bog management scarcity:Water table engineering expertise and integrated pest management specialization are aging out of the workforce faster than agricultural extension programs can replenish pipelines.
- Dual carbon policy complexity:Wisconsin state climate targets and federal methane monitoring requirements are imposing overlapping reporting burdens without harmonized measurement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranberries Market |
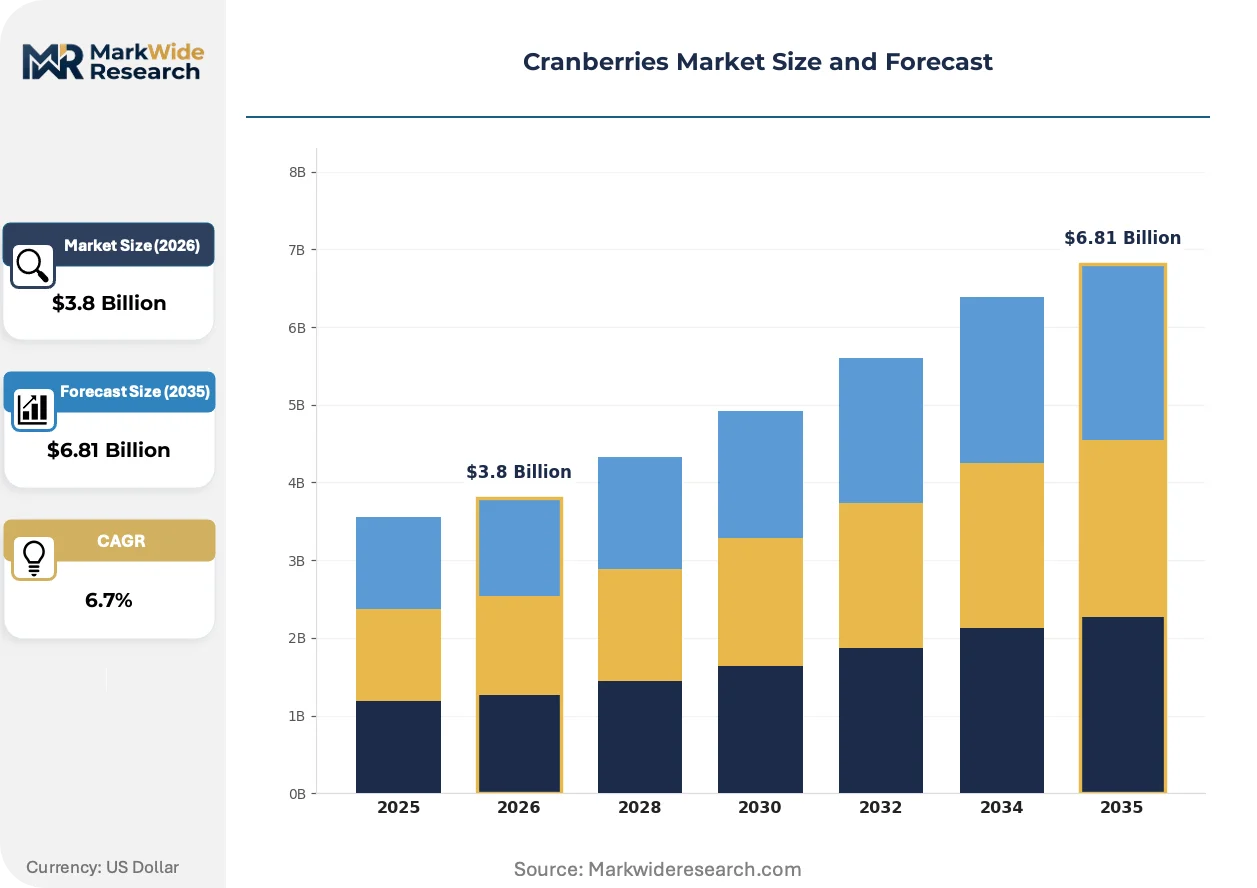
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Cranberries, Dried Cranberries, Cranberry Juice, Cranberry Sauce End Use: Food & Beverage, Dietary Supplements, Cosmetics, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales Packaging Type: Bottles, Packs, Jars, Bulk Containers |
| Companies Covered | Ocean Spray Cranberries, Inc., Graceland Fruit, Inc., Decas Cranberry Products, Inc., Fruit d'Or, Cape Blanco Cranberries, Inc., Atoka Cranberries, Mariani Packing Company, Inc., The Wonderful Company, Cape Cod Select, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranberries Market Emerging Trajectories
Processing technology and regulatory compliance systems are converging to reshape how cranberry value moves from bog to finished goods, with particular pressure on sugar reduction and extraction efficiency.
Membrane filtration concentration systems are absorbing capital allocation from traditional evaporative processing, reducing thermal degradation of heat-sensitive proanthocyanidins while cutting energy inputs by half. Functional beverage manufacturers in the United States are specifying membrane-concentrate feedstocks for premium positioning. This technology diffusion is compressing competitive differentiation formerly held by proprietary extraction patents.
EPA Clean Water Act discharge permits are tightening allowable phosphorus and nitrogen runoff thresholds from Massachusetts and New Jersey bog operations, forcing capital deployment into constructed wetland buffer systems. Processors with grandfathered permits face steeper compliance timelines than greenfield entrants. The regulatory friction is concentrating expansion interest in Wisconsin, where state-level water quality trading programs offer flexibility mechanisms.
Retailer private-label procurement is consolidating formerly fragmented ingredient buying, with mass-market chains now demanding PAC-standardized cranberry powders with certificate-of-analysis documentation per lot. This specification tightening is displacing commodity-grade dried fruit suppliers from premium shelf placements. The channel shift is most visible in United States natural and conventional grocery, where clean-label requirements intersect with scale purchasing leverage.
Cranberries Market Segmentation
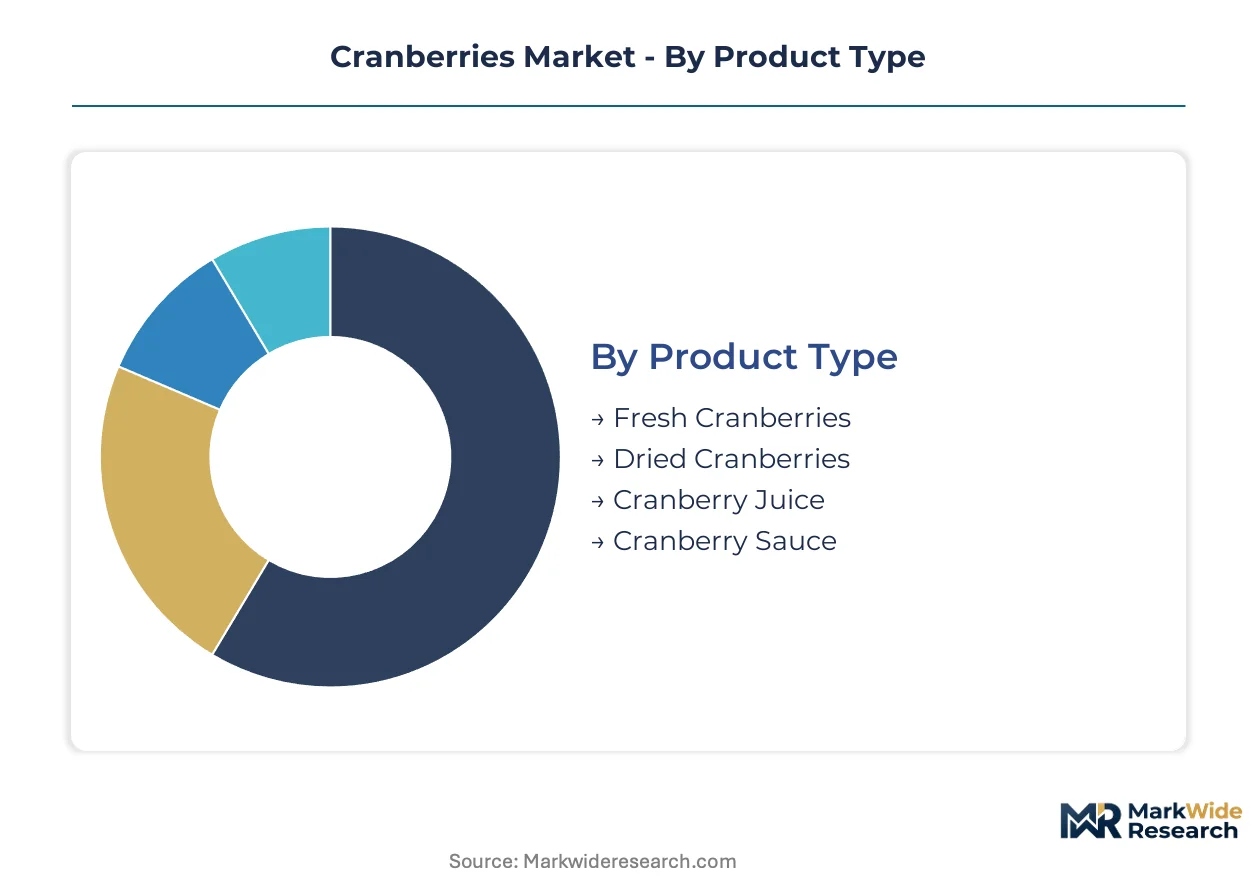
Cranberry value chains diverge sharply between fresh commodity flows and processed ingredient systems, with each segment demanding distinct procurement specifications, shelf-life protocols, and margin structures. Understanding these fault lines reveals where processor investments concentrate and which channels offer defensible positioning.
Product Type:
Fresh cranberries circulate as standalone commodities requiring cold-chain integrity, while processed derivatives embed as functional ingredients across multiple finished goods categories.
- Dried Cranberries:These shelf-stable products undergo osmotic dehydration with sweetener infusion to achieve moisture levels below 15%. Food manufacturers in the United States specify them for bakery inclusion and trail mix formulations as clean-label fruit alternatives to artificial flavors. Demand concentrates in retail private-label programs where bulk procurement contracts favor scaled processors with year-round supply continuity.
- Cranberry Juice:This segment spans single-strength beverages and concentrated feedstocks for functional drink manufacturing. Massachusetts and Wisconsin processors are deploying membrane filtration systems to preserve heat-sensitive proanthocyanidins for premium positioning. The channel pulls strongly from millennial and Gen-Z cohorts seeking immunity-positioned beverages with standardized PAC content.
- Fresh Cranberries:Harvested from Vaccinium macrocarpon shrubs in acidic bogs, these berries serve seasonal retail windows and foodservice decoration applications with strict USDA grading compliance.
- Cranberry Sauce:Thermally processed fruit preparations targeting holiday retail peaks and foodservice portion-control requirements with established brand loyalty patterns.
Dried cranberries lead volumes today; cranberry juice is gaining share fastest.
End Use:
Cost tier stratification separates commodity food applications from premium nutraceutical and cosmeceutical channels demanding certificate-of-analysis documentation.
- Food & Beverage:The largest consumption tier spanning bakery, confectionery, dairy, and beverage applications. Processors leverage cranberry inclusion for natural colorant, acidulant, and preservative functionality while meeting FDA clean-label reformulation mandates. Wisconsin cooperative structures dominate procurement through backward integration into bog operations.
- Dietary Supplements:Standardized proanthocyanidin extracts for urinary tract health positioning command premium pricing per active unit. Ultrafiltration concentration technology is improving PAC yield rates from press cake, transforming former waste streams into high-margin inputs. Massachusetts processors lead adoption curves for this extraction advancement.
- Cosmetics:Antioxidant extracts for skincare formulations targeting natural preservation and anti-aging claims with organic certification premiums.
- Pharmaceuticals:Investigational and approved drug applications leveraging cranberry bioactives for urological therapeutic indications with regulatory pathway complexity.
Food and beverage absorbs the highest absolute volume; dietary supplements climb the fastest.
Distribution Channel:
Customer type fragmentation separates institutional procurement systems from fragmented retail and direct-to-consumer pathways with divergent specification requirements.
- Supermarkets:Mass-market retail chains consolidate formerly fragmented ingredient buying, now demanding PAC-standardized powders with lot-level documentation. Clean-label requirements intersect with scale purchasing leverage in United States natural and conventional grocery. This channel displacement is squeezing commodity-grade suppliers from premium shelf placements.
- Online Retail:Direct-to-consumer platforms enable supplement brands to bypass traditional ingredient distributors for PAC standardization co-development. Multi-year offtake security emerges through direct contracting relationships with nutraceutical formulators.
- Health Food Stores:Specialty retail emphasizing organic certification density and European export channel specialization with educated consumer bases.
- Direct Sales:Foodservice and industrial ingredient supply through established procurement relationships with volume commitment structures.
Supermarkets dominate current volume throughput; online retail expands most quickly.
Packaging Type:
Volume-to-margin ratios dictate format selection, with bulk systems serving processor economies and unitized packaging capturing retail premium realization.
- Bulk Containers:Industrial totes and drums for food manufacturing and ingredient processing inputs with freight optimization and handling efficiency priorities.
- Packs:Flexible retail pouches and bags for dried fruit and snack applications with resealability and portion control features.
- Bottles:Rigid containers for juice and liquid concentrates with light protection and pour control engineering.
- Jars:Glass and rigid plastic for sauce and premium preserves with shelf presence and reuse value positioning.
Bulk containers move the highest tonnage; packs capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bog water engineering specialists and cooperative agronomists concentrate in Wisconsin and Massachusetts, anchoring North American processing capacity. European cultivation clusters in Quebec and British Columbia draw on French-Canadian horticultural expertise. Chilean agronomists are expanding counter-seasonal supply to balance hemispheric harvest windows.
United States
Functional beverage manufacturers in Wisconsin and Massachusetts are elevating cranberry inclusion rates for immunity-positioned drinks. The FDA's updated Nutrition Facts labeling requirements are forcing reformulation investments toward lower-added-sugar formulations. Massachusetts processors around Carver and Middleborough lead adoption of ultrafiltration concentration technology for proanthocyanidin extraction.
Canada
Quebec's Saguenay-Lac-Saint-Jean region and British Columbia's Fraser Valley sustain organic certification density for European export channels. Health Canada maintains active health claim review processes for cranberry proanthocyanidin content, creating asynchronous market access timelines. Richmond-based processors specialize in PAC-standardized powders for nutraceutical brands.
Chile
Counter-seasonal harvest windows from Maule and La Araucanía regions supply North American processors during domestic off-seasons. Chile's national agricultural service enforces phytosanitary protocols that determine export eligibility to United States and European destination markets. Concepción-area cooperatives are expanding constructed wetland buffer systems for water discharge compliance.
Germany
Ingredient distributors in Hamburg and Bremen handle European transshipment of North American cranberry concentrates. EFSA health claim review processes for proanthocyanidin standardization create regulatory friction for supplement formulations. Bavarian nutraceutical formulators specify membrane-concentrate feedstocks for premium positioning.
China
Coastal processors in Shandong and Jiangsu provinces are importing cranberry juice concentrates for functional beverage manufacturing. The country's national food safety regulator enforces label compliance for imported fruit ingredients with certificate-of-analysis requirements. Qingdao-area manufacturers blend cranberry extracts into immunity-positioned drink formulations for domestic distribution.
Cranberries Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the cranberry value chain, with cooperative structures dominating North American supply. The market exhibits tiered concentration: scaled operators with backward integration into bog operations command procurement leverage, while regional processors serve niche organic and private-label channels. Three archetypes define competitive positioning: grower-owned cooperatives, independent processors with geographic specialization, and diversified fruit conglomerates. Capacity consolidation and direct-to-brand nutraceutical contracting represent the dominant competitive moves reshaping procurement relationships.
Within the cooperative archetype, Ocean Spray Cranberries, Inc. exemplifies grower-owned scale advantages through year-round supply continuity. Decas Cranberry Products, Inc. occupies a position as a Massachusetts-focused independent processor with bog control. Fruit d'Or represents the organic certification and European export specialization tier. These three anchors illustrate how competitive advantage flows from supply chain configuration rather than product differentiation alone.
| Leading Market Players |
|---|
| Ocean Spray Cranberries, Inc. |
| Graceland Fruit, Inc. |
| Decas Cranberry Products, Inc. |
| Fruit d'Or |
| Cape Blanco Cranberries, Inc. |
| Atoka Cranberries |
| Mariani Packing Company, Inc. |
| The Wonderful Company |
| Cape Cod Select |
| Others |
Supply Flow & Price Mechanics
Family-owned bog operations in Wisconsin and Massachusetts anchor supply discipline through cooperative pooling arrangements that buffer fertilizer and fuel price volatility. This ownership concentration enables long-term contracting leverage with retailers while constraining spot-market liquidity for smaller independents.
Pricing Analysis
Bundled year-round supply contracts with PAC-standardization services command premium realization against unbundled commodity-grade dried fruit sales. Three-tier pricing structure across premium membrane-concentrates, standard evaporated juices, and economy-grade sauce stock reflects quality-grade and certification-level differentiation. Pricing pressure stems from tart cherry and pomegranate extract substitution in supplement formulations. Private-label buyers at mass-market chains exhibit highest price sensitivity; direct-to-brand nutraceutical contracts show lowest.
Supply Chain Analysis
Bog water management rests on Wisconsin and Massachusetts engineering expertise, with Chilean counter-seasonal harvests feeding North American off-season gaps. Cranberry supply draws from Vaccinium macrocarpon cultivation, membrane filtration equipment, and constructed wetland buffer systems. Single-source vulnerability concentrates in Wisconsin-Massachusetts weather exposure. Distribution runs through cooperative processor networks to retail private-label programs and direct nutraceutical brand contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
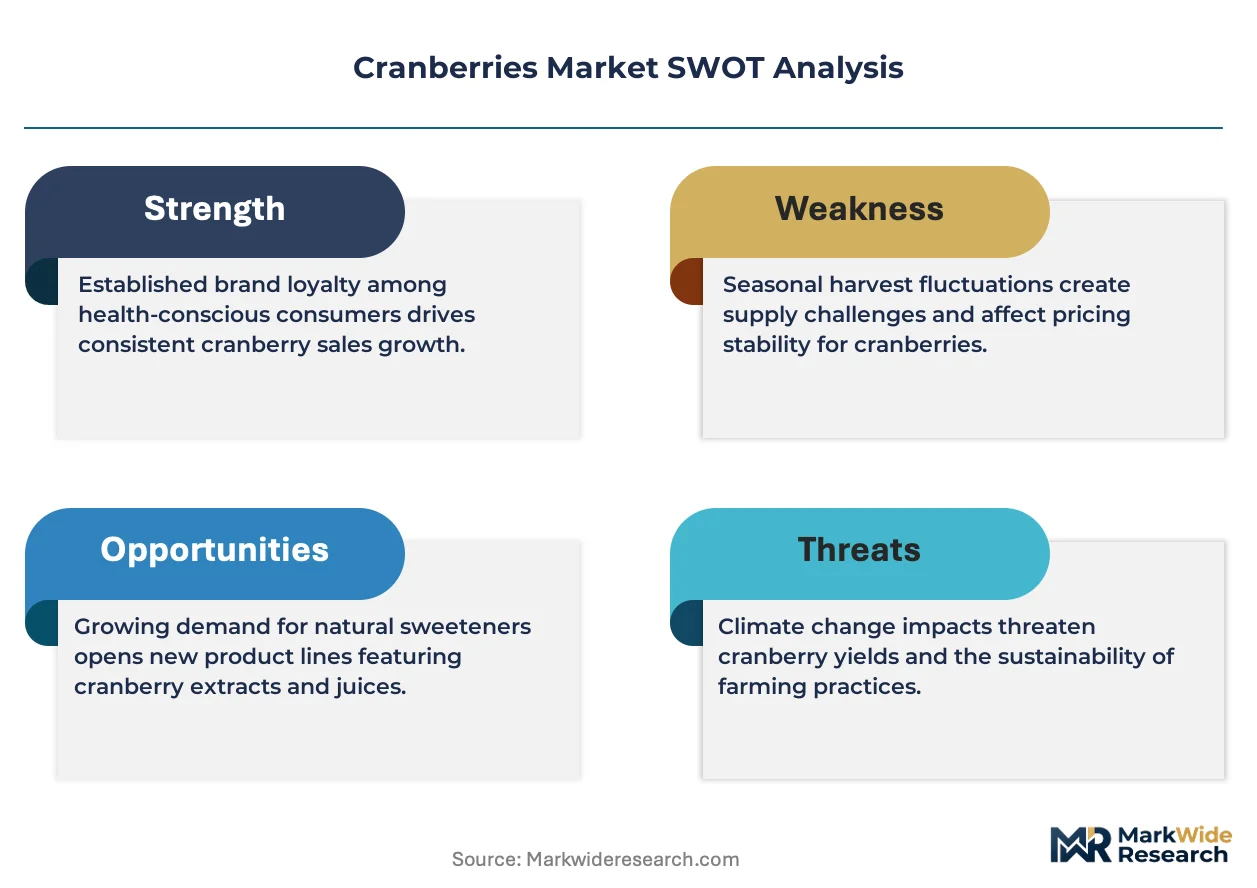
This market reads as a late-cycle quality story where PAC-standardized extract demand from supplement brands rewards specification discipline over volume scale.
For Market Incumbents: Extend backward integration into organic bog acreage ahead of USDA National Organic Program rule revisions. Deepen membrane filtration capacity in Massachusetts to capture proanthocyanidin extraction premiums. Tart cherry substitution in standardized antioxidant categories threatens commodity-grade positioning. For New Entrants and Emerging Players: Direct-to-brand nutraceutical buyers remain underserved by traditional ingredient distributor networks. Target organic certification white space in Quebec and British Columbia for European export channel specialization. Pursue PAC standardization co-development agreements with supplement formulators seeking multi-year offtake security. For Investors and Strategic Acquirers: Diversified fruit conglomerates with existing clean-label portfolios are the most active acquirer in this space. Five-to-ten year viability hinges on bog water engineering talent pipelines and carbon policy harmonization. Acquisition targets with ultrafiltration concentration capabilities and direct brand relationships offer defensive positioning. Watch EPA Clean Water Act discharge permit tightening in Massachusetts as margin compression trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Massachusetts processors deploying ultrafiltration systems capture proanthocyanidin yield premiums from press cake waste streams. |
| Organic Bog Acreage Conversion | USDA National Organic Program rule revisions expand eligible acreage for first-mover advantage ahead of compliance deadlines. |
| Direct-to-Brand Nutraceutical Contracting | Bypassing traditional ingredient distributors enables PAC standardization co-development with supplement formulators. |
| Solar Array Deployment on Bog Peripheries | IRA clean energy incentives reduce cold storage and processing facility operational costs for cooperative operators. |
| Constructed Wetland Buffer Investment | EPA discharge permit tightening in Massachusetts forces capital deployment for phosphorus and nitrogen runoff compliance. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down bog production tracking forms the analytical core of this study. Primary interviews with cooperative agronomists, membrane filtration equipment suppliers, supplement brand formulators, and retail private-label procurement managers combined with secondary validation from USDA grading reports, EPA discharge permit filings, Health Canada health claim submissions, and EFSA regulatory proceedings. Trade flow data from customs records and cooperative financial disclosures enabled cross-verification of volume and value estimates.
Input-output matrices map cranberry harvest volumes through processing stages to finished goods segments across the projection horizon. Segmentation dimensions include product type, end-use application, distribution channel, and packaging format. CAGRs derive from trend extrapolation of proanthocyanidin standardization adoption, organic certification conversion rates, and functional beverage inclusion rate shifts. Forecast inputs incorporate fertilizer and fuel price benchmarks, dual carbon policy implementation timelines, and membrane filtration technology diffusion curves.
Inputs from cooperative financial disclosures and regulatory filing databases were available through the study window; gaps in real-time bog-level yield data introduce uncertainty bands around harvest volume assumptions. Forecasts reflect documented assumptions regarding EPA discharge permit enforcement intensity and EFSA health claim authorization timelines. Weather anomaly frequency and tart cherry substitution elasticity in supplement formulations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
White Mushroom Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Spain Lime Market