
 Avocado Puree Market | 2026-2036
Avocado Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Avocado Puree Market Outlook
FDA heavy metal testing protocols for processed baby foods is shifting the cost-of-entry calculus for avocado puree suppliers targeting infant nutrition channels. Calavo Growers leverages its integrated sourcing infrastructure across California and Mexico to sustain margin control from orchard to processing. Mission Produce anchors its competitive position through dedicated ripening and puree facilities that dominate North American supply consistency.
Avocado puree consists of mechanically processed Hass or Fuerte avocado flesh, typically standardized to 10-12% oil content and pasteurized to achieve shelf stability for industrial and retail applications. Its primary commercial purpose centers on delivering consistent fat texture and nutritional density to infant formula, smoothie bases, and sauce formulations without whole-fruit variability. Organic puree commands premium positioning among health-conscious food manufacturers, while conventional product lines compete on volume scale for quick-service restaurant procurement. Bulk container packaging occupies the dominant share of food manufacturer demand, though pouch formats are gaining fastest among direct-to-consumer channels seeking portion-controlled convenience.
USDA organic certification and FDA Good Manufacturing Practice standards govern product integrity for domestic market access, while Mexico's national health regulator enforces equivalent sanitary controls for export-grade processing facilities. These frameworks elevate compliance investment but simultaneously filter lower-capability processors, concentrating supply relationships among certified operators. Stakeholders must monitor evolving heavy metal thresholds and organic fraud detection protocols as determinants of supplier qualification and procurement risk.
Market Dynamics
FDA's updated heavy metal testing protocols for processed baby foods is compressing supplier margins while concentrating procurement relationships among vertically integrated processors with captive laboratory infrastructure.
Growth Catalysts
- Clean-label infant nutrition reformulation:Manufacturers are accelerating avocado puree incorporation into organic baby food lines to replace synthetic fat sources.
- Mexico's export-grade cold-chain expansion:Michoacán-based processors are building dedicated puree facilities with USDA-equivalent sanitary controls for North American food manufacturer supply.
- High-pressure pasteurization technology:Non-thermal processing systems are extending refrigerated puree shelf life without nutrient degradation, unlocking foodservice distribution channels.
Market Restraints
- Perishability-driven input cost volatility:Hass avocado spot prices fluctuate with California and Mexican harvest cycles, compressing processor margins during supply gaps.
- Geographic supply concentration:Over 80% of export-grade puree originates from Mexico's Michoacán-Jalisco corridor, creating climate and logistics vulnerability.
- Regulatory friction from heavy metal thresholds:FDA's reduced arsenic and cadmium limits for infant foods are disqualifying conventional orchard sources without soil remediation.
Strategic Opportunities
- Underpenetrated European organic channels:EFSA's evolving guidance on infant lipid profiles creates entry path for avocado puree suppliers meeting EU organic certification.
- Smoothie base co-manufacturing partnerships:Cold-pressed juice and functional beverage brands are outsourcing fat-emulsion formulation to certified puree processors.
- Plant-based sauce R&D convergence:Quick-service restaurant chains are reformulating creamy dressings with avocado puree to reduce dairy dependency.
Industry Challenges
- Certification timeline compression:USDA organic and FDA cGMP dual qualification cycles extend 18-24 months, delaying new facility commissioning.
- Specialized cold-chain logistics scarcity:Refrigerated bulk tanker capacity for temperature-sensitive puree transport lags demand growth in secondary distribution corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avocado Puree Market |
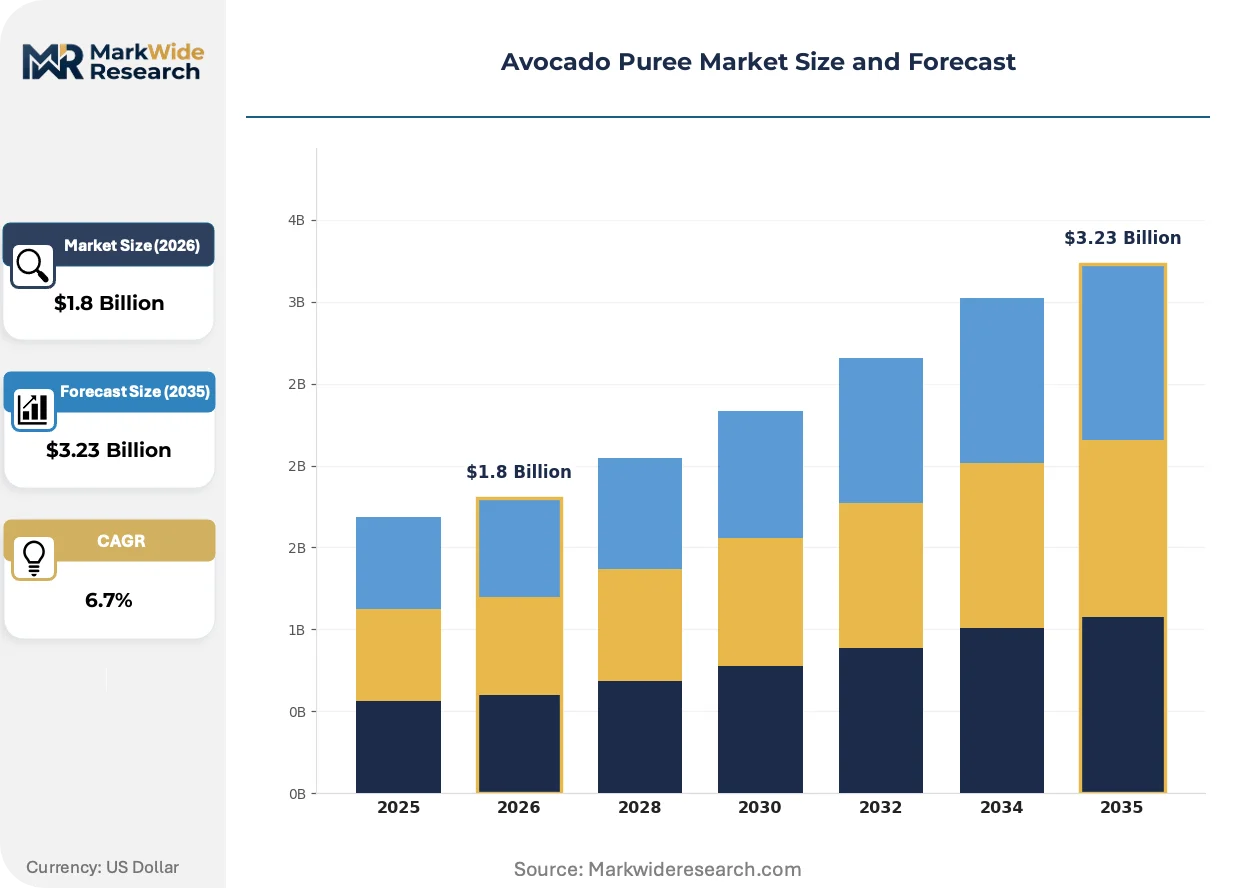
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Freeze-Dried, Fresh End User: Food Manufacturers, Restaurants, Retailers, Health Institutions Packaging Type: Bulk Containers, Pouches, Jars, Sachets Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Calavo Growers, Inc., Mission Produce, Inc., Westfalia Fruit (Pty) Ltd., DMH Ingredients Inc., Florigin Limited, Stonehill Produce, Ferreiro and Company, Simped Foods Pty Ltd, Döhler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avocado Puree Market Strategic Shifts
Processing technology and regulatory compliance requirements are converging to reshape competitive capability requirements, with capital-intensive infrastructure investments becoming the primary barrier to supply relationships.
High-pressure processing (HPP) systems are consolidating quality assurance standards across premium puree segments. Infant nutrition manufacturers are specifying HPP-treated product for organic lines to achieve extended refrigerated shelf life without thermal degradation. This technology is consolidating procurement relationships toward processors with in-house HPP capacity, marginalizing toll-processing dependent competitors.
REACH-compliant heavy metal testing protocols are elevating laboratory infrastructure requirements for EU-bound exports. European food manufacturers now require batch-level arsenic, cadmium, and lead documentation exceeding baseline Codex standards. Organic puree suppliers with captive testing facilities in Mexico are securing multi-year supply agreements while uncertified operators lose shelf access.
Direct-to-consumer pouch formats are fragmenting traditional bulk-channel concentration. Health-conscious households are subscribing to refrigerated avocado puree subscriptions for smoothie preparation, bypassing foodservice distributors. California and Texas urban markets exhibit the strongest subscription velocity, prompting processors to install dedicated retail packaging lines alongside industrial bulk operations.
Avocado Puree Market Segmentation
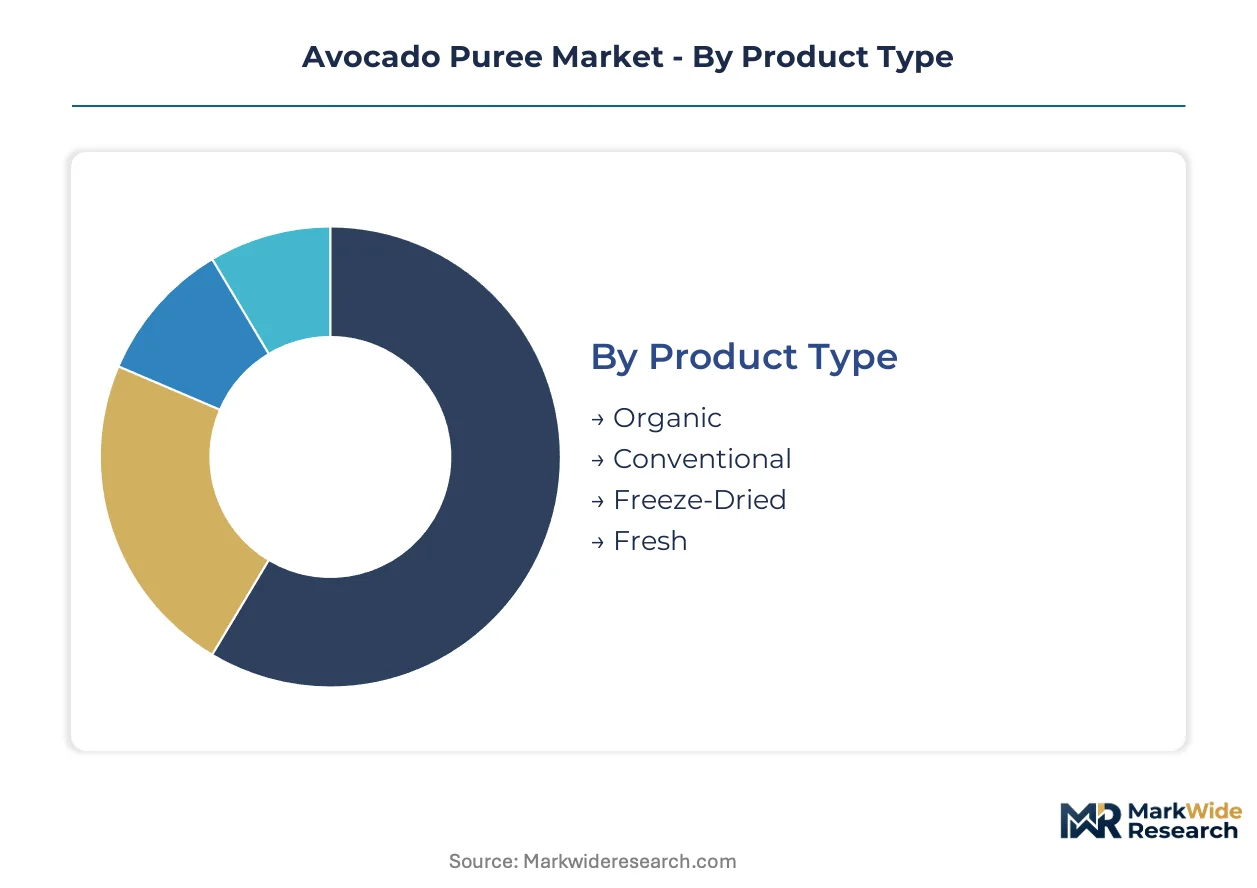
Avocado puree procurement patterns diverge sharply across product grades and channel structures. Manufacturers optimize formulations against shelf-life requirements, organic certification thresholds, and end-use viscosity specifications. Understanding these segment boundaries clarifies where margin pools concentrate and where new entrants face qualification barriers.
Product Type:
Processing intensity and certification status define the technical specification axis across product categories. Oil content standardization, pasteurization method, and organic integrity create distinct procurement tiers with diverging qualification timelines.
- Organic:USDA-certified puree commands premium positioning among infant nutrition manufacturers reformulating toward clean-label ingredient decks. Demand concentrates in California and Texas subscription channels where health-conscious households prioritize pesticide-free sourcing for direct-to-consumer smoothie preparation.
- Conventional:Mechanically processed Hass or Fuerte flesh standardized to 10-12% oil content serves quick-service restaurant chains and industrial sauce manufacturers competing on volume scale. Procurement relationships favor vertically integrated processors with captive laboratory infrastructure for heavy metal screening.
- Freeze-Dried:Shelf-stable powder format extends distribution reach to emergency food supply and military ration applications where refrigerated logistics prove prohibitive.
- Fresh:Unpasteurized refrigerated puree retains maximum enzymatic activity for high-end culinary applications and raw-food retail channels.
Conventional leads on scale; organic leads on momentum.
End User:
Formulation complexity and volume predictability separate customer tiers across the demand base. Each end-use channel imposes distinct specification regimes, from FDA infant food compliance to foodservice portion consistency.
- Food Manufacturers:Industrial buyers specify bulk deliveries for infant formula, smoothie base, and sauce formulation applications. Procurement concentrates among certified processors with in-house high-pressure pasteurization capacity and batch-level heavy metal documentation exceeding baseline Codex standards.
- Restaurants:Quick-service chains drive creamy dressing reformulation to reduce dairy dependency, sourcing refrigerated puree through dedicated foodservice distributors.
- Retailers:Supermarket and specialty store channels stock pouch and jar formats for household smoothie preparation, with subscription velocity strongest in California urban markets.
- Health Institutions:Hospital and clinical nutrition programs incorporate avocado puree into therapeutic diet protocols for cardiac and diabetic patient populations.
Food manufacturers anchor volume commitment; restaurants are expanding most quickly.
Packaging Type:
Unit economics and cold-chain requirements shape format selection across distribution corridors. Packaging technology directly determines shelf-life extension and retail accessibility.
- Bulk Containers:Refrigerated tanker and drum shipments dominate food manufacturer procurement, with specialized bulk tanker capacity lagging demand growth in secondary distribution corridors.
- Pouches:Portion-controlled flexible formats gain fastest among direct-to-consumer channels seeking convenience, prompting processors to install dedicated retail packaging lines alongside industrial operations.
- Jars:Glass containment satisfies premium positioning in specialty retail and gift-oriented channels.
- Sachets:Single-serve packets serve travel, hospitality, and institutional portion control applications.
Bulk containers dominate procurement tonnage; pouches gain share fastest.
Distribution Channel:
Customer acquisition cost and cold-chain integrity requirements fragment route-to-market strategies. Channel selection determines margin capture and brand control positioning.
- Online:Subscription platforms and direct-to-consumer marketplaces bypass traditional distributor markups, with refrigerated delivery infrastructure expanding in Texas and California urban corridors.
- Supermarkets:Mass retail placement requires slotting fee investment and regional distribution partnerships, concentrating shelf access among scaled processors.
- Specialty Stores:Natural products retailers prioritize USDA organic certification and transparent sourcing narratives for premium positioning.
- Direct Sales:Processor-to-manufacturer contracts lock in multi-year supply agreements with infant nutrition and beverage co-manufacturing partners.
Direct sales secure volume commitment; online climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing talent and orchard management expertise concentrate in Michoacán's avocado belt, where multi-generational farming operations supply the bulk of export-grade puree feedstock. Cold-chain engineers and food safety specialists cluster around Mexico City and Guadalajara, supporting vertically integrated processing infrastructure.
Mexico
Michoacán-based processors dominate export-grade puree production for North American infant nutrition channels. Mexico's national health regulator enforces sanitary controls equivalent to FDA standards for export facilities. Jalisco's emerging processing corridor is attracting cold-chain investment from California-based food manufacturers seeking supply security.
United States
California's Central Valley hosts the domestic Hass avocado harvest and puree processing for quick-service restaurant supply. FDA heavy metal testing protocols for processed baby foods are elevating laboratory infrastructure requirements at California-based facilities. San Diego County processors maintain cross-border coordination with Baja California orchard operations.
Germany
EFSA guidance on infant lipid profiles is creating formulation demand for avocado puree among German organic baby food manufacturers. REACH-compliant heavy metal documentation requirements exceed baseline Codex standards for EU market access. Hamburg's food ingredient trading hub is consolidating procurement relationships with certified Mexican exporters.
Netherlands
Rotterdam's port infrastructure anchors European distribution for refrigerated bulk puree shipments from Latin America. EU organic certification and cold-chain integrity standards filter supplier qualification toward vertically integrated processors. Dutch food manufacturers are reformulating plant-based sauces with avocado puree to reduce dairy dependency.
Australia
Health-conscious households in Sydney and Melbourne are driving subscription velocity for direct-to-consumer avocado puree pouches. Food Standards Australia New Zealand maintains parallel requirements to FDA for heavy metal screening in infant foods. Queensland's emerging avocado belt is developing processing capacity for domestic puree supply and Asia-Pacific export.
Avocado Puree Market Competitive Environment
The competitive structure tilts toward vertically integrated orchard-to-processor operators with captive laboratory infrastructure. Tiered capability concentration separates certified suppliers serving infant nutrition channels from commodity-grade processors competing on volume scale. Strategic archetypes include California-Mexico cross-border integrators, European ingredient conglomerates with puree diversification, and Australian specialists in direct-to-consumer formats. Dominant competitive moves center on backward integration into orchard assets and high-pressure pasteurization capacity installation.
Among North American integrators, Calavo Growers, Inc. and Mission Produce, Inc. exemplify the orchard-processor archetype with cross-border infrastructure spanning California and Mexico. Westfalia Fruit (Pty) Ltd. represents the southern hemisphere specialist position with African and Latin American sourcing networks. Döhler Group occupies the European ingredient conglomerate tier with diversified fruit puree portfolios and REACH-compliant certification infrastructure.
| Leading Market Players |
|---|
| Calavo Growers, Inc. |
| Mission Produce, Inc. |
| Westfalia Fruit (Pty) Ltd. |
| DMH Ingredients Inc. |
| Florigin Limited |
| Stonehill Produce |
| Ferreiro and Company |
| Simped Foods Pty Ltd |
| Döhler Group |
| Others |
Value Chain & Pricing Dynamics
Backward integration into Michoacán orchard assets anchors both supply security and pricing power for processors serving North American infant nutrition channels. This captive sourcing model insulates certified operators from Hass avocado spot volatility while commanding premium positioning against toll-dependent competitors lacking laboratory infrastructure for FDA heavy metal compliance.
Pricing Analysis
Unbundled testing and certification services separate procurement tiers, with organic puree commanding substantial premiums over conventional lines. Three-tier pricing structure across premium, standard, and economy levels reflects USDA certification status, oil content standardization, and HPP treatment. Cost compression in conventional bulk channels is intensifying because quick-service restaurant buyers consolidate volumes among vertically integrated suppliers. Food manufacturers exhibit highest price sensitivity due to formulation cost targets, while infant nutrition buyers prioritize batch-level documentation over unit economics.
Supply Chain Analysis
Reverse-logistics infrastructure for refrigerated bulk tanker returns remains underdeveloped, creating asset utilization inefficiencies that elevate transport costs. Feedstock draws from Mexico, California, and Peru, with Michoacán-Jalisco orchards supplying over eighty percent of export-grade Hass fruit. Processing hinges on pasteurization equipment, laboratory testing capacity, and cold-chain packaging materials. Single-source vulnerability concentrates in Mexican harvest cycles vulnerable to climate disruption. Distribution runs through dedicated foodservice distributors for food manufacturers and subscription platforms for direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The avocado puree market functions as a stable compounder, with clean-label infant nutrition reformulation providing durable demand expansion across economic cycles.
For Market Incumbents: Deploy captive laboratory infrastructure as the primary defensive lever. Expand high-pressure pasteurization capacity in Jalisco processing corridors to capture organic line growth from infant nutrition manufacturers. Lock in multi-year supply agreements with smoothie base co-manufacturers before secondary processors achieve USDA organic qualification.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable entry path for Australian and European operators lacking Mexican orchard access. Target California urban households with refrigerated pouch formats bypassing traditional foodservice distributor markups. Partner with cold-pressed juice brands for outsourced fat-emulsion formulation contracts.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap processors with dual USDA-FDA certification because regulatory compliance timelines create acquisition scarcity value. Five-to-ten year viability rests on backward integration into orchard assets rather than toll-processing dependence. Monitor EFSA guidance evolution on infant lipid profiles for European market entry signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive Hass avocado supply insulates processors from Michoacán harvest volatility and spot price compression. |
| High-Pressure Pasteurization Installation | HPP capacity unlocks extended refrigerated shelf life for organic infant nutrition lines without nutrient degradation. |
| EU Organic Certification Investment | REACH-compliant heavy metal documentation opens German and Dutch formulation demand for premium puree supply. |
| Direct-to-Consumer Pouch Launch | Subscription velocity in California and Texas urban corridors bypasses foodservice distributor margin capture. |
| Co-Manufacturing Partnership Expansion | Functional beverage brands outsource fat-emulsion formulation to certified processors with laboratory infrastructure. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with infant nutrition procurement directors, cold-chain logistics operators, food safety laboratory managers, and quick-service restaurant supply chain executives informed demand-side assessment. Secondary sources include FDA guidance documents, USDA organic certification databases, EFSA scientific opinions, customs trade records, and processor facility inspection reports. Bottom-up volume modeling triangulated against top-down category spend analysis.
Granularity-level modeling addressed product type, end-use channel, packaging format, and geographic supply cluster throughout the forecast period. CAGRs derived from historical volume trajectories adjusted for regulatory compliance cost inflation and technology adoption curves. Infant nutrition formulation trends and cold-chain infrastructure investment patterns served as key demand-side inputs. Supply-side constraints incorporated orchard maturity cycles and processing capacity commissioning timelines.
The model assumes a particular technology adoption path; alternative pathways for non-thermal pasteurization would alter the outlook if thermal methods achieve cost parity. Forecasts reflect assumptions regarding FDA heavy metal threshold stability and Mexican export facility expansion. Practitioners should monitor EFSA infant lipid guidance revisions and California drought conditions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market