
 Farro Market | 2026-2036
Farro Market Size, Share, and Industry Trends Forecast 2026-2036
Farro Market Analysis
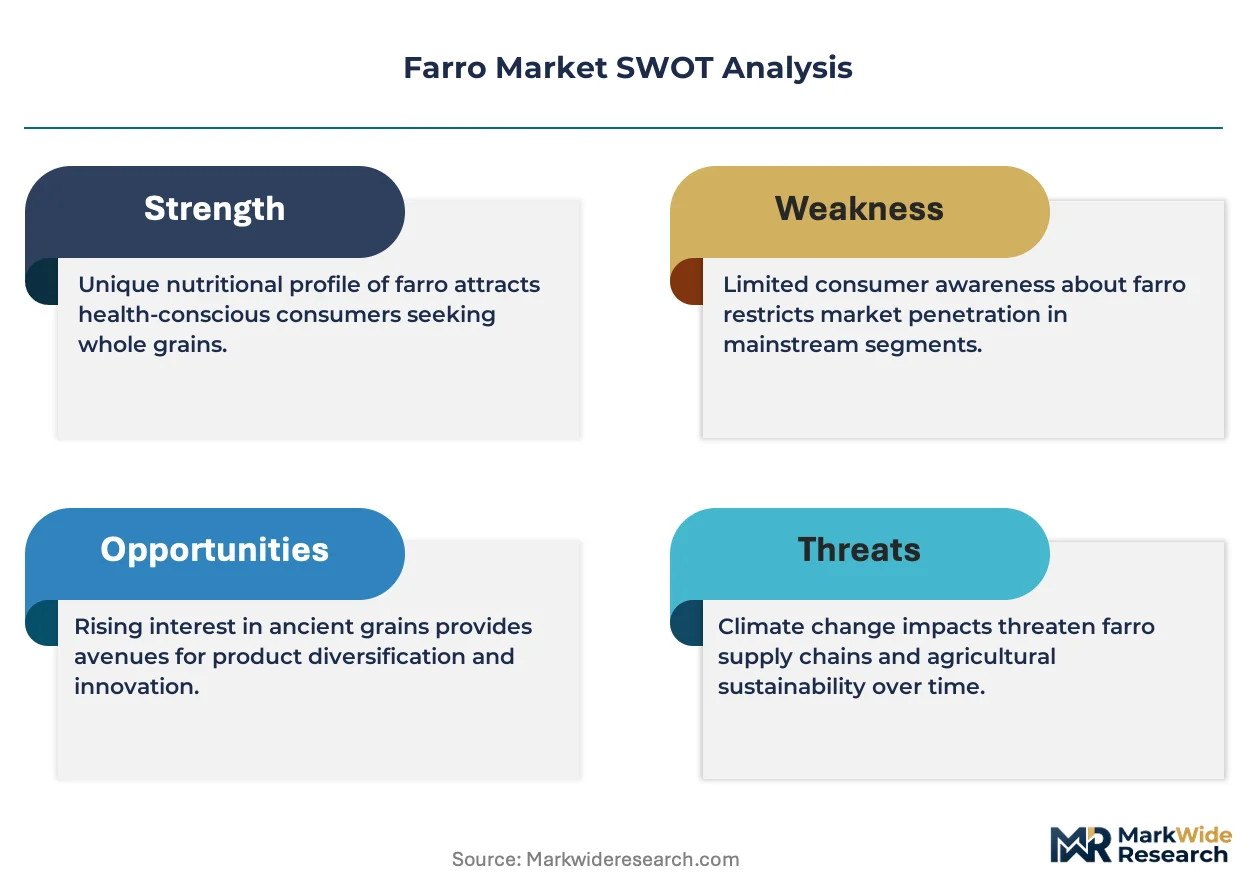
Multi-source sourcing from Italian heritage mills to North American organic growers is restructuring procurement reliability for farro distributors. Bob's Red Mill Natural Foods leverages its vertically integrated milling infrastructure to control grain-to-package traceability. Woodland Foods sustains broad specialty-ingredient distribution reach across food service accounts. Poggio del Farro Srl anchors its position through Protected Geographical Indication ties in Tuscany.
Farro denotes hulled wheat of the Triticum genus, typically Triticum dicoccum, with a dense, chewy endosperm requiring parboiling or extended simmering to achieve palatable texture; its primary commercial purpose centers on premium grain bowls, risotto-style preparations, and artisan bakery inclusions. Organic farro commands disproportionate shelf space in health-focused retail channels where margin pools exceed conventional equivalents. Whole grain farro retains the bran layer and germ, appealing to fiber-seeking consumers, while farro flour competes in gluten-aware bakery formulations despite the grain's inherent gluten content. Specialty stores and online channels together capture the fastest-growing distribution dimension as direct-to-consumer heritage storytelling displaces commodity positioning.
USDA organic standards govern North American labeling claims, while EU Regulation 2018/848 defines organic production rules for Italian and other European suppliers, and FDA food allergen labeling mandates affect farro's wheat-derived gluten disclosure. These frameworks elevate compliance costs for cross-border suppliers but simultaneously filter out uncertified competitors. Stakeholders must monitor evolving carbon-accounting requirements for imported heritage grains and assess whether regional milling investments reduce transatlantic shipment exposure.
Market Dynamics
EU organic certification standards and FDA allergen labeling mandates are compressing margins for uncertified farro suppliers while creating compliance moats for heritage millers who control grain-to-package traceability.
Growth Catalysts
- EU Regulation 2018/848:Organic production rules for Italian suppliers are filtering out uncertified competitors and concentrating shelf space among heritage-certified producers.
- Ancient-grain menu expansion:Specialty food service channels in Italy and the United States are absorbing rising volumes as chefs feature farro in risotto-style preparations and grain bowls.
- Tuscany's Protected Geographical Indication:Geographic concentration of heritage supply is anchoring premium positioning and import demand for authentic Italian farro.
Market Restraints
- Gluten-labeling compliance costs:FDA food allergen mandates require wheat-derived disclosure, elevating packaging and testing expenses for cross-border suppliers.
- Extended cooking time:Dense endosperm requiring parboiling or extended simmering limits adoption in quick-service food formats.
- Quinoa and freekeh substitution:Alternative ancient grains with faster preparation profiles are capturing share in time-constrained consumer segments.
Strategic Opportunities
- Carbon-accounting requirements:Evolving standards for imported heritage grains are creating first-mover advantages for regional milling investments that reduce transatlantic shipment exposure.
- Direct-to-consumer heritage storytelling:Specialty stores and online channels are displacing commodity positioning through provenance narratives.
- Gluten-aware bakery formulations:Farro flour is penetrating fiber-focused bakery inclusions despite inherent gluten content, opening formulation partnerships.
Industry Challenges
- Heritage grain agronomy expertise:Limited farmer familiarity with Triticum dicoccum cultivation is constraining supply expansion outside Tuscany and the Pacific Northwest organic cluster.
- Multi-jurisdiction certification timelines:Simultaneous USDA organic and EU organic compliance is extending product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farro Market |
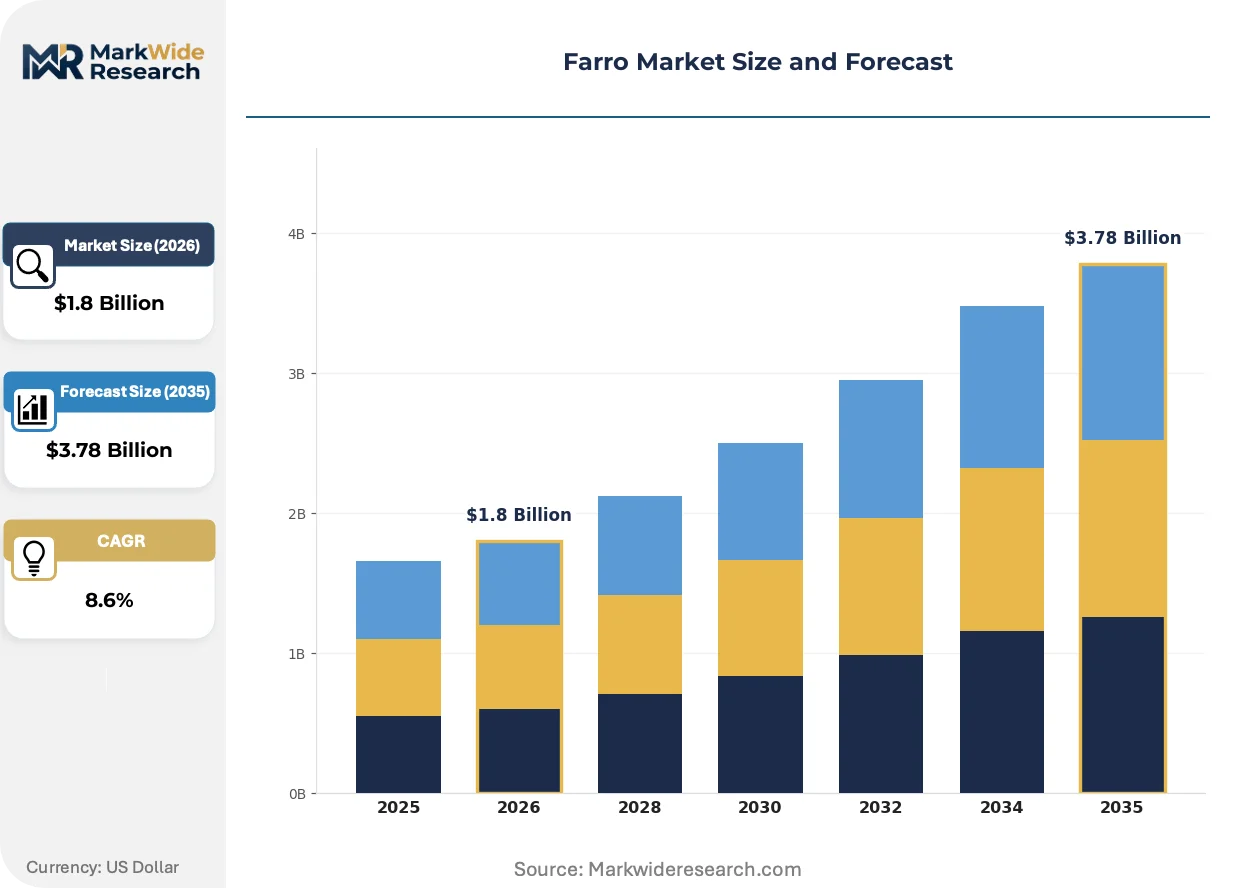
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Farro, Conventional Farro, Whole Grain Farro, Farro Flour End Use: Food Service, Retail, Manufacturing, Bakery Distribution Channel: Online, Supermarkets, Health Stores, Specialty Stores Packaging Type: Bulk Bags, Retail Packs, Eco-friendly Packaging, Glass Jars |
| Companies Covered | Whole Foods Market Services Inc., Timeless Seeds Inc., Woodland Foods, Vigo Importing Co. Inc., Nature's Earthly Choice, Bluebird Grain Farms, Roland Foods LLC, Poggio del Farro Srl, Bob's Red Mill Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farro Market Emerging Trajectories
Processing technology and distribution infrastructure are reshaping how farro moves from heritage mills to end-use channels, with traceability systems and preparation formats driving competitive differentiation.
Parboiling technology is converging with retail-ready packaging formats to reduce home-cooking time from forty-five minutes to twelve minutes. Health-focused retailers are adopting these convenience-oriented SKUs at accelerated rates. This compression of preparation barriers is converging with premium positioning to expand addressable demand beyond traditional culinary enthusiasts.
EU organic certification standards are tightening input documentation requirements for imported grains. Italian heritage suppliers face elevated audit costs for cross-border shipments to North American buyers. Specialty distributors are responding by consolidating procurement relationships with vertically integrated Tuscan millers who control full-chain documentation.
Chef-driven procurement is rotating toward single-origin contracts with named heritage varieties. Food service accounts in the Pacific Northwest are replacing commodity ancient-grain purchasing with direct relationships with organic growers. This specification behavior is most visible in Seattle and Portland restaurant groups featuring provenance-transparent menu narratives.
Farro Market Segmentation
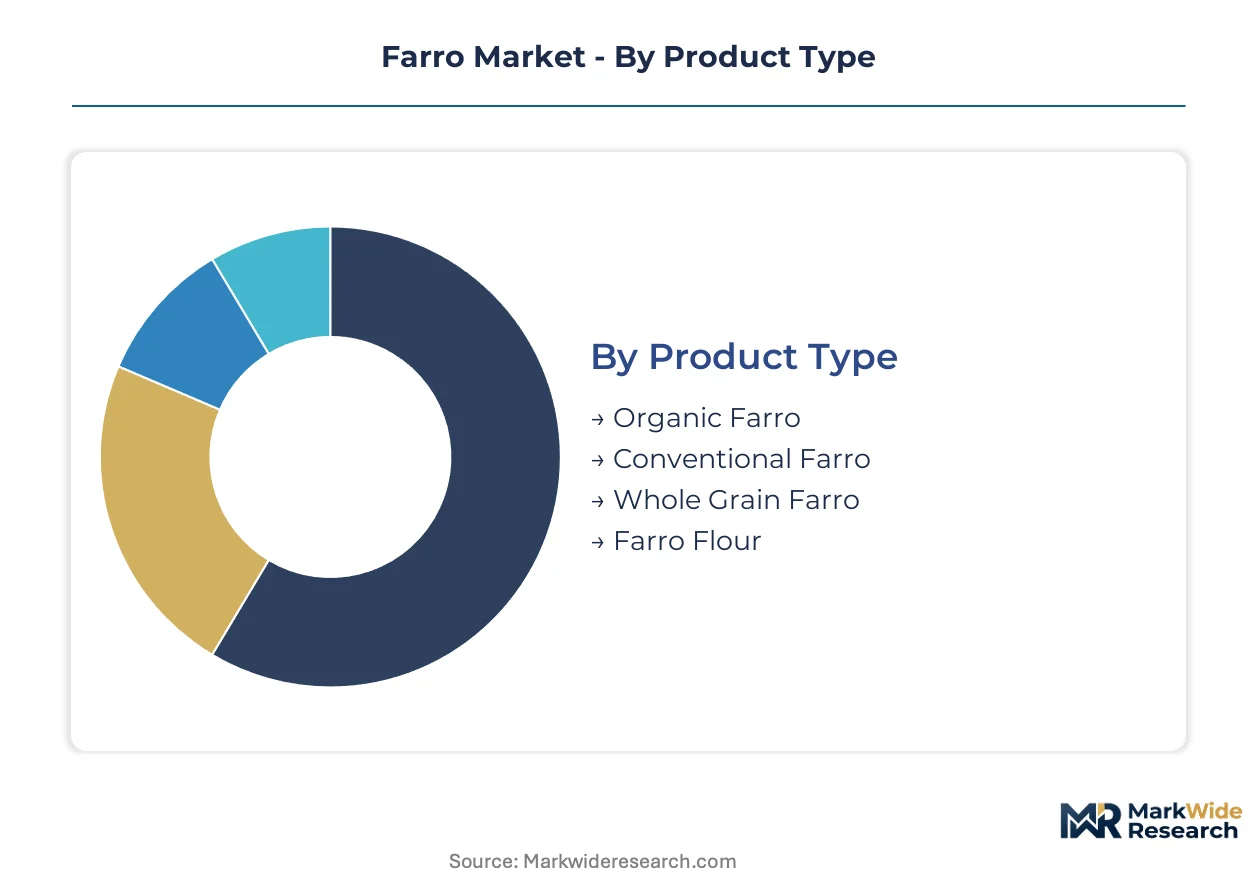
Farro's commercial structure fragments across certification tiers, preparation formats, and channel-specific packaging requirements. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape supplier positioning.
Product Type:
Certification and processing intensity define the product hierarchy, with organic premiums commanding shelf-space allocation in health-focused retail.
- Organic Farro:Cultivation under USDA organic or EU Regulation 2018/848 standards requires three-year field conversion and prohibited-synthetic input documentation. Pacific Northwest organic clusters and Tuscan heritage zones concentrate supply as health-focused retailers allocate disproportionate shelf space to certified SKUs.
- Whole Grain Farro:Intact bran layer and germ retention delivers elevated fiber and mineral content versus pearled alternatives. Food service channels in Seattle and Portland absorb volumes for provenance-transparent grain bowls as chef-driven procurement rotates toward single-origin contracts.
- Conventional Farro:Non-certified cultivation without organic input restrictions serves price-sensitive food manufacturing and commodity retail tiers.
- Farro Flour:Milled Triticum dicoccum competes in fiber-focused bakery formulations despite inherent gluten content, penetrating gluten-aware but not gluten-free product development.
Organic farro leads on scale; farro flour leads on momentum.
End Use:
Application-specific preparation requirements and margin structures concentrate investment across four demand pools.
- Food Service:Chef-driven procurement in Italy and the United States specification behavior demands named heritage varieties and parboiled formats reducing kitchen labor. Ancient-grain menu expansion in Seattle, Portland, and Tuscan restaurant groups absorbs rising volumes.
- Retail:Health-focused grocers and specialty stores capture direct-to-consumer heritage storytelling opportunities with premium positioning.
- Bakery:Farro flour inclusion in artisan formulations targets fiber-seeking consumers despite wheat-derived gluten disclosure requirements.
- Manufacturing:Ingredient-scale procurement for packaged grain bowls and ready meals prioritizes supply reliability over provenance documentation.
Food service commands margin premiums; retail channels are expanding most quickly.
Distribution Channel:
Channel selection determines traceability investment levels and provenance narrative control.
- Specialty Stores:Curated heritage storytelling and single-origin SKUs displace commodity positioning through provenance-transparent merchandising.
- Online:Direct-to-consumer platforms enable grain-to-package traceability display and subscription-format heritage variety access.
- Health Stores:Certified organic SKUs dominate shelf space with elevated margin pools exceeding conventional equivalents.
- Supermarkets:Mass retail placement requires parboiled convenience formats and competitive unit economics against quinoa and freekeh alternatives.
Specialty stores anchor premium positioning; online channels show steepest expansion trajectory.
Packaging Type:
Format selection balances preparation convenience, sustainability credentials, and shelf-life engineering.
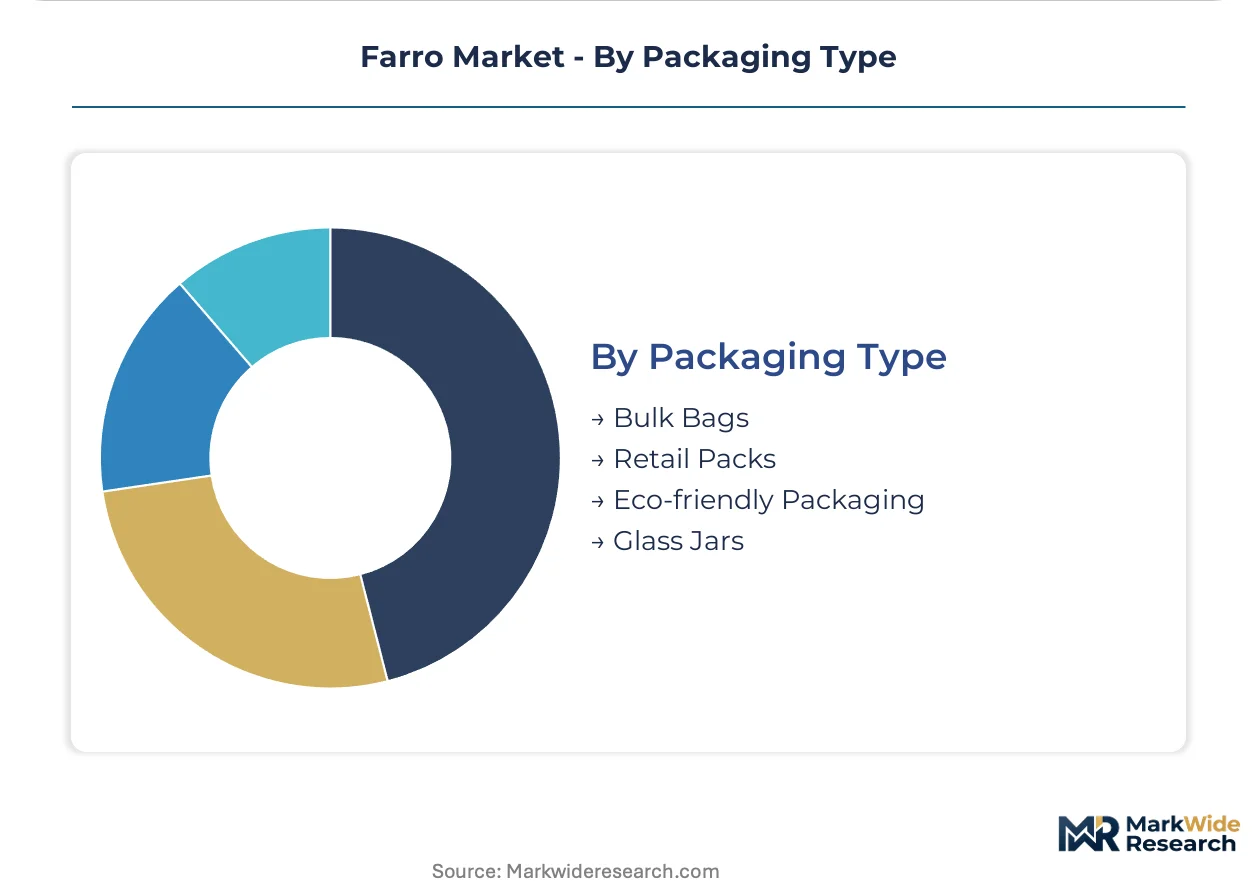
- Retail Packs:Consumer-portioned packaging with cooking instruction panels targets home preparation barriers through parboiled product claims.
- Eco-friendly Packaging:Compostable or recyclable materials align with carbon-accounting requirements for imported heritage grains.
- Bulk Bags:Food service and manufacturing procurement minimizes per-unit packaging cost for high-volume accounts.
- Glass Jars:Premium positioning in specialty retail emphasizes visual grain quality and reusability messaging.
Retail packs dominate volume throughput; eco-friendly formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tuscany's heritage supply zone anchors import demand for authentic Italian farro, while the Pacific Northwest organic cluster drives North American cultivation expansion. Demand concentrates in chef-driven procurement corridors across Italy and the United States.
United States
Seattle and Portland restaurant groups specification behavior demands named heritage varieties and parboiled formats. FDA food allergen labeling mandates require wheat-derived disclosure for farro's gluten content. The Pacific Northwest organic cluster in Washington and Oregon states sustains supply expansion through direct grower relationships.
Italy
Tuscan restaurant groups and specialty food service channels absorb rising volumes of Protected Geographical Indication farro. EU Regulation 2018/848 organic production rules filter uncertified competitors and concentrate shelf space among heritage-certified producers. Tuscany's heritage supply zone anchors premium positioning through vertically integrated millers controlling full-chain documentation.
Germany
Health-focused retailers in Berlin and Munich allocate disproportionate shelf space to certified organic ancient grains. EFSA guidelines on health claims shape labeling requirements for fiber-focused farro products. Bavarian and Baden-Württemberg distribution hubs channel Italian imports into Central European food service accounts.
Canada
Health Canada and PMRA govern organic certification equivalency for Italian farro imports into Ontario and Quebec retail channels. Toronto and Vancouver specialty grocers specification behavior favors grain-to-package traceability display. British Columbia's organic farming corridor experiments with Triticum dicoccum cultivation to reduce transatlantic shipment exposure.
France
Paris and Lyon chef-driven procurement rotates toward single-origin contracts with Tuscan heritage millers. ANSM and CNIL frameworks intersect with EU organic standards for cross-border specialty grain documentation. Île-de-France distribution infrastructure channels imported farro into premium bakery and food service formulations.
Farro Market Vendor Landscape
Global majors compete with regional champions across certification tiers and provenance documentation. The vendor base stratifies between vertically integrated heritage millers, broad specialty-ingredient distributors, and health-focused retail private labels. Three archetypes dominate: Tuscan PGI-anchored heritage suppliers, North American organic cluster growers, and multi-category ancient-grain specialists. Capacity expansion and backward integration into controlled cultivation represent the dominant competitive moves.
Among vertically integrated millers, Bob's Red Mill Natural Foods and Poggio del Farro Srl exemplify the heritage-traceability archetype through grain-to-package control. Woodland Foods occupies a position within the broad specialty-distribution tier, sustaining reach across food service accounts. Timeless Seeds Inc. represents the organic cultivation specialist archetype, anchoring supply from the Pacific Northwest cluster.
| Leading Market Players |
|---|
| Whole Foods Market Services Inc. |
| Timeless Seeds Inc. |
| Woodland Foods |
| Vigo Importing Co. Inc. |
| Nature's Earthly Choice |
| Bluebird Grain Farms |
| Roland Foods LLC |
| Poggio del Farro Srl |
| Bob's Red Mill Natural Foods |
| Others |
Supply Flow & Price Mechanics
Chef-driven procurement in Seattle and Portland demanding named heritage varieties and parboiled formats is forcing supply-side reconfiguration toward vertically integrated Tuscan millers and Pacific Northwest organic growers, compressing margins for commodity traders while concentrating pricing power among documentation-compliant suppliers.
Pricing Analysis
Input-cost pass-through from EU organic certification audit expenses and FDA allergen labeling compliance is reshaping pricing structures across the farro market. Three-tier pricing structure across premium, standard, and economy levels separates PGI-certified Tuscan heritage lots from USDA organic Pacific Northwest supply and conventional non-certified grain. Pricing pressure stems from quinoa and freekeh substitution in time-constrained consumer segments. Food manufacturing procurement shows highest price sensitivity; chef-driven food service accounts exhibit lowest sensitivity due to provenance premiums.
Supply Chain Analysis
Dual-sourcing requirements from North American distributors mandating simultaneous Italian heritage mill and Pacific Northwest organic grower qualification are restructuring procurement relationships. Supply concentrates in Italy, the United States, and Canada. Raw material dependencies include Triticum dicoccum seed stock, organic fertilizer inputs, and parboiling equipment. Single-source vulnerability threatens distributors relying exclusively on Tuscan imports. Distribution runs through vertically integrated specialty-ingredient distributors and direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The farro market represents a late-cycle quality story as chef-driven procurement rotates toward single-origin contracts with named heritage varieties, displacing commodity positioning and rewarding traceability investments.
For Market Incumbents: Cement market position through backward integration into controlled cultivation in Washington and Oregon states, capturing Pacific Northwest organic cluster expansion. Invest in simultaneous USDA organic and EU Regulation 2018/848 certification to extend compliance moats. Threat from quinoa substitution demands parboiled format innovation to reduce preparation barriers. For New Entrants and Emerging Players: Enter via direct-to-consumer heritage storytelling in online channels, where provenance-transparent merchandising displaces commodity positioning. Target British Columbia's experimental Triticum dicoccum cultivation corridor to reduce transatlantic shipment exposure. Go-to-market angle: subscription-format heritage variety access with grain-to-package traceability display. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated heritage millers controlling full-chain documentation from cultivation through retail packaging. Long-term viability favors suppliers with dual-jurisdiction certification capability and regional milling assets. Signal to watch: carbon-accounting requirement adoption rates for imported heritage grains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Cultivation | Pacific Northwest organic cluster expansion reduces transatlantic shipment exposure for North American distributors. |
| Dual-Jurisdiction Certification Investment | Simultaneous USDA organic and EU Regulation 2018/848 compliance extends product launch cycles but filters uncertified competitors. |
| Parboiled Format Development | Convenience-oriented SKUs compress home-cooking time from forty-five minutes to twelve minutes, expanding addressable demand. |
| Direct-to-Consumer Channel Launch | Online platforms enable grain-to-package traceability display and subscription-format heritage variety access. |
| Carbon-Accounting Program Implementation | Regional milling investments create first-mover advantages as evolving standards reshape import requirements for heritage grains. |
Methodological Framework
Multiple input streams — primary interviews with specialty grain distributors, organic certification auditors, and chef procurement leads; secondary validation through USDA organic database records, EU Regulation 2018/848 compliance filings, and FDA food allergen guidance documents; plus customs trade data for Triticum dicoccum shipments — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across certification tiers, preparation formats, and channel-specific packaging requirements anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include organic versus conventional cultivation, whole grain versus pearled processing, and food service versus retail channel splits. CAGRs were derived from volume trajectory analysis incorporating ancient-grain menu expansion rates and parboiled format adoption curves.
Inputs from heritage miller production records and Pacific Northwest organic grower cooperatives were available through the study window; gaps in carbon-accounting requirement implementation timelines introduce uncertainty bands around regional milling investment forecasts. Deviation in EU organic certification enforcement intensity or FDA allergen labeling mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Turkish Figs Market