
 Europe Frozen Fruits and Vegetables Market | 2026-2036
Europe Frozen Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frozen Fruits and Vegetables Market Intelligence
EU Green Deal carbon-accounting rules is repositioning the cost structure for frozen produce supply chains entering the European market. Ardo Group leverages its Belgian processing footprint to sustain year-round berry volumes. Bonduelle anchors its competitive stance through deep specialization in frozen vegetable varietals. Nestlé S.A. extends its private-label and branded presence across multiple European retail channels.
Europe frozen fruits and vegetables comprise plant-based products preserved at temperatures below minus eighteen degrees Celsius after blanching or individual quick freezing, maintaining nutritional parity with fresh alternatives while eliminating seasonal supply constraints. Frozen berries command premium positioning within the product type matrix due to their application in smoothies and bakery formulations. The foodservice end-user segment generates disproportionate volume throughput, though retail chains capture wider margin pools through branded and private-label bag formats. Supermarkets and online retail distribution channels are expanding cold-chain fulfillment capabilities to reduce stockout frequency.
EFSA safety protocols, EU Green Deal sustainability disclosures, and national packaging directives from France and Germany collectively shape product formulation, labeling requirements, and market access conditions across the region. EMA-aligned cold-chain documentation standards further complicate cross-border shipment protocols for temperature-sensitive inventory. Stakeholders must monitor evolving carbon-border adjustment mechanisms and packaging waste regulations to preserve margin structures and distribution eligibility.
Market Dynamics
The EU Green Deal's carbon-accounting framework is restructuring procurement economics across European frozen produce supply chains, forcing logistics providers and foodservice buyers to recalculate total cost of ownership for temperature-controlled inventory movements.
Growth Catalysts
- EU Green Deal compliance mandates:Carbon-border adjustment mechanisms are elevating frozen produce competitiveness against air-freighted fresh alternatives, particularly for berry imports from North Africa and prepared vegetable blends from Eastern Europe.
- Foodservice operator consolidation:Institutional catering chains and quick-service restaurant groups across Germany, France, and Italy are standardizing frozen vegetable specifications to reduce kitchen labor and trim waste.
- Individual quick freezing (IQF) technology maturation:Belgian and Dutch processing facilities have achieved texture parity with fresh produce in prepared vegetable blends, unlocking premium positioning in retail channels.
Market Restraints
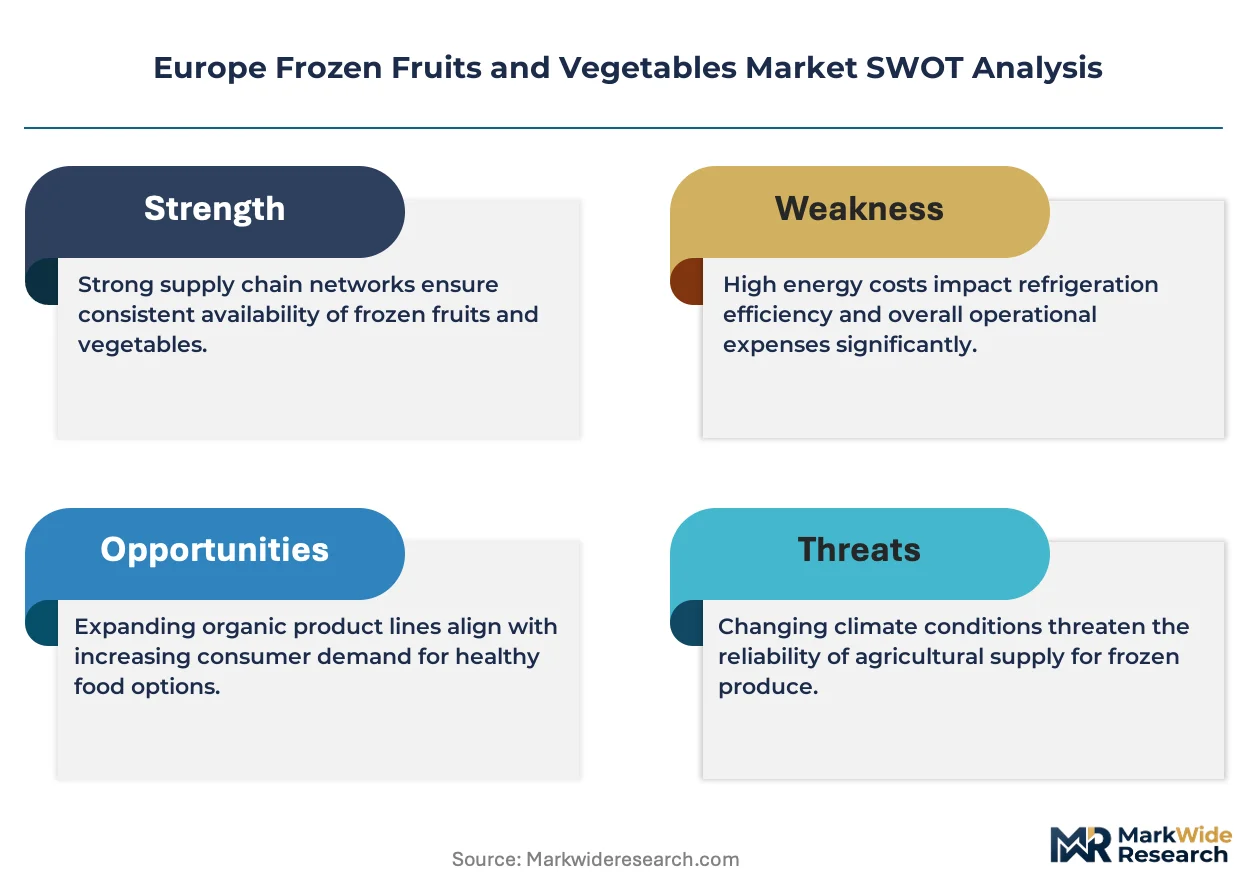
- Energy cost volatility:Natural gas and electricity price swings in Germany and Italy directly compress blast-freezing and cold-storage margins, particularly for independent processors without renewable power purchase agreements.
- Supply concentration in berry sourcing:Poland and Serbia control disproportionate volumes of IQF strawberry and raspberry raw material, creating procurement vulnerability during adverse weather cycles.
- Fresh produce substitution threat:Controlled-atmosphere storage and modified-atmosphere packaging for fresh vegetables are narrowing the shelf-life gap that historically favored frozen alternatives in Western European retail.
Strategic Opportunities
- Eastern European retail underpenetration:Romania, Bulgaria, and Hungary present frozen vegetable volume growth potential as modern trade formats expand cold-chain infrastructure beyond capital cities.
- Plant-based protein convergence:Frozen pea and fava bean processors can capture demand from meat-alternative manufacturers seeking clean-label protein isolates and texturized vegetable bases.
- CSRD-aligned sustainability disclosures:The EU Corporate Sustainability Reporting Directive creates first-mover advantage for processors with verified Scope 3 emissions data and regenerative agriculture sourcing certifications.
Industry Challenges
- Cold-chain engineering talent scarcity:Refrigeration system design and ammonia-based cooling expertise are aging out across Central European processing hubs, constraining capacity expansion timelines.
- EMA-aligned documentation complexity:Cross-border shipments of organic-certified frozen berries require harmonized temperature logs and phytosanitary certificates that delay customs clearance at Polish-German and Hungarian-Austrian frontiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frozen Fruits and Vegetables Market |
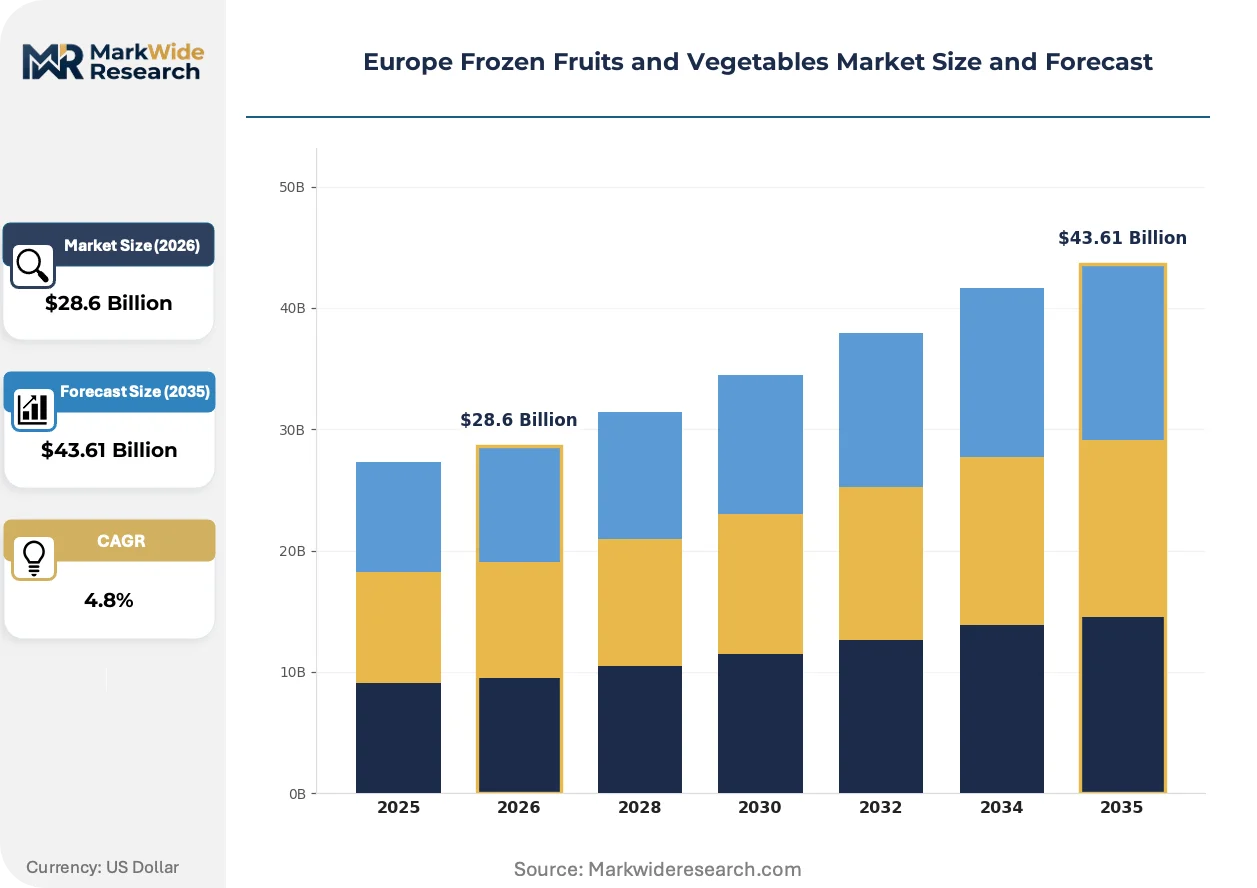
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Berries, Frozen Peas, Frozen Carrots, Frozen Spinach End User: Retail Chains, Foodservice, Manufacturers, Households Distribution Channel: Supermarkets, Online Retail, Wholesale, Convenience Stores Packaging Type: Bags, Boxes, Bulk Packs, Individual Portions |
| Companies Covered | Ardo Group, Unilever PLC, Nomad Foods, Bonduelle, McCain Foods, Greenyard Foods, Nestlé S.A., Grupo Virto, FRoSTA AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frozen Fruits and Vegetables Market Strategic Shifts & Innovations
European frozen produce markets are experiencing accelerated technology substitution and regulatory compression, with sustainability verification and automation reshaping competitive requirements across processing and distribution layers.
Blast-freezing systems with integrated heat recovery are overtaking conventional ammonia-based installations in new Belgian and Dutch processing facilities. Ardo Group and Bonduelle have retrofitted multiple plants with energy-recapture modules that redirect waste heat to pre-wash water systems. This thermal efficiency gain is compressing operating cost differentials between legacy and modern processing footprints, forcing smaller competitors toward contract manufacturing arrangements.
France's national packaging directive and Germany's Verpackungsgesetz amendments are mandating minimum recycled content thresholds for polyethylene terephthalate trays and polypropylene bags used in frozen vegetable retail packs. EFSA safety protocols for recycled food-contact materials are extending approval timelines for innovative barrier films, delaying compostable packaging rollouts by processors seeking shelf-life parity with conventional plastics. Western European retailers are responding with private-label specifications that phase in recycled-content requirements ahead of legal deadlines.
Centralized procurement by pan-European foodservice buying groups is consolidating supplier relationships around processors with multi-country certification coverage. Sodexo and Compass Group contracts now specify frozen vegetable suppliers holding BRC, IFS, and organic certifications across multiple production sites, displacing single-facility regional processors from tender shortlists. This concentration is most visible in the Benelux corridor, where cross-border logistics integration enables single-source supply to restaurant chains operating in Belgium, Netherlands, and Luxembourg.
Europe Frozen Fruits and Vegetables Market Segmentation
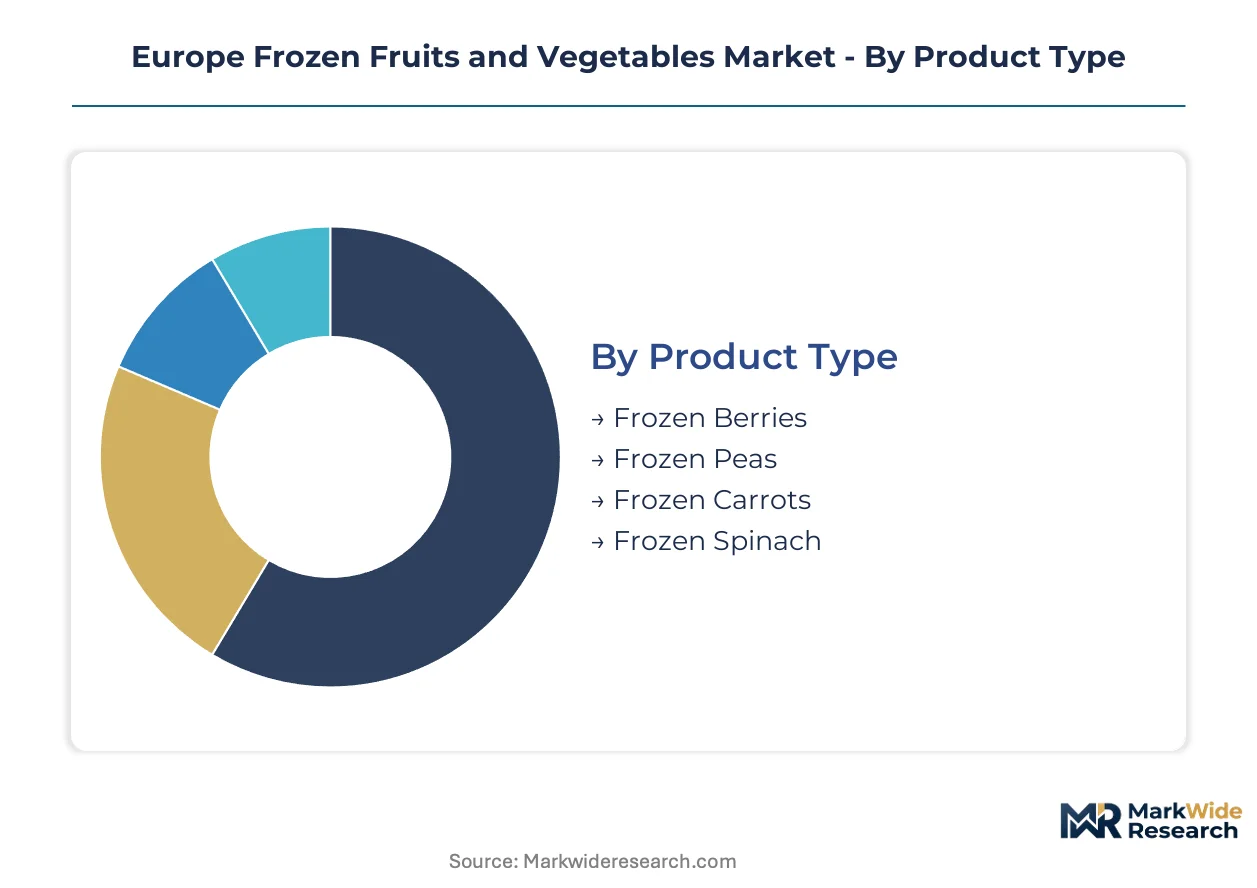
Segmentation in Europe frozen fruits and vegetables determines which processors qualify for foodservice tenders and retail private-label contracts. EFSA safety protocols, organic certifications, and national packaging directives create divergent compliance burdens across product categories and distribution channels.
Product Type:
EFSA frozen produce safety protocols apply universally, yet organic certification and carbon-accounting documentation requirements vary sharply by product type and sourcing geography.
- Frozen Berries:IQF strawberries, raspberries, and blueberries preserved at minus eighteen degrees Celsius. Demand concentrates in German and French retail chains for smoothie and bakery applications, with Polish and Serbian sourcing concentration creating procurement vulnerability during adverse weather. EFSA organic certification and EU Green Deal carbon-border documentation add fifteen to twenty percent administrative overhead for North African imports.
- Frozen Peas:Blanched garden peas and petit pois varieties flash-frozen to maintain texture parity. Foodservice operators across Italy and Spain standardize procurement specifications to reduce kitchen labor, with Belgian and Dutch processing facilities capturing volume through BRC and IFS multi-site certifications.
- Frozen Carrots:Diced, sliced, and crinkle-cut carrot products for institutional catering. German Verpackungsgesetz recycled-content thresholds apply to polypropylene retail bags.
- Frozen Spinach:Leaf and chopped spinach products for ready-meal manufacturing. France's national packaging directive mandates minimum recycled content for polyethylene terephthalate trays.
Leading the category by volume: Frozen Peas. Growing fastest: Frozen Berries.
End User:
Cost tier stratification separates mass-volume foodservice procurement from premium retail margin pools, with certification requirements scaling accordingly.
- Retail Chains:Supermarket and hypermarket private-label and branded bag formats. Western European retailers phase in recycled-content packaging specifications ahead of France and Germany legal deadlines, compressing processor margin structures.
- Foodservice:Institutional catering chains, quick-service restaurants, and hospitality groups. Pan-European buying groups consolidate supplier relationships around processors holding BRC, IFS, and organic certifications across multiple production sites.
- Manufacturers:Ready-meal and soup processors sourcing frozen vegetable inputs. EMA-aligned cold-chain documentation standards complicate cross-border shipment protocols at Polish-German frontiers.
- Households:Direct consumer purchases through retail and online channels. Online retail expansion in Romania and Bulgaria drives cold-chain infrastructure investment beyond capital cities.
Highest margin capture: Retail Chains. Fastest volume expansion: Foodservice.
Distribution Channel:
Geography determines cold-chain fulfillment capabilities and stockout frequency, with urban density shaping channel economics.
- Supermarkets:Traditional hypermarket and supermarket frozen food aisles. Benelux corridor cross-border logistics integration enables single-source supply to chains operating in Belgium, Netherlands, and Luxembourg.
- Online Retail:E-commerce platforms with cold-chain last-mile delivery. German and French markets lead platform investment in temperature-controlled fulfillment centers.
- Wholesale:Cash-and-carry and dedicated foodservice distributors. Eastern European wholesale networks expand frozen vegetable penetration as modern trade formats grow.
- Convenience Stores:Small-format urban retail with limited frozen capacity. Convenience channel growth concentrates in Italian and Spanish metropolitan areas.
Dominant volume channel: Supermarkets. Steepest expansion trajectory: Online Retail.
Packaging Type:
Margin structure correlates with packaging complexity, with sustainability verification requirements reshaping competitive positioning.
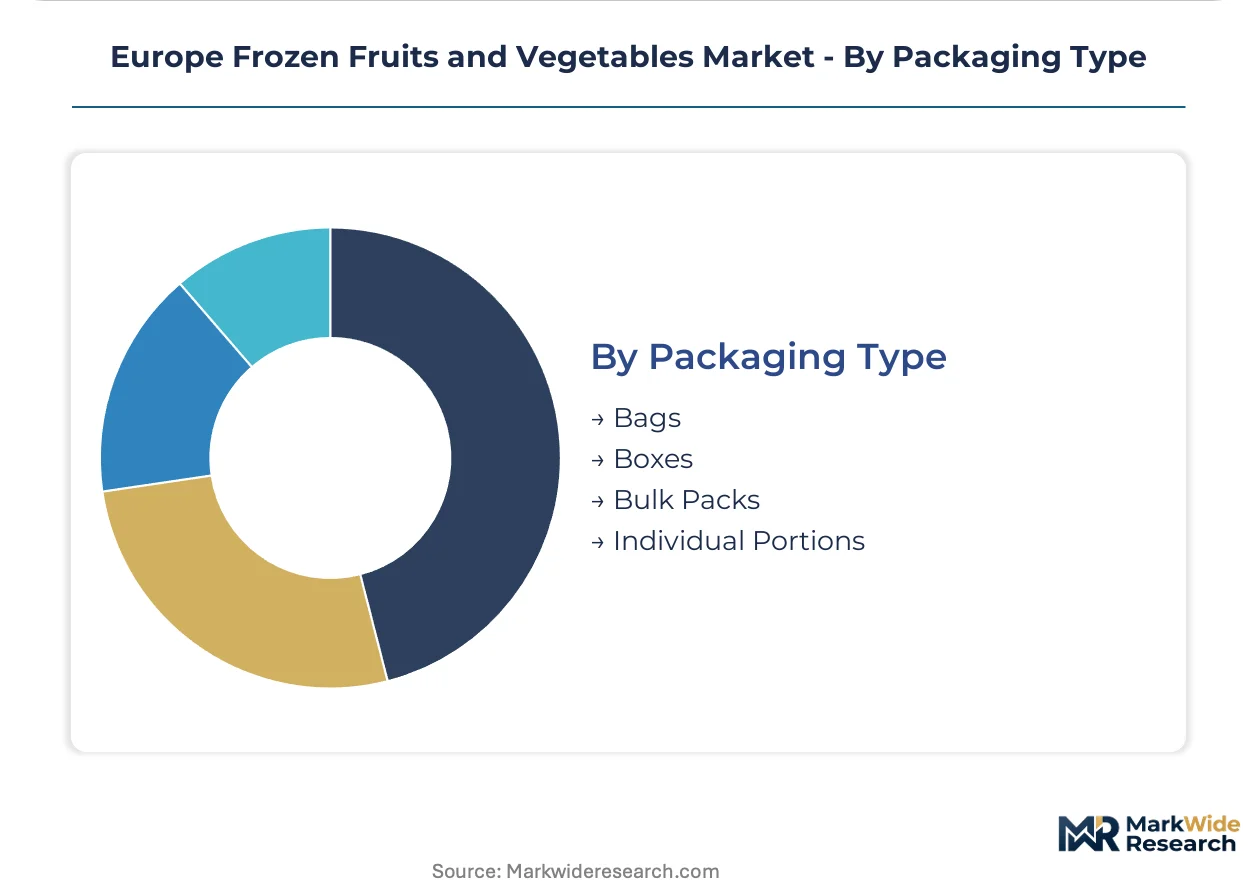
- Bags:Polypropylene and polyethylene flexible pouches for retail vegetable blends. Germany's Verpackungsgesetz amendments mandate minimum recycled content thresholds, with EFSA safety protocols extending approval timelines for innovative barrier films.
- Boxes:Paperboard cartons for premium berry and vegetable presentations. French national packaging directive recycled-content requirements apply.
- Bulk Packs:Large-format polypropylene sacks for foodservice and manufacturing procurement. Reduced packaging intensity lowers per-unit compliance costs.
- Individual Portions:Single-serve polyethylene terephthalate trays for convenience-oriented retail. Compostable packaging rollouts face delays as processors seek shelf-life parity with conventional plastics.
Highest volume format: Bags. Gaining share fastest: Individual Portions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux processing clusters attract frozen produce investment through EU Green Deal carbon-accounting incentives and cross-border logistics integration. Cold-chain infrastructure expansion concentrates in port-adjacent zones with renewable energy access.
Germany
Foodservice operator consolidation drives frozen vegetable procurement standardization across institutional catering chains. Germany's Verpackungsgesetz amendments mandate recycled-content thresholds for retail packaging. Processing activity clusters in Lower Saxony near Bremen port facilities.
France
Retail chains phase in sustainable packaging specifications ahead of national directive deadlines. France's national packaging directive imposes minimum recycled content requirements on polyethylene terephthalate trays. The Hauts-de-France region anchors berry processing capacity near Calais logistics corridors.
Poland
IQF strawberry and raspberry sourcing concentration creates procurement vulnerability during adverse weather cycles. Polish national agricultural regulators enforce EFSA-aligned phytosanitary documentation for cross-border shipments. Processing facilities concentrate in Greater Poland Voivodeship near Poznań distribution hubs.
Belgium
Ardo Group leverages Belgian processing footprint for year-round berry volume sustainability. EU Green Deal carbon-border adjustment mechanisms elevate frozen produce competitiveness against air-freighted alternatives. The Flanders region hosts blast-freezing facilities with integrated heat recovery systems.
Netherlands
Dutch processing facilities achieve texture parity with fresh produce through IQF technology maturation. EMA-aligned cold-chain documentation standards complicate organic-certified berry cross-border protocols. Rotterdam port logistics enable single-source supply to Benelux restaurant chains.
Europe Frozen Fruits and Vegetables Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across frozen produce supply tiers. The vendor base organizes around three strategic archetypes: multinational packaged food conglomerates with frozen divisions, dedicated frozen vegetable and fruit processors, and private-label contract manufacturers serving retail chains. Consolidation pressures favor players with multi-country BRC and IFS certification coverage. Capacity expansion and sustainability verification investments represent the dominant competitive moves reshaping positioning.
Among Belgium-based processors, Ardo Group exemplifies the dedicated frozen produce specialist archetype through its year-round berry processing concentration. Bonduelle occupies a position within the French-dominated vegetable processing tier. Nestlé S.A. represents the diversified conglomerate archetype with private-label and branded presence across multiple European retail channels.
| Leading Market Players |
|---|
| Ardo Group |
| Unilever PLC |
| Nomad Foods |
| Bonduelle |
| McCain Foods |
| Greenyard Foods |
| Nestlé S.A. |
| Grupo Virto |
| FRoSTA AG |
| Others |
Cost & Logistics Intelligence
Polish and Serbian IQF strawberry price indices cascade through European frozen berry supply chains, compressing margin structures for processors without backward integration into raw material sourcing. The concentration of raspberry cultivation in Greater Poland Voivodeship and Serbian agricultural belts funnels pricing power toward upstream growers during adverse weather cycles, forcing downstream buyers into premium spot markets or long-term offtake commitments.
Pricing Analysis
Short lead-time premiums dominate frozen vegetable procurement contracts, with foodservice operators paying fifteen to twenty percent above baseline for just-in-time delivery guarantees against standard thirty-day forward contracts. Three-tier pricing structure across premium organic-certified, standard BRC-IFS compliant, and economy private-label tiers separates margin pools, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from energy cost volatility in German and Italian blast-freezing operations, squeezing independent processors without renewable power purchase agreements. Retail chains exhibit highest price sensitivity due to private-label margin compression, while pan-European foodservice buying groups absorb premiums for multi-site certification coverage.
Supply Chain Analysis
Refrigeration engineering talent scarcity in Belgian and Dutch processing hubs constrains capacity expansion timelines, with ammonia-based cooling expertise aging out faster than vocational training pipelines replenish. Geographic supply concentrates in Poland, Serbia, and Belgium for IQF berry raw material, with Belgian and Dutch facilities dominating prepared vegetable processing. Raw material dependencies center on seasonal strawberry and raspberry harvests, natural gas for blast-freezing energy input, and polyethylene terephthalate for retail tray packaging. Single-source vulnerability in Polish-Serbian berry sourcing creates procurement risk during frost events and drought cycles. Distribution runs through Rotterdam and Bremen port-adjacent cold-chain hubs, with cross-border logistics integration enabling single-source supply to Benelux restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a supply-constrained story where blast-freezing capacity bottlenecks in Benelux and cold-chain engineering talent scarcity prop pricing power toward incumbent processors with certified multi-site footprints.
For Market Incumbents: Extend certification coverage into regenerative agriculture sourcing and CSRD-aligned Scope 3 emissions verification to capture first-mover advantage in sustainability disclosure mandates. Expand blast-freezing capacity in Flanders and Lower Saxony regions with integrated heat recovery systems to defend margin position against energy cost volatility. Deepen backward integration into Polish and Serbian berry cultivation through contract farming arrangements to reduce single-source weather vulnerability.
For New Entrants and Emerging Players: Quick-service restaurant groups in Romania, Bulgaria, and Hungary represent the most penetrable buyer archetype as modern trade formats expand cold-chain infrastructure beyond capital cities. Capture white-space in Eastern European retail underpenetration by establishing wholesale distribution partnerships with cash-and-carry networks before supermarket chains consolidate frozen vegetable shelf space. Lead with plant-based protein convergence positioning, supplying frozen pea and fava bean isolates to meat-alternative manufacturers seeking clean-label texturized vegetable bases.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Belgian and Dutch processors with BRC-IFS multi-site certifications and renewable energy purchase agreements, as margin compression forces independent single-facility operators toward contract manufacturing arrangements. Long-term viability over the next decade hinges on sustainability verification infrastructure and regenerative agriculture sourcing relationships that satisfy tightening EU Green Deal carbon-accounting requirements. Watch for inflection in carbon-border adjustment mechanism implementation timelines, which would accelerate frozen produce competitiveness against air-freighted fresh alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Berry Cultivation | Contract farming in Poland and Serbia reduces weather-driven procurement vulnerability for IQF strawberry supply. |
| Heat Recovery System Retrofit | Belgian and Dutch blast-freezing facilities capture waste thermal energy to pre-wash water systems, compressing operating cost differentials. |
| CSRD-Aligned Sustainability Disclosure | Verified Scope 3 emissions data unlocks first-mover positioning as EU Corporate Sustainability Reporting Directive mandates expand. |
| Eastern European Distribution Expansion | Romanian and Bulgarian wholesale network partnerships capture frozen vegetable volume growth as modern trade formats extend cold-chain reach. |
| Plant-Based Protein Isolate Development | Frozen pea and fava bean processors supply clean-label protein bases to meat-alternative manufacturers converging on frozen vegetable supply chains. |
Research Approach
EFSA safety protocol documentation, EU Green Deal regulatory filings, and national packaging directive amendments from France and Germany formed the secondary backbone for compliance requirement mapping. Primary interviews with frozen produce procurement managers at pan-European foodservice buying groups, plant operations directors at Belgian and Dutch processing facilities, and category buyers at Western European retail chains combined with customs trade data and SEC filings from diversified conglomerates with frozen divisions. Bottom-up volume triangulation across product type, end user, and distribution channel segments validated against top-down market sizing from cold-chain infrastructure investment disclosures.
Historical trendline analysis of frozen berry and vegetable volume flows through Rotterdam and Bremen port facilities established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including product type matrix, end-user cost tier stratification, distribution channel cold-chain fulfillment capability, and packaging type sustainability verification intensity. CAGRs derived from regression analysis of historical volume data adjusted for regulatory inflection points and technology substitution effects, with IQF technology maturation curves and carbon-border adjustment mechanism implementation timelines as key forecast inputs.
Revisions become necessary when EMA-aligned cold-chain documentation standards tighten cross-border shipment protocols, energy cost volatility in German and Italian processing hubs exceeds historical bands, or carbon-border adjustment mechanisms accelerate implementation timelines beyond baseline assumptions. Material deviation in these triggers warrants pause and re-evaluation of volume and value projections across the analysis window.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Dried Grapes Market