
 Fabric Protection Market | 2026-2036
Fabric Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Protection Market Insights
Silicone-based formulations is expanding its share in fabric protection as manufacturers phase out long-chain fluorocarbons on cost and compliance grounds. 3M leverages its Scotchguard heritage to sustain brand recognition in commercial channels. RPM International anchors its position through Rust-Oleum's retail shelf dominance in North American home improvement stores. SC Johnson competes on volume through mass-market aerosol distribution.
Fabric protection encompasses chemical treatments applied to textiles to impart water repellency, oil resistance, and stain blocking, typically involving fluoropolymer, silicone, or hydrocarbon active ingredients at 2-8% solids concentration with spray application rates of 3-5 ounces per square yard. The chemistry serves industrial laundries, furniture manufacturers, and automotive tier-one suppliers seeking to extend material service life. Sprays occupy the largest revenue pool in product type segmentation due to consumer familiarity and immediate availability, while liquid solutions gain traction in textile finishing mills pursuing inline application efficiency. The hospitality end user segment commands premium pricing through contract specifications requiring certified performance against wine, coffee, and grease staining protocols.
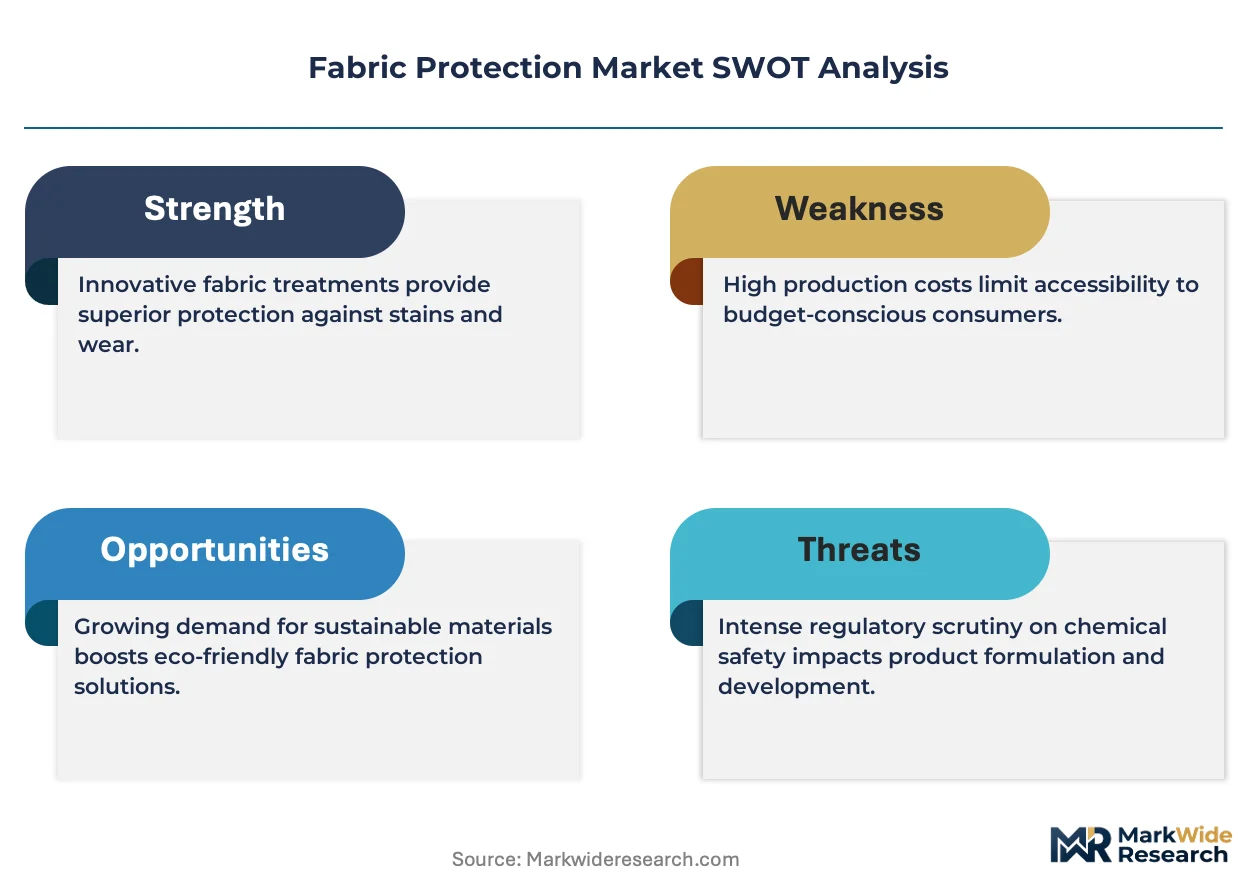
EPA Safer Choice certification and REACH restrictions on per- and polyfluoroalkyl substances in Europe constrain formulation options and accelerate reformulation timelines for suppliers seeking cross-border market access. The EU Green Deal's chemical sustainability targets further pressure manufacturers to demonstrate biodegradability and reduced toxicity profiles in next-generation products. China's GB standards for textile safety and volatile organic compound emissions add compliance layers for imports entering the country's apparel and upholstery supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and determine where regional formulation specialization outperforms unified global product platforms.
Market Dynamics
Fluorine-free chemistry migration is compressing formulation cycles as mills retool finishing lines to meet EPA Safer Choice and REACH compliance deadlines simultaneously. This regulatory overlay is forcing dual-track R&D investment and fragmenting raw material sourcing strategies across supplier networks.
Growth Catalysts
- REACH PFAS restrictions:European chemical phase-outs are accelerating silicone-based formulation demand as mills seek compliant drop-in replacements for legacy fluorocarbon treatments.
- Automotive upholstery specifications:Tier-one seating suppliers now mandate stain-resistant fabric performance under OEM warranty terms, embedding protection chemistry into original equipment contracts.
- China's textile manufacturing belt:Mills in Zhejiang and Jiangsu provinces are integrating inline finishing systems that apply protection chemistry during dyeing operations, reducing standalone treatment costs.
Market Restraints
- Silicone feedstock volatility:Organosilicon precursor prices fluctuate with energy costs at Chinese chlor-alkali complexes, squeezing margin stability for formulated product suppliers.
- Performance gap in oil repellency:Fluorine-free alternatives fail to match C8 fluorocarbon benchmarks on grease and oil resistance, limiting adoption in food service and industrial uniform segments.
- Dual certification burden:Suppliers must validate formulations separately under EPA Safer Choice and EU Green Deal biodegradability protocols, extending time-to-market by 12-18 months.
Strategic Opportunities
- India apparel export compliance:Tirupur and Surat textile clusters face EU import restrictions on untreated fabrics, creating first-mover advantage for certified protection chemistry suppliers.
- Digital printing convergence:Mills adopting single-pass inkjet systems require compatible low-temperature cure protection treatments, opening formulation white space.
- Extended producer responsibility schemes:France's AGEC law and similar frameworks in Germany mandate fabric durability labeling, indirectly incentivizing protection treatment uptake.
Industry Challenges
- Formulation chemist scarcity:Expertise in fluorine-free polymer design concentrates at legacy fluorochemical houses, creating recruitment competition during retooling phases.
- Mill equipment retrofit costs:Inline application systems require pad-dry-cure line modifications costing $2-4 million per facility, slowing adoption at mid-scale operations.
- Cross-border inventory stranding:Divergent regulatory timelines between EPA and ECHA create formulation versioning complexity, risking obsolete stock in transatlantic distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Protection Market |
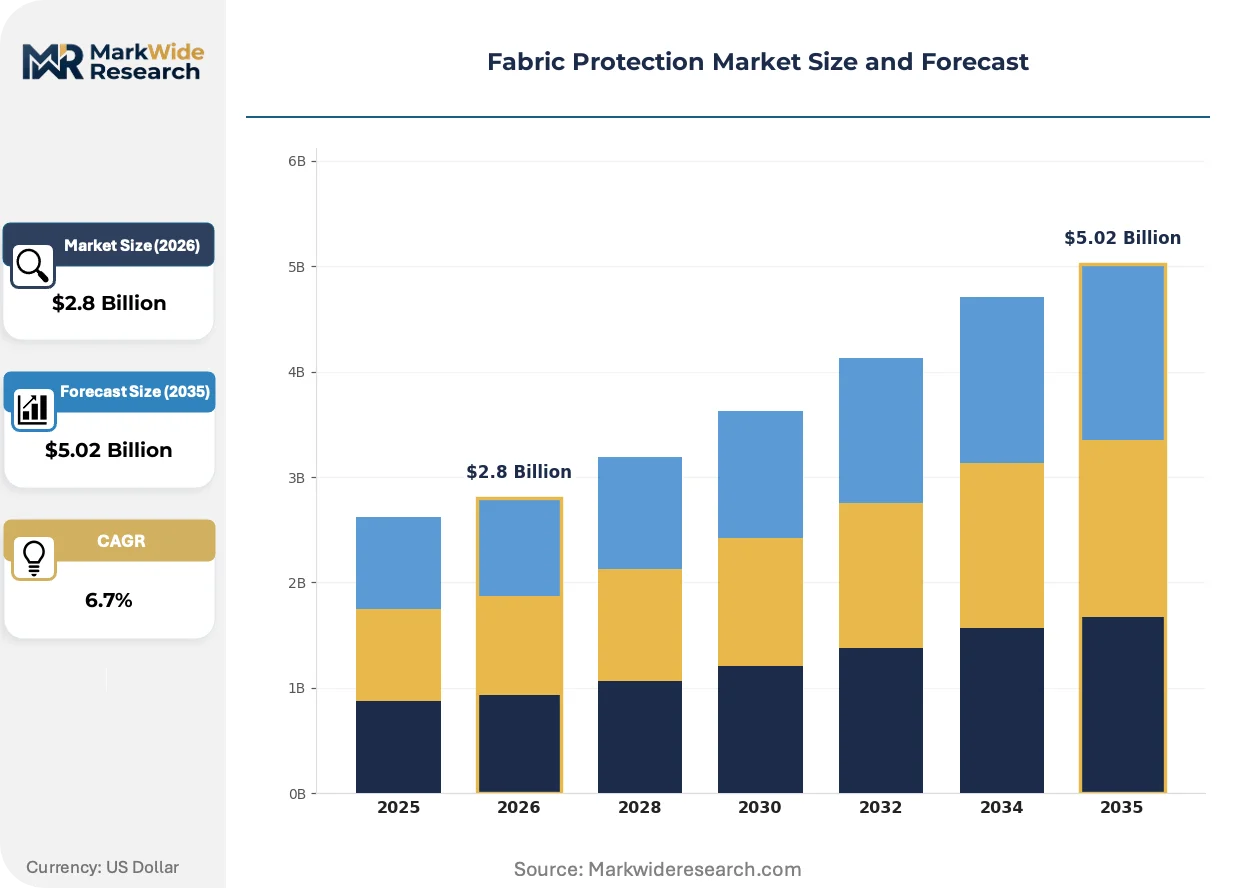
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Liquid Solutions, Coatings, Wipes Application: Textile, Upholstery, Carpet, Leather End User: Residential, Commercial, Automotive, Hospitality Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | 3M, RPM International, Guardsman, Shield Industries, Vectra, Actichem, Ultra-Guard, SC Johnson, Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Protection Market Trends and Innovations
Active chemistry platforms are bifurcating between high-performance fluorinated systems for specialized industrial use and bio-based alternatives for consumer-facing applications. This divergence is reshaping R&D allocation and supplier positioning across the value chain.
Hybrid silicone-fluoropolymer blends are integrating nano-scale particle dispersion to bridge the performance gap between legacy C6 chemistry and pure silicone alternatives. Automotive seating engineers at major OEMs are piloting these intermediate formulations for mid-tier vehicle lines where full fluorine-free performance remains unacceptable. The technology is integrating performance benchmarking into supplier qualification protocols that previously relied on single-chemistry pass-fail criteria.
EPA Safer Choice certification expansion into industrial laundry chemicals is tightening disclosure requirements for fabric protection additives used in rental uniform programs. Industrial launderers serving hospitality and healthcare sectors must now document treatment chemistry in sustainability reports under CSRD-aligned client mandates. European contract textile laundries are responding by consolidating supplier relationships to reduce certification audit burden.
Specification-driven procurement is consolidating buyer power among hospitality procurement consortia and automotive OEM material boards. These centralized purchasing functions are displacing mill-level chemical selection with approved-supplier lists vetted for regulatory pre-compliance. Hotel chains in the United States and Germany are most advanced in this transition, using consolidated chemical specifications to streamline cross-border property outfitting.
Fabric Protection Market Segmentation
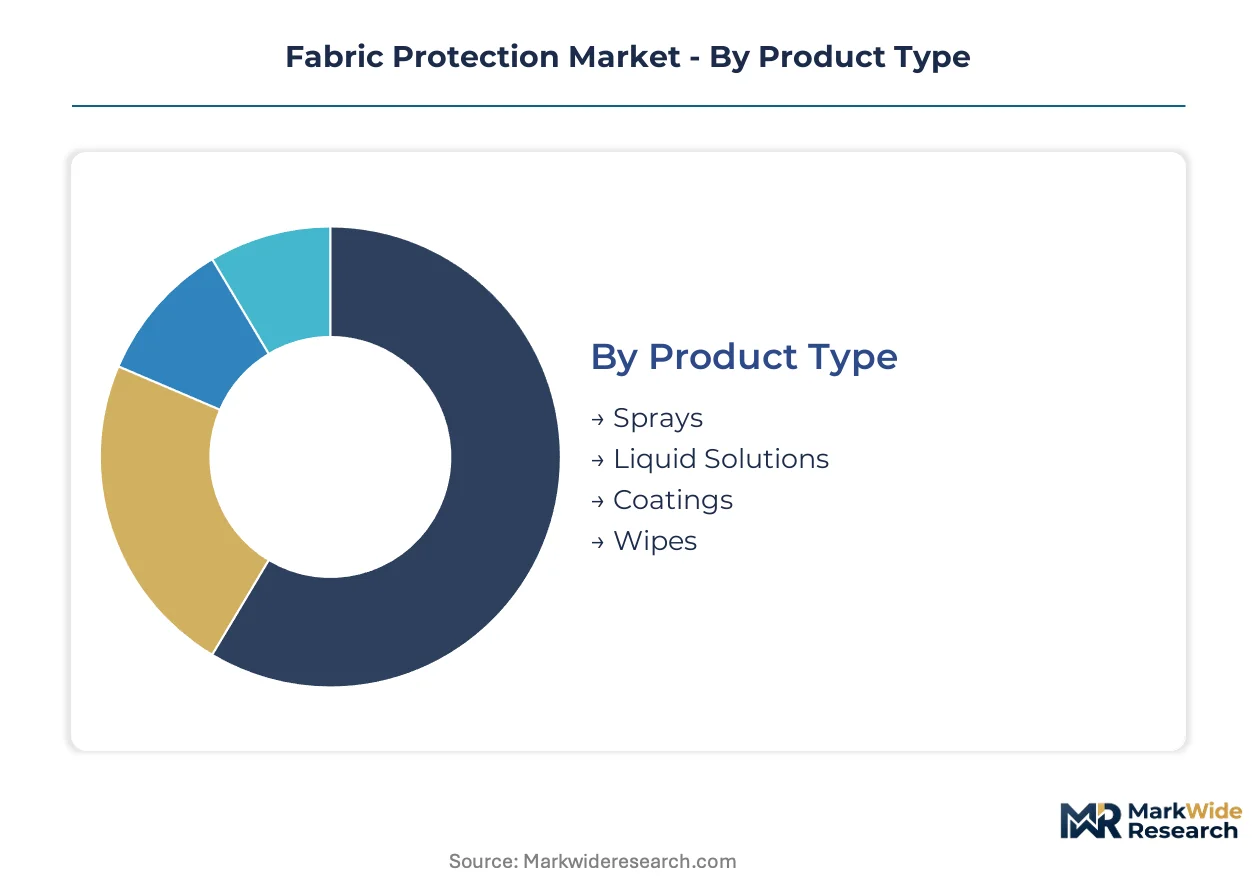
Fabric protection chemistry fragments across application methods, material substrates, and procurement channels. Each segment carries distinct capital requirements, regulatory exposure, and margin profiles that determine supplier positioning strategies.
Product Type:
Sprays demand the lowest upfront manufacturing investment with standard aerosol filling lines, while inline coatings require multi-million dollar finishing system retrofits at textile mills.
- Sprays:Aerosol and trigger-spray formats deliver 2-8% active ingredient suspensions in hydrocarbon or water-based carriers. Hospitality procurement consortia in the United States specify spray formats for property-wide furniture treatment contracts due to application flexibility and immediate availability.
- Liquid Solutions:Concentrated formulations designed for industrial pad-dry-cure finishing lines integrate directly into textile mill operations. Zhejiang and Jiangsu province mills in China's manufacturing belt are converting standalone treatment facilities to inline systems, reducing per-meter processing costs.
- Coatings:Factory-applied finishes bond at molecular level during fiber production. Automotive seating suppliers mandate coating-grade protection under OEM warranty terms for original equipment contracts.
- Wipes:Pre-saturated substrate formats target spot-treatment and maintenance applications. Retail shelf space constraints limit distribution primarily to specialty stores and online channels.
Most installed capacity flows through Sprays. Expansion is steepest in Liquid Solutions.
Application:
Capital deployment varies sharply by substrate complexity, with leather requiring specialized curing equipment and textile finishing demanding the largest continuous processing volumes.
- Textile:Woven and nonwoven fabrics receive protection during dyeing or as post-process finishing. India's Tirupur and Surat apparel clusters face EU import restrictions on untreated fabrics, accelerating certified treatment adoption for export compliance.
- Upholstery:Residential and contract furniture applications combine spray maintenance with mill-applied base protection. EPA Safer Choice guidelines now govern hospitality operator specifications in the United States.
- Carpet:Solution-dyed fiber integration and topical treatments serve residential and commercial installation markets. Performance benchmarking for stain resistance follows separate protocols from flat textile applications.
- Leather:Aniline and semi-aniline finishes require compatible chemistry that preserves tactile properties. Automotive tier-one suppliers specify leather protection under extended warranty programs.
Volume concentrates in Textile applications. Upholstery gains share fastest through hospitality specification consolidation.
End User:
Procurement sophistication determines segment attractiveness, with automotive and hospitality buyers imposing qualification protocols that exclude commodity suppliers.
- Residential:DIY consumers purchase through retail and online channels, prioritizing convenience over technical performance metrics. Mass-market aerosol distribution dominates this segment.
- Commercial:Facility managers and industrial laundries specify protection for rental uniform and contract furniture programs. CSRD-aligned client mandates now require documented treatment chemistry in sustainability reporting.
- Automotive:OEM material boards and tier-one seating suppliers mandate stain-resistant fabric performance under warranty terms. Protection chemistry embeds into original equipment supply contracts.
- Hospitality:Hotel chains in the United States and Germany deploy consolidated chemical specifications across cross-border property portfolios. Procurement consortia displace mill-level chemical selection with approved-supplier lists.
Commercial end users deploy the largest treatment volumes. Hospitality represents the steepest expansion trajectory through specification-driven procurement consolidation.
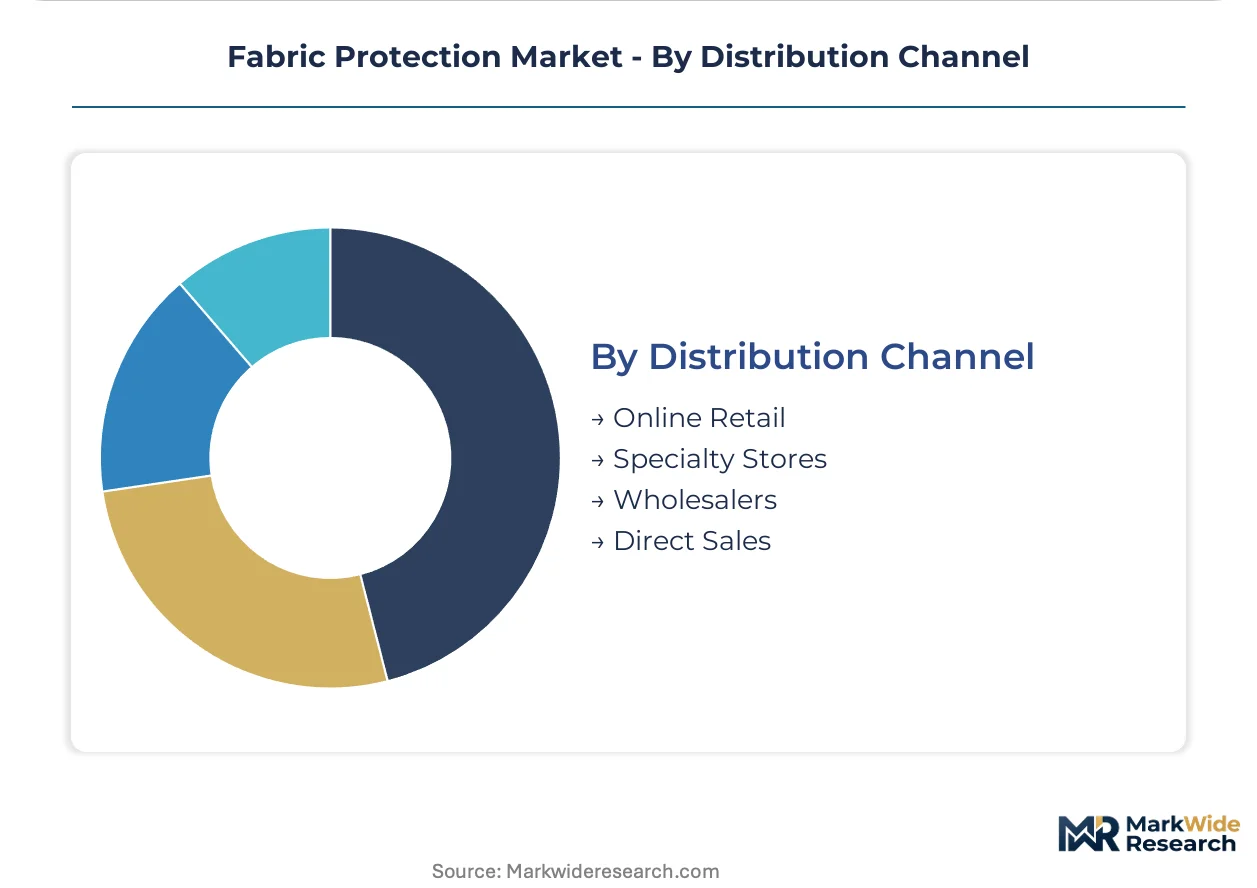
Distribution Channel:
Channel economics reflect working capital intensity and technical support requirements, with direct sales demanding dedicated technical service teams and online retail minimizing inventory carrying costs.
- Online Retail:E-commerce platforms aggregate consumer and small commercial demand with minimal technical consultation. Product differentiation relies on brand recognition and review velocity.
- Specialty Stores:Home improvement and fabric care retailers provide tactile product demonstration and immediate fulfillment. Rust-Oleum's retail shelf dominance in North American channels anchors this segment.
- Wholesalers:Industrial chemical distributors serve textile mills and commercial laundries with bulk formulation supply. REACH and EPA Safer Choice certification documentation accompanies shipments to qualified buyers.
- Direct Sales:Supplier technical teams engage automotive OEMs and hospitality procurement consortia for specification development and line qualification. Extended sales cycles accompany multi-year contract structures.
Wholesalers move the largest product volumes. Direct Sales expands most quickly through automotive and hospitality specification consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Jiangsu provinces anchor fabric protection demand through China's textile manufacturing belt, where mills integrate inline finishing systems. The United States, Germany, India, and Japan concentrate distinct regulatory and industrial drivers across hospitality, automotive, and apparel export segments.
United States
Hospitality procurement consortia specify fluorine-free formulations under EPA Safer Choice guidelines for cross-border property outfitting. The EPA's industrial laundry chemical certification expansion tightens disclosure requirements for rental uniform programs. Mills in North Carolina's furniture manufacturing corridor adapt spray-application contracts to meet consolidated chemical specifications from hotel chains.
Germany
Automotive OEM material boards mandate stain-resistant fabric performance under extended warranty terms for tier-one seating suppliers. The EU Green Deal's chemical sustainability targets pressure manufacturers to demonstrate biodegradability in next-generation products. Bavaria's automotive component clusters pilot hybrid silicone-fluoropolymer blends for mid-tier vehicle lines.
China
Textile mills in Zhejiang and Jiangsu provinces convert standalone treatment facilities to inline pad-dry-cure systems, reducing per-meter processing costs. GB standards for textile safety and volatile organic compound emissions add compliance layers for import supply chains. The Yangtze River Delta manufacturing belt concentrates finishing chemistry integration during dyeing operations.
India
Tirupur and Surat apparel clusters face EU import restrictions on untreated fabrics, accelerating certified protection chemistry adoption for export compliance. The Bureau of Indian Standards monitors textile safety protocols for international market access. Maharashtra's industrial laundries serving hospitality sectors consolidate supplier relationships to reduce certification audit burdens.
Japan
Automotive seating engineers at major OEMs pilot intermediate formulation platforms bridging C6 chemistry and pure silicone alternatives. METI oversees chemical management frameworks aligned with international sustainability reporting standards. Osaka-based textile finishers develop low-temperature cure treatments compatible with single-pass inkjet printing systems.
Fabric Protection Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution channel access. The vendor base organizes around three tiers: diversified chemical conglomerates with aerosol heritage, specialized fabric treatment houses, and mill-direct industrial suppliers. Strategic moves concentrate on dual-track R&D investment for fluorine-free compliance and specification-driven procurement consolidation in hospitality and automotive verticals.
Within the diversified chemical tier, 3M leverages Scotchguard brand recognition in commercial channels, while RPM International anchors retail shelf presence through Rust-Oleum's North American home improvement store network. SC Johnson occupies the mass-market aerosol distribution vector. These three exemplify how heritage brands defend position through channel-specific dominance rather than chemistry innovation alone.
| Leading Market Players |
|---|
| 3M |
| RPM International |
| Guardsman |
| Shield Industries |
| Vectra |
| Actichem |
| Ultra-Guard |
| SC Johnson |
| Chemours Company |
| Others |
Pricing and Supply Chain Analysis
Organosilicon precursor indices at Chinese chlor-alkali complexes cascade through formulated product pricing tiers, compressing margins for silicone-based fabric protection suppliers while fluorine-free certification premiums sustain value capture in hospitality and automotive contract channels.
Pricing Analysis
Input-cost pass-through from silicone feedstock volatility fragments pricing power across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates EPA Safer Choice-certified formulations from uncertified alternatives and commodity hydrocarbon sprays. Price differentiation rests on certification grade and volume scale, with mill-direct liquid solutions commanding premiums over retail aerosol formats. Cost compression in standard-tier silicone formulations is intensifying because of energy price swings at Zhejiang chemical complexes. DIY residential consumers exhibit highest price sensitivity, while automotive OEM material boards demonstrate lowest sensitivity due to warranty compliance requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for formulated product delivery to textile mills and hospitality procurement consortia. Manufacturing concentrates in China, Germany, and the United States, with Zhejiang and Jiangsu provinces hosting inline finishing system integration. Raw material sourcing draws from organosilicon precursors, fluoropolymer intermediates, and hydrocarbon carriers. Single-source vulnerability from Chinese chlor-alkali complex concentration threatens margin stability. Distribution runs through industrial chemical wholesalers serving mill-direct accounts, supplemented by retail channel penetration for consumer spray formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fabric protection chemistry rewards geographic arbitrage between REACH-regulated European markets and EPA-guided North American specifications, with compliance cost differentials creating margin expansion opportunities for dual-certified suppliers.
For Market Incumbents: Acquire formulation chemist expertise pools from legacy fluorochemical houses to accelerate fluorine-free R&D timelines. Consolidate supplier relationships with Zhejiang and Jiangsu mills before mid-scale competitors complete pad-dry-cure retrofits. Defensive positioning against silicone feedstock volatility demands backward integration into organosilicon precursor sourcing or long-term offtake agreements with Chinese chlor-alkali producers. For New Entrants and Emerging Players: Begin with India's Tirupur and Surat apparel clusters facing EU import restrictions on untreated fabrics, where first-mover certification advantage remains unclaimed. Target digital printing convergence opportunities in Japan and Germany, where single-pass inkjet systems require compatible low-temperature cure treatments lacking established supply relationships. Channel entry through industrial laundry chemical distributors serving CSRD-aligned hospitality clients offers lowest customer acquisition friction. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fabric treatment houses possessing EPA Safer Choice pre-certification and existing automotive OEM qualification protocols. Long-term viability over the projection horizon favors suppliers with demonstrated biodegradability profiles under EU Green Deal frameworks. Monitor ECHA PFAS restriction timeline acceleration as inflection indicator for silicone-based formulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Precursors | Captive supply of silicone feedstock insulates margin stability from Zhejiang energy price volatility. |
| Dual Certification Investment | Simultaneous EPA Safer Choice and EU Green Deal validation accelerates cross-border market access timelines. |
| Mill-Direct Technical Service Expansion | Dedicated finishing line qualification teams secure specification-driven procurement consolidation in hospitality. |
| Hybrid Formulation Development | Silicone-fluoropolymer nano-dispersion bridges performance gaps for automotive mid-tier seating contracts. |
| Regional Distribution Hub Consolidation | Rotterdam and Singapore center consolidation reduces cross-border inventory stranding from regulatory divergence. |
Research Methodology
Multiple input streams — primary interviews with textile mill technical directors, hospitality procurement consortium leads, and automotive OEM material engineers; secondary validation through customs trade data, EPA Safer Choice certified product registries, and ECHA restriction proposal documentation — were reconciled through bottom-up segment sizing and top-down market reconciliation.
Historical volume trajectories were cross-referenced against expert panel inputs across product type, application substrate, end-user vertical, and distribution channel segmentation dimensions. CAGRs were derived from regression analysis of installed finishing line capacity, regulatory compliance deadline clustering, and substitution elasticity between fluorinated and fluorine-free chemistries.
Several conditions sit outside the modeled scope, including unannounced ECHA PFAS restriction accelerations, abrupt chlor-alkali complex shutdowns, and automotive OEM warranty term revisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Global Industrial Protective Clothing Fabrics Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
North America Western Wear Market