
 Water-Proof Dust Covers Market | 2026-2036
Water-Proof Dust Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Proof Dust Covers Market Insights
Chinese textile and polymer converter capacity is hardening as domestic producers scale laminated fabric output for export-grade dust covers. Everest Case leverages vertical manufacturing to control polyethylene supply chains from resin to finished tarp. Bai Er Rui Trade Co., Limited anchors its position through dedicated export channels serving European industrial distributors. Garnetics Outdoor differentiates via specialized outdoor equipment covers engineered for UV and moisture resistance.
Water-proof dust covers are laminated or coated fabric barriers engineered to specific hydrostatic head ratings, typically constructed from polyethylene, vinyl, canvas, or polyester substrates with heat-sealed seams to block particulate intrusion and liquid penetration. Their primary purpose spans industrial storage protection, automotive surface preservation, and outdoor equipment longevity across commercial and consumer settings. Tarps and bags capture the bulk of volume demand from construction and logistics end users, while custom-sized solutions command premium positioning in aerospace and precision machinery applications. Vinyl and polyethylene materials dominate industrial procurement due to cost efficiency and chemical resistance, though canvas and polyester variants sustain niche demand where breathability and abrasion tolerance matter.
FDA regulations govern food-contact storage covers, EPA frameworks shape material disposal and recyclability mandates, and REACH compliance in Europe restricts phthalate plasticizers in vinyl formulations. These standards compel manufacturers to reformulate coatings and document supply chain chemistry to maintain market access. Stakeholders must monitor evolving chemical disclosure requirements and decide whether to absorb compliance costs or reposition toward material categories with lighter regulatory burden.
Market Dynamics
Automotive OEMs and aftermarket suppliers are expanding procurement of protective covers for vehicle storage and transport, tightening specification requirements around hydrostatic head ratings and seam integrity as supply chains regionalize.
Growth Catalysts
- REACH compliance in Europe:Phthalate restrictions in vinyl formulations are accelerating reformulation toward polyethylene and polyester substrates, opening premium positioning for compliant suppliers.
- Construction and logistics end users:Tarps and bags capture volume demand as infrastructure spending hardens procurement of laminated fabric barriers for equipment protection.
- Shanghai and Guangzhou manufacturing clusters:Chinese textile converter capacity scaling export-grade dust cover output is hardening supply availability for international distributors.
Market Restraints
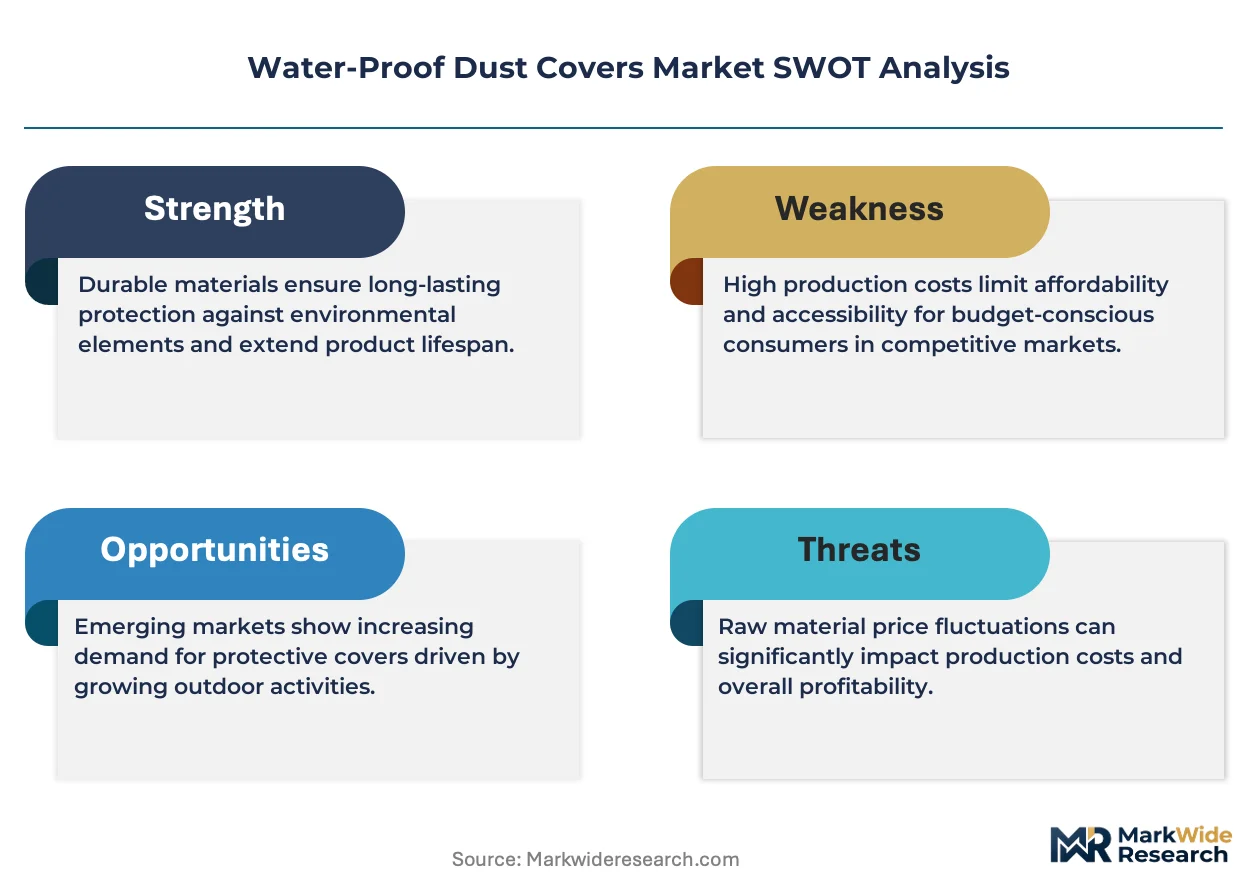
- Petrochemical input volatility:Polyethylene resin prices swing with crude oil benchmarks, compressing margin predictability for converters lacking captive supply.
- Single-source geography risk:Laminated fabric production concentrates in eastern China, exposing buyers to port congestion and tariff friction.
- Breathability-versus-barrier tradeoff:Vinyl and polyethylene formulations block moisture but trap condensation, limiting adoption for precision machinery requiring vapor transmission.
Strategic Opportunities
- EPA material recyclability guidelines:Evolving US mandates on post-consumer content create first-mover advantage for converters developing closed-loop polyethylene recovery systems.
- Aerospace and precision machinery:Custom-sized solutions command premium positioning as OEMs specify hydrostatic head ratings above standard industrial grades.
- Direct-to-industrial digital channels:Bypassing distributor markups through configured-ecommerce platforms is compressing lead times for mid-volume buyers.
Industry Challenges
- Heat-sealed seam certification timelines:Third-party validation for hydrostatic head ratings adds 8-12 weeks to new product qualification, delaying contract awards.
- Coating chemistry documentation:Full supply chain disclosure requirements under REACH and EPA frameworks strain supplier data collection capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Proof Dust Covers Market |
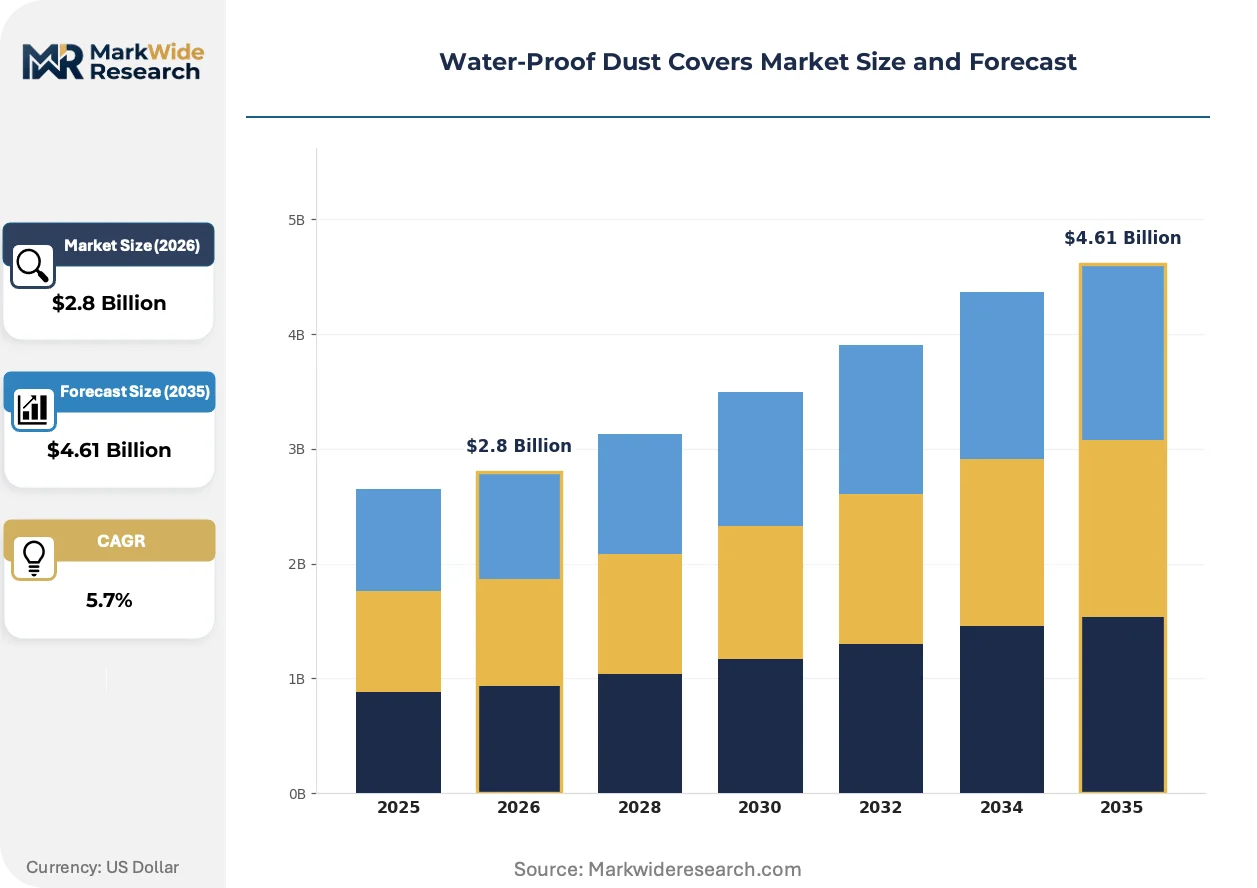
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tarps, Liners, Bags, Cloths Material: Polyethylene, Vinyl, Canvas, Polyester Application: Industrial Storage, Automotive Protection, Outdoor Equipment, Household Use Size: Small, Medium, Large, Custom |
| Companies Covered | Everest Case, Bai Er Rui Trade Co., Limited, TrueTouch, COREtec Originals, Johnson Hardwood, Garnetics Outdoor, KOLIFE, Clicks, Lish Premium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Proof Dust Covers Market Trends and Innovations
Material science advances and regulatory chemistry disclosure mandates are reshaping how converters formulate coatings and validate barrier performance. Three developments are restructuring competitive positioning.
Multi-layer coextruded polyethylene is expanding into aerospace and precision machinery applications where hydrostatic head ratings must exceed 10,000mm. Tier-one automotive suppliers are qualifying these substrates for vehicle transport covers at accelerated pace. The technology is expanding into territory previously held by heavier vinyl formulations, compressing weight and freight costs for export shipments.
REACH restrictions on phthalate plasticizers in vinyl formulations are forcing compounders toward bio-based plasticizer alternatives or substrate switching. Industrial buyers in Germany and France now require full material safety data sheet disclosure upstream to resin sources. Vinyl-dependent suppliers are responding with polyester TPU laminates that bypass restricted chemistry while maintaining chemical resistance.
Configured-to-specification digital procurement is displacing catalog-standard purchasing among mid-volume industrial buyers. Distributor portals offering real-time seam configuration and logo imprinting are capturing share from traditional stock-and-ship wholesalers. This pattern is most visible in the US and UK construction equipment rental channels where fleet standardization drives repeat specification.
Water-Proof Dust Covers Market Segmentation
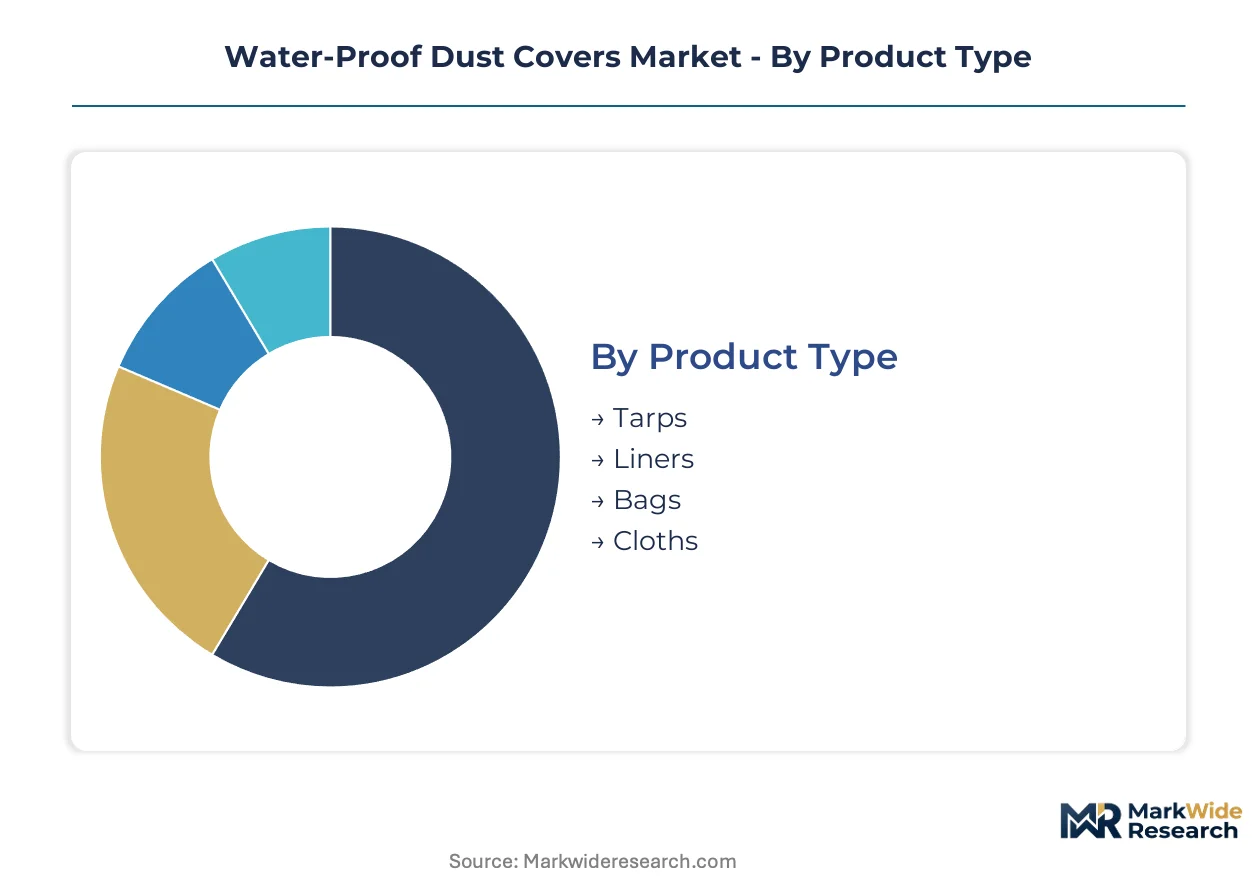
Water-proof dust cover procurement splits across performance specifications, material chemistry, and end-use durability requirements. Buyers segment demand by hydrostatic head ratings, seam certification standards, and regulatory compliance burdens that vary sharply across automotive OEMs, industrial logistics operators, and consumer channels.
Product Type:
Tarps and liners carry heavier FDA and EPA documentation burdens for food-contact and disposal compliance, while bags and cloths face lighter certification requirements in consumer channels.
- Tarps:Laminated polyethylene or vinyl sheets with heat-sealed hems and grommet reinforcement, engineered for 5,000-10,000mm hydrostatic head ratings. Construction equipment rental fleets in the US and Germany specify tarps for fleet standardization, though breathability limitations restrict adoption for precision machinery requiring condensation control.
- Liners:Form-fitted barriers for container and vessel protection, typically multi-layer coextruded constructions with RF-welded seams. Food-grade storage applications in the US trigger FDA 21 CFR compliance for resin chemistry, extending qualification timelines for converters lacking pre-certified substrate libraries.
- Bags:Enclosed configurations with drawstring or zippered closures, dominating household and light commercial channels. PE woven variants from Chinese manufacturing clusters around Shanghai serve export distributors with cost-efficient volume supply.
- Cloths:Flexible draped covers without structural rigidity, positioned for indoor surface protection where abrasion resistance matters less than dust exclusion. Canvas and polyester substrates sustain niche positioning among heritage equipment collectors and museum conservators.
Tarps sit at the top of the volume ranking, with liners climbing the fastest as food-contact and chemical storage specifications harden.
Material:
Raw material selection locks in cost structure, recyclability pathway, and regulatory exposure across EPA, REACH, and emerging state-level mandates.
- Polyethylene:Linear low-density and high-density grades dominate industrial procurement through cost efficiency and chemical inertness. Closed-loop recovery systems under evolving EPA recyclability guidelines create first-mover positioning for converters with captive regrind capabilities.
- Vinyl:PVC formulations with phthalate plasticizers face REACH restrictions in Europe, forcing compounders toward bio-based alternatives or substrate abandonment. German and French industrial buyers now require full material safety data sheet disclosure upstream to resin sources.
- Canvas:Cotton or cotton-polyester woven substrates with natural breathability, sustaining demand where vapor transmission prevents condensation damage. Heritage automotive collectors and precision machinery operators specify canvas for long-term indoor storage.
- Polyester:TPU-laminated constructions bypass REACH-restricted chemistry while maintaining chemical resistance, capturing share from vinyl in European industrial channels. Higher unit costs limit penetration in price-sensitive construction and logistics segments.
Polyethylene commands the volume base, with polyester expanding most quickly as regulatory chemistry restrictions displace vinyl formulations.
Application:
End-use segmentation determines specification intensity, with aerospace and precision machinery demanding hydrostatic head ratings that exceed standard industrial grades by 2-3x.
- Industrial Storage:Warehouse and yard protection for machinery, raw materials, and work-in-process inventory. Infrastructure spending in the US and China hardens procurement of laminated fabric barriers with accelerated depreciation schedules driving replacement cycles.
- Automotive Protection:OEM vehicle transport covers and aftermarket storage solutions, with tier-one suppliers qualifying multi-layer coextruded PE at accelerated pace. Hydrostatic head and seam integrity specifications tighten as supply chains regionalize.
- Outdoor Equipment:UV-stabilized formulations for recreational and professional gear exposure, requiring additive packages that comply with varying state-level chemical disclosure regimes. California Proposition 65 labeling obligations extend to covers with certain stabilizer chemistries.
- Household Use:Consumer-grade protection for furniture, vehicles, and seasonal items, distributed through retail and configured-ecommerce channels. Price sensitivity compresses margins, favoring converters with vertical manufacturing control over resin supply.
Industrial storage anchors revenue concentration, with automotive protection gaining share fastest as OEM qualification timelines compress.
Size:
Scale segmentation directly correlates with customization depth, certification burden, and margin structure across stock and made-to-order channels.
- Small:Standardized dimensions for consumer appliances, tools, and compact equipment. High-volume production from Guangzhou manufacturing clusters serves distributor stock-and-ship models with minimal configuration overhead.
- Medium:Mid-scale coverage for commercial vehicles, industrial machinery, and palletized goods. Configured-ecommerce platforms capture share from traditional wholesalers by offering real-time seam specification and logo imprinting.
- Large:Heavy equipment and fleet vehicle protection, often requiring reinforced hems and specialized grommet spacing. Freight cost sensitivity drives regional sourcing preferences, with US buyers favoring domestic converters for urgent replacement cycles.
- Custom:Application-specific engineering for aerospace components, precision machinery, and irregular geometries. Third-party hydrostatic head validation adds 8-12 weeks to qualification, delaying contract awards and favoring incumbents with pre-certified substrate libraries.
Medium sizes dominate transaction velocity, with custom specifications delivering the steepest margin expansion trajectory despite extended lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as converters seek cost-of-compliance advantages. REACH restrictions in Europe and EPA recyclability mandates in North America are pushing reformulation investment toward jurisdictions with lighter chemical disclosure burdens. Manufacturing clusters in eastern China absorb displaced volume from vinyl-dependent European compounders.
China
Shanghai and Guangzhou manufacturing clusters scale laminated polyethylene output for export-grade dust covers serving European industrial distributors. MIIT guidelines on dual carbon goals pressure domestic converters toward closed-loop recovery systems. Pearl River Delta fabricators expand coextruded substrate capacity to capture aerospace qualification contracts from tier-one automotive suppliers.
Germany
Industrial buyers in Bavaria and North Rhine-Westphalia now mandate full material safety data sheet disclosure upstream to resin sources under tightened ECHA enforcement. KBA automotive specifications for vehicle transport covers accelerate multi-layer PE substrate qualification. Stuttgart-area compounders develop bio-based plasticizer alternatives to bypass REACH-restricted vinyl chemistry.
United States
Construction equipment rental fleets in Texas and the Southeast drive fleet-standardized tarp procurement with hydrostatic head specifications above 5,000mm. EPA evolving guidelines on material recyclability compel converters toward post-consumer content integration. Midwest converters lacking captive polyethylene supply face margin compression from petrochemical input volatility.
Japan
Precision machinery operators in the Chubu region specify canvas and polyester substrates where vapor transmission prevents condensation damage. METI industrial storage standards harden documentation requirements for food-contact barrier applications. Osaka-area distributors capture mid-volume configured-ecommerce demand through real-time seam specification platforms.
India
Infrastructure spending in Maharashtra and Gujarat hardens procurement of laminated fabric barriers for equipment protection in warehouse and yard applications. BIS certification timelines for heat-sealed seam validation extend product qualification cycles. Tamil Nadu textile converters scale PE woven bag output for household and light commercial export channels.
Water-Proof Dust Covers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized substrate and configured-ecommerce channels. The vendor base stratifies across three maturity levels: legacy compounders with captive resin supply, mid-scale converters dependent on spot polyethylene markets, and digital-native platforms bypassing distributor markups. Two strategic archetypes dominate: vertical manufacturers controlling supply chains from resin to finished cover, and export-focused traders anchoring dedicated channels to European industrial distributors. Capacity expansion and portfolio diversification toward REACH-compliant substrates represent the dominant competitive moves as regulatory chemistry restrictions displace vinyl formulations.
Among China-based fabricators, Everest Case exemplifies vertical manufacturing archetypes with upstream control over polyethylene supply chains, while Bai Er Rui Trade Co., Limited occupies a position within the export-trader tier serving European industrial distributors. Garnetics Outdoor represents the specialization vector, sitting within the outdoor equipment cover segment where UV and moisture resistance engineering commands premium positioning.
| Leading Market Players |
|---|
| Everest Case |
| Bai Er Rui Trade Co., Limited |
| TrueTouch |
| COREtec Originals |
| Johnson Hardwood |
| Garnetics Outdoor |
| KOLIFE |
| Clicks |
| Lish Premium |
| Others |
Pricing and Supply Chain Analysis
Polyethylene resin costs cascade from Shanghai petrochemical feedstock through three distinct pricing tiers, with spot-market volatility compressing margins for converters lacking captive supply while premium custom specifications capture value from aerospace qualification delays.
Pricing Analysis
Distributor markups of 35-50% separate stock-grade tarps from direct-to-OEM contract pricing for automotive fleet covers. Three-tier pricing structure across premium, standard, and economy levels stratifies by hydrostatic head certification and seam validation timelines. Cost compression in standard-grade polyethylene tarps is intensifying because Chinese manufacturing clusters absorb displaced vinyl volume from REACH-restricted European compounders. Construction equipment rental fleets exhibit highest price sensitivity, while aerospace OEMs tolerate premium positioning for custom-sized solutions with pre-certified substrate libraries.
Supply Chain Analysis
Domestic-content mandates under US EPA evolving recyclability guidelines are reshaping sourcing preferences toward North American converters with closed-loop recovery capabilities. Laminated fabric production concentrates in China, South Korea, and Vietnam, drawing from linear low-density polyethylene, phthalate-free plasticizers, and UV stabilizer additive packages. Single-source geography risk in eastern China exposes buyers to port congestion and tariff friction. Distribution runs through industrial distributor networks in Europe and North America, with configured-ecommerce platforms capturing mid-volume construction and logistics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in REACH-compliant substrate switching and captive polyethylene supply chains, as regulatory chemistry restrictions displace vinyl-dependent compounders toward premium-positioned alternatives.
For Market Incumbents: Deepen backward integration into resin supply or expand coextruded substrate capacity in Pearl River Delta clusters to defend against spot-market volatility. Invest in pre-certified hydrostatic head libraries to compress aerospace qualification timelines. Lock long-term offtake agreements with German automotive OEMs specifying multi-layer PE vehicle transport covers.
For New Entrants and Emerging Players: Multi-layer coextruded polyethylene technology offers entry into precision machinery and aerospace segments previously held by heavier vinyl formulations. Target US construction equipment rental channels with configured-ecommerce platforms offering real-time seam specification. Bypass distributor markups through direct-to-industrial digital procurement to capture mid-volume buyers.
For Investors and Strategic Acquirers: Consolidation pressure builds where vinyl-dependent suppliers face REACH compliance cost absorption without premium positioning. Long-term viability favors converters with vertical manufacturing control and closed-loop recovery systems. Watch EPA material recyclability guideline enforcement as inflection indicator for first-mover advantage in post-consumer content integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Resin | Captive supply shields margin from crude oil benchmark volatility. |
| REACH-Compliant Substrate Qualification | Pre-certified libraries compress aerospace OEM contract timelines. |
| Configured-Ecommerce Platform Launch | Real-time seam specification captures mid-volume construction procurement. |
| Closed-Loop Recovery System Investment | EPA recyclability guidelines create first-mover positioning advantage. |
| Multi-Layer Coextruded Capacity Expansion | Pearl River Delta fabricators target tier-one automotive supplier contracts. |
Research Methodology
Multiple input streams — primary interviews with converter plant managers, automotive OEM procurement teams, and industrial distributor channel partners; secondary validation through customs/trade data, MIIT dual carbon goal disclosures, and SEC filings from publicly traded petrochemical suppliers; plus ECHA REACH restriction documentation — were reconciled through bottom-up and top-down triangulation to establish baseline market sizing.
Data-stream reconciliation across the projection horizon modeled segmentation by material chemistry, hydrostatic head performance tier, end-use application intensity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of automotive OEM qualification timelines, infrastructure spending patterns, and substrate switching rates. Industry-specific forecast inputs included REACH compliance cost absorption trajectories and EPA recyclability guideline implementation pace.
The model holds under stable petrochemical input cost conditions and gradual regulatory enforcement; deviation in crude oil volatility spikes or accelerated ECHA restriction expansion would shift volume and value outputs. Forecasts reflect documented assumptions about Chinese manufacturing cluster capacity expansion and German automotive specification tightening. A small set of named triggers — polyethylene resin price shocks, port congestion in Shanghai and Guangzhou, and REACH restriction scope expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Global Industrial Protective Clothing Fabrics Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Industrial Workwear Market