
 United Arab Emirates Modular Kitchen Market | 2026-2036
United Arab Emirates Modular Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Modular Kitchen Market Analytics
Dubai's manufacturing zone expansion is rewriting supply logistics for modular kitchen components across the Emirates. Inter IKEA Group leverages its flat-pack logistics expertise to sustain cost advantages in volume residential segments. Al Marri Metal Kitchen Factory LLC anchors local fabrication capacity with in-house metalwork and laminate finishing operations. Danube Home competes through integrated retail-showroom networks that control last-mile customer access across Abu Dhabi and Sharjah.
Modular kitchens are prefabricated cabinetry systems engineered from standardized panel components, typically assembled from moisture-resistant MDF or marine-grade plywood with hardware-rated hinge and slide mechanisms, designed for efficient spatial configuration in residential and commercial food preparation environments. Custom kitchens dominate margin pools through bespoke dimensioning and premium surface specifications, while flat-pack systems lead volume throughput in developer bulk procurement. Luxury modular kitchens represent the fastest-growing tier, driven by penthouse and villa specifications in Emirates Hills and Saadiyat Island developments.
MOHAP enforces material flammability and formaldehyde emission standards for interior fixtures installed across UAE residential towers, while Dubai Municipality's green building regulations incentivize low-VOC laminate and certified sustainable plywood sourcing. BIS equivalency requirements for imported Indian-manufactured components create additional compliance layers for cross-border suppliers. Stakeholders must monitor evolving emirate-level building codes and certification reciprocity agreements to anticipate procurement specification shifts.
Market Dynamics
MOHAP's material certification mandates are compressing supplier qualification timelines while Dubai Municipality's green building regulations accelerate specification upgrades across Emirates residential towers. Developer-led bulk procurement now dominates volume flows, reshaping how fabrication capacity aligns with project pipelines.
Growth Catalysts
- MOHAP flammability standards:Certification requirements for interior fixtures are filtering out uncertified imports, creating procurement advantages for compliant domestic fabricators.
- Luxury villa developments:Penthouse and villa specifications in Emirates Hills and Saadiyat Island are pulling premium modular kitchen configurations into high-net-worth residential segments.
- Marine-grade plywood adoption:Moisture-resistant panel specifications are expanding addressable market into coastal high-humidity installations previously served by custom carpentry.
Market Restraints
- Formaldehyde emission compliance costs:Low-VOC laminate and certified sustainable plywood sourcing adds 15-25% to material input costs for volume residential suppliers.
- Indian component import friction:BIS equivalency requirements for cross-border suppliers create documentation bottlenecks and extended customs clearance timelines.
- Skilled installation labor scarcity:Certified fit-out technicians capable of precision assembly in high-rise towers remain concentrated in Dubai, constraining Sharjah and Abu Dhabi deployment speed.
Strategic Opportunities
- Sharjah residential corridor:Developer activity in Aljada and Tilal City projects remains underpenetrated by integrated retail-showroom networks relative to Dubai saturation.
- Smart kitchen convergence:IoT-enabled appliance integration with modular cabinetry systems opens specification channels through MEP contractor relationships.
- Dubai Municipality green incentives:Certified sustainable material sourcing unlocks fast-track permitting and marketing advantages for compliant developers.
Industry Challenges
- Emirate-level code fragmentation:Divergent building safety interpretations between Dubai, Abu Dhabi, and Sharjah municipalities force redundant product testing and certification cycles.
- Legacy MEP integration complexity:Retrofit installations in existing towers require custom dimensioning that erodes the cost advantages of standardized panel systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Modular Kitchen Market |
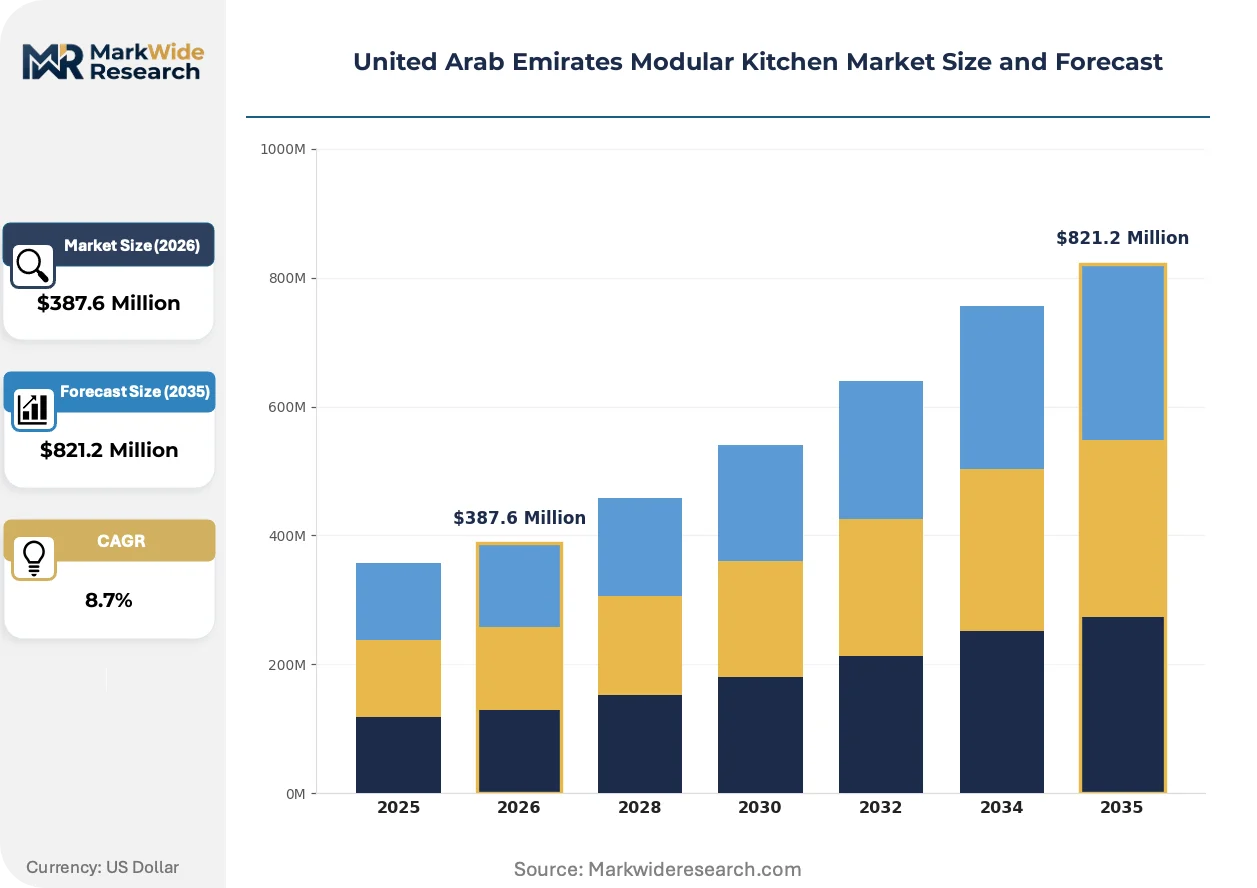
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat-pack Kitchens, Custom Kitchens, Ready-to-Assemble Kitchens, Luxury Modular Kitchens Material: Plywood, MDF, Particleboard, Laminates Installation Type: DIY Installation, Professional Installation, Pre-assembled Installation, Modular Installation End User: Residential, Commercial, Hospitality, Builders |
| Companies Covered | Inter IKEA Group, Al Marri Metal Kitchen Factory LLC, Danube Home, Scavolini, SieMatic, British Kitchen Ind, L.L.C, Hacker, Space 3 LLC, Al Khalid Furniture Factory LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Modular Kitchen Market Evolving Landscape
Specification standards across the Emirates are tightening faster than supplier adaptation cycles, compressing margins for non-compliant imports while rewarding certified domestic fabrication. Three shifts are restructuring competitive positioning.
Moisture-resistant MDF is migrating from economy residential bulk procurement into mid-tier developer specifications as MOHAP durability testing protocols raise minimum performance thresholds. Project managers in Dubai's premium residential corridor now specify marine-grade plywood alternatives for coastal installations, compressing the addressable market for standard-grade panels in high-humidity zones.
Dubai Municipality's green building regulations are mandating low-VOC laminate and certified sustainable plywood sourcing for new residential tower approvals. This regulatory pressure is disqualifying uncertified import suppliers from developer procurement lists while creating specification advantages for domestic fabricators with in-house finishing operations. High-rise residential towers in Business Bay and Dubai Marina are the most affected segments, with compliance documentation now required at pre-tender stage.
Buyer concentration around master developer fit-out specifications is displacing fragmented retail showroom purchasing in volume residential segments. Integrated procurement teams at Emaar, Aldar, and Dubai Holding now dictate cabinet configurations, hardware specifications, and installation protocols, compressing decision cycles and marginalizing independent kitchen retailers. This pattern is most visible in Dubai's premium residential corridor where developer-led bulk orders account for the majority of new installation volume.
United Arab Emirates Modular Kitchen Market Segmentation
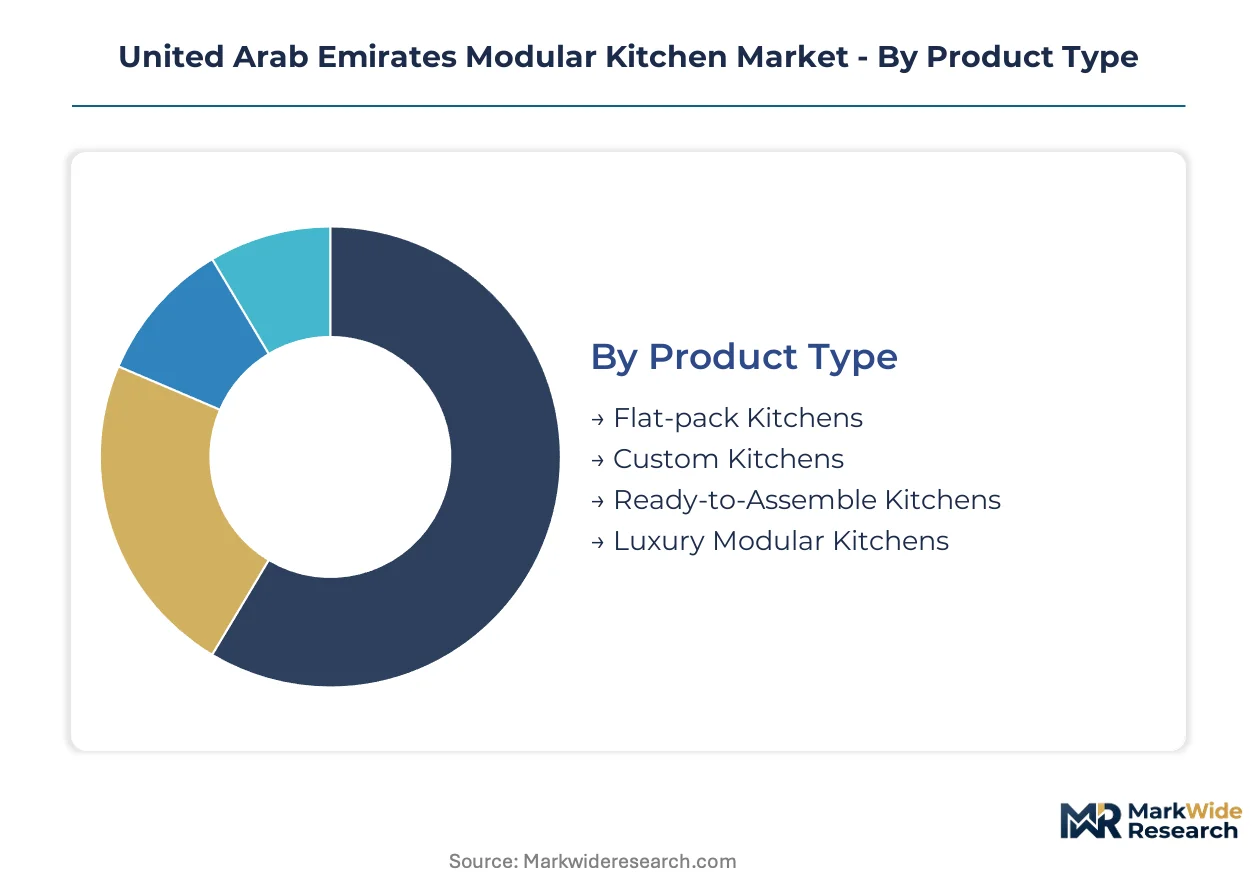
Segmentation in the UAE modular kitchen market reflects divergent procurement logics across developer bulk contracts and retail showroom sales. Specification requirements vary sharply between coastal high-humidity installations and standard inland residential towers.
Product Type:
After-sales service intensity varies dramatically across product tiers, with custom kitchens demanding dedicated project management while flat-pack systems rely on self-service support portals.
- Flat-pack Kitchens:Standardized panel components ship disassembled with hardware packets and illustrated assembly guides. Developer bulk procurement in Dubai's residential corridor dominates volume flows, compressing margin structures through scale economics.
- Custom Kitchens:Bespoke dimensioning with site-specific templating and premium surface specifications including stone countertops and imported hardware. Penthouse fit-outs in Emirates Hills and Saadiyat Island villas sustain margin pools through individualized design consultancy and white-glove installation protocols.
- Ready-to-Assemble Kitchens:Pre-cut components with connector systems targeting mid-tier residential buyers in Sharjah's emerging developments.
- Luxury Modular Kitchens:Marine-grade plywood construction with soft-close hardware and integrated appliance specifications for high-net-worth segments.
Custom kitchens hold the largest share; momentum sits with luxury modular kitchens.
Material:
Cost tier stratification in material selection directly shapes compliance pathways under MOHAP certification mandates.
- Plywood:Cross-laminated veneer construction delivers structural integrity for heavy-load cabinetry and coastal humidity resistance. Emirates Hills and Saadiyat Island specifications increasingly mandate marine-grade variants, pulling premium material sourcing into luxury residential segments.
- MDF:Engineered wood fiber panels with resin binders enable precise CNC routing for detailed door profiles and consistent finishing. Mid-tier developer specifications in Business Bay and Dubai Marina balance cost control with MOHAP durability thresholds.
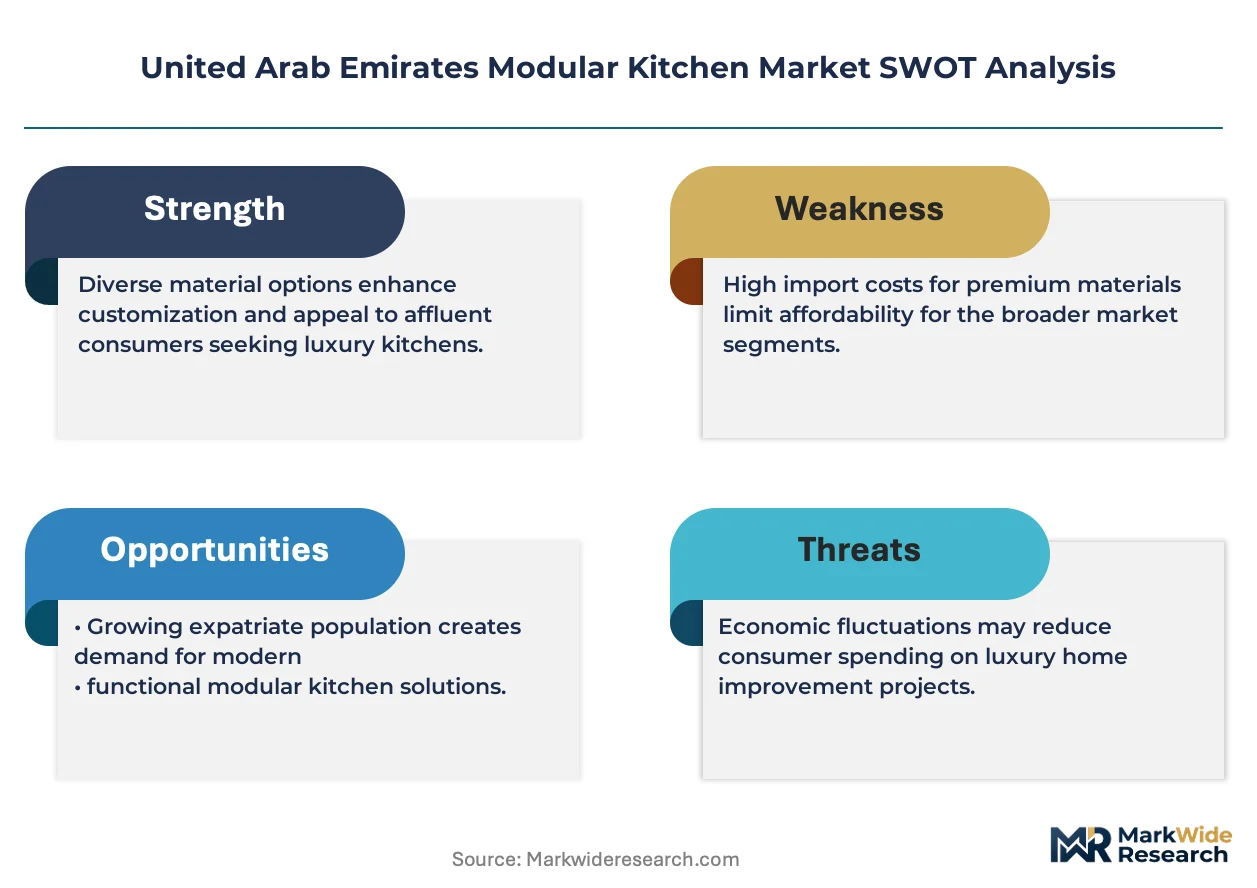
- Particleboard:Compressed wood chip construction with laminate surfacing serves economy residential bulk procurement where cost minimization outweighs longevity requirements.
- Laminates:Decorative surface layers bonded to substrate panels, with low-VOC specifications now required for Dubai Municipality green building compliance.
Plywood commands the premium tier; MDF is gaining share fastest in mid-market developer specifications.
Installation Type:
Volume concentration in professional installation reflects developer-led procurement patterns and skilled labor scarcity constraints.
- DIY Installation:Self-assembly by end-users with basic tools and manufacturer-provided guides. Limited penetration in UAE due to fit-out quality expectations and high-rise access challenges.
- Professional Installation:Certified technician teams execute precision assembly, leveling, and MEP integration. Dubai's concentration of qualified fit-out crews creates geographic bottlenecks for Sharjah and Abu Dhabi project deployment.
- Pre-assembled Installation:Factory-built cabinet units delivered for site placement and connection. Accelerating adoption in luxury villa developments where schedule compression outweighs transport cost premiums.
- Modular Installation:Standardized component systems assembled through sequential panel connection protocols. Dominates volume residential towers where repetitive unit configurations enable crew specialization.
Professional installation captures the majority of value; pre-assembled installation shows the steepest expansion trajectory in premium segments.
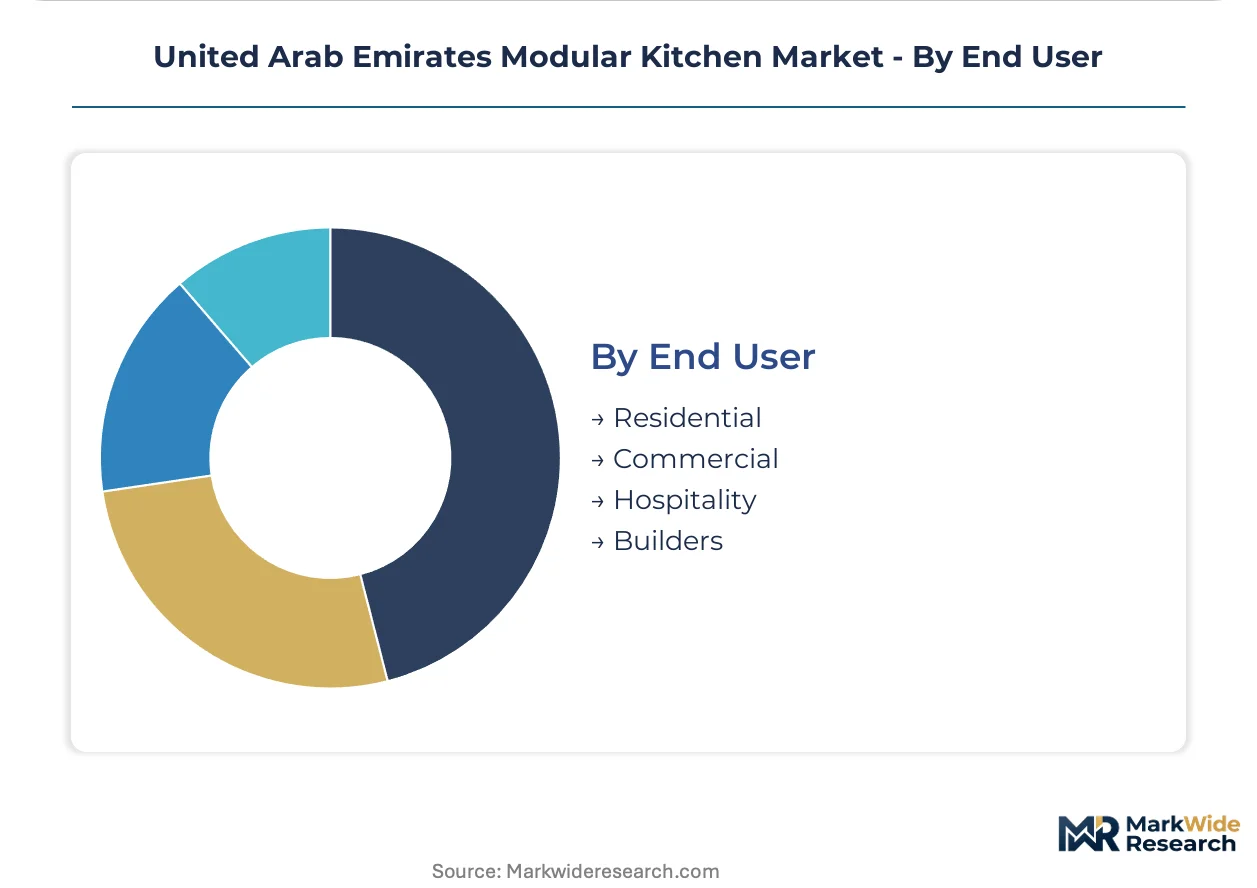
End User:
Customer type fragmentation separates bulk procurement decision-makers from individual specification authority.
- Residential:Individual homeowners and tenant purchasers selecting kitchen configurations through retail showroom networks or developer fit-out packages. Dubai's premium residential corridor concentrates discretionary spending on upgraded specifications.
- Commercial:Office pantry and staff kitchen installations with durability-focused specifications and accelerated replacement cycles. Business Bay tower fit-outs represent the primary addressable segment.
- Hospitality:Hotel and serviced apartment kitchenettes requiring fire-rated materials and standardized configurations for operational efficiency. Procurement flows through FF&E contractors with brand-standard compliance mandates.
- Builders:Master developers including Emaar, Aldar, and Dubai Holding dictate cabinet specifications across entire project pipelines. Integrated procurement teams now control the majority of new installation volume in volume residential segments.
Builders dominate procurement volume; hospitality represents the most margin-accretive end-user tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput underwrites the UAE's position as the Gulf's primary import hub for modular kitchen components. The emirate-level regulatory divergence between Dubai, Abu Dhabi, and Sharjah creates distinct procurement environments across the federation.
Dubai
Emirates Hills and Saadiyat Island villa developments pull premium modular kitchen specifications into high-net-worth segments. Dubai Municipality's green building regulations mandate low-VOC laminate sourcing for new residential tower approvals. Business Bay and Dubai Marina concentrate developer-led bulk procurement where Emaar and Dubai Holding dictate cabinet configurations.
Abu Dhabi
Aldar Properties' master developments on Yas Island and Al Reem Island drive volume demand for standardized fit-out packages. The Department of Municipalities and Transport enforces building safety codes that align with MOHAP material flammability standards. Saadiyat Island's luxury residential corridor sustains margin pools for marine-grade plywood configurations.
Sharjah
Aljada and Tilal City projects remain underpenetrated by integrated retail-showroom networks relative to Dubai saturation. Sharjah Municipality's building permit processes create documentation bottlenecks for cross-emirate suppliers. The emirate's emerging residential corridor offers expansion channels for fabrication capacity beyond Dubai's competitive intensity.
Northern Emirates
Ras Al Khaimah and Fujairah residential developments source modular kitchens through Dubai-based distributors, extending logistics lead times. Federal MOHAP standards apply uniformly, though local municipality enforcement varies. Ajman's manufacturing zones host secondary fabrication operations serving cost-sensitive procurement segments.
United Arab Emirates Modular Kitchen Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in panel fabrication and hardware supply. The vendor base clusters around three strategic archetypes: flat-pack logistics platforms with retail-showroom networks, domestic metalwork fabricators with in-house finishing operations, and European premium brands serving villa specifications. Competitive moves concentrate on emirate-level certification compliance and developer procurement team relationships.
Among UAE-based fabricators, Al Marri Metal Kitchen Factory LLC anchors local production capacity, while Danube Home exemplifies integrated retail-showroom control over last-mile customer access. Inter IKEA Group represents flat-pack logistics expertise applied to volume residential segments. These three players occupy distinct positions across the procurement spectrum from developer bulk contracts to individual showroom purchases.
| Leading Market Players |
|---|
| Inter IKEA Group |
| Al Marri Metal Kitchen Factory LLC |
| Danube Home |
| Scavolini |
| SieMatic |
| British Kitchen Ind, L.L.C |
| Hacker |
| Space 3 LLC |
| Al Khalid Furniture Factory LLC |
| Others |
Value Network & Pricing Analysis
Indian BIS equivalency documentation bottlenecks determine both pricing tier spreads and supply chain shape, compressing margins for cross-border suppliers while rewarding domestic fabricators with streamlined customs clearance. Developer-led bulk procurement concentrates buyer power, forcing volume-discount structures that marginalize independent retailers.
Pricing Analysis
Volume-discount tiering structures dominate procurement flows, with Emaar and Aldar extracting scale concessions across flat-pack and mid-tier specifications. Price differentiation rests on certification grade and after-sales service bundling, with MOHAP-compliant domestic fabricators commanding premium positioning over uncertified imports. Cost compression in economy residential segments intensifies due to particleboard substitution and self-service support models. Builders exhibit highest price sensitivity through competitive tendering, while hospitality buyers prioritize fire-rated material compliance over unit cost.
Supply Chain Analysis
Al Marri Metal Kitchen Factory LLC and Danube Home anchor domestic fabrication capacity, with Jebel Ali Port container throughput feeding component inflows from China, India, and Germany. Raw material dependencies center on marine-grade plywood from Southeast Asia, low-VOC laminates from European suppliers, and soft-close hardware from Italian manufacturers. Single-source vulnerability concentrates in certified sustainable plywood sourcing, where Dubai Municipality green building compliance disqualifies secondary suppliers. Distribution runs through integrated retail-showroom networks controlling last-mile access in Dubai and Abu Dhabi, with Sharjah and Northern Emirates served via Dubai-based distributor extensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around master developer procurement teams at Emaar, Aldar, and Dubai Holding, fragmenting independent retailer influence and compressing decision cycles for volume residential fit-outs.
For Market Incumbents: Harden certification portfolios against MOHAP flammability and formaldehyde emission mandates to defend procurement list eligibility. Deepen backward integration into in-house metalwork and laminate finishing operations to capture margin pools eroded by import documentation friction. Channel control through exclusive developer relationships represents the critical defensive lever against flat-pack logistics platforms.
For New Entrants and Emerging Players: Sharjah's Aljada and Tilal City residential corridors represent the most penetrable entry point, with underdeveloped integrated showroom networks relative to Dubai saturation. Mid-tier ready-to-assemble specifications targeting cost-conscious developer procurement in Northern Emirates offer secondary white-space. A go-to-market angle through MEP contractor relationships for smart kitchen convergence unlocks specification channels bypassing saturated retail competition.
For Investors and Strategic Acquirers: Dubai Municipality's expanding green building compliance mandates reshape the acquisition landscape, elevating domestic fabricators with certified sustainable material sourcing capabilities. Long-term viability across the analysis window favors vertically integrated specialists with in-house finishing and emirate-level certification reciprocity. The signal to watch is Sharjah Municipality building permit process harmonization with Dubai standards, which would eliminate documentation bottlenecks and revalue cross-emirate supply capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Certification Investment | Unlocks procurement list eligibility at Emaar and Aldar master developments. |
| Backward Integration into Metalwork | Captures margin pools eroded by import component documentation delays. |
| Sharjah Showroom Network Expansion | Addresses underpenetrated Aljada and Tilal City developer pipelines. |
| Smart Kitchen MEP Partnership | Opens specification channels through contractor relationships beyond retail saturation. |
| Sustainable Material Sourcing Program | Qualifies for Dubai Municipality fast-track permitting and marketing advantages. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with procurement directors at master developers, fit-out contractors, MOHAP certification officers, and showroom network managers combined with Dubai Municipality building permit databases, MOHAP material safety filings, customs import records, and developer tender documentation. Bottom-up project pipeline enumeration and top-down emirate-level construction spend analysis provide triangulation checks.
Calibration against historical fit-out specification trends and regulatory implementation timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, material grade, installation protocol, and end-user procurement archetype. CAGRs derive from unit volume build-ups applied to specification-mix pricing trajectories, with marine-grade plywood adoption curves and smart kitchen integration rates as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in UAE residential construction permits, expatriate population inflows, or oil revenue-funded infrastructure budgets would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and certification reciprocity agreements. Quarterly review of MOHAP amendment notices and Dubai Municipality green building code updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Vietnam Kitchen Furniture Market