
 Saudi Arabia Kitchen Hoods Market | 2026-2036
Saudi Arabia Kitchen Hoods Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Kitchen Hoods Market Analytics
Specialty kitchen retail channels in Riyadh and Jeddah is rewriting how manufacturers reach Saudi households, with showrooms and e-commerce platforms now commanding disproportionate influence over purchase decisions. AB Electrolux leverages its European design heritage to anchor premium positioning in upscale Saudi neighborhoods. Elica S.p.A. specializes in sleek island hood configurations that dominate villa kitchen layouts across the kingdom.
A kitchen hood is a mechanical ventilation appliance housing a motorized fan and filtration system, typically constructed from stainless steel with aluminum or baffle filters, designed to extract airborne grease, combustion byproducts, smoke, odors, and steam from cooking environments. Wall-mounted units retain the largest installed base in Saudi residential construction due to compatibility with standard kitchen wall configurations. Smart technology features represent the fastest-expanding specification tier as Saudi consumers prioritize Wi-Fi-enabled controls and sensor-based automation. Ducted installation types command the margin pool in commercial and hospitality deployments where building infrastructure supports external venting.
The Saudi Building Code and SASO energy efficiency standards govern minimum performance requirements for kitchen ventilation equipment, while SFDA oversight extends to commercial food preparation environments where hood specifications tie directly to operating licenses. These regulatory layers compel manufacturers to certify products for thermal efficiency and fire safety before market entry. Stakeholders must track evolving SASO labeling requirements and hospitality sector build-out schedules to align production and inventory decisions with compliance timelines and project pipelines.
Market Dynamics
Saudi Building Code energy efficiency mandates are compressing product development cycles and forcing manufacturers to re-engineer ventilation systems around thermal performance thresholds before market entry.
Growth Catalysts
- Saudi Building Code ventilation mandates:SASO energy efficiency standards are mandating minimum thermal performance thresholds, compelling replacement cycles in existing residential stock across Riyadh and Jeddah.
- Hospitality sector build-out:The Eastern Province's hotel and restaurant pipeline is generating concentrated demand for commercial-grade ducted hood systems tied to operating license requirements.
- Smart sensor integration:Wi-Fi-enabled automation and particulate detection are becoming baseline specifications in upscale villa developments, accelerating premium product penetration.
Market Restraints
- Stainless steel input volatility:Raw material price swings for 304-grade stainless are compressing margin buffers for manufacturers serving the mid-tier residential segment.
- SFDA commercial certification timelines:Extended approval cycles for food preparation ventilation equipment are delaying project handoffs in the hospitality sector.
- Technical limitation in recirculating systems:Charcoal filter saturation rates in ductless configurations are limiting adoption in high-volume commercial kitchens where external venting is structurally constrained.
Strategic Opportunities
- Neom and Red Sea Project zones:Giga-project construction timelines are creating synchronized demand windows for integrated kitchen ventilation in residential and hospitality units.
- E-commerce platform expansion:Digital showroom penetration is opening direct-to-consumer channels that bypass traditional retail markups in secondary cities.
- SASO labeling evolution:Anticipated mandatory energy disclosure requirements will create first-mover advantages for manufacturers with pre-certified efficient product lines.
Industry Challenges
- Fire safety certification complexity:Thermal testing protocols under Saudi Building Code fire safety chapters are extending product validation timelines by 4-6 months for new entrants.
- Integration friction with HVAC systems:Building-wide climate control coordination is requiring specialized commissioning expertise that remains scarce in the Eastern Province construction workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Kitchen Hoods Market |
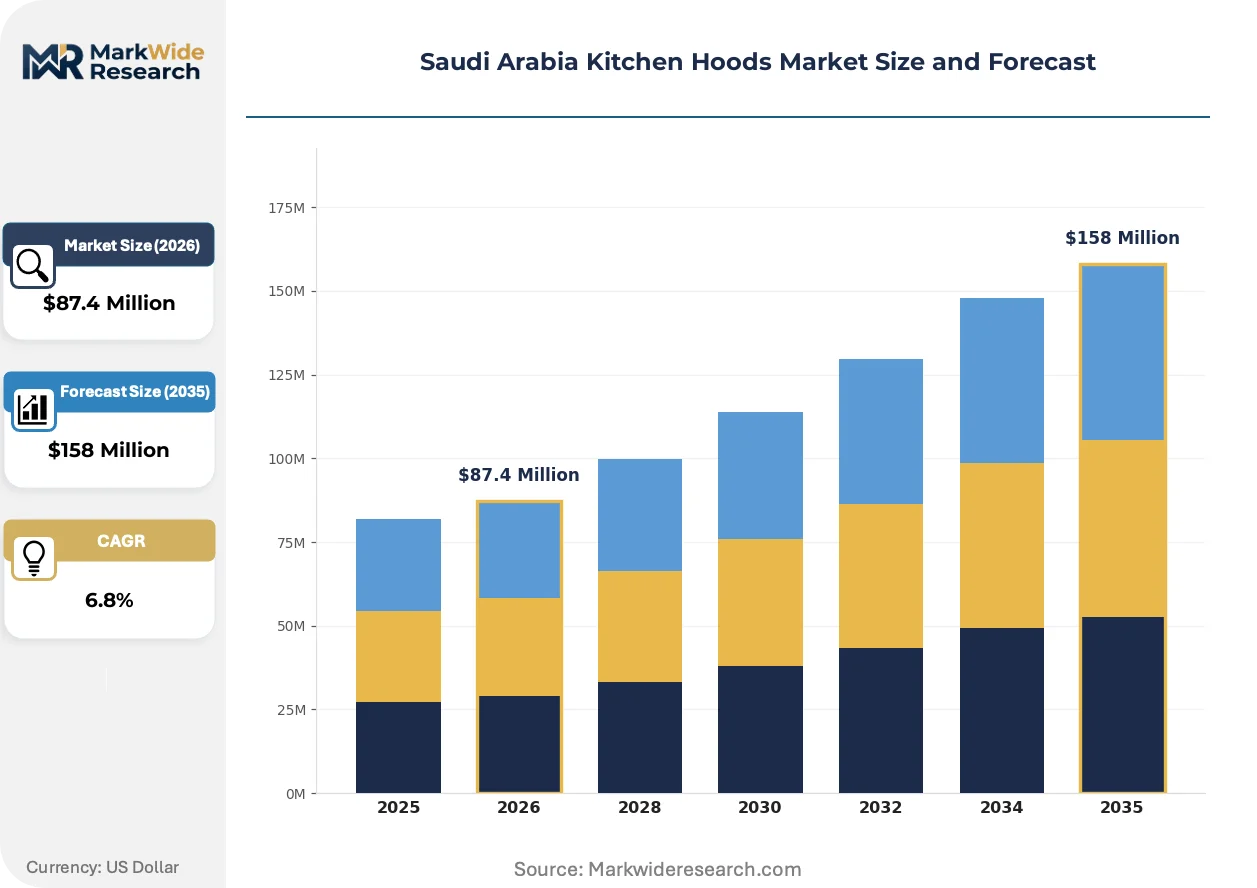
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Under-Cabinet, Island, Downdraft Installation Type: Hardwired, Plug-In, Ducted, Ductless Feature: Smart Technology, Energy Efficiency, Noise Level, Filter Type End User: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | AB Electrolux, Panasonic, Samsung, Elica S.p.A., Midea, LG, Bosch, Faber S.p.A., Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Kitchen Hoods Market Evolving Landscape
Connected automation and sensor-based controls are displacing manual interfaces across the Saudi residential market, while regulatory pressure on thermal efficiency is compressing the performance gap between premium and standard product tiers.
Perimeter aspiration technology is collapsing the distinction between island and wall-mounted extraction efficiency. High-end villa developers in Riyadh are specifying these systems as standard in open-plan kitchen layouts. The technology is collapsing the premium pricing power that island configurations previously commanded.
SASO energy efficiency labeling requirements are tightening disclosure obligations for kitchen ventilation equipment. Manufacturers must now submit third-party thermal performance data before market authorization. The commercial hospitality segment is responding by pre-specifying certified products in tender documents to accelerate project approvals.
Specialty retail showrooms are displacing general appliance distributors as the primary influence point for Saudi household purchase decisions. Consumers in Jeddah are prioritizing hands-on product demonstration over catalog-based selection. This channel rotation is most visible in the premium villa segment where kitchen design consultants now specify ventilation systems during early construction phases.
Saudi Arabia Kitchen Hoods Market Segmentation
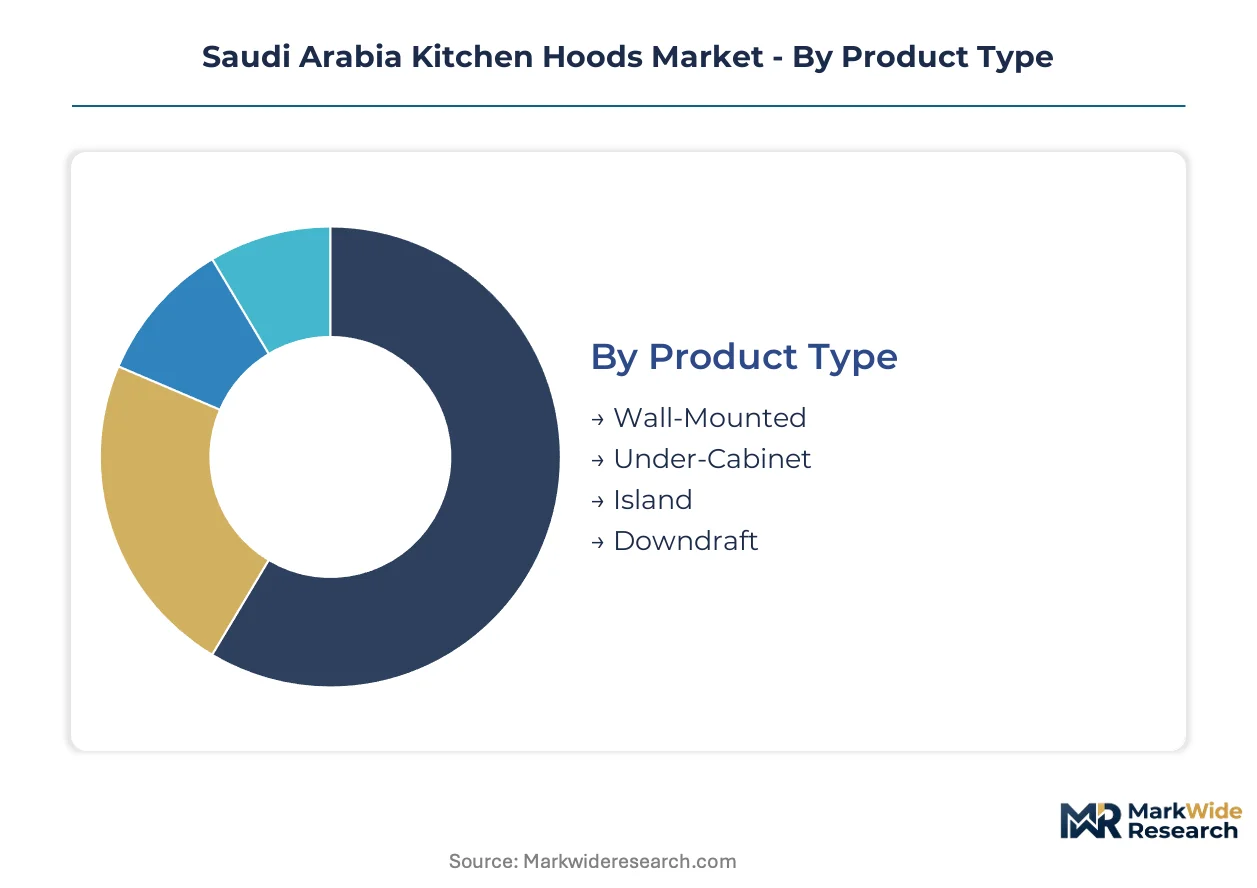
Kitchen hood specification in Saudi Arabia splits across four dimensions that each reshape procurement patterns. Product geometry dictates installation feasibility in villa versus apartment construction. Feature tiers separate compliance-driven hospitality purchases from consumer-driven residential upgrades.
Product Type:
Geometry determines airflow capture efficiency and spatial integration across Saudi residential formats.
- Wall-Mounted:Vertical extraction units anchor to kitchen wall surfaces with stainless steel canopy construction. Riyadh apartment stock drives volume here, with SASO thermal compliance now mandatory for all new installations. Standard wall configurations in Saudi residential construction make this the default specification for cost-sensitive developments.
- Island:Suspended ceiling-mounted systems with perimeter aspiration technology serve open-plan villa kitchens. Jeddah premium developments specify these for aesthetic integration, though perimeter technology is collapsing the efficiency gap with wall-mounted alternatives. Developers now question the traditional island price premium.
- Under-Cabinet:Compact units integrate beneath overhead storage in space-constrained kitchens. Dammam secondary housing stock favors this format where ceiling height limits island suspension.
- Downdraft:Retractable surface-integrated ventilation emerges in ultra-compact urban units. Khobar micro-apartment projects pilot this format where vertical extraction is structurally impossible.
The dominant share belongs to Wall-Mounted, while Island is closing the gap fastest.
Installation Type:
Electrical and venting infrastructure availability splits the market between new-build flexibility and retrofit constraint.
- Ducted:External venting systems channel effluent outside building envelopes through rigid or flexible ducting. Eastern Province hospitality projects mandate this format, with SFDA operating licenses contingent on demonstrated grease and particulate evacuation. Building-wide HVAC coordination requires specialized commissioning expertise that remains scarce in regional construction workforces.
- Ductless:Recirculating configurations pass air through charcoal filtration before returning it to kitchen spaces. Riyadh high-rise retrofits adopt this where structural ducting is impossible, though filter saturation rates limit commercial kitchen viability.
- Hardwired:Direct electrical connection to building circuits supports higher motor capacities. New villa construction in Jeddah specifies this for integrated smart control compatibility.
- Plug-In:Standard outlet connection enables rapid replacement in rental stock and budget renovations. Secondary city apartment markets favor this for installer flexibility.
Ducted systems command the margin pool in commercial deployments, while Ductless climbs fastest in constrained urban retrofits.
Feature:
Performance specifications now differentiate products at similar price points across Saudi distribution channels.
- Smart Technology:Wi-Fi-enabled controls, particulate sensors, and automated speed adjustment respond to cooking intensity. Upscale Riyadh villa developments specify these as baseline, with sensor-based automation displacing manual interfaces in premium segments.
- Energy Efficiency:Thermal performance metrics governed by SASO standards determine market authorization. Manufacturers now submit third-party data before authorization, with anticipated mandatory disclosure creating first-mover advantages for pre-certified lines.
- Noise Level:Decibel ratings at maximum extraction speed influence residential purchase decisions. Jeddah showroom demonstrations prioritize acoustic performance in hands-on consumer evaluation.
- Filter Type:Baffle, mesh, and charcoal configurations determine maintenance cycles and grease capture efficiency. Commercial hospitality tenders now pre-specify certified filter assemblies to accelerate SFDA approval timelines.
Smart Technology captures developer attention in new construction, while Energy Efficiency expands most quickly across replacement cycles.
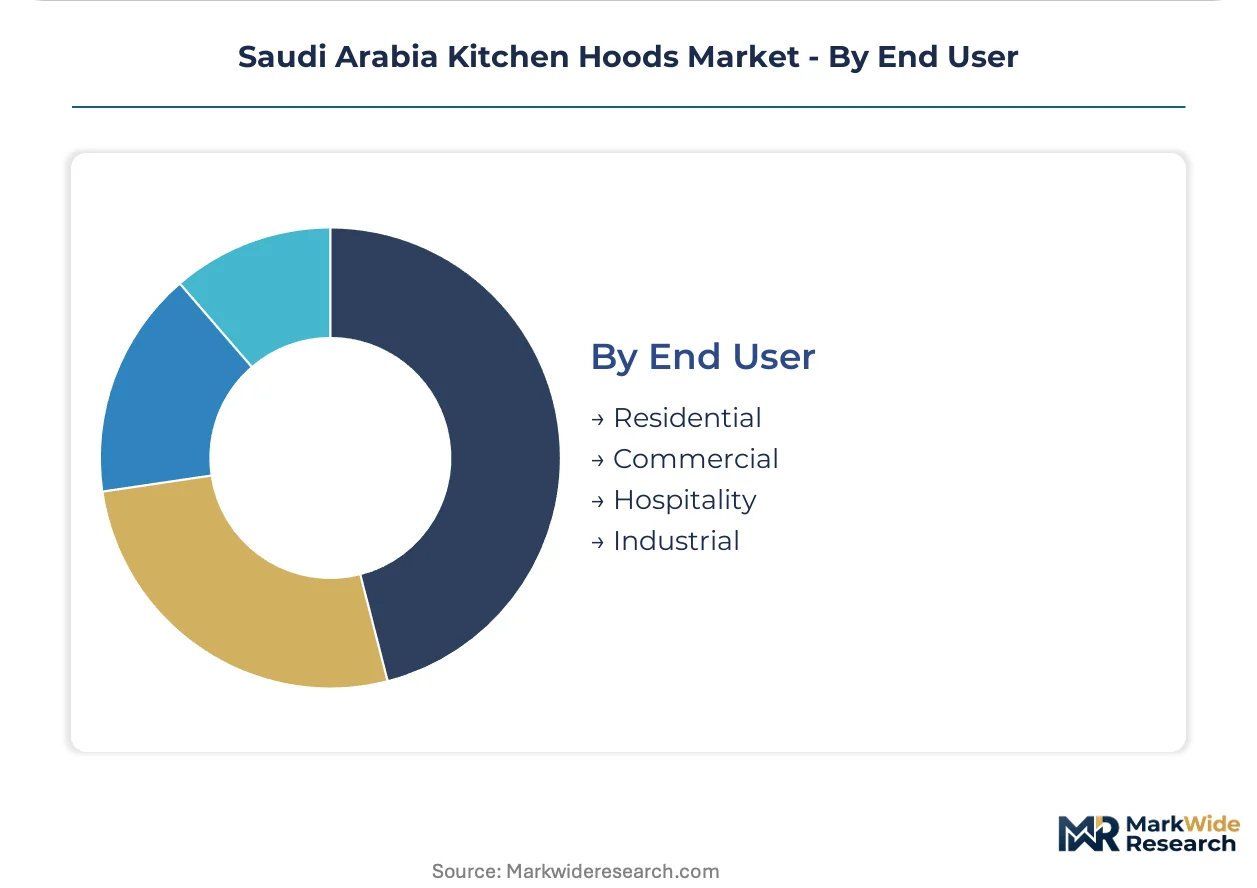
End User:
Regulatory exposure and project scale reshape procurement authority and specification rigor.
- Residential:Individual household purchases through retail showrooms and e-commerce platforms. Riyadh and Jeddah specialty channels now command disproportionate influence over purchase timing and brand selection.
- Hospitality:Hotel and restaurant operators face SFDA ventilation requirements tied directly to operating licenses. Eastern Province build-out concentrates demand for commercial-grade ducted systems with fire safety certification.
- Commercial:Non-hospitality food service and institutional kitchens require compliant ventilation without full hospitality-tier specifications. Corporate cafeteria projects in Dammam industrial zones fall here.
- Industrial:High-volume food processing and manufacturing facilities with specialized effluent handling. Neom giga-project food production facilities represent emerging specification volume.
Residential volume dominates unit shipments, while Hospitality drives value concentration through compliance-linked premium specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Building Code mandates and giga-project construction timelines are redistributing kitchen hood demand across the kingdom's economic corridors. Regional procurement patterns now track closely with hospitality licensing requirements and residential development waves.
Riyadh
High-end villa developments and smart city infrastructure are concentrating premium ventilation specifications in the capital region. SASO energy efficiency labeling requirements are accelerating replacement cycles in existing residential stock. The Riyadh housing pipeline is generating synchronized demand for wall-mounted and island hood configurations.
Eastern Province
Hotel and restaurant build-out in Dammam and Khobar is creating concentrated demand for commercial-grade ducted systems. SFDA operating license requirements are compelling hospitality operators to pre-specify certified ventilation equipment. The Eastern Province construction workforce scarcity is extending commissioning timelines for integrated HVAC coordination.
Western Region
Jeddah's premium residential segment is driving island hood adoption through specialty retail showroom channels. Perimeter aspiration technology is collapsing efficiency gaps between wall-mounted and suspended configurations. The Jeddah villa market is prioritizing acoustic performance and smart sensor integration in purchase decisions.
NEOM Northwest
Giga-project residential and hospitality units are creating integrated specification windows for kitchen ventilation systems. Neom food production facilities represent emerging industrial-grade demand for specialized effluent handling. The project zone is mandating pre-certified efficient product lines to meet accelerated construction schedules.
Saudi Arabia Kitchen Hoods Market Competitive Landscape
On the supply side, the industry is tiered across European design heritage brands, Asian volume manufacturers, and regional specialists. The vendor base clusters around three strategic archetypes: premium European heritage players, scale-driven Asian conglomerates, and kitchen ventilation specialists. Competitive moves concentrate on portfolio diversification into smart automation features and strategic partnerships with Saudi distributors for project channel access.
Within the European heritage tier, AB Electrolux and Elica S.p.A. exemplify premium positioning anchored in design credentials. Among Asian conglomerates, Panasonic and Samsung occupy positions spanning consumer electronics into built-in kitchen appliances. Bosch represents the German engineering archetype with established Saudi distribution infrastructure. These players collectively illustrate how brand origin and channel relationships stratify competitive positioning in the kingdom's ventilation equipment procurement landscape.
| Leading Market Players |
|---|
| AB Electrolux |
| Panasonic |
| Samsung |
| Elica S.p.A. |
| Midea |
| LG |
| Bosch |
| Faber S.p.A. |
| Whirlpool Corporation |
| Others |
Value Network & Pricing Analysis
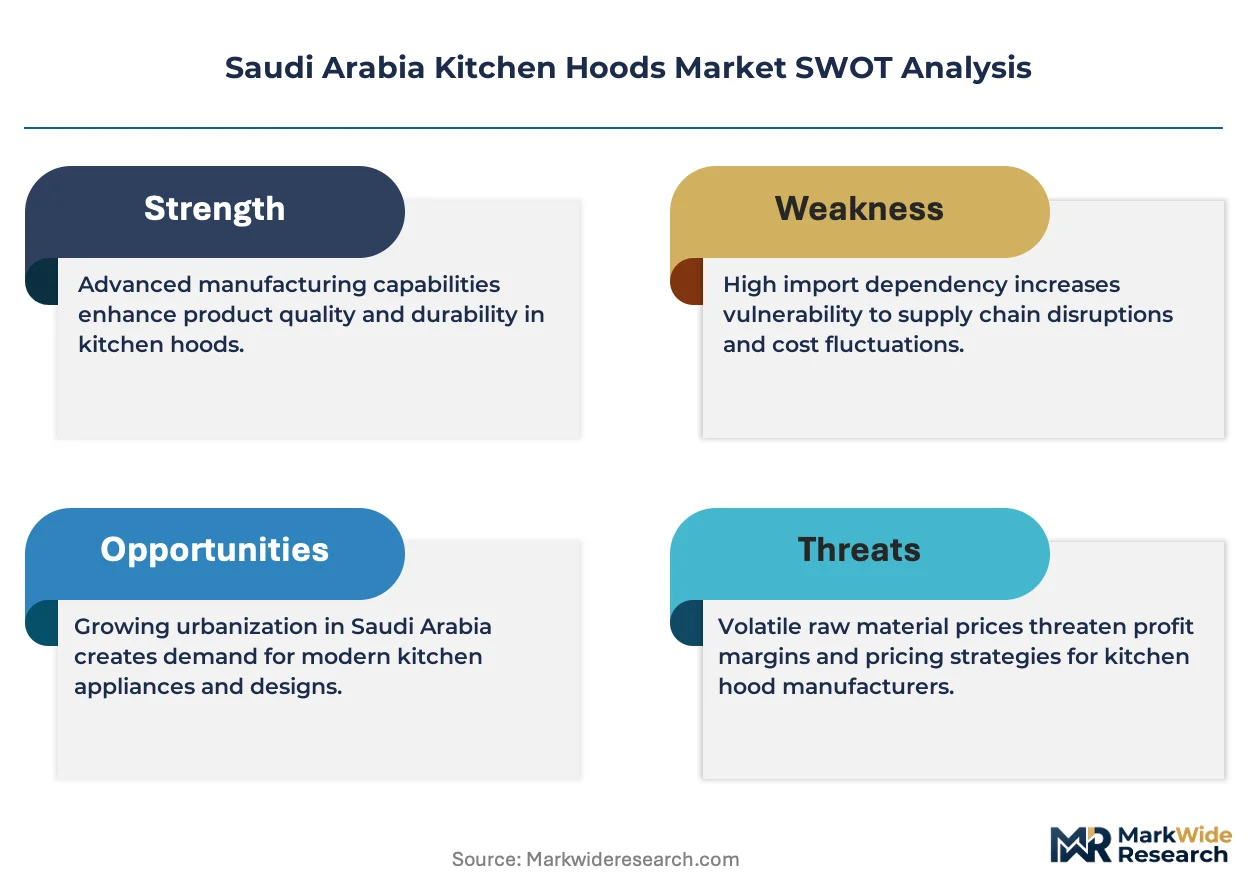
Eastern Province manufacturing clusters anchor stainless steel fabrication capacity for Saudi kitchen hood assembly, with throughput dynamics at Dammam industrial zones translating directly into downstream pricing leverage for finished ventilation systems. Raw material volatility in 304-grade stainless inputs compresses margin buffers differently across product tiers, forcing manufacturers to calibrate pricing power against inventory carrying costs and spot market exposure.
Pricing Analysis
Certification level under SASO energy efficiency standards creates the primary spread between product tiers, with pre-certified thermal performance lines commanding substantial premiums over uncertified alternatives pending market authorization. Three-tier pricing structure across premium, standard, and economy levels stratifies by smart sensor integration and fire safety rating, with hospitality procurement teams least sensitive to unit cost due to SFDA operating license contingencies. Cost compression in mid-tier residential segments is intensifying because stainless steel input volatility erodes manufacturer buffers, while Riyadh apartment developers exhibit highest price sensitivity in volume tenders.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese mills, South Korean producers, and European specialty metal suppliers, with 304-grade coil and aluminum baffle components forming the core material base. Motor assemblies and sensor modules feed from Taiwan, China, and Germany, creating multi-source dependencies for smart-enabled product lines. Single-source vulnerability concentrates in perimeter aspiration technology patents held by limited European specialists. Distribution runs through Riyadh and Jeddah specialty retail showrooms for residential segments, while project channels in Eastern Province hospitality deploy direct manufacturer-to-contractor coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia kitchen hoods market sits in early-cycle expansion, with SASO energy efficiency mandates and giga-project construction waves driving penetration acceleration across residential and commercial verticals.
For Market Incumbents: Build regulatory certification moats by pre-positioning product lines for anticipated mandatory SASO labeling disclosure, securing first-mover authorization advantages before compliance deadlines compress competitor windows. Deepen backward integration into stainless steel component fabrication to buffer margin pressure from raw material volatility, while locking exclusive distribution partnerships with Jeddah and Riyadh specialty showroom networks to control residential channel access against emerging Asian volume players. For New Entrants and Emerging Players: Build out digital direct-to-consumer platforms targeting secondary cities beyond Riyadh and Jeddah, where traditional retail markups create arbitrage opportunities for e-commerce-first positioning. Target the underpenetrated Dammam and Khobar hospitality retrofit segment, where SFDA compliance urgency and extended certification timelines for established brands create temporary specification windows for pre-certified challengers willing to absorb accelerated approval costs. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because SASO energy efficiency standards and Saudi Building Code ventilation mandates are structurally raising compliance barriers that favor scaled incumbents with certification infrastructure. Acquisition focus should center on European heritage brands with established Saudi distribution and pre-certified product portfolios, or Asian manufacturers with captive stainless steel supply and cost structures suited to mid-tier volume expansion. The signal to watch is hospitality sector tender pre-specification patterns, where SFDA-linked procurement is concentrating demand around certified suppliers faster than residential replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Pre-Certification Investment | Accelerates market authorization timelines before mandatory energy disclosure takes effect. |
| Specialty Showroom Partnership | Captures Jeddah and Riyadh residential purchase decisions away from general appliance distributors. |
| Perimeter Aspiration Technology Licensing | Neutralizes island hood efficiency premiums as wall-mounted alternatives achieve parity. |
| Eastern Province Project Channel Direct Access | Bypasses retail markups in hospitality sector build-out concentrated in Dammam and Khobar. |
| Smart Sensor Integration Platform | Meets upscale villa developer specifications for Wi-Fi-enabled automation as baseline requirement. |
Research Methodology
The analysis maps wall-mounted, island, under-cabinet, and downdraft product configurations, each validated through kitchen design consultants, hospitality procurement directors, SFDA compliance officers, and specialty retail showroom operators. Primary fieldwork combined structured interviews with manufacturer sales executives and distributor channel heads, cross-referenced against SASO certification databases, Saudi Building Code technical appendices, and Eastern Province hospitality project development filings. Bottom-up unit shipment estimates by product tier and installation type were triangulated against top-down construction pipeline valuations from giga-project disclosures and regional housing authority data.
Assumptions held fixed include current SASO energy efficiency thresholds and Saudi Building Code fire safety chapter requirements, while variables tested across the projection horizon encompass stainless steel price trajectory, hospitality sector build-out acceleration, and smart technology adoption curves in residential new construction. Segmentation modeling incorporated product geometry, venting infrastructure availability, feature tier penetration, and end-user regulatory exposure as orthogonal demand drivers. CAGRs were derived from installed base turnover rates and new-build specification patterns, with particular sensitivity to Neom and Red Sea Project construction timelines as synchronized demand windows.
Stress conditions across raw material cost bands, SFDA certification timeline extensions, and hospitality licensing approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and could revise materially if SASO mandates accelerate or giga-project timelines compress. Cross-checking against Saudi Contractors Authority project award databases and SASO market authorization registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Italy Cookware Market