
 Rail Damper Market | 2026-2036
Rail Damper Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Damper Market Insights
The capital-intensity divergence between integrated brake-damper specialists and component-only suppliers is unwinding competitive boundaries across the rail damper landscape. Knorr-Bremse AG leverages its braking systems heritage to bundle damper contracts with full train control packages. Dellner Dampers AB anchors its position through specialized hydraulic architectures for high-speed applications. ZF Friedrichshafen AG competes via automotive-derived manufacturing scale that compresses unit economics on polymer-based designs.
A rail damper is a mechanical or mechatronic device engineered to dissipate kinetic energy from wheel-rail contact, track irregularities, and braking events through elastomeric shear, fluid displacement, or friction interfaces, typically specified by damping coefficient (kN·s/m), stroke capacity, and temperature operating range. Its primary purpose is to attenuate vibrations that degrade ride quality, damage track infrastructure, and accelerate component fatigue in rolling stock. Hydraulic dampers dominate freight and heavy-haul segments where load variability demands tunable force-velocity characteristics, while viscoelastic systems lead urban transit procurement cycles driven by maintenance interval compression. Semi-active technology represents the fastest-expanding margin pool as OEMs integrate magnetorheological valves with predictive diagnostic architectures.
The European Union's F-Gas Regulation and MDR conformity requirements shape material selection and sealing technologies for cross-border rolling stock certification, while China's NMPA-aligned rail equipment standards and GB technical codes govern domestic procurement eligibility for foreign suppliers. Japan's METI enforces JIS vibration limits that filter damper performance thresholds for Shinkansen fleet renewals. Stakeholders must monitor how adaptive system validation protocols evolve alongside digital twin deployment timelines in operator maintenance frameworks.
Market Dynamics
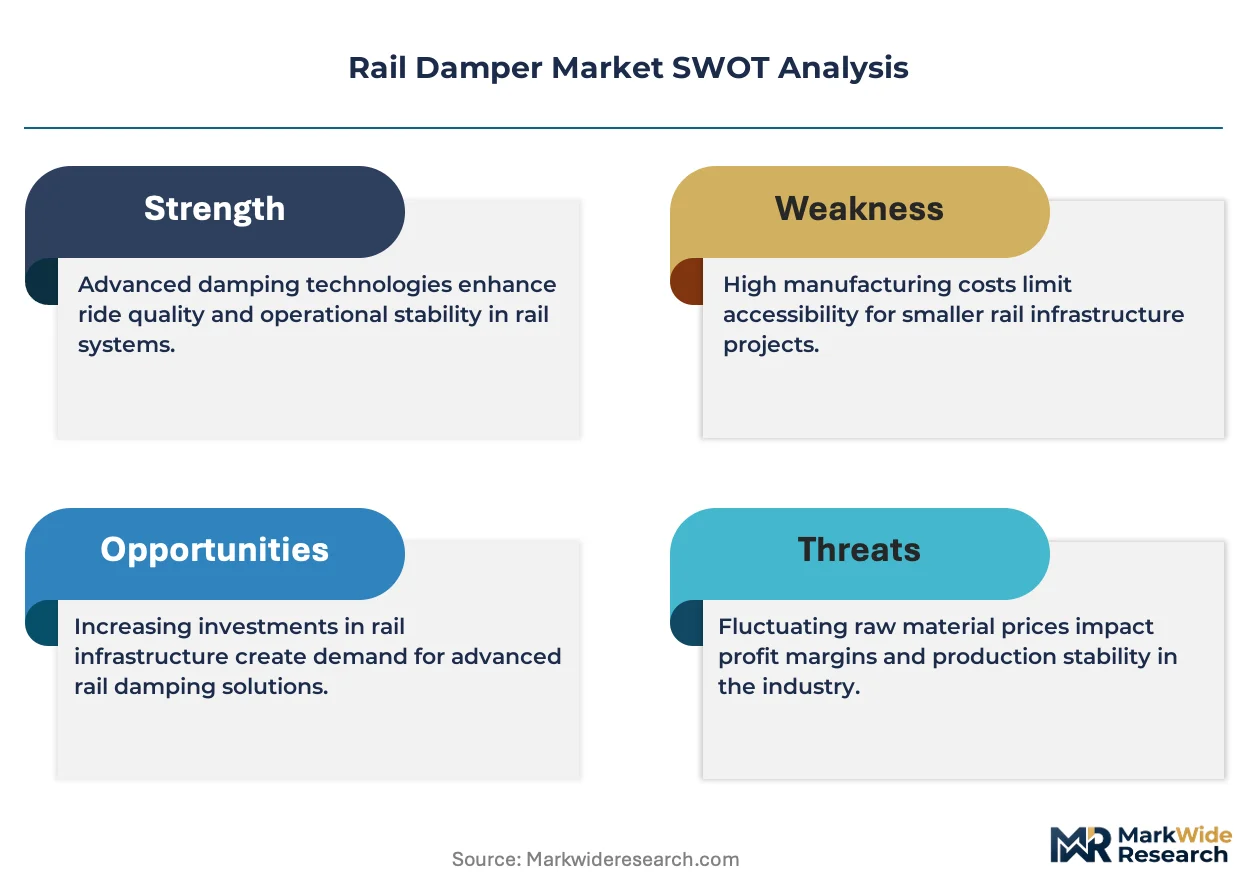
The transition from passive to semi-active damping architectures is compressing supplier margins while elevating system integration requirements across rolling stock procurement cycles.
Growth Catalysts
- EU Green Deal modal shift targets:The European Commission's binding rail freight volume mandates are forcing fleet operators to prioritize energy-efficient suspension systems that reduce track degradation and rolling resistance.
- High-speed rail expansion:China's coastal manufacturing belt is generating concentrated demand for hydraulic dampers rated above 400 kN·s/m as CRRC accelerates 350 km/h trainset deployments.
- Magnetorheological valve maturation:Real-time damping coefficient adjustment is enabling predictive maintenance architectures that extend component replacement intervals by 40% in urban transit applications.
Market Restraints
- Specialized elastomer supply concentration:Fluorocarbon seal production clusters in Germany and Japan, exposing damper manufacturers to input cost volatility when EUR/JPY exchange rates fluctuate.
- MDR conformity timeline friction:The European Union's Medical Device Regulation certification requirements for embedded sensor systems are extending product validation cycles by 8-14 months.
- Active suspension substitution threat:Fully active electromagnetic systems from automotive suppliers are penetrating premium locomotive segments where ride quality specifications exceed 0.15 m/s² vertical acceleration limits.
Strategic Opportunities
- India's Dedicated Freight Corridor:The country's PLI scheme for rail component manufacturing is creating localized procurement channels for foreign damper suppliers meeting BIS certification requirements.
- Digital twin convergence:Integration of physics-based damper models with operator maintenance frameworks is opening recurring revenue streams through condition-monitoring subscriptions.
- F-Gas Regulation material pivot:The European Union's phasedown of hydrofluorocarbon-based hydraulic fluids is accelerating bio-synthetic alternative development for cross-border rolling stock.
Industry Challenges
- Mechatronics skill scarcity:The shortage of engineers proficient in both fluid dynamics and embedded software is constraining semi-active system development timelines at tier-two suppliers.
- Legacy fleet integration complexity:Retrofitting magnetorheological dampers onto 1990s-era bogie designs requires structural modifications that void original equipment warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Damper Market |
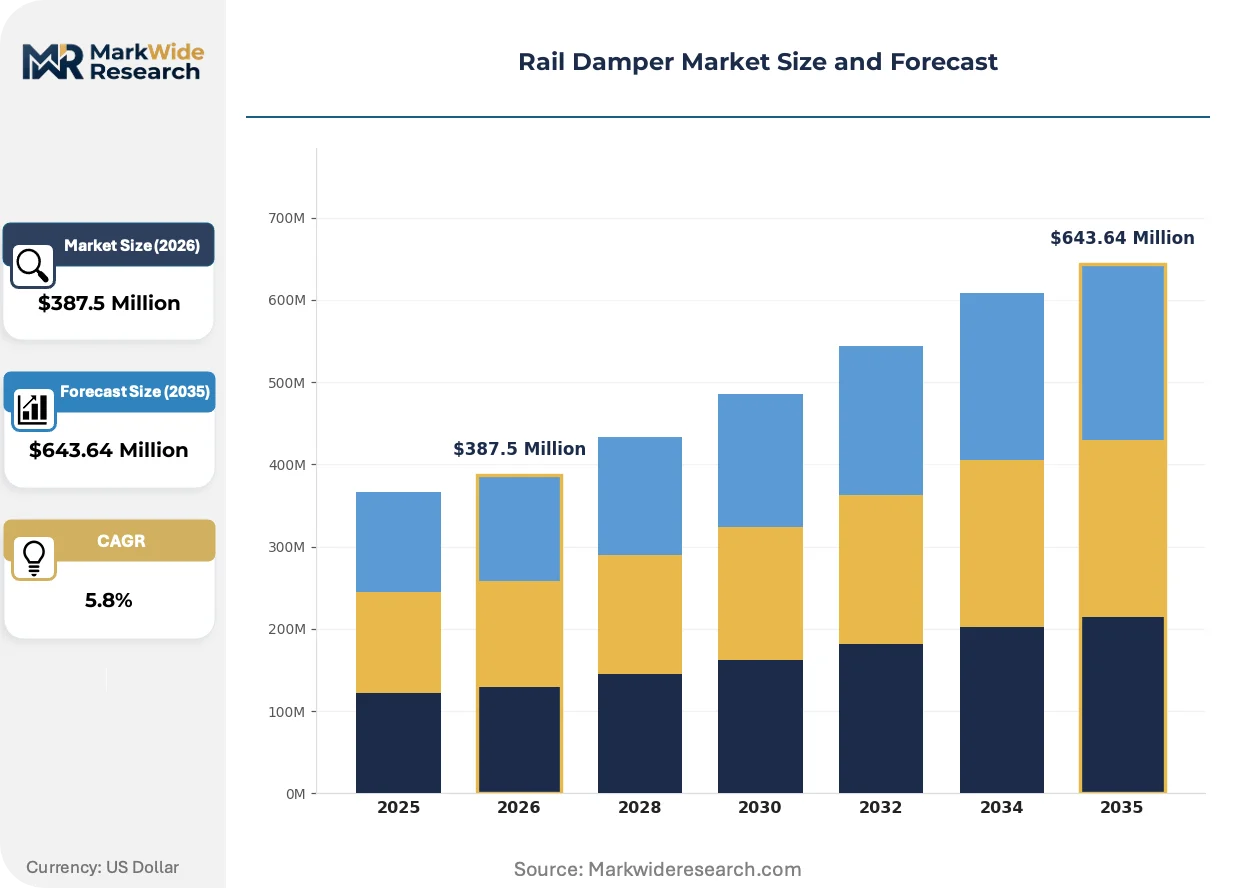
| Market Size in 2026 | $387.5 Million |
| Market Size in 2035 | $643.64 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscoelastic Dampers, Hydraulic Dampers, Pneumatic Dampers, Friction Dampers Application: Freight Transportation, Passenger Rail Systems, High-Speed Rail, Urban Transit End User: Rail Operators, Infrastructure Managers, OEMs, Maintenance Providers Technology: Passive Systems, Active Systems, Semi-Active Systems, Adaptive Systems |
| Companies Covered | Knorr-Bremse AG, ZF Friedrichshafen AG, Dellner Dampers AB, ITT Inc., Voestalpine Railway Systems, Trelleborg, Schrey & Veit GmbH, ITV GmbH, Oleo International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Damper Market Trends and Innovations
Digitalization of damper performance data is restructuring supplier-operator relationships and enabling outcome-based maintenance contracts that transfer component risk to manufacturers.
Magnetorheological fluid technology is decomposing the traditional trade-off between damping tunability and mechanical simplicity. Urban transit operators in Japan and South Korea are specifying semi-active systems for 80% of new metro car procurements. This capability convergence is decomposing the historical segmentation between hydraulic specialists and electronic control suppliers.
The European Union's F-Gas Regulation is mandating phasedown schedules for hydrofluorocarbon-based hydraulic fluids used in rail dampers. Seal manufacturers are reformulating elastomer compounds to accommodate bio-synthetic alternatives with different lubricity profiles. High-speed operators in Germany and France are absorbing 12-18% fluid cost premiums to maintain cross-border certification compliance.
Operator procurement departments are consolidating damper contracts into multi-year lifecycle agreements that bundle hardware, installation, and predictive maintenance. This purchasing pattern is displacing spot-buy component sourcing in Nordic markets where state-owned rail operators dominate fleet decisions. The shift is most pronounced in Sweden and Norway, where SJ and Vy are requiring 15-year total cost of ownership guarantees from damping system suppliers.
Rail Damper Market Segmentation
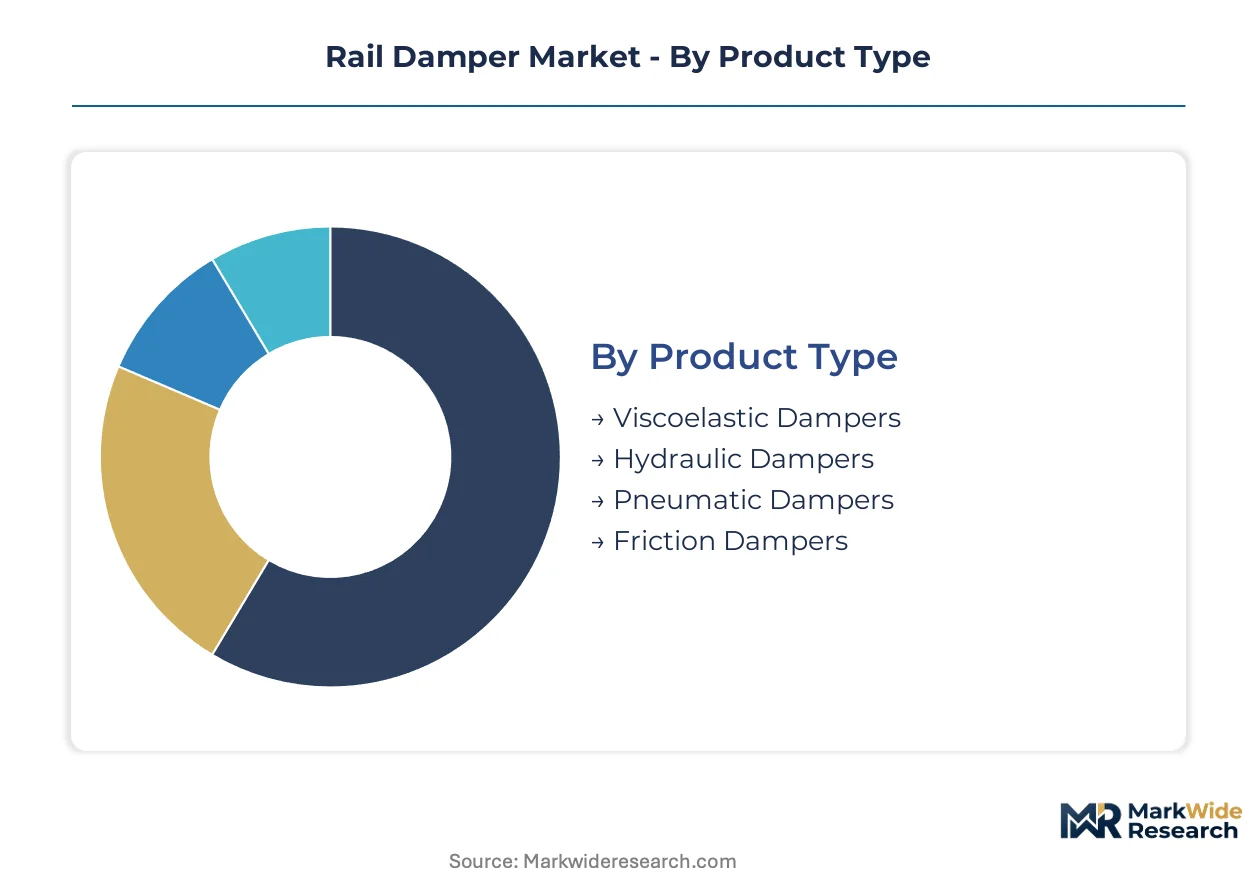
Rail damper procurement patterns diverge sharply across product architectures and operator categories, with technology transitions compressing traditional segment boundaries. Understanding these splits reveals where specification requirements concentrate and which customer types drive margin expansion.
Product Type:
Hydraulic dampers dominate export-led procurement from Germany and Japan, while viscoelastic systems anchor domestic manufacturing in China's coastal belt.
- Hydraulic Dampers:These systems deploy piston-cylinder architectures with mineral oil or bio-synthetic fluid displacement to generate velocity-dependent damping forces. Demand concentrates in Germany's industrial corridor where Deutsche Bahn and Siemens Mobility specify tunable force-velocity characteristics for heavy-haul freight corridors. The EU F-Gas Regulation is accelerating fluid reformulation timelines.
- Viscoelastic Dampers:Polymer shear layers convert kinetic energy to heat through molecular friction without sealed fluid circuits. China's CRRC procurement cycles favor these designs for urban transit maintenance interval compression, with NMPA-aligned certification requirements filtering supplier eligibility.
- Pneumatic Dampers:Compressed air chambers provide adjustable stiffness through orifice control, finding niche application in legacy rolling stock retrofits across India's Dedicated Freight Corridor.
- Friction Dampers:Dry sliding interfaces between metal or composite plates deliver constant damping coefficients, deployed primarily in cost-sensitive emerging markets where BIS certification governs component sourcing.
Hydraulic dampers hold the largest share; momentum sits with viscoelastic architectures.
Application:
Cost tier separation distinguishes premium high-speed specifications from standardized freight requirements.
- High-Speed Rail:Magnetorheological semi-active systems with real-time damping adjustment are climbing the fastest as Japan's METI JIS vibration limits and China's 350 km/h deployments drive specification upgrades. Shinkansen fleet renewals require sub-0.15 m/s² vertical acceleration compliance.
- Urban Transit:Predictive maintenance architectures with embedded sensor networks are expanding most quickly in Tokyo, Seoul, and Shanghai metro procurement cycles. Operators specify 15-year total cost of ownership guarantees.
- Freight Transportation:Load variability demands hydraulic architectures rated above 400 kN·s/m, with India's PLI scheme creating localized manufacturing incentives for foreign suppliers meeting domestic content thresholds.
- Passenger Rail Systems:Regional and intercity operators balance ride quality against capital constraints, favoring passive viscoelastic designs in Nordic markets where SJ and Vy consolidate lifecycle contracts.
High-speed rail commands premium pricing; urban transit shows steepest expansion trajectory.
End User:
Customer type determines contract structure, with state-owned operators driving long-term lifecycle agreements versus spot-buy component sourcing.
- OEMs:Rolling stock manufacturers like CRRC, Siemens Mobility, and Alstom integrate damper specifications into bogie platform designs, locking suppliers into 10-15 year production contracts with technology refresh clauses.
- Rail Operators:Deutsche Bahn, SNCF, and JR East are consolidating procurement into multi-year agreements bundling hardware, installation, and predictive maintenance subscriptions.
- Infrastructure Managers:Track authorities in Germany and France absorb 12-18% fluid cost premiums to maintain cross-border certification under EU F-Gas phasedown schedules.
- Maintenance Providers:Third-party service firms face warranty void risks when retrofitting magnetorheological dampers onto 1990s-era bogie designs, constraining addressable retrofit volumes.
OEMs dominate contract value; rail operators are gaining procurement leverage fastest.
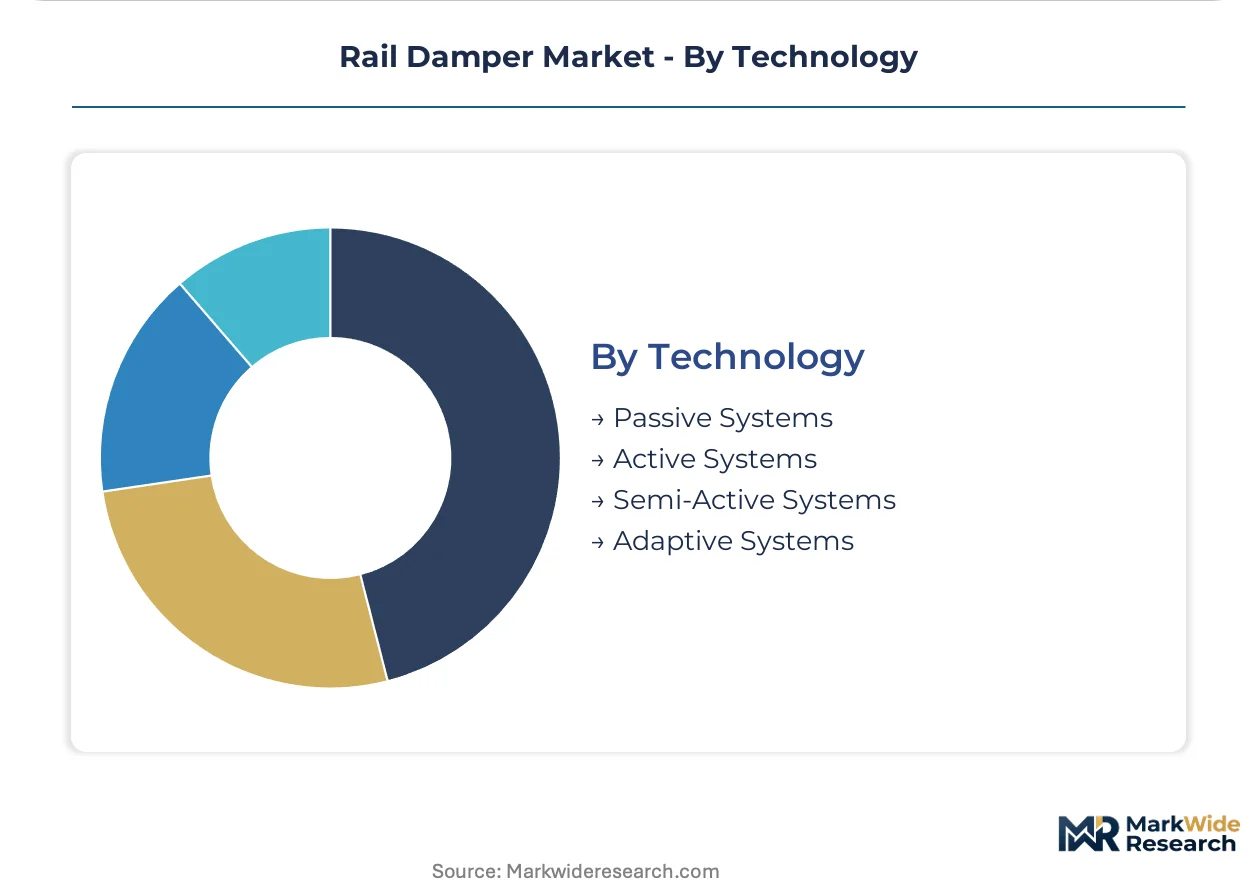
Technology:
Supply concentration in mechatronics engineering shapes competitive access to semi-active and adaptive architectures.
- Semi-Active Systems:Magnetorheological valves with real-time damping coefficient adjustment are expanding most quickly, enabling 40% extension of component replacement intervals in Tokyo and Seoul metro applications. The capability convergence decomposes historical segmentation between hydraulic specialists and electronic control suppliers.
- Passive Systems:Fixed-parameter elastomeric and hydraulic designs retain volume leadership in freight and heavy-haul segments where capital constraints override performance optimization.
- Active Systems:Electromagnetic force cancellation from automotive-derived suppliers penetrates premium locomotive segments where ride specifications exceed passive system limits.
- Adaptive Systems:Self-tuning algorithms with machine learning integration remain developmental, constrained by MDR conformity timelines for embedded sensor validation extending product cycles 8-14 months.
Passive systems retain installed base dominance; semi-active architectures show steepest share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Damper procurement patterns diverge sharply across geographies. China's coastal manufacturing belt favors viscoelastic maintenance-interval compression, while Germany's industrial corridor demands tunable hydraulic architectures for heavy-haul freight corridors.
Germany
Deutsche Bahn and Siemens Mobility drive specification upgrades for heavy-haul freight corridors. The EU Green Deal's modal shift targets force energy-efficient suspension priorities. Production concentrates in North Rhine-Westphalia and Bavaria, where component suppliers cluster around braking system integrators.
China
CRRC accelerates 350 km/h trainset deployments along the coastal manufacturing belt. NMPA-aligned rail equipment standards and GB technical codes govern domestic procurement eligibility. Yangtze River Delta and Pearl River Delta clusters generate concentrated demand for hydraulic dampers rated above 400 kN·s/m.
Japan
Shinkansen fleet renewals require sub-0.15 m/s² vertical acceleration compliance. METI enforces JIS vibration limits that filter damper performance thresholds. Kanto and Kansai regions anchor semi-active system adoption across Tokyo and Osaka metro procurement cycles.
India
The Dedicated Freight Corridor generates localized procurement channels for foreign suppliers. The PLI scheme for rail component manufacturing creates domestic content thresholds. Manufacturing activity concentrates in Maharashtra and Gujarat, where BIS certification requirements shape supplier eligibility.
France
SNCF consolidates procurement into multi-year lifecycle agreements bundling hardware and predictive maintenance. The EU F-Gas Regulation mandates phasedown schedules for hydrofluorocarbon-based hydraulic fluids. Industrial activity centers on Île-de-France and Auvergne-Rhône-Alpes, where operators absorb fluid cost premiums for cross-border certification.
Rail Damper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the rail damper landscape. Brake-damper bundlers and hydraulic architects occupy distinct competitive positions, with automotive-derived scale players compressing unit economics on polymer designs. The dominant competitive moves involve strategic partnerships for mechatronics capability acquisition and geographic expansion through localized certification compliance.
Among Germany-based integrated suppliers, Knorr-Bremse AG and ZF Friedrichshafen AG exemplify the tier-one archetype through braking systems heritage and automotive manufacturing scale respectively. Swedish specialist Dellner Dampers AB occupies a position within the hydraulic architecture tier. These three anchors represent contrasting pathways to damper market participation: bundled train control packages, compressed polymer unit economics, and specialized high-speed applications.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| ZF Friedrichshafen AG |
| Dellner Dampers AB |
| ITT Inc. |
| Voestalpine Railway Systems |
| Trelleborg |
| Schrey & Veit GmbH |
| ITV GmbH |
| Oleo International |
| Others |
Pricing and Supply Chain Analysis
Bio-synthetic hydraulic fluid substitution for hydrofluorocarbon-based formulations is redrawing supplier geography while compressing margin structures across European procurement channels. Rail operators in Germany and France now absorb elevated fluid premiums to maintain cross-border certification compliance under EU F-Gas phasedown schedules.
Pricing Analysis
Predictive maintenance subscriptions and 15-year total cost of ownership guarantees now anchor lifetime value capture for damper suppliers. Pricing stratifies across premium semi-active systems, standard hydraulic architectures, and economy-grade passive designs. Cost compression in viscoelastic polymer tiers intensifies as CRRC procurement volumes scale across China's coastal manufacturing belt. Freight operators in India and emerging markets exhibit highest price sensitivity, while Shinkansen fleet operators in Japan prioritize vibration compliance over unit economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors constrain just-in-time delivery windows for German and French damper assemblers. Fluorocarbon seal production clusters in Germany and Japan, while magnetorheological fluid feedstocks concentrate in North American specialty chemical corridors. Single-source vulnerability in elastomer compound formulations exposes tier-two suppliers to EUR/JPY exchange volatility. Distribution runs through OEM-integrated channels for new trainset production and operator-direct agreements for aftermarket retrofit cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semi-active magnetorheological technology is disrupting established competitive boundaries, with real-time damping adjustment compressing replacement intervals and enabling outcome-based contracting architectures.
For Market Incumbents: Fortify mechatronics capabilities through embedded software talent acquisition and magnetorheological valve supply chain control. Brake-damper bundlers must defend against automotive-derived electromagnetic active suspension entrants penetrating premium locomotive segments. Backward integration into fluorocarbon seal manufacturing mitigates input cost volatility from Japanese supply concentration. For New Entrants and Emerging Players: Differentiate on digital twin integration and condition-monitoring subscription models rather than hardware-only positioning. India's Dedicated Freight Corridor PLI scheme offers the most penetrable geography for foreign suppliers meeting BIS certification thresholds. Urban transit operators in Southeast Asian metro systems present uncaptured demand for maintenance-interval-compressing viscoelastic architectures. For Investors and Strategic Acquirers: Capital is best deployed toward mechatronics-capable tier-two suppliers with proven semi-active system deployments and operator maintenance framework integrations. Long-term viability hinges on adaptive algorithm development and machine learning validation timelines. Watch MDR conformity acceleration for embedded sensor systems as the inflection signal for product cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetorheological Valve Supply Integration | Captures margin pool from real-time damping coefficient adjustment demanded by Tokyo and Seoul metro operators. |
| Bio-Synthetic Fluid Formulation Partnership | Secures EU F-Gas Regulation compliance for cross-border rolling stock certification in German and French corridors. |
| Digital Twin Platform Development | Enables recurring revenue streams through physics-based damper models integrated with operator maintenance frameworks. |
| BIS Certification Localization | Unlocks procurement channels under India's PLI scheme for rail component manufacturing in Maharashtra and Gujarat. |
| Semi-Active System Retrofit Program | Addresses legacy fleet integration complexity constraining addressable volumes in 1990s-era bogie designs. |
Research Methodology
Cross-validation between OEM procurement disclosures and operator maintenance framework documentation anchors the qualitative findings in this study. Primary interviews with rolling stock platform engineers, rail operator fleet directors, damper manufacturing R&D leads, and infrastructure manager track maintenance heads combined with secondary validation from EU F-Gas Regulation filings, METI JIS standard publications, NMPA-aligned GB technical codes, and CRRC procurement cycle disclosures. Bottom-up unit shipment estimates and top-down rolling stock production data triangulate market sizing across product architectures and application segments.
Sensitivity analysis around magnetorheological adoption velocity and bio-synthetic fluid cost premiums shapes the projection framework. Segmentation dimensions modeled include damper technology tier, trainset speed class, operator ownership structure, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to OEM production schedules and fleet renewal timelines. Industry-specific forecast inputs incorporate Deutsche Bahn modal shift procurement priorities and CRRC 350 km/h deployment acceleration.
Material uncertainties — regulatory timeline shifts for MDR embedded sensor validation, EUR/JPY exchange volatility affecting fluorocarbon seal input costs, and active electromagnetic suspension substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology transition velocities and procurement consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rolling Stocks Market
Railway
Railway Automated Inspection Equipment Market
Railway
Check Rails Market
Railway
Smart Railways Market
Railway
Rail Glazing Market
Railway
Railway Axle Market
Railway
Rail Transit Traction Converter Market
Railway
Heritage Railways Trains Market
Railway
Road-Rail Vehicles Market
Railway
Railway Buffer Stops Market
Railway
Railway Bearing Market
Railway
Latin America Connected Rail Market
Railway
Railroads Market
Railway
Locomotive Parking Brake Market
Railway
Bullet Train Market
Railway
Global High-Speed Train Seat Market