
 Safety Protective Helmet Market | 2026-2036
Safety Protective Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Protective Helmet Market Insights
Helmet-as-a-service subscription models featuring IoT-enabled impact monitoring and predictive replacement scheduling is expanding revenue streams beyond unit sales. 3M Company leverages its materials science portfolio to sustain premium positioning in polycarbonate headgear. MSA Safety Incorporated anchors North American industrial distribution through captive channel relationships with energy and utility buyers. Honeywell International Inc. differentiates via integrated connected-safety platforms that bundle helmets with gas detection and communications hardware.
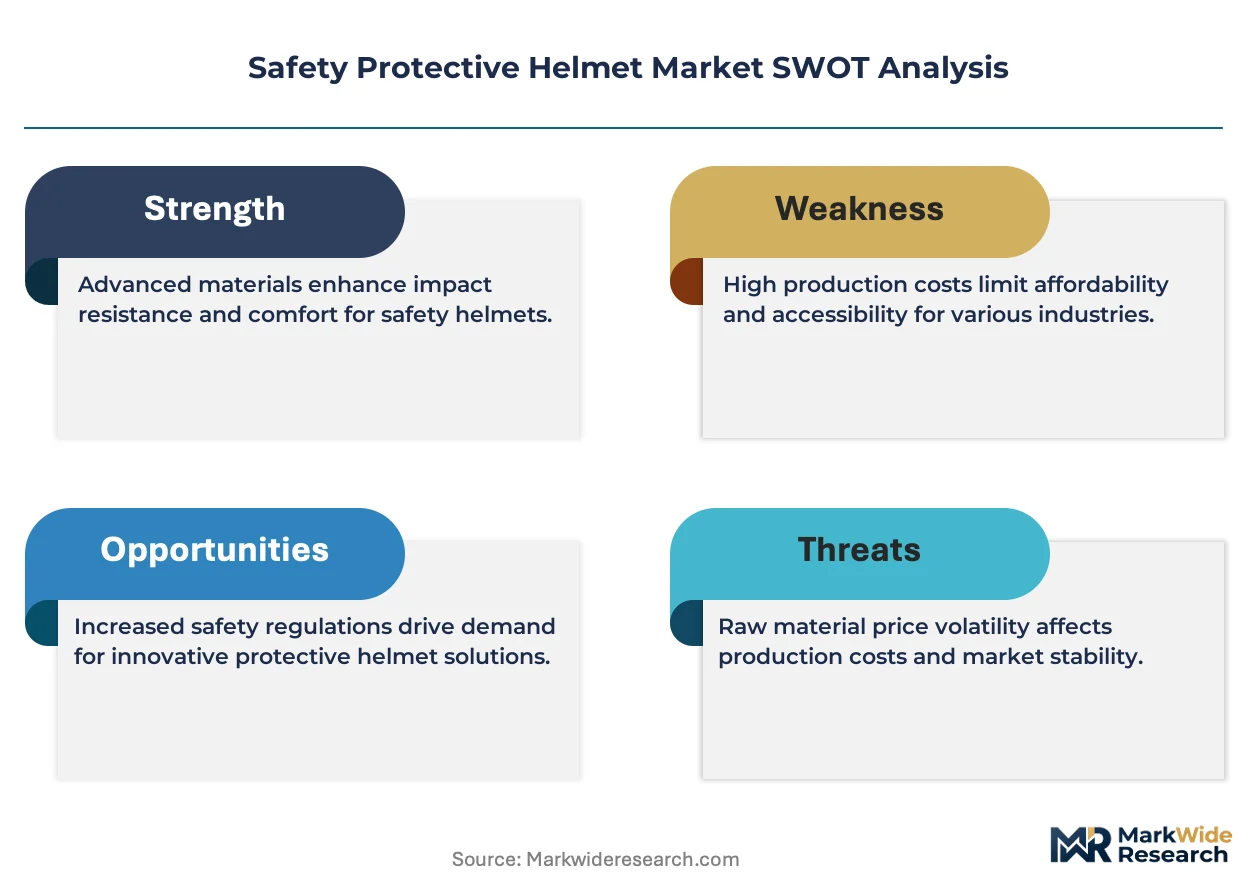
A safety protective helmet is a rigid head enclosure engineered from polycarbonate, fiberglass, ABS, or high-density polyethylene with a suspension system designed to absorb and dissipate kinetic energy from impacts, falls, or projectile penetration in hazardous work environments. Hard hats dominate volume sales across construction and manufacturing end users where ANSI Z89.1 and EN 397 compliance is mandatory, though full-face helmets command superior margins in oil & gas and firefighting applications due to integrated respiratory and thermal protection requirements. Polycarbonate material formulations are capturing share from traditional HDPE in segments where optical clarity and repeated impact durability justify cost premiums.
OSHA workplace safety directives in the United States, EN 397 and CE marking requirements across Europe, and China's GB 2811 national standard collectively define product certification barriers and recurring testing obligations for manufacturers. ISO 3873 provides the foundational international benchmark for industrial helmet performance that national regulators reference when updating domestic rules. Stakeholders must monitor evolving material substitution trends and connected-safety integration requirements as procurement specifications shift from passive protection toward real-time hazard intelligence.
Market Dynamics
Connected-safety convergence is compressing procurement cycles as industrial buyers demand integrated headgear systems rather than standalone protective equipment. This structural shift forces manufacturers to bundle sensors, communications modules, and predictive analytics into helmet platforms.
Growth Catalysts
- OSHA enforcement escalation:United States workplace safety inspections are intensifying across construction and energy infrastructure, mandating ANSI Z89.1-compliant headgear replacement at accelerated intervals.
- China's state infrastructure buildout:GB 2811 certification requirements are expanding across railway, highway, and port construction projects as state-backed investment multiplies worksite density.
- Polycarbonate material substitution:Optical-grade formulations are capturing share from high-density polyethylene in segments where repeated impact durability and thermal stability justify cost premiums.
Market Restraints
- Petrochemical input volatility:Polycarbonate and ABS resin prices fluctuate with crude oil derivatives, compressing margin stability for manufacturers without captive polymer supply.
- Testing laboratory concentration:Third-party EN 397 and ANSI Z89.1 certification capacity clusters in Germany and the United States, creating bottlenecks for new market entrants.
- Substitution from soft-shell alternatives:Bump caps penetrate light manufacturing and warehousing applications where falling-object hazards fall below hard-hat thresholds.
Strategic Opportunities
- India's industrial corridor expansion:BIS certification mandates are tightening across steel, cement, and power plant construction as the PLI scheme accelerates manufacturing capacity buildout.
- Helmet-as-a-service platforms:IoT-enabled subscription models bundling impact monitoring, predictive replacement scheduling, and compliance documentation are displacing transactional unit sales.
- Wearable sensor convergence:Integration of biometric monitoring, gas detection, and location tracking creates premium pricing power in oil & gas and confined-space applications.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for impact sensors, mesh networking, and edge computing exceeds the talent pool available to traditional PPE manufacturers.
- Multi-standard certification complexity:Simultaneous OSHA, EN 397, and GB 2811 compliance testing extends product launch timelines and fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Protective Helmet Market |
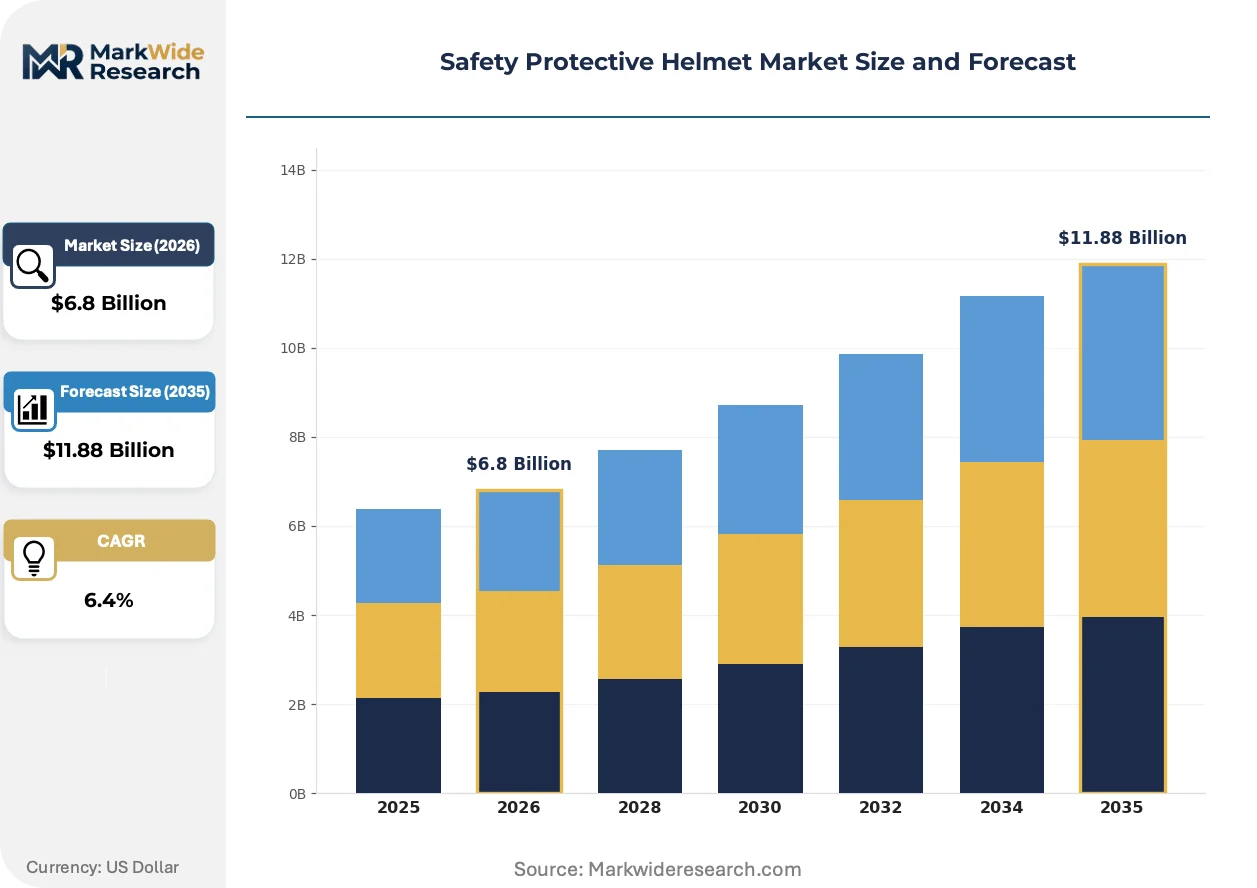
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Hats, Bump Caps, Face Shields, Full-Face Helmets End User: Construction, Manufacturing, Oil & Gas, Firefighting Material: Polycarbonate, Fiberglass, ABS, High-Density Polyethylene Standards Compliance: ANSI, EN, ISO, AS |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety Incorporated, Bullard, JSP Limited, Pyramex Safety Products LLC, Schuberth GmbH, Delta Plus Group, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Protective Helmet Market Trends and Innovations
Sensor miniaturization and edge computing capabilities are embedding intelligence directly into helmet platforms, transforming passive protective equipment into active hazard-detection nodes. This convergence is redrawing competitive boundaries between traditional PPE manufacturers and industrial IoT specialists.
Polycarbonate optical-grade formulations are consolidating market position in premium industrial segments. Oil & gas operators and electrical utility crews specify these materials for repeated impact durability and arc-flash resistance. The technology is consolidating supplier power among chemical conglomerates with integrated resin-to-helmet production capabilities.
REACH substance restrictions and the EU Green Deal are tightening material disclosure requirements for polycarbonate and fiberglass formulations. Manufacturers must document full supply chain chemistry to maintain CE marking eligibility. European construction and utility procurement specifications now prioritize recyclability and bio-based content in helmet shell materials.
Buyer consolidation among multinational infrastructure contractors is compressing vendor rosters and extending contract durations. EPC firms in the Middle East and Southeast Asia are mandating multi-year helmet supply agreements with embedded IoT service tiers. Saudi Arabia's giga-project construction pipeline exemplifies this shift toward integrated safety procurement frameworks.
Safety Protective Helmet Market Segmentation
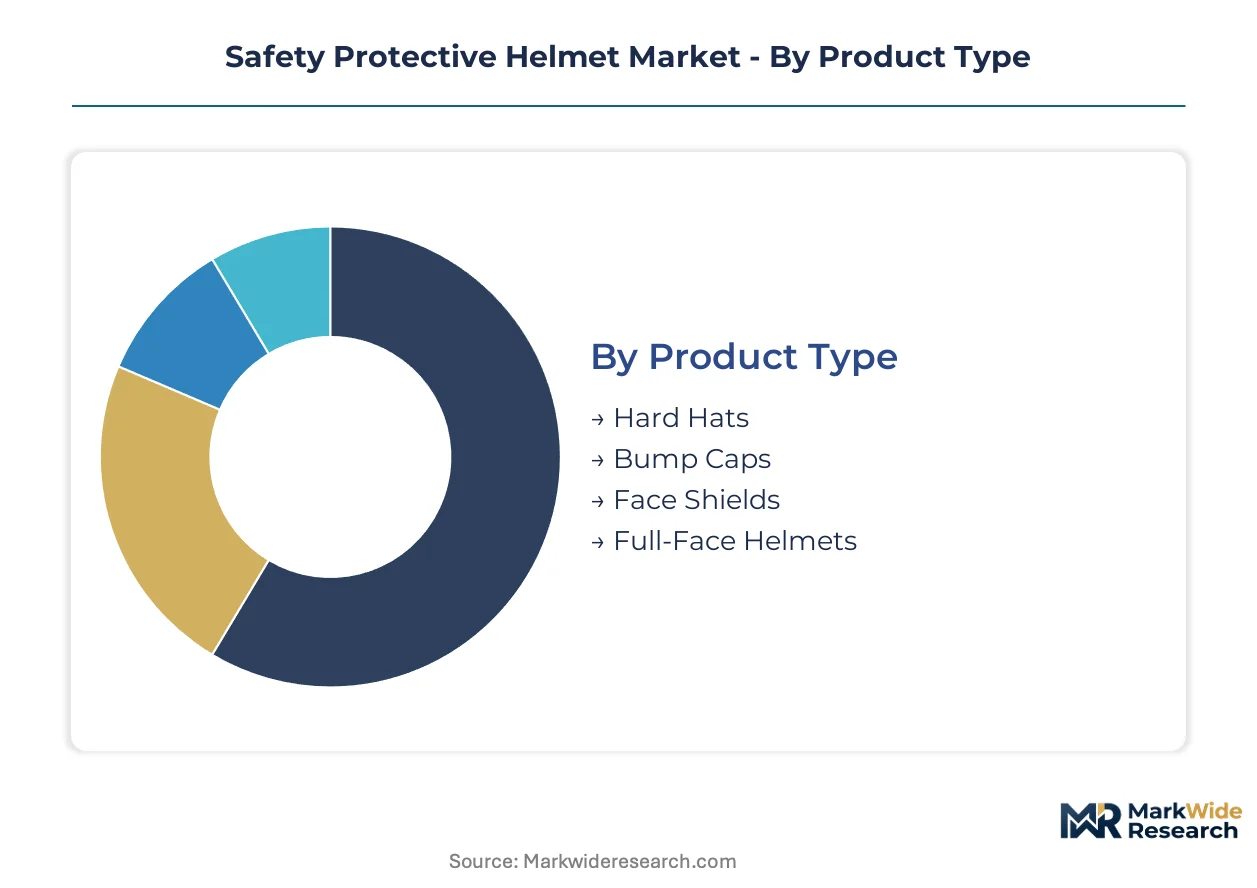
Segmentation in the safety protective helmet market reflects divergent procurement logics across standalone commodity purchases and integrated connected-safety systems. Material specifications and certification tiers increasingly determine supplier selection criteria as buyers consolidate vendor relationships.
Product Type:
Integration depth varies sharply across this category, with standalone passive protection dominating volume sales while sensor-embedded configurations capture premium expansion.
- Hard Hats:These rigid head enclosures utilize suspension systems to absorb kinetic energy from impacts and falling objects. Construction procurement across China's state-backed infrastructure programs drives concentrated demand where GB 2811 compliance is mandatory for site access.
- Full-Face Helmets:Integrated respiratory, thermal, and communications protection systems distinguish these configurations. Oil & gas operators in Saudi Arabia's giga-project pipeline specify these for confined-space and arc-flash environments where multi-hazard protection justifies cost premiums.
- Bump Caps:Lightweight soft-shell alternatives for low-impact environments.
- Face Shields:Supplementary protection modules typically mounted to hard hat brims.
Volume placements concentrate in Hard Hats; the faster expansion belongs to Full-Face Helmets.
End User:
Application environments dictate performance specifications, with outdoor heavy infrastructure imposing fundamentally different requirements than controlled manufacturing floors.
- Construction:Outdoor exposure to falling debris, electrical hazards, and weather extremes defines procurement specifications. OSHA enforcement escalation across United States job sites accelerates replacement cycles for ANSI Z89.1-compliant headgear.
- Oil & Gas:Explosive atmospheres and hydrogen sulfide exposure mandate integrated gas detection and communications. Middle East EPC contractors are embedding multi-year helmet supply agreements with IoT service tiers into project procurement frameworks.
- Manufacturing:Assembly line and warehousing environments with standardized hazard profiles.
- Firefighting:Thermal protection and SCBA compatibility requirements for emergency response.
Construction absorbs the highest unit volumes; oil & gas generates the steepest expansion trajectory for connected-safety configurations.
Material:
Cost tier positioning separates commodity resin formulations from optical-grade engineered polymers with performance premiums.
- Polycarbonate:Optical-grade formulations deliver repeated impact durability and thermal stability for electrical utility and oil & gas applications. European REACH substance restrictions and EU Green Deal disclosure requirements are tightening supply chain chemistry documentation for these formulations.
- High-Density Polyethylene:Commodity resin dominates mass-market construction procurement where single-impact protection satisfies regulatory minimums. Petrochemical input volatility compresses margin stability for manufacturers without captive polymer supply.
- Fiberglass:Composite reinforcement for high-heat and electrical arc applications.
- ABS:Cost-optimized engineering plastic for standard industrial environments.
High-Density Polyethylene retains the largest installed base; polycarbonate is gaining share fastest in premium specification segments.
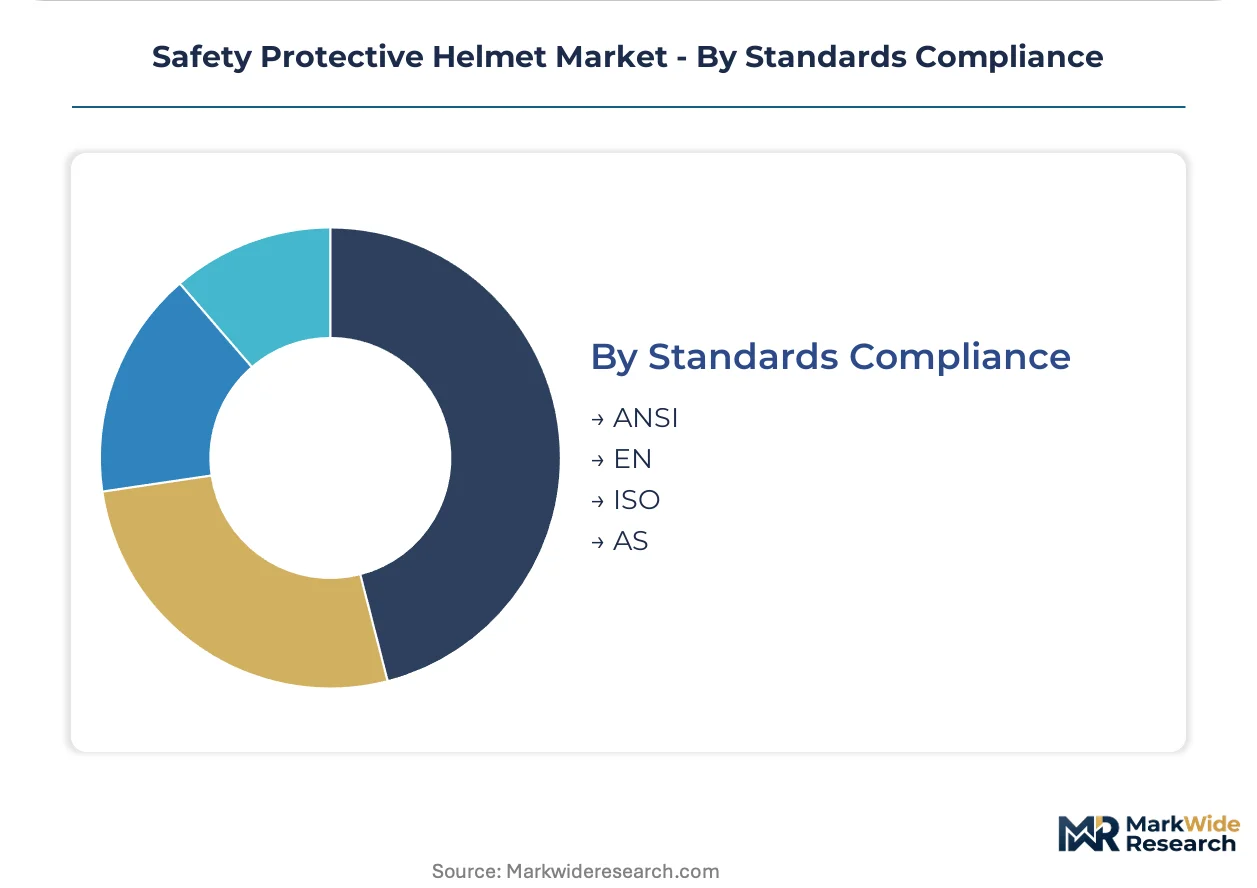
Standards Compliance:
Certification geography determines market access, with multi-standard testing extending launch timelines for global suppliers.
- ANSI:United States workplace safety mandate enforced through OSHA inspections. United States energy infrastructure contractors require ANSI Z89.1 documentation for vendor qualification.
- EN:European CE marking prerequisite with testing laboratory concentration in Germany creating certification bottlenecks.
- ISO:International reference standard that national regulators adapt for domestic rule updates.
- AS:Australian certification requirements for Oceania market access.
ANSI certifications dominate North American placements; EN testing capacity constraints slow European market entry for new suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States while procurement demand concentrates across China's infrastructure corridors and the Middle East's giga-project pipeline. This geographic split creates supply chain tensions as lead times stretch for premium polycarbonate formulations. Regulatory divergence between OSHA, EN 397, and GB 2811 standards forces manufacturers to maintain multiple certification inventories.
United States
Energy infrastructure contractors and construction conglomerates drive ANSI Z89.1-compliant procurement volumes. OSHA enforcement escalation across Texas and Gulf Coast petrochemical corridors accelerates replacement cycle frequencies. Houston anchors North American distribution networks for MSA Safety Incorporated's captive channel relationships with utility buyers.
Germany
EN 397 certification testing laboratory concentration creates bottlenecks for new market entrants seeking CE marking. REACH substance restrictions and EU Green Deal disclosure requirements tighten material chemistry documentation for polycarbonate formulations. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate demand from automotive and chemical plant construction.
China
State-backed railway, highway, and port construction programs multiply GB 2811-mandated worksite density requirements. MIIT and SAMR oversight of industrial safety equipment quality standards intensifies domestic certification scrutiny. Yangtze River Delta infrastructure corridors absorb concentrated polycarbonate helmet volumes for bridge and tunnel projects.
Saudi Arabia
Giga-project construction pipelines mandate multi-year helmet supply agreements with embedded IoT service tiers. SFDA and national safety authority coordination enforces dual compliance for imported protective equipment. NEOM and Red Sea Project sites specify full-face helmet configurations for confined-space and arc-flash environments.
India
PLI scheme acceleration across steel, cement, and power plant construction tightens BIS certification mandates for site access. Central and state industrial corridor expansion multiplies worksite safety officer procurement quotas. Maharashtra and Gujarat manufacturing hubs concentrate demand from refinery and port infrastructure buildout.
Safety Protective Helmet Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material formulation, embedded systems integration, and certification service tiers. The vendor base separates into consolidated chemical conglomerates with captive resin supply, mid-scale fabricators dependent on spot polymer markets, and emerging IoT platform specialists. Three archetypes dominate: integrated materials-science conglomerates, distribution-anchored safety specialists, and connected-safety platform bundlers. Competitive moves concentrate on M&A for sensor technology capabilities and strategic partnerships with EPC contractors for multi-year supply agreements.
Among North American safety equipment specialists, MSA Safety Incorporated exemplifies distribution-anchored positioning through captive channel relationships. Honeywell International Inc. occupies the connected-safety platform tier, bundling helmet systems with gas detection hardware. 3M Company represents integrated materials-science conglomerate positioning, leveraging polycarbonate formulation capabilities for premium specification segments.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Bullard |
| JSP Limited |
| Pyramex Safety Products LLC |
| Schuberth GmbH |
| Delta Plus Group |
| Drägerwerk AG & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
China's state-backed infrastructure procurement consolidation is forcing polycarbonate resin suppliers to absorb GB 2811 certification costs while maintaining volume commitments to tier-one manufacturers. This demand-side compression cascades into margin pressure across injection-molding tiers and regional distribution layers.
Pricing Analysis
Cost-down pressure on economy-tier HDPE helmets accelerates as spot resin volatility compresses fabricator margins without captive polymer supply. Three-tier pricing structure across premium, standard, and economy levels separates optical-grade polycarbonate formulations certified for arc-flash protection from commodity HDPE meeting single-impact ANSI Z89.1 minimums. Pricing pressure stems from petrochemical input volatility that manufacturers without backward integration into resin production cannot hedge effectively. Construction procurement teams in China exhibit highest price sensitivity, while oil & gas operators in Saudi Arabia's giga-project pipeline prioritize integrated IoT service tiers over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Shanghai anchor hub-and-spoke fulfillment patterns for ANSI, EN, and GB-certified inventory pools. Manufacturing concentrates in China, Germany, and the United States, with polycarbonate resin production drawing from petrochemical complexes in the US Gulf Coast, Northeast Asia, and Western Europe. Supply chain risk centers on single-source vulnerability for optical-grade polycarbonate formulations where integrated resin-to-helmet capabilities cluster among chemical conglomerates. Distribution runs through captive channel relationships with energy utility buyers and EPC contractor multi-year agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The safety protective helmet market is becoming a vertical-integration race where captive resin supply and embedded firmware development capabilities determine margin capture. Players without upstream polymer control or downstream IoT platform integration face structural disadvantage.
For Market Incumbents: To counter embedded systems engineering scarcity, secure exclusive partnerships with industrial IoT specialists for sensor firmware development and predictive analytics platforms. Deepen backward integration into polycarbonate resin production to insulate margin stability from petrochemical volatility. Anchor channel control through multi-year helmet-as-a-service agreements with Saudi Aramco and Chinese state infrastructure contractors. For New Entrants and Emerging Players: The mid-tier price-point gap between Honeywell's connected-safety bundles and commodity HDPE hard hats offers white-space entry for BIS-certified fabricators serving India's PLI-accelerated industrial corridor. Target Maharashtra and Gujarat refinery construction where safety officer procurement quotas outstrip established vendor capacity. Pursue direct EPC contractor relationships rather than distribution intermediaries to capture margin and build reference accounts. For Investors and Strategic Acquirers: The window for entry favors mid-scale European fabricators with EN 397 certification infrastructure and latent IoT engineering capacity. Long-term viability hinges on acquiring sensor technology capabilities and integrating predictive replacement scheduling platforms before buyer consolidation among multinational contractors closes vendor rosters. Watch for inflection when Saudi giga-projects mandate full-face helmet configurations with embedded gas detection as standard specification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Resin | Captive supply from BASF or Covestro partnerships insulates margin from crude derivative volatility. |
| IoT Platform Acquisition | Sensor firmware capabilities from industrial IoT specialists transform passive helmets into active hazard-detection nodes. |
| Multi-Year EPC Supply Agreement | NEOM and Red Sea Project contractors embed helmet-as-a-service tiers into procurement frameworks. |
| GB 2811 Certification Investment | MIIT and SAMR scrutiny intensifies domestic testing requirements for China infrastructure access. |
| India BIS Certification Buildout | PLI scheme acceleration across steel and cement construction tightens site access mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with safety equipment procurement managers at EPC contractors, plant engineers at oil & gas operators, and distribution channel partners for industrial PPE validated demand-side assumptions. Secondary sources included OSHA enforcement databases, EN 397 certification laboratory records, SAMR GB 2811 registration filings, and SEC 10-K disclosures from listed manufacturers. Bottom-up volume modeling across material tiers and top-down value reconciliation against customs trade flows ensured cross-verification.
Granularity-level modeling tracked polycarbonate versus HDPE material substitution, ANSI versus EN versus GB certification tier penetration, and connected-safety versus passive protection configuration splits across the projection horizon. CAGRs derived from regression analysis against construction spending indices, oil & gas capital deployment, and regulatory enforcement intensity trajectories. Industry-specific forecast inputs incorporated polycarbonate resin price elasticity coefficients and IoT sensor adoption curves in confined-space applications.
Inputs from OSHA inspection databases and SAMR certification registries were available through the study window; gaps in real-time EPC contractor procurement pipeline data introduce uncertainty bands around Saudi giga-project demand timing. Forecasts reflect documented assumptions regarding petrochemical input stability and regulatory enforcement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market