
 North America Riot Control Equipment Market | 2026-2036
North America Riot Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Riot Control Equipment Market Analytics
NIJ compliance mandates for less-lethal systems is expanding the addressable market for certified manufacturers. Axon Enterprise leverages its body-worn camera ecosystem to cross-sell integrated crowd-control platforms. The Safariland Group anchors its position through captive distribution to federal law enforcement agencies. Combined Systems competes on manufacturing scale for aerosol irritant and kinetic impact munitions.
Riot control equipment encompasses protective gear, dispersal agents, and command systems engineered for civilian crowd management without lethal force, typically incorporating NIJ Level IIIA ballistic ratings or OC concentration thresholds measured in Scoville Heat Units. Non-lethal weapons and surveillance equipment represent the dominant product categories, with acoustic hailing devices and drone-based situational awareness systems capturing the fastest growth trajectories as agencies prioritize standoff distance. Law enforcement applications command the largest share of procurement volumes, while event security segments exhibit higher margin profiles due to recurring seasonal demand cycles.
Federal buyers navigate overlapping compliance requirements from the National Institute of Justice, EPA registrations for chemical irritants under FIFRA, and FAA operational waivers for unmanned aerial systems deployed in crowd monitoring. State-level procurement statutes in California, Texas, and New York impose additional certification layers that filter vendor eligibility. Stakeholders must track pending Congressional appropriations for homeland security equipment grants and evolving municipal liability standards governing less-lethal deployment protocols.
Market Dynamics
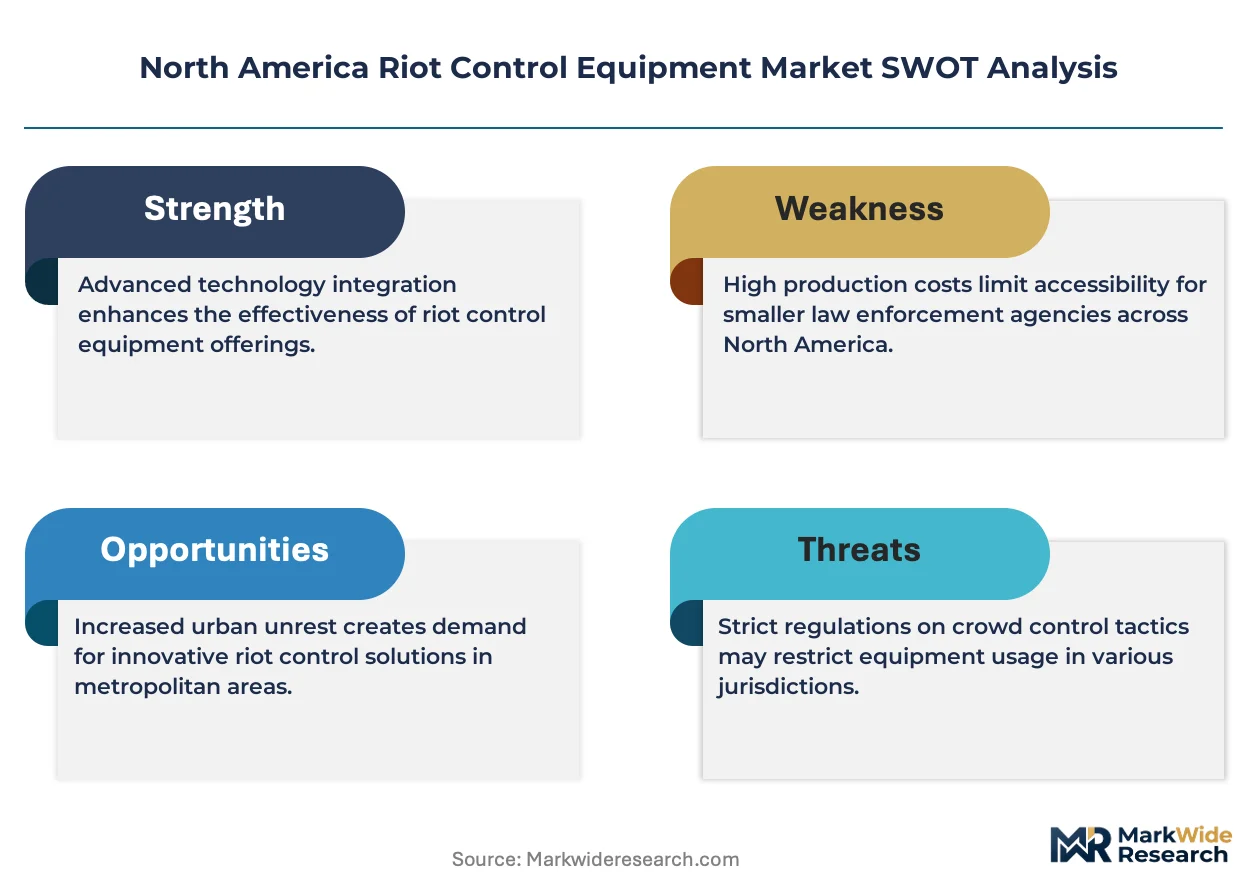
NIJ certification mandates for less-lethal technologies are compressing product development cycles while federal procurement under updated use-of-force guidelines expands the qualified vendor pool. Municipal police departments in high-budget states now require certified dispersal agents and ballistic-rated protective gear as standard procurement terms.
Growth Catalysts
- Updated Use-of-Force Guidelines:Federal law enforcement agencies are expanding procurement volumes under revised deployment protocols that mandate less-lethal alternatives for crowd management scenarios.
- California Municipal Budgets:Dedicated crowd-control allocations in the state's largest police departments are concentrating demand for integrated command systems and protective equipment.
- Acoustic Hailing Devices:Standoff-distance priorities among tactical units are accelerating adoption of long-range communication systems that reduce physical confrontation risks.
Market Restraints
- EPA FIFRA Registration Delays:Chemical irritant manufacturers face extended approval timelines for new OC concentration formulations, constraining product pipeline velocity.
- OC Oleoresin Supply Concentration:Capsicum extract sourcing depends on concentrated agricultural regions in India and China, exposing producers to input volatility and trade friction.
- Ballistic Material Cost Structure:NIJ Level IIIA-rated protective gear requires aramid fiber and ceramic plate inputs subject to aerospace and defense competing demand.
Strategic Opportunities
- Texas Event Security Vertical:Seasonal demand cycles for stadium and convention protection services offer higher-margin recurring revenue streams distinct from municipal procurement.
- Drone-Based Situational Awareness:FAA operational waivers for unmanned aerial systems in crowd monitoring create white space for integrated aerial-ground command platforms.
- Cross-Selling Through Body-Worn Ecosystems:Vendors with established camera infrastructure can bundle crowd-control platforms into existing law enforcement technology contracts.
Industry Challenges
- NIJ Certification Timeline Compression:Manufacturers must navigate extended testing protocols for less-lethal technologies while federal buyers accelerate procurement schedules.
- Multi-Agency Compliance Stacking:Vendors face overlapping EPA registrations for chemical irritants, FAA waivers for aerial systems, and state-level procurement statutes that fragment go-to-market execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Riot Control Equipment Market |
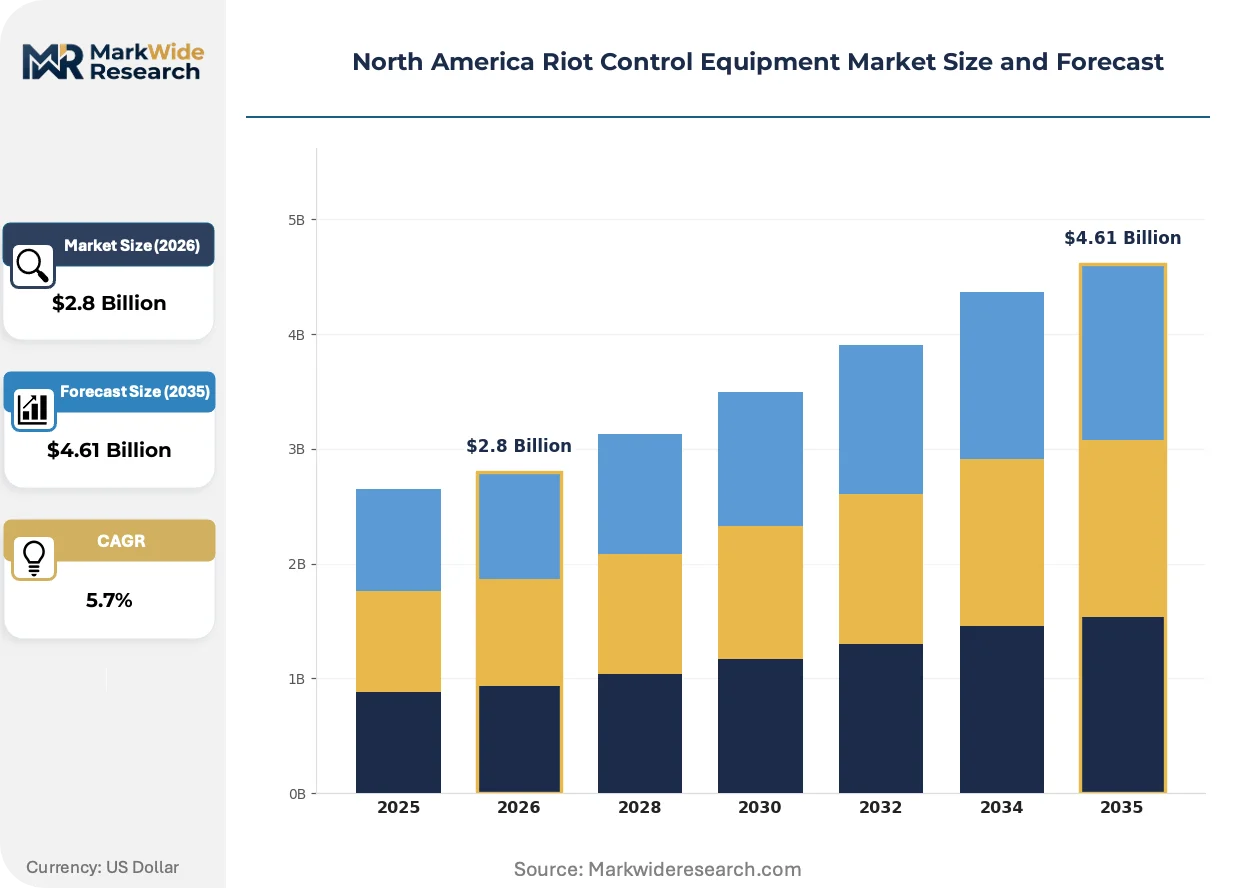
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Barriers, Non-Lethal Weapons, Surveillance Equipment, Communication Devices Application: Law Enforcement, Military Operations, Crowd Management, Event Security End User: Government Agencies, Private Security Firms, Military Organizations, Law Enforcement Agencies Technology: Ballistic Shields, Tear Gas, Drones, Acoustic Hailing Devices |
| Companies Covered | Axon Enterprise, Inc., The Safariland Group, Combined Systems, Inc., Byrna Technologies Inc., NonLethal Technologies, Inc., PepperBall Technologies, Blackhawk, Defense Technology, Central Lake Armor Express, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Riot Control Equipment Market Evolving Landscape
Product evolution centers on standoff-distance technologies and integrated command platforms that reduce personnel exposure while improving situational coordination. Regulatory pressure from certification bodies is simultaneously reshaping R&D investment priorities.
Drone-based situational awareness systems are integrating thermal imaging and real-time video feeds into centralized command interfaces. Tactical units in Texas and California municipal departments are deploying these platforms for pre-event site assessment and live crowd-density monitoring. This convergence of aerial hardware and analytics software is compressing the traditional separation between surveillance and response functions.
NIJ certification standards for less-lethal technologies are mandating expanded ballistic testing and OC concentration documentation. Manufacturers must now submit products through extended validation protocols before federal eligibility. The protective gear segment faces the steepest compliance burden, with Level IIIA ratings requiring documented performance against multiple threat types.
Municipal procurement departments are consolidating vendor relationships around integrated platform providers rather than point-product suppliers. Texas and California police departments now prioritize single-source contracts covering body-worn cameras, command software, and crowd-control equipment. This buyer concentration favors vendors with captive distribution networks and multi-product portfolios over specialized manufacturers.
North America Riot Control Equipment Market Segmentation
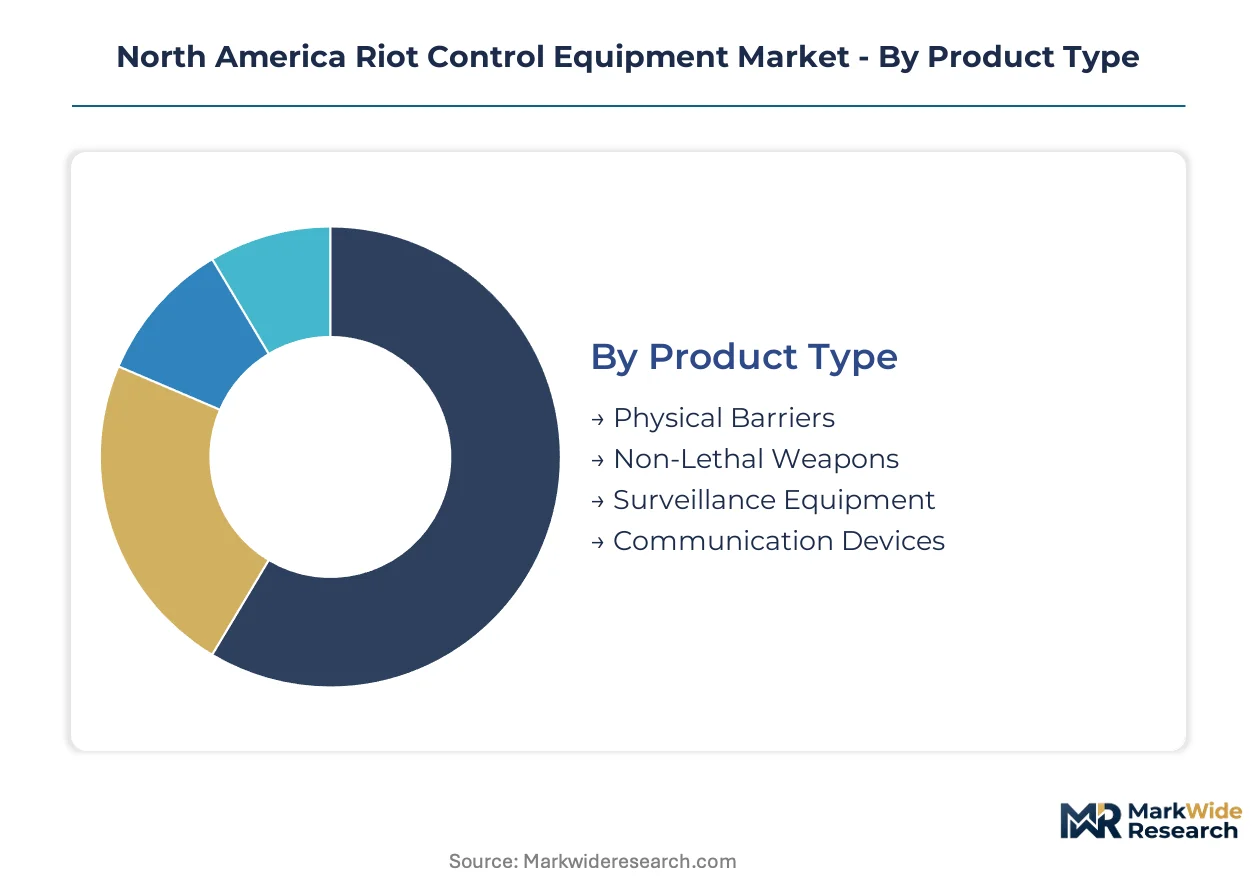
Procurement patterns across North American riot control equipment diverge sharply by operational context, with federal agencies prioritizing NIJ certification compliance while municipal departments balance budget constraints against liability exposure. Understanding these segment-specific buying logics reveals where product development investments concentrate and which vendor capabilities command premium positioning.
Product Type:
Cost tier differentiation separates commodity protective gear from integrated command platforms that capture multi-year maintenance contracts.
- Non-Lethal Weapons:Kinetic impact munitions, aerosol irritants, and directed-energy systems operate under EPA FIFRA registrations and NIJ less-lethal certification protocols. Texas and California municipal police departments now mandate OC concentration documentation and ballistic performance testing as standard procurement terms, compressing vendor qualification timelines.
- Surveillance Equipment:Thermal imaging systems, crowd-density analytics software, and centralized video management platforms integrate with existing law enforcement IT infrastructure. Demand concentrates in federal agencies seeking standoff-distance capabilities that reduce personnel exposure during large-scale crowd events.
- Physical Barriers:Modular fencing, vehicle barriers, and rapid-deployment shield walls with NIJ Level IIIA ratings.
- Communication Devices:Encrypted radio networks and command coordination software for multi-agency operations.
Non-lethal weapons lead volumes today; surveillance equipment is gaining share fastest.
Application:
Volume concentration tracks municipal budget scale, with high-expenditure states driving platform-level procurement rather than point-product purchasing.
- Law Enforcement:Municipal police departments and sheriff offices deploy protective gear, dispersal agents, and command systems for routine crowd management and civil disturbance response. California and Texas maintain the largest dedicated crowd-control budgets, with procurement cycles increasingly favoring single-source vendors offering integrated camera-software-equipment bundles.
- Event Security:Stadium protection services, convention center security, and temporary venue hardening generate recurring seasonal demand with higher margin profiles than municipal procurement. Texas event security verticals exhibit particularly strong seasonal cycles tied to professional sports and energy sector conferences.
- Military Operations:Domestic base security and civil support missions under Posse Comitatus constraints.
- Crowd Management:Protest response and public assembly oversight requiring graduated force protocols.
Law enforcement dominates absolute procurement volumes; event security delivers superior margin capture.
End User:
Customer type determines compliance burden depth, with federal buyers navigating multi-agency certification stacking that filters vendor eligibility.
- Government Agencies:Federal law enforcement, homeland security departments, and state emergency management offices procure under Congressional appropriations cycles with stringent NIJ, EPA, and FAA overlapping requirements. These buyers prioritize documented compliance trails and established vendor relationships over price competition.
- Law Enforcement Agencies:Municipal police departments and county sheriff offices balance equipment effectiveness against municipal liability standards governing less-lethal deployment protocols. California and Texas departments increasingly consolidate vendor relationships around integrated platform providers.
- Private Security Firms:Corporate protection services and contracted venue security operating under state licensing regimes.
- Military Organizations:Domestic installation security units with distinct procurement channels from civilian law enforcement.
Government agencies anchor federal procurement volumes; law enforcement agencies drive platform consolidation trends.
Technology:
Maturity gradients separate established protective equipment from emerging aerial and acoustic systems facing evolving regulatory frameworks.
- Drones:Unmanned aerial systems with thermal imaging and real-time video feeds require FAA operational waivers for crowd monitoring applications. Tactical units in California and Texas municipal departments deploy these platforms for pre-event site assessment and live crowd-density monitoring, compressing traditional separations between surveillance and response functions.
- Acoustic Hailing Devices:Long-range communication systems enabling standoff-distance crowd direction without physical confrontation. These systems are climbing the fastest adoption curves as agencies prioritize personnel safety and de-escalation protocols.
- Ballistic Shields:NIJ Level IIIA-rated portable protection requiring aramid fiber and ceramic plate inputs.
- Tear Gas:OC and CS formulations subject to EPA FIFRA registration and state-level deployment restrictions.
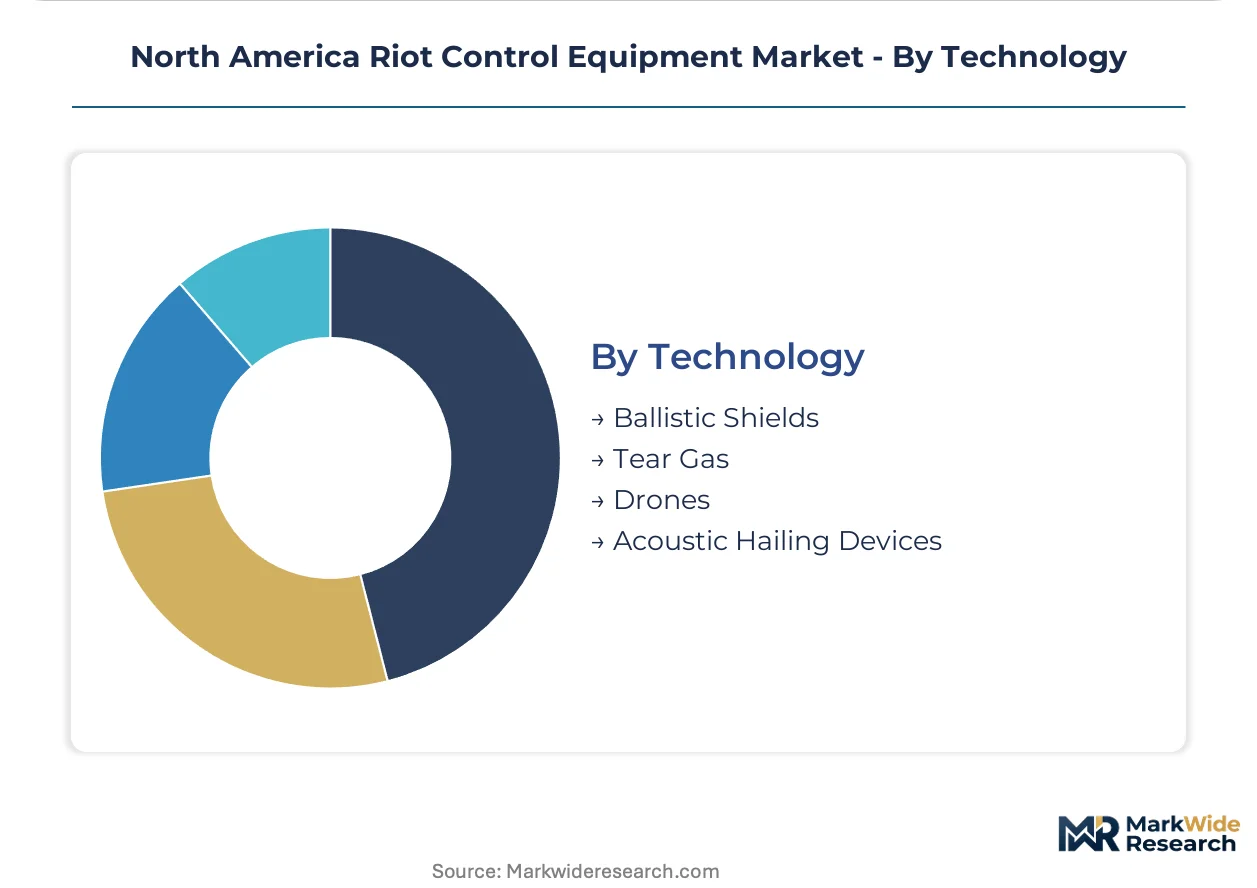
Ballistic shields and tear gas retain volume leadership; drones and acoustic hailing devices are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American riot control equipment industry traces its modern scale to federal law enforcement procurement expansions following civil unrest events of the 1960s and 1970s, when agencies first standardized less-lethal force protocols and established dedicated crowd-control budgets.
United States
California and Texas municipal police departments maintain the largest dedicated crowd-control allocations in North America, driving concentrated demand for integrated command platforms. The National Institute of Justice certification standards filter vendor eligibility for federal procurement contracts. Los Angeles and Houston tactical units deploy drone-based situational awareness systems for pre-event site assessment and live crowd-density monitoring.
Canada
Ontario and Quebec provincial police services anchor federal and municipal procurement volumes for protective gear and dispersal agents. Health Canada and PMRA regulate chemical irritant registrations under parallel frameworks to EPA FIFRA, extending approval timelines for new OC formulations. Toronto and Montreal departments prioritize NIJ-compliant ballistic-rated equipment for cross-border operational compatibility with U.S. agencies.
Mexico
Federal police and military units under the Secretariat of National Defense procure crowd-control equipment for domestic security and border-adjacent operations. The country's national public security regulator imposes equipment standards that increasingly reference NIJ protocols for interoperability. Mexico City concentrates procurement decision-making for federal law enforcement technology acquisitions.
North America Riot Control Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and integrated platform capabilities. The vendor base stratifies into three tiers: full-spectrum platform providers with captive distribution networks, specialized manufacturers of point-product categories, and regional fabricators serving state-level procurement statutes. Dominant competitive moves include backward integration into OC oleoresin supply chains and strategic bundling of body-worn camera ecosystems with crowd-control platforms.
Among U.S.-based integrated platform providers, Axon Enterprise, Inc. and The Safariland Group exemplify archetypes that leverage established law enforcement relationships to cross-sell multi-product portfolios. Combined Systems, Inc. occupies a position representing manufacturing-scale specialists focused on aerosol irritant and kinetic impact munitions. These three anchors demonstrate how certification compliance and distribution control separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Axon Enterprise, Inc. |
| The Safariland Group |
| Combined Systems, Inc. |
| Byrna Technologies Inc. |
| NonLethal Technologies, Inc. |
| PepperBall Technologies |
| Blackhawk |
| Defense Technology |
| Central Lake Armor Express, Inc. |
| Others |
Value Network & Pricing Analysis
Aramid fiber and ceramic plate inputs for NIJ Level IIIA-rated protective gear flow from aerospace and defense competing demand into three-tier pricing structures that separate certified federal contractors from municipal procurement tiers. OC oleoresin capsicum extract originating in concentrated agricultural regions of India and China feeds aerosol irritant production, with EPA FIFRA registration status determining margin capture across standard and premium formulation grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NIJ-certified federal contractors from municipal point-product vendors and regional fabricators serving state-level procurement statutes. Price differentiation hinges on certification depth and integrated platform bundling, with body-worn camera ecosystem cross-selling commanding premium positioning. Cost compression in standard-grade protective gear is intensifying because aramid fiber inputs face aerospace competing demand. Municipal police departments in California and Texas exhibit highest price sensitivity due to consolidated vendor relationships, while federal agencies prioritize compliance trails over unit economics.
Supply Chain Analysis
OC oleoresin supply rests on agricultural concentration in India and China, with capsicum extract sourcing exposing producers to input volatility and trade friction. Raw material dependencies span aramid fiber for ballistic composites, ceramic plates for Level IIIA ratings, and specialty chemical formulations for aerosol irritants. Single-source vulnerability concentrates in Indian capsicum farming regions subject to monsoon disruption and export policy shifts. Distribution runs through captive federal procurement channels, Safariland's law enforcement agency relationships, and municipal consolidated vendor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as municipal procurement shifts toward integrated command platforms with multi-year maintenance contracts rather than point-product purchasing.
For Market Incumbents: Anchor federal eligibility through accelerated NIJ certification timelines for less-lethal technologies while backward integration into OC oleoresin supply chains defends against Indian and Chinese agricultural volatility. Threat substitution from drone-based situational awareness systems demands R&D investment in aerial-ground command platform integration. For New Entrants and Emerging Players: Launch via FAA operational waiver partnerships for unmanned aerial systems in Texas event security verticals, where seasonal demand cycles and higher-margin recurring revenue create white space outside consolidated municipal procurement. Texas stadium protection services represent the most penetrable segment given fragmented vendor relationships and technology refresh cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-product platform capabilities outrun specialized point-product manufacturers unable to meet California and Texas single-source contract requirements. Long-term viability favors vendors with captive distribution networks and cross-selling infrastructure. The signal to watch is Congressional appropriations velocity for homeland security equipment grants.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Certification Acceleration | Federal procurement eligibility under updated use-of-force guidelines expands qualified vendor pools. |
| Backward Integration into OC Supply | Captive capsicum sourcing from Indian agricultural regions reduces input volatility exposure. |
| Drone Platform Integration | FAA waiver compliance for aerial systems compresses surveillance-response function separation. |
| Body-Worn Camera Cross-Selling | Existing law enforcement technology contracts bundle crowd-control platforms at premium margins. |
| Texas Event Security Vertical Expansion | Seasonal stadium and convention demand delivers recurring revenue above municipal procurement yields. |
Research Methodology
Direct dialogue with municipal police procurement officers, federal law enforcement technology directors, EPA regulatory affairs specialists, and NIJ certification testing engineers combined with secondary validation from SEC 10-K filings, federal procurement databases, and state budget appropriations records. Bottom-up vendor shipment triangulation against top-down agency expenditure analysis anchored the market sizing framework.
Bottom-up unit economics modeled across product type, application, end user, and technology segmentation dimensions over the projection horizon. CAGRs derived from agency budget trajectory analysis, certification pipeline velocity, and substitution elasticity between protective gear and standoff-distance technologies. Forecast inputs incorporated Congressional homeland security appropriations cycles and municipal liability standard evolution.
Several conditions sit outside the modeled scope, including unscheduled civil unrest events, abrupt EPA FIFRA registration moratoria, and FAA operational waiver policy reversals. Forecasts reflect assumptions about certification timeline stability and agricultural trade continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market