
 E-Beam Wafer Inspection System Market | 2026-2036
E-Beam Wafer Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
E-Beam Wafer Inspection System Market Intelligence
Memory chip makers is redrawing procurement priorities for e-beam wafer inspection systems as logic foundries expand advanced node capacity. KLA Corporation dominates reticle and wafer inspection through sustained R&D intensity in multi-beam architectures. Applied Materials leverages its process equipment ecosystem to bundle inspection tools with deposition and etch systems. Hitachi High-Tech Corporation anchors the Japanese supply base with specialized electron optics expertise.
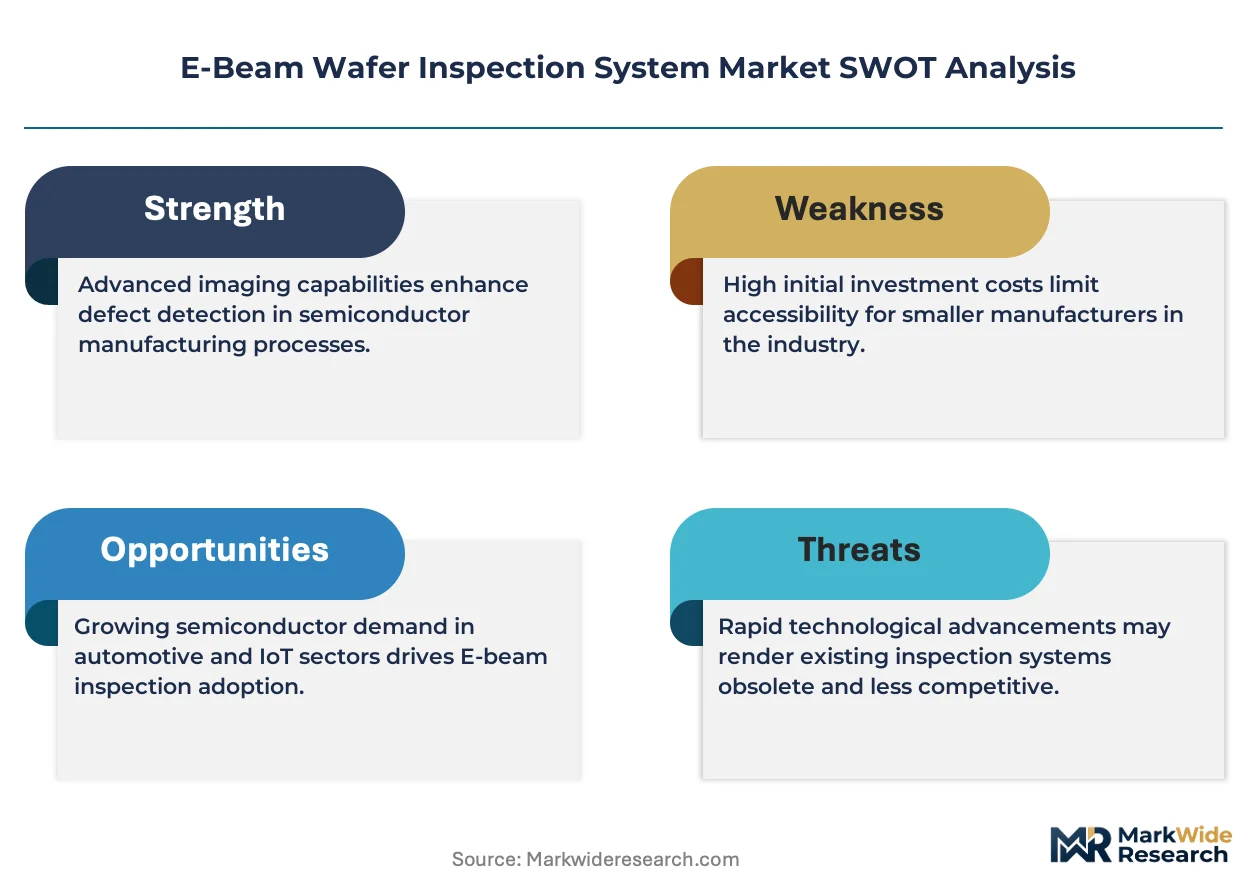
An e-beam wafer inspection system employs focused electron beams to detect sub-10 nanometer defects on semiconductor wafers, operating at accelerating voltages between 1 keV and 30 keV with pixel resolutions below 3 nanometers. The technology serves as the final arbiter of yield-critical pattern fidelity at nodes where optical systems lose resolving power. Electron beam technology leads the installed base but multi-beam architectures represent the fastest-growing product category as throughput bottlenecks diminish. Foundries command the largest end-user spending pool while research institutions concentrate demand for novel materials characterization applications.
Japan's METI coordinates domestic semiconductor equipment standards through JIS frameworks that govern electron beam tool safety and electromagnetic compatibility. The US FDA and EPA jointly oversee hazardous substance disclosures in fabrication equipment under overlapping jurisdiction, while Taiwan's national science council enforces local content requirements for tools deployed in subsidized fabs. Stakeholders must monitor how export control expansions affect component sourcing for electron column assemblies and detector arrays.
Market Dynamics
Multi-beam electron column architectures are compressing inspection throughput bottlenecks at sub-7 nanometer nodes, forcing foundries to retire single-beam platforms faster than depreciation schedules originally projected. This technology transition concentrates procurement decisions among three equipment suppliers capable of delivering production-qualified multi-beam systems.
Growth Catalysts
- Advanced node foundry expansion:Logic manufacturers at 3nm and 2nm nodes require e-beam inspection for critical dimension verification where optical systems fail. Taiwan's Hsinchu Science Park cluster drives the fastest tool installation cycles.
- EU REACH substance restrictions:Compliance mandates for hazardous material disclosure in fabrication equipment accelerate replacement of legacy systems with certified platforms. Equipment vendors must document full material compositions for electron column assemblies.
- Multi-beam throughput gains:Parallel electron beam arrays reduce die inspection time by an order of magnitude compared to serial scanning. Foundries achieve higher sampling rates without sacrificing resolution.
Market Restraints
- Electron source supply concentration:Thermal field emission cathodes and cold emission tips rely on a narrow supplier base concentrated in Japan and Germany. Disruption to this upstream tier halts final assembly lines.
- Technical resolution limits:Signal-to-noise degradation at sub-3 nanometer pixel sizes demands longer dwell times, partially offsetting multi-beam throughput advantages. Physics constraints impose hard boundaries on simultaneous speed and precision.
- Cyclical capital intensity:Semiconductor fabrication equipment spending compresses during memory price downturns, elongating replacement cycles for inspection tools. Memory chip makers defer upgrades when wafer starts decline.
Strategic Opportunities
- Research institution characterization demand:Universities and national laboratories seek e-beam platforms for novel materials analysis beyond semiconductor applications. Gallium nitride and silicon carbide substrates require defect inspection protocols adapted from silicon workflows.
- Japan METI equipment standardization:JIS frameworks for electron beam tool safety create compliance pathways that favor domestic suppliers. Foreign vendors must certify electromagnetic compatibility through designated Japanese testing bodies.
- Aftermarket service unbundling:Independent service providers now offer electron column refurbishment and detector recalibration outside OEM channels. Foundries reduce total cost of ownership through third-party maintenance contracts.
Industry Challenges
- Multi-physics simulation expertise gap:Electron optics design requires simultaneous mastery of electrostatics, magnetostatics, and thermal management. The talent pool capable of optimizing beam crossover points and aberration coefficients remains shallow.
- Legacy tool integration complexity:New multi-beam platforms must communicate with existing manufacturing execution systems and defect management databases. Custom middleware development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Beam Wafer Inspection System Market |
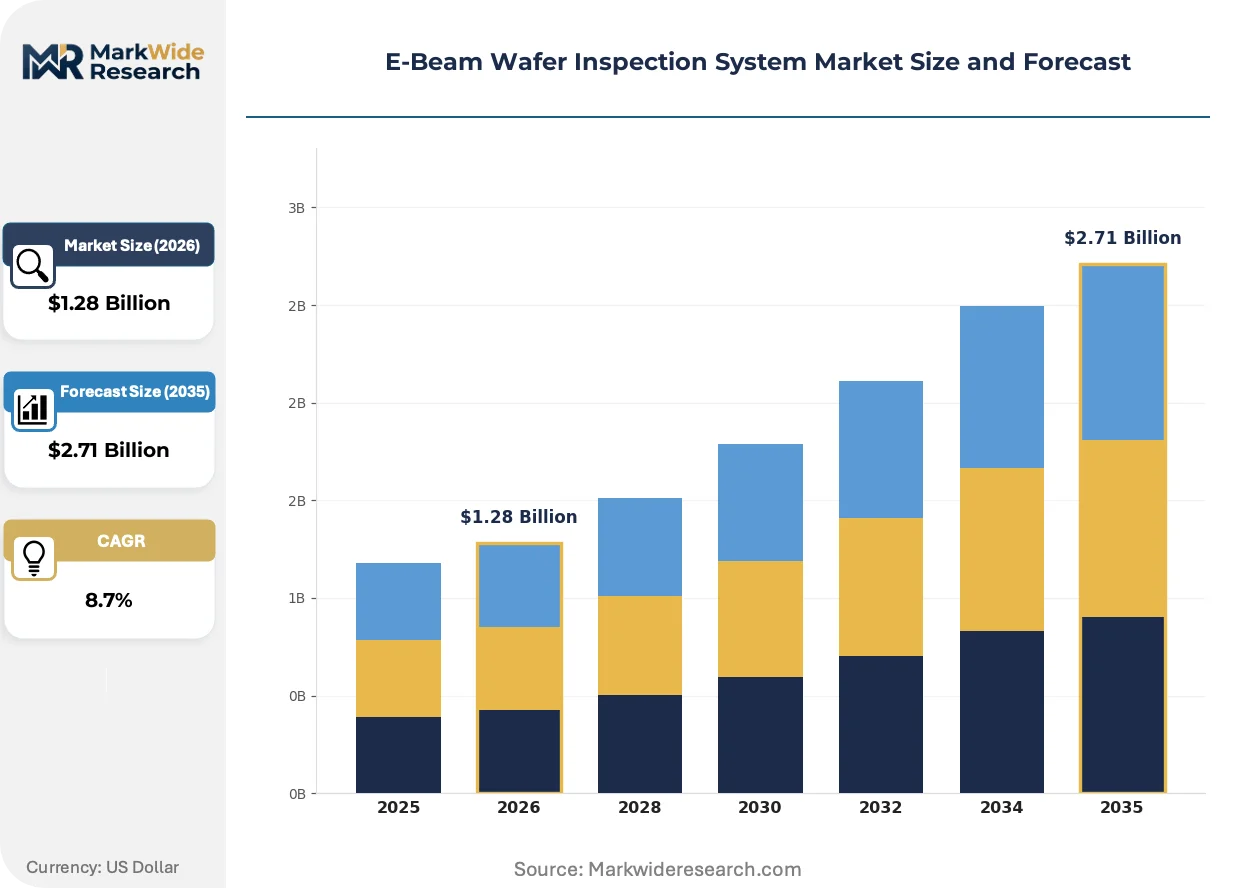
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.71 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
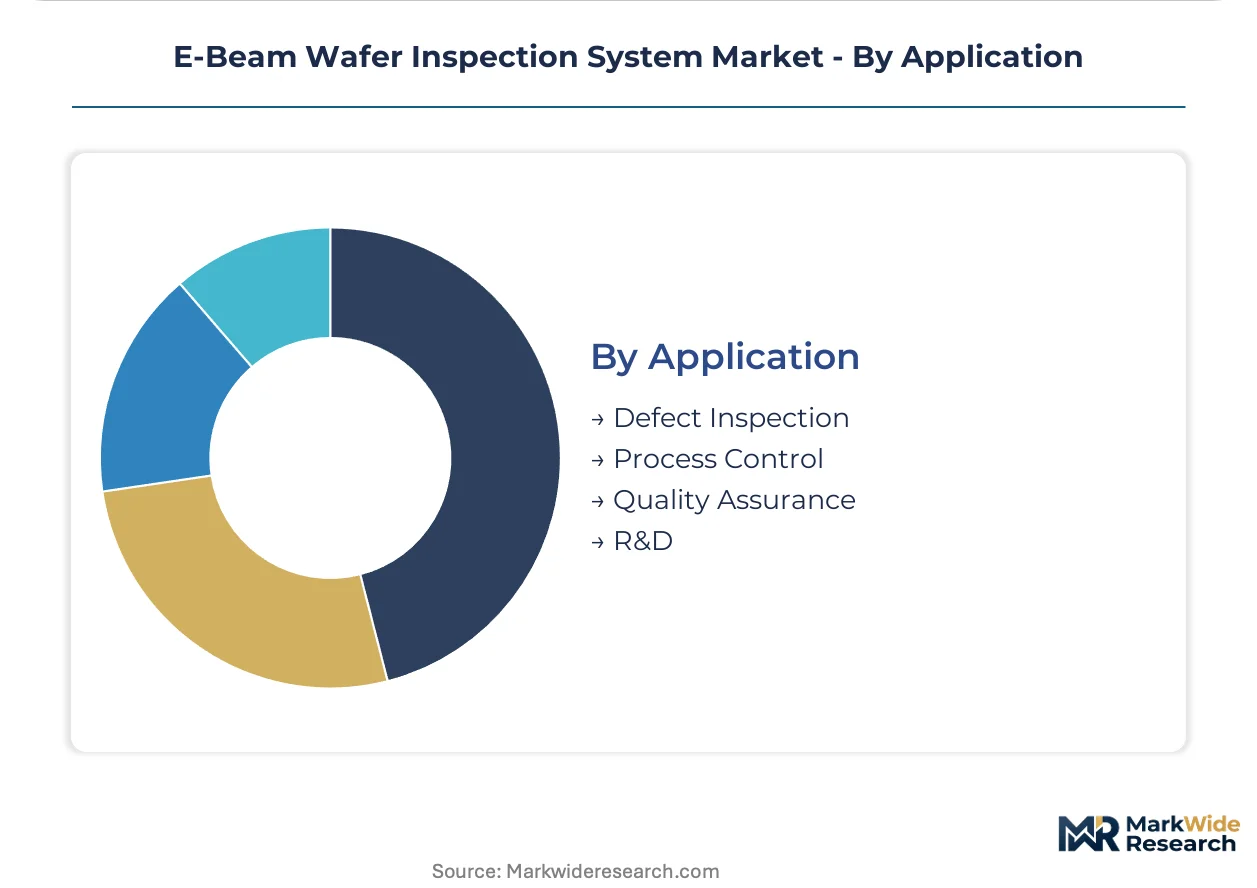
| Segmentation | Technology: Electron Beam, X-ray, Optical, Laser Product Type: Standalone Systems, Integrated Systems, Automated Systems, Manual Systems End User: Semiconductor Manufacturers, Research Institutions, Electronics Companies, Foundries Application: Defect Inspection, Process Control, Quality Assurance, R&D |
| Companies Covered | Hitachi High-Tech Corporation, Toray Engineering, KLA Corporation, Dongfang Jingyuan Electron, Wuhan Jingce Electronic Group, Applied Materials, Onto Innovation, JEOL Ltd., ASML Holding N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Beam Wafer Inspection System Market Strategic Shifts & Innovations
Electron beam inspection technology is fragmenting into specialized architectures optimized for specific defect classes rather than general-purpose platforms. Equipment suppliers now tune column designs for voltage contrast, physical defect, or pattern fidelity applications rather than unified solutions.
Machine learning defect classification is decomposing the traditional workflow where human operators reviewed electron micrographs for anomaly flagging. Advanced foundries deploy neural networks trained on historical defect libraries to prioritize wafer disposition decisions. This automation compresses the feedback loop between inspection and process adjustment, reducing yield excursion duration from hours to minutes.
EU REACH substance restrictions are tightening disclosure requirements for persistent organic pollutants in vacuum system components. Equipment manufacturers must reformulate greases, seals, and coatings used in electron column assemblies to maintain market access. Japanese suppliers with pre-certified material libraries capture preferential positioning in European foundry procurement evaluations.
Consolidated procurement among the three leading-edge logic manufacturers concentrates negotiation leverage and compresses pricing premiums for inspection tools. Foundry technical teams now specify performance benchmarks rather than accepting vendor-defined metrics. This buyer-driven standardization forces equipment suppliers to disclose proprietary beam current stability data previously treated as competitive intelligence.
E-Beam Wafer Inspection System Market Segmentation
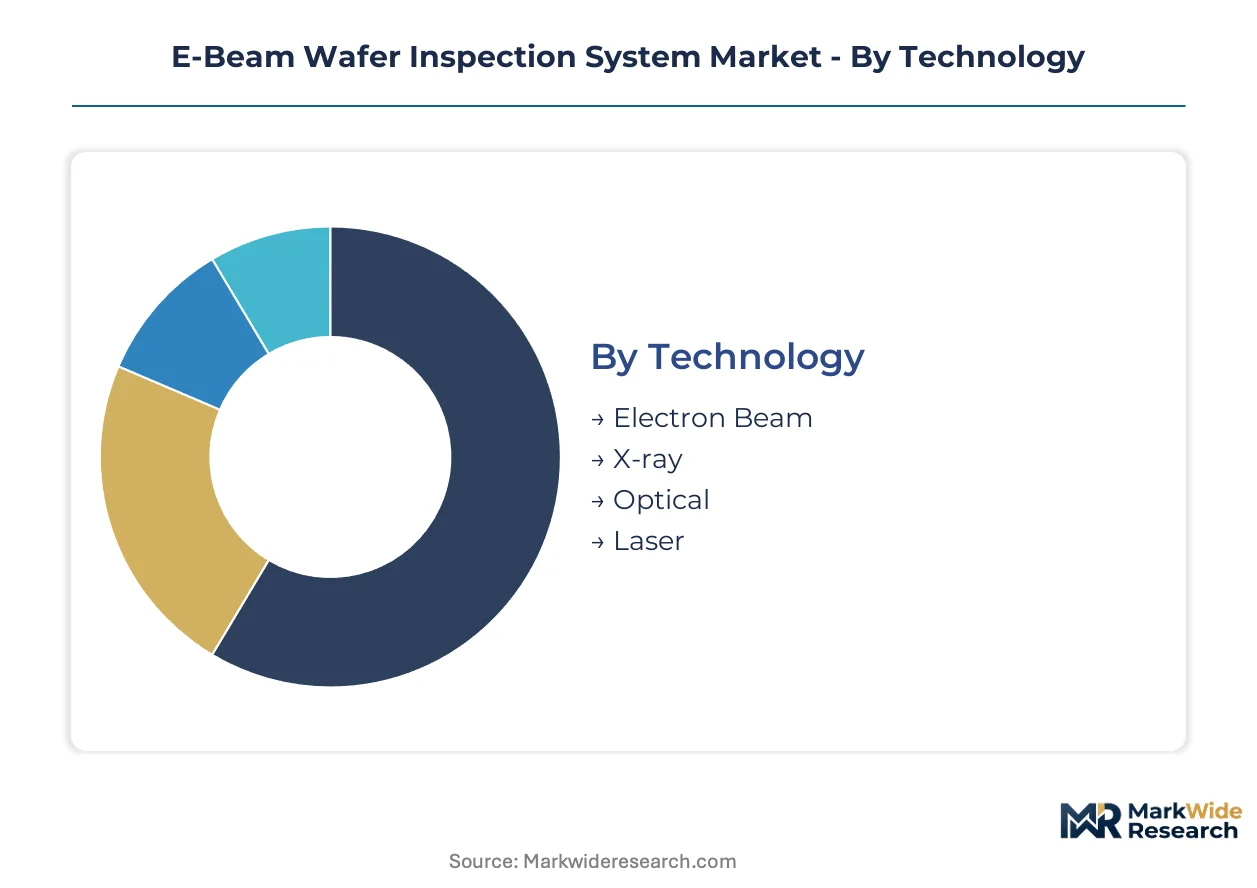
E-beam wafer inspection systems fragment across multiple technical and commercial dimensions. Equipment suppliers configure platforms differently for foundry volume production versus research laboratory flexibility. Procurement patterns diverge sharply between memory manufacturers chasing bit density and logic foundries prioritizing pattern fidelity.
Technology:
Domestic production concentrates electron beam architectures in Japan and Germany, while X-ray and optical platforms flow through broader international supply chains. Export licensing shapes availability for advanced electron column assemblies.
- Electron Beam:Thermal field emission and cold emission sources generate focused beams at 1-30 keV with sub-3 nanometer resolution. Taiwan's Hsinchu Science Park cluster drives the densest installation base as leading-edge foundries retire single-beam platforms faster than depreciation schedules originally projected. Multi-beam architectures now compress throughput bottlenecks that historically limited fab adoption.
- X-ray:Synchrotron and laboratory-based systems penetrate buried layers for three-dimensional defect localization. Research institutions in the United States and Germany concentrate procurement for novel materials characterization beyond silicon workflows. Throughput limitations restrict foundry deployment despite superior subsurface visibility.
- Optical:Broadband and laser-based inspection retains relevance for macro defect detection at mature nodes. Equipment vendors bundle optical pre-screening with e-beam review to reduce die-level inspection overhead.
- Laser:Confocal and interferometric methods map surface topography for process control feedback. Japanese suppliers integrate laser modules as auxiliary channels on hybrid inspection platforms.
Electron Beam holds the largest share; momentum sits with Multi-beam architectures expanding most quickly.
Product Type:
Cost tiering separates capital-intensive standalone platforms from integrated tools bundled with deposition or etch systems. Automated configurations command pricing premiums over manual alternatives.
- Standalone Systems:Self-contained electron column, vacuum chamber, and detector array requiring dedicated fab floor space. Foundries in Taiwan and South Korea dominate procurement for dedicated defect review stations. EU REACH compliance documentation for electron column assemblies extends sales cycles for European deployments.
- Integrated Systems:Modules designed for seamless coupling with process equipment from Applied Materials or Tokyo Electron. Memory manufacturers favor this architecture to compress wafer transport overhead between inspection and subsequent processing steps.
- Automated Systems:Robotic wafer handling and recipe-driven operation minimize operator intervention. Japanese METI safety certifications through JIS frameworks govern electromagnetic compatibility for domestic installations.
- Manual Systems:Operator-controlled stage positioning and beam alignment for research flexibility. Universities and national laboratories in Germany and the United States concentrate this lower-volume segment.
Standalone Systems dominate capital expenditure; Integrated Systems are gaining share fastest through process equipment bundling.
End User:
Volume concentration among three leading-edge logic manufacturers compresses pricing leverage, while research institutions accept longer lead times for specialized configurations.
- Semiconductor Manufacturers:Integrated device operators running memory and logic fabrication lines. South Korean and Taiwanese producers drive the largest equipment procurement pools for yield-critical pattern verification.
- Research Institutions:Universities and national laboratories characterizing gallium nitride, silicon carbide, and two-dimensional materials. German Fraunhofer institutes and United States Department of Energy facilities concentrate demand for novel substrate inspection protocols.
- Electronics Companies:IDMs and system houses verifying incoming wafer quality for captive packaging operations. Japanese consumer electronics producers maintain smaller installed bases for internal quality gates.
- Foundries:Pure-play contract manufacturers at 3nm and 2nm nodes requiring e-beam inspection where optical systems fail. Taiwan Semiconductor Manufacturing Company and Samsung Foundry dictate performance benchmarks rather than accepting vendor-defined metrics.
Foundries command the largest spending pool; Research Institutions show the steepest expansion trajectory for materials beyond silicon.
Application:
Process control applications demand highest sampling rates, while R&D tolerates extended inspection times for comprehensive defect libraries.
- Defect Inspection:Systematic detection of particles, pattern deviations, and electrical anomalies. Taiwan's Hsinchu Science Park cluster operates the densest concentration of multi-beam platforms for die-level review.
- Process Control:Real-time feedback to lithography and etch modules for excursion containment. Foundries deploy machine learning classification to compress feedback loops from hours to minutes.
- Quality Assurance:Final verification before wafer shipment to downstream packaging. Japanese suppliers pre-certify material libraries to satisfy EU REACH disclosure requirements for European-bound equipment.
- R&D:Exploratory characterization of new process chemistries and device architectures. United States national laboratories and German Max Planck institutes drive specialized electron optics development.
Defect Inspection captures the largest installed base; Process Control is climbing the fastest as automation reduces operator review overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Tainan high-speed rail corridor underwrites Taiwan's dominance in semiconductor infrastructure, shuttling personnel and precision components between Hsinchu Science Park and southern expansion zones. This transport backbone connects northern R&D clusters with emerging 2nm fabrication campuses.
Taiwan
TSMC and United Microelectronics Corporation drive multi-beam platform procurement for 3nm and 2nm node qualification. Taiwan's National Science and Technology Council enforces local content thresholds for subsidized fab equipment. Hsinchu Science Park hosts the densest concentration of electron beam inspection installations globally, with tool density accelerating as single-beam platforms retire ahead of schedule.
South Korea
Samsung Foundry and SK Hynix expand advanced logic and memory capacity requiring sub-5nm defect verification. South Korea's Ministry of Trade, Industry and Energy coordinates domestic equipment certification through KATS standards. The Pyeongtaek semiconductor cluster concentrates new multi-beam installation cycles, with foundry technical teams dictating vendor performance benchmarks.
United States
Intel's domestic foundry buildout and Department of Energy national laboratories sustain demand for novel materials characterization. The US FDA and EPA jointly oversee hazardous substance disclosures in fabrication equipment under overlapping jurisdiction. Arizona's Ocotillo campus and New York's Albany NanoTech Complex anchor the largest tool installation pipelines outside Asia.
Japan
Domestic memory manufacturers and electron optics specialists maintain captive demand for specialized inspection protocols. Japan's METI coordinates semiconductor equipment standards through JIS frameworks governing electron beam tool safety and electromagnetic compatibility. The Kyushu semiconductor cluster and Tokyo metropolitan manufacturing belt concentrate supplier R&D and final assembly operations.
Germany
Fraunhofer institutes and Max Planck facilities drive research-oriented procurement for gallium nitride and silicon carbide substrate inspection. EU REACH restrictions on hazardous substances tighten equipment material compliance requirements for persistent organic pollutants. Dresden's Silicon Saxony cluster anchors European demand, with Bosch and GlobalFoundries expanding leading-edge capacity.
E-Beam Wafer Inspection System Market Key Industry Players
Listed leaders compete with private specialists across electron optics architectures, creating a tiered structure where scale advantages concentrate in publicly traded equipment conglomerates while technical depth resides in focused private entities. The competitive landscape segments into three strategic archetypes: integrated process equipment bundlers, standalone inspection platform specialists, and electron column component suppliers. Dominant competitive moves include strategic partnerships between foundries and equipment vendors for co-development of node-specific inspection protocols, plus vertical integration into electron source manufacturing to secure supply chain resilience.
Within the standalone inspection tier, KLA Corporation and Applied Materials exemplify divergent strategic positioning, with the former representing pure-play metrology dominance and the latter illustrating process equipment ecosystem bundling. Hitachi High-Tech Corporation anchors Japanese supply base capabilities, occupying a position that leverages domestic electron optics heritage. Among emerging Asian challengers, Dongfang Jingyuan Electron and Wuhan Jingce Electronic Group represent state-backed vertical integration strategies targeting captive domestic foundry demand.
| Leading Market Players |
|---|
| Hitachi High-Tech Corporation |
| Toray Engineering |
| KLA Corporation |
| Dongfang Jingyuan Electron |
| Wuhan Jingce Electronic Group |
| Applied Materials |
| Onto Innovation |
| JEOL Ltd. |
| ASML Holding N.V. |
| Others |
Cost & Logistics Intelligence
EU REACH substance disclosure mandates gate both supplier qualification and price differentiation simultaneously, forcing equipment vendors to document full material compositions for electron column assemblies before European foundries will evaluate procurement bids. Foundries in Taiwan's Hsinchu Science Park cluster exploit this compliance burden to extract pricing concessions from vendors lacking pre-certified material libraries.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating multi-beam platforms from refurbished single-beam systems and manual research configurations. Price differentiation rests on certification grade under JIS frameworks and after-sales service bundling rather than base hardware specifications. Pricing pressure stems from consolidated procurement among three leading-edge logic manufacturers compressing vendor margins. Memory chip makers exhibit highest price sensitivity due to cyclical capital intensity, while research institutions accept premium positioning for specialized electron optics.
Supply Chain Analysis
Thermal field emission cathode manufacturing in Japan and Germany underwrites the critical upstream tier for electron source supply, with cold emission tip fabrication concentrated in Osaka and Munich metropolitan clusters. Final assembly draws from vacuum system components, detector arrays, and precision motion stages sourced across Taiwan, South Korea, and the United States. Single-source vulnerability in cathode supply creates acute disruption risk for multi-beam platform production lines. Distribution runs through direct OEM channels for foundry volume procurement and specialized distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three leading-edge logic manufacturers whose consolidated procurement compresses vendor pricing leverage and forces disclosure of proprietary performance data previously shielded as competitive intelligence.
For Market Incumbents: Consolidate backward integration into electron source manufacturing to secure cathode supply resilience against Japanese and German supplier concentration. Deepen JIS certification investment to defend positioning in European procurement evaluations where EU REACH compliance gates market access. Multi-physics simulation talent scarcity threatens column design leadership; acquire specialized electron optics engineering teams before competitors lock capacity. For New Entrants and Emerging Players: Differentiate on novel materials characterization protocols for gallium nitride and silicon carbide substrates where research institutions tolerate longer lead times and premium positioning. Target German Fraunhofer institutes and United States Department of Energy facilities as the most penetrable segment, bypassing foundry procurement consolidation. Pursue co-development partnerships with national laboratories to establish credibility before attempting commercial fab penetration. For Investors and Strategic Acquirers: EU REACH expansion reshapes the acquisition landscape toward vendors with pre-certified material libraries and electromagnetic compatibility documentation through designated Japanese testing bodies. Long-term viability favors electron column component specialists with captive cathode supply relationships rather than pure-play system integrators. Monitor Japan METI standardization announcements as the critical signal for regulatory-driven procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Beam Platform Launch | TSMC and Samsung Foundry procurement specifications now mandate parallel electron beam arrays for sub-3nm qualification. |
| Backward Integration into Cathode Supply | Captive thermal field emission source production insulates final assembly from Japanese supplier concentration risk. |
| JIS Certification Pathway | Electromagnetic compatibility approval through METI-designated bodies unlocks preferential positioning in domestic Japanese foundry procurement. |
| Machine Learning Defect Classification Partnership | Neural network training collaborations with leading-edge foundries compress feedback loops and deepen customer switching costs. |
| Aftermarket Service Unbundling | Independent electron column refurbishment contracts reduce total cost of ownership for memory manufacturers during cyclical downturns. |
Research Approach
Operator-level perspectives from fab engineering directors, electron optics specialists, procurement managers at leading-edge foundries, and aftermarket service technicians anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through SEMI equipment market data, SEC filings from listed equipment vendors, Japan METI industrial statistics, and EU REACH substance disclosure registries. Bottom-up installation base modeling and top-down capital expenditure triangulation cross-checked volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against semiconductor capital expenditure cyclicality, export control expansion scenarios, and multi-beam throughput improvement trajectories. Segmentation dimensions modeled include technology architecture, product configuration, end-user category, and application workflow across the projection horizon. CAGRs derived from equipment procurement pipeline analysis and foundry capacity expansion announcements, with electron source supply constraints and regulatory compliance timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU REACH substance restrictions and Japan METI JIS standardization regimes; material policy shifts would require re-modeling supply qualification pathways and procurement preference structures. Practitioners should keep alternative scenarios live as export control expansions affecting electron column assemblies and detector arrays evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Fogging Tester Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Electrical and Electronic Test Equipment Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market