
 Pyrites Market | 2026-2036
Pyrites Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrites Market Analysis
REACH compliance is shifting the cost-of-entry calculus for European pyrite processors, forcing investment in cleaner roasting technologies and traceable supply chains. Hickman Williams & Company leverages its North American distribution network to serve sulfuric acid manufacturers with consistent industrial-grade supply. Foshan Pyrite Mineral Materials Co. Ltd. dominates downstream integration in China's electronics-grade pyrite segment. Veneta Mineraria S.p.a. anchors Mediterranean supply through specialized reagent-grade production for European chemical manufacturers.
Pyrite, an iron disulfide mineral with the chemical formula FeS₂ and a brass-yellow metallic luster, typically contains 46-47% sulfur by weight and serves as a primary feedstock for sulfuric acid production through roasting and contact processes. Iron pyrite leads global volume due to its abundance and established processing infrastructure for sulfur recovery, while reagent-grade material commands premium positioning in analytical chemistry and semiconductor applications. Chemical manufacturing absorbs the largest share of industrial-grade pyrite, though renewable energy applications in photovoltaic manufacturing represent the fastest-expanding demand channel.
EPA emissions standards in the United States restrict sulfur dioxide releases from pyrite roasting facilities, compelling capital upgrades at legacy plants. ECHA's REACH framework and China's MEE environmental compliance protocols collectively tighten traceability and purity documentation across export supply chains. Stakeholders must monitor evolving battery mineral regulations, as pyrite's sulfur content gains attention in next-generation energy storage chemistries.
Market Dynamics
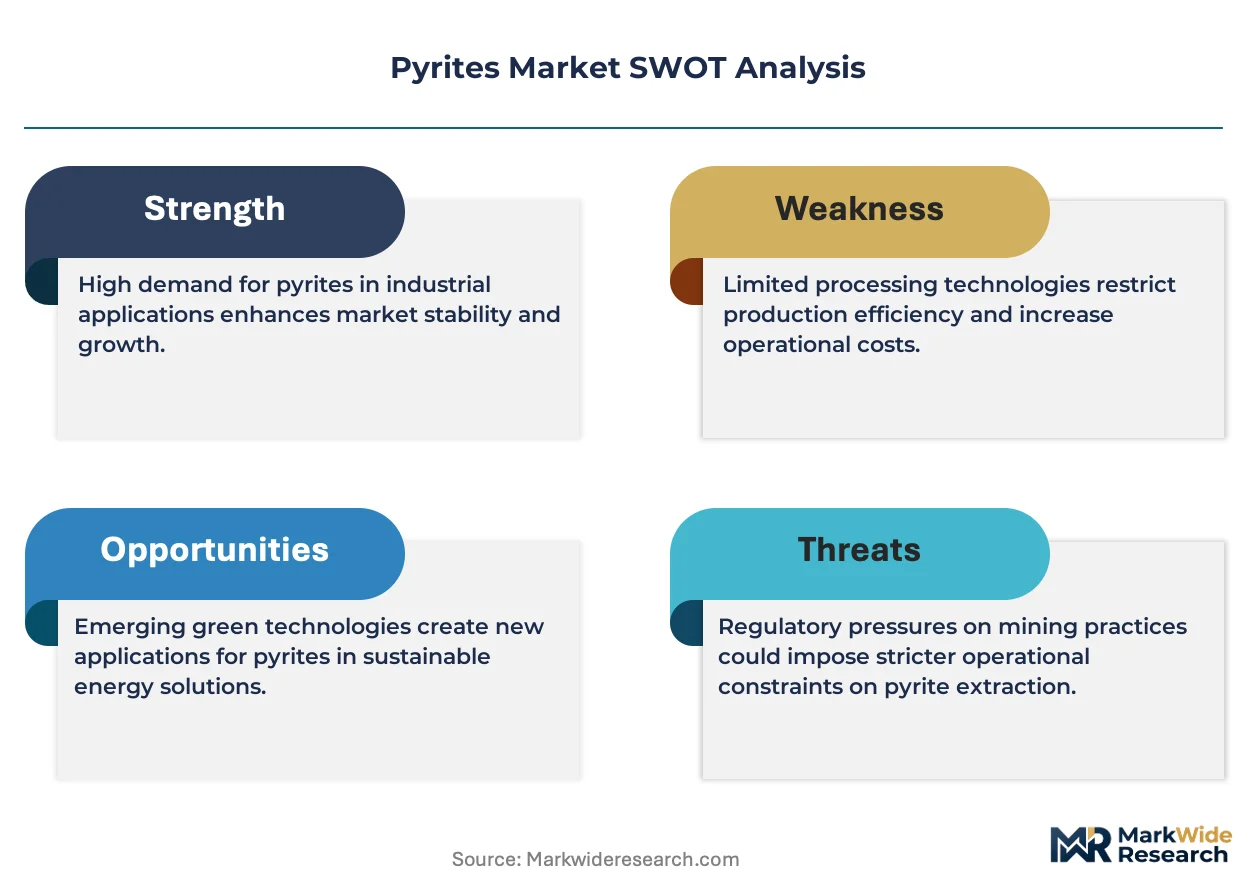
China's GB standards for industrial mineral purity are restructuring processing requirements across sulfuric acid supply chains, forcing capital reallocation toward cleaner roasting infrastructure and traceable sourcing systems.
Growth Catalysts
- Sulfuric acid manufacturing expansion:Chemical producers in East Asian metallurgical hubs are scaling pyrite feedstock procurement to serve fertilizer and industrial chemical synthesis.
- REACH compliance upgrades:ECHA's traceability mandates are accelerating investment in certified reagent-grade production for European analytical chemistry applications.
- Photovoltaic manufacturing demand:Sulfur recovery from pyrite is overtaking conventional feedstocks in polysilicon purification processes for solar cell production.
Market Restraints
- Energy cost volatility:Roasting operations face margin compression from natural gas price fluctuations in European processing facilities.
- Supply concentration risk:Industrial-grade pyrite sourcing clusters in China's steel-producing provinces, creating single-geography dependency for global sulfuric acid manufacturers.
- Substitution pressure:Elemental sulfur and spent acid recovery systems are displacing pyrite in sulfuric acid production where environmental permits restrict SO₂ emissions.
Strategic Opportunities
- Next-generation battery chemistries:Pyrite's sulfur content is attracting R&D investment for lithium-sulfur and sodium-sulfur energy storage systems.
- Electronics-grade purification:Semiconductor manufacturers in Japan and South Korea are qualifying high-purity FeS₂ for specialized deposition processes.
- EPA emissions trading:US sulfur dioxide credit markets are creating financial incentives for pyrite processors that deploy scrubbing technology exceeding baseline standards.
Industry Challenges
- Roasting technician scarcity:Specialized furnace operators with SO₂ capture expertise are in short supply across North American and European facilities.
- Legacy equipment retrofitting:Contact process plants built before 1990 require capital-intensive upgrades to meet MEE environmental compliance protocols for export certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrites Market |
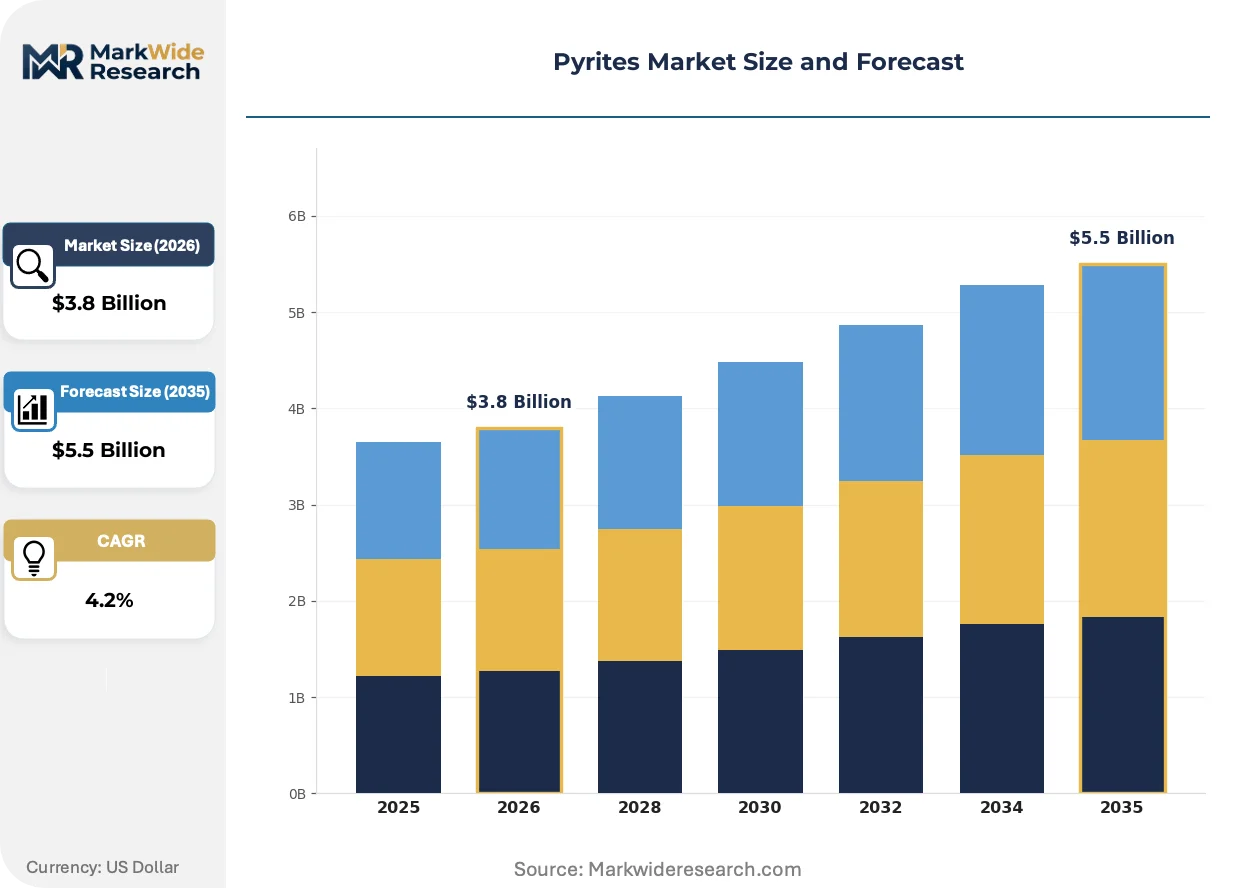
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Pyrite, Cobalt Pyrite, Nickel Pyrite, Zinc Pyrite End Use Industry: Mining, Metallurgy, Chemical Manufacturing, Fertilizer Production Grade: Industrial Grade, Reagent Grade, Agricultural Grade, Food Grade Application: Electronics, Renewable Energy, Paints, Ceramics |
| Companies Covered | Hickman Williams & Company, Washington Mills, Veneta Mineraria S.p.a., Foshan Pyrite Mineral Materials Co. Ltd., Justo Gems S.A.C., Avrupa Minerals Ltd, Pakistan Minerals Company, Jainson Labs, Outotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrites Market Emerging Trajectories
Processing technology and regulatory traceability are converging to reshape competitive positioning in pyrite supply chains, with purity certification and emissions accountability becoming primary differentiators.
Flash roasting technology with integrated heat recovery is overtaking conventional multi-hearth furnace designs in new plant construction. Sulfuric acid producers in China and India are adopting these systems to reduce energy intensity per ton of sulfur recovered. The shift is compressing operating margins for processors running legacy equipment without thermal efficiency upgrades.
REACH Article 33 disclosure requirements are mandating supply chain documentation for sulfur content origin in chemical manufacturing inputs. European compounders now reject pyrite lots lacking certified impurity profiles for arsenic and heavy metals. Reagent-grade suppliers in Italy and Spain are investing in laboratory certification to maintain access to German and French analytical chemistry markets.
Long-term offtake agreements with fixed purity bands are displacing spot market purchasing for industrial-grade material. Sulfuric acid manufacturers in the US and Brazil are locking in three-to-five-year contracts with penalty clauses for sulfur content deviation. The contracting pattern is most pronounced in agricultural chemical supply chains where input cost predictability outweighs price optimization.
Pyrites Market Segmentation
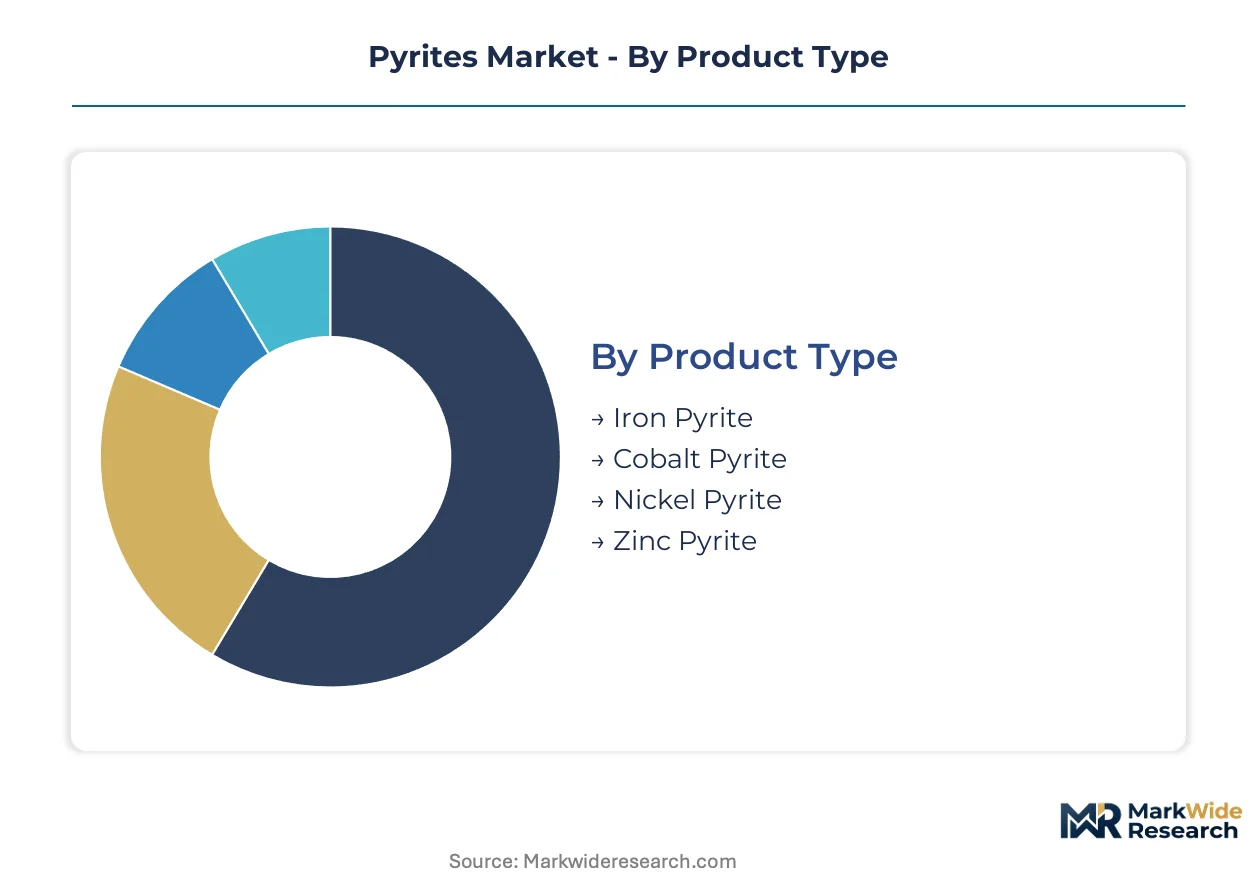
Pyrite buyers select feedstock based on sulfur content precision, impurity tolerance, and downstream process compatibility. Segmentation reveals how sulfuric acid manufacturers, semiconductor fabricators, and agricultural chemical producers prioritize different purity-cost trade-offs.
Product Type:
Mineral composition dictates roasting efficiency and sulfur recovery economics, with iron-rich variants commanding volume due to established processing infrastructure.
- Iron Pyrite:FeS₂ with 46-47% sulfur content serves as the dominant feedstock for contact-process sulfuric acid manufacturing. China's steel-producing provinces in Hebei and Shandong absorb the majority of industrial-grade supply for fertilizer and chemical synthesis operations.
- Cobalt Pyrite:CoAsS-CoFeS₂ mineralization contains recoverable cobalt alongside sulfur, attracting dual-stream processing investments in Canadian and Australian metallurgical facilities. Battery material refiners in Ontario are qualifying this feedstock for cobalt-sulfur co-recovery circuits.
- Nickel Pyrite:(Ni,Fe)S₂ deposits support nickel-cobalt refining with sulfuric acid as a byproduct. Sudbury Basin processors in Canada leverage this mineralogy for integrated battery metal supply chains.
- Zinc Pyrite:ZnS-FeS₂ associations occur in complex sulfide ores; zinc smelters in Tennessee and Tennessee Valley Authority corridors recover sulfur dioxide for acid production during roaster off-gas treatment.
Volume sits with Iron Pyrite; growth tilts toward Cobalt Pyrite.
End Use Industry:
Downstream process intensity and emissions compliance requirements separate high-volume commodity buyers from specialty chemical purchasers.
- Chemical Manufacturing:Sulfuric acid producers for industrial synthesis represent the largest procurement channel. Facilities in Louisiana's Chemical Corridor and Germany's Ludwigshafen cluster require consistent sulfur content within 0.5% tolerance bands for contact-process efficiency.
- Fertilizer Production:Phosphate fertilizer manufacturers consume pyrite-derived acid for wet-process phosphoric acid production. Mosaic Company operations in Florida and Nutrien facilities in Saskatchewan specify low-arsenic feedstock to meet EPA and PMRA contaminant thresholds.
- Mining:Flotation reagent applications and mine-site acid leaching consume industrial-grade material. Chilean copper porphyry operations use pyrite as a sulfur source for heap leach pH control.
- Metallurgy:Base metal smelters recover sulfur from pyritic concentrates during roasting. Glencore's Horne Smelter in Quebec processes complex feeds with pyrite associations for copper and sulfur co-production.
Procurement concentrates in Chemical Manufacturing; Fertilizer Production expands most quickly on phosphate demand.
Grade:
Certification requirements and traceability documentation create tiered pricing structures across purity specifications.
- Industrial Grade:95-98% FeS₂ with controlled arsenic and heavy metal content serves sulfuric acid roasting. ECHA REACH Article 33 disclosure mandates now require certified impurity profiles for European chemical manufacturing acceptance.
- Reagent Grade:99.5%+ purity with ppm-level trace metal specification supports analytical chemistry and semiconductor deposition processes. Japanese and South Korean electronics manufacturers qualify Italian and Spanish suppliers for specialized FeS₂ sputtering targets.
- Agricultural Grade:Moderate purity material with soil amendment certification feeds sulfur-deficient cropland in Brazil's Cerrado and US Midwest corn belts.
- Food Grade:Refined sulfur derivatives from pyrite roasting enter food processing applications under FDA and EFSA additive regulations.
Industrial Grade dominates volume; Reagent Grade commands steepest expansion trajectory on semiconductor qualification.
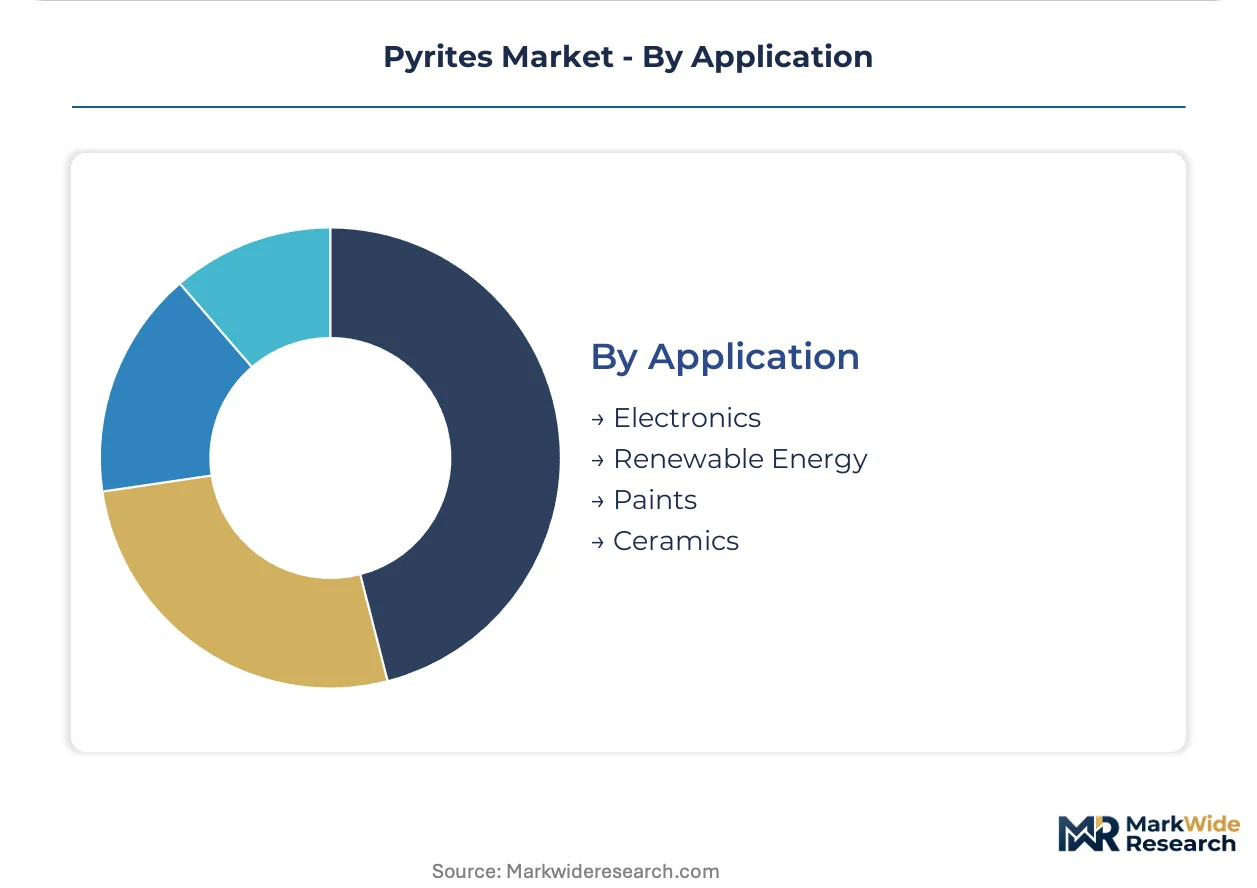
Application:
Technology-specific performance requirements drive grade selection and supplier certification investments.
- Renewable Energy:Polysilicon purification for photovoltaic manufacturing uses sulfur recovery from pyrite in silicon tetrachloride processing. LONGi and Tongwei facilities in China's Yunnan and Sichuan provinces are scaling sulfur feedstock procurement.
- Electronics:High-purity FeS₂ thin films and quantum dot applications require sub-50ppm metallic impurity levels. Samsung and SK Hynix R&D programs in South Korea are evaluating pyrite for next-generation memory materials.
- Paints:Iron oxide pigments derived from pyrite roasting supply architectural coatings. Sherwin-Williams and PPG operations in Ohio and Pennsylvania specify consistent particle size distribution.
- Ceramics:Sulfur-containing glazes and specialty refractories use controlled-purity pyrite for color development and fluxing properties.
Renewable Energy absorbs the largest volume gains; Electronics is gaining share fastest on material science investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hebei Free Trade Zone incentives concentrate sulfuric acid feedstock processing, attracting capital from Japanese and South Korean chemical manufacturers seeking tariff-advantaged pyrite roasting capacity.
China
Sulfuric acid manufacturers in Hebei and Shandong provinces scale pyrite procurement for phosphate fertilizer synthesis. MEE environmental compliance protocols mandate emissions monitoring systems at all roasting facilities. Tangshan metallurgical clusters deploy flash roasting technology with integrated heat recovery to serve LONGi and Tongwei polysilicon operations.
United States
Louisiana Chemical Corridor facilities consume industrial-grade pyrite for contact-process acid serving Mosaic Company fertilizer operations. EPA emissions standards restrict sulfur dioxide releases, compelling scrubbing technology investments at legacy plants. Florida phosphate mining districts specify low-arsenic feedstock to meet PMRA contaminant thresholds for agricultural chemical production.
Germany
Ludwigshafen chemical manufacturers require certified impurity profiles within 0.5% sulfur content tolerance bands. ECHA REACH Article 33 disclosure mandates reject pyrite lots lacking traceable arsenic and heavy metal documentation. Bavarian analytical chemistry compounders source reagent-grade material from Italian and Spanish laboratory-certified suppliers.
Italy
Veneta Mineraria anchors Mediterranean reagent-grade production for European semiconductor and analytical chemistry markets. EU Green Deal carbon border adjustments pressure roasting energy intensity at legacy multi-hearth furnace operations. Sardinian mining districts qualify high-purity FeS₂ for Samsung and SK Hynix thin-film deposition process evaluation.
Canada
Sudbury Basin processors leverage nickel pyrite mineralogy for integrated battery metal and sulfuric acid co-production. Ontario battery material refiners qualify cobalt pyrite feedstock for dual-stream cobalt-sulfur recovery circuits. Quebec's Horne Smelter complex processes complex pyritic concentrates for copper and sulfur co-production under federal emissions trading frameworks.
Pyrites Market Vendor Landscape
Chinese producers anchor the industrial-grade volume tier; European and North American specialists hold premium reagent-grade positioning through certification infrastructure. Market structure fragments across geography and purity specification, with three archetypes dominating: integrated mining-roasting conglomerates, laboratory-certified specialty refiners, and regional distribution intermediaries. Competitive moves center on backward integration into captive mining assets and three-to-five-year offtake contracting with penalty clauses for sulfur deviation.
Within the specialty refiner tier, Veneta Mineraria S.p.a. and Foshan Pyrite Mineral Materials Co. Ltd. exemplify divergent geographic strategies for purity-driven market access. Hickman Williams & Company occupies a position bridging North American distribution scale with sulfuric acid manufacturer procurement specifications. These three entities represent the archetype spectrum: Mediterranean laboratory certification, Chinese downstream integration, and continental logistics consolidation.
| Leading Market Players |
|---|
| Hickman Williams & Company |
| Washington Mills |
| Veneta Mineraria S.p.a. |
| Foshan Pyrite Mineral Materials Co. Ltd. |
| Justo Gems S.A.C. |
| Avrupa Minerals Ltd |
| Pakistan Minerals Company |
| Jainson Labs |
| Outotec |
| Others |
Supply Flow & Price Mechanics
Sulfuric acid manufacturers in Louisiana's Chemical Corridor and Germany's Ludwigshafen cluster anchor procurement volume, locking in contract-based long-term offtake agreements with penalty clauses for sulfur content deviation rather than transacting on spot markets.
Pricing Analysis
Short lead-time premiums reward reagent-grade suppliers maintaining laboratory-certified inventory for European analytical chemistry and South Korean semiconductor qualification programs. Three-tier pricing structure across premium, standard, and economy levels separates reagent-grade certification from industrial-grade volume contracts and agricultural-grade soil amendment material. Cost compression in industrial-grade roasting is intensifying because flash roasting technology with integrated heat recovery reduces energy intensity per ton of sulfur recovered. Agricultural-grade buyers in Brazil's Cerrado exhibit highest price sensitivity, while Japanese electronics manufacturers demonstrate lowest sensitivity given sub-50ppm metallic impurity requirements.
Supply Chain Analysis
Direct-to-roaster channels handle sulfuric acid manufacturer demand in Hebei and Shandong provinces, while laboratory-certified specialists in Italy and Spain serve reagent-grade procurement through distributor intermediaries. Supply concentrates in China's steel-producing provinces, with secondary sourcing from Canadian Sudbury Basin operations and Sardinian mining districts. Raw material dependencies include iron disulfide ore quality, natural gas for roasting energy, and limestone for sulfur dioxide scrubbing systems. Single-source vulnerability stems from Hebei Free Trade Zone concentration for industrial-grade pyrite feedstock. Distribution runs through regional chemical distributors in North America and direct mill relationships in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive mining assets defines competitive positioning, as processors secure ore supply to offset volatility in sulfur content specifications and ECHA REACH traceability mandates.
For Market Incumbents: Deploy flash roasting technology upgrades to defend margin position against energy cost volatility and substitution pressure from elemental sulfur recovery systems. Lock in three-to-five-year offtake contracts with sulfur deviation penalties to secure volume commitments from Mosaic Company and Nutrien fertilizer operations. Prioritize laboratory certification investments for reagent-grade access to German and French analytical chemistry markets. For New Entrants and Emerging Players: Begin with cobalt pyrite dual-stream processing for Ontario battery material refiners, where lithium-sulfur energy storage R&D investment outpaces established supply. Target Sardinian high-purity FeS₂ deposits for Samsung and SK Hynix thin-film deposition qualification programs. Pursue EPA emissions trading credit monetization as a differentiated service layer for US sulfuric acid manufacturers facing scrubbing technology mandates. For Investors and Strategic Acquirers: The window for entry favors laboratory-certified specialty refiners with existing ECHA REACH documentation infrastructure and Italian or Spanish geographic positioning. Long-term viability rests on semiconductor qualification momentum and next-generation battery chemistry sulfur feedstock adoption. Monitor EPA sulfur dioxide credit market liquidity and MEE environmental compliance protocol enforcement intensity as inflection indicators for processing margin expansion or compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Secures ore supply against Hebei concentration risk and GB standards compliance costs. |
| Flash Roasting Technology Deployment | Reduces energy intensity for Tangshan metallurgical clusters serving LONGi polysilicon operations. |
| Laboratory Certification Investment | Unlocks reagent-grade access for Bavarian analytical chemistry compounders under REACH Article 33. |
| Long-term Supply Agreement Structuring | Locks in sulfur content predictability for Louisiana Chemical Corridor contact-process efficiency. |
| Joint Venture with Battery Material Refiners | Positions cobalt pyrite feedstock for Ontario lithium-sulfur co-recovery circuit development. |
Methodological Framework
Multi-period observation of pyrite procurement volumes, roasting capacity utilization, and sulfuric acid manufacturer contract structures anchored the trend analysis, supplemented by interviews with plant managers at contact-process facilities, procurement leads at fertilizer operations, distribution channel partners in North American chemical corridors, and technical R&D directors at reagent-grade refiners. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings by listed chemical manufacturers, and MEE environmental compliance disclosure databases. Bottom-up segment sizing and top-down macroeconomic triangulation converged on volume and value estimates.
Input-output matrices modeled pyrite consumption across grade tier, end-use industry, and regional production hub dimensions over the projection horizon. CAGRs were derived from segment-level demand elasticity analysis and capacity expansion timelines. Industry-specific forecast inputs included polysilicon purification scaling at LONGi and Tongwei facilities, lithium-sulfur battery chemistry R&D investment trajectories, and EPA emissions trading market development.
Underlying measurement precision varies by segment; reagent-grade semiconductor qualification and battery chemistry applications carry tighter precision than industrial-grade sulfuric acid feedstock forecasting. Forecasts reflect assumptions regarding MEE enforcement intensity, REACH documentation harmonization, and flash roasting technology adoption rates. Periodic stress-testing of base assumptions against actual contract structures and emissions credit market liquidity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Global and US Inorganic Salt Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Fluorspar Market