
 Global Gamma Linolenic Acid Market | 2026-2036
Global Gamma Linolenic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gamma Linolenic Acid Market Foresight
Evening primrose oil is hardening its position against borage oil as the preferred botanical source for pharmaceutical-grade GLA, driven by more stable supply chains and broader organic certification availability. DSM-Firmenich leverages its integrated fermentation capabilities to supply consistent fermentation-derived GLA to European pharmaceutical customers. Croda International Plc anchors its competitive stance through backward integration into specialty oilseed crushing and refined lipid processing. BASF SE competes via its global distribution network for synthetic GLA intermediates serving cosmetic formulators.
Gamma linolenic acid is an omega-6 polyunsaturated fatty acid with an 18-carbon chain and three cis double bonds at positions 6, 9, and 12, typically extracted from evening primrose or borage seed oils through cold-pressing and subsequent molecular distillation to achieve 9-10% or higher purity grades for pharmaceutical applications. The compound functions primarily as a prostaglandin E1 precursor, supporting anti-inflammatory, skin-barrier repair, and hormonal balance applications across nutraceutical and dermatological formulations. Vegetable-based GLA occupies the dominant volume position due to established organic cultivation networks and consumer preference for plant-derived ingredients, while fermentation-derived GLA represents the fastest-expanding category as microbial cell factories eliminate agricultural yield volatility and pesticide residue concerns. The dietary supplements application segment leads absolute consumption, though cosmetics is deepening its margin pool through premium positioning of GLA-infused serums targeting atopic dermatitis and aging skin conditions.
FDA dietary supplement cGMP enforcement and EU EFSA Novel Food approvals are elevating analytical testing burdens for imported GLA raw materials, particularly around residual solvent limits and fatty acid profile verification. REACH registration requirements for synthetic GLA intermediates are reshaping supplier qualification protocols for European cosmetic and pharmaceutical manufacturers. Japan's MHLW positive list system for functional food ingredients adds a third compliance layer for brands targeting East Asian markets. Stakeholders must monitor evolving purity specifications across FDA, EFSA, and Japanese frameworks to avoid batch rejection risks and secure long-term supply agreements with qualified extractors.
Market Dynamics
Pharmaceutical procurement contracts are consolidating around fermentation-derived GLA suppliers capable of meeting FDA cGMP and EU EFSA Novel Food dual-certification requirements, compressing supplier qualification timelines and elevating analytical testing burdens for botanical extractors.
Growth Catalysts
- Anti-inflammatory drug pipelines:Pharmaceutical formulators are expanding GLA procurement for prostaglandin E1 precursor applications in rheumatoid arthritis and atopic dermatitis therapeutics, with EU-based contract manufacturers leading volume commitments.
- Fermentation technology maturation:Microbial cell factory platforms are eliminating agricultural yield volatility and pesticide residue concerns, enabling year-round production consistency that cold-pressed evening primrose oil cannot match.
- REACH registration clarity:ECHA guidance on synthetic GLA intermediates has reduced regulatory uncertainty for European cosmetic and pharmaceutical manufacturers, accelerating supplier qualification protocols.
Market Restraints
- Organic evening primrose oil supply concentration:Cultivation networks cluster in China and Argentina, exposing pharmaceutical-grade supply to climate volatility and geopolitical friction in seed oil trade flows.
- Fatty acid profile verification costs:FDA cGMP enforcement and EU EFSA Novel Food approvals mandate gas chromatography-mass spectrometry testing for every imported batch, elevating analytical expenditure for smaller extractors.
- Algal DHA and EPA substitution:Marine-derived omega fatty acids are capturing formulation share in anti-inflammatory nutraceuticals, pressuring GLA positioning in joint health and cardiovascular segments.
Strategic Opportunities
- Japan's functional food positive list:MHLW approvals for GLA-containing health claims remain underpenetrated, creating first-mover advantage for suppliers investing in Japan-specific toxicology dossiers.
- Cosmeceutical serum premiumization:GLA-infused atopic dermatitis treatments command 40-60% formulation premiums in South Korean and German dermocosmetic channels, deepening margin pools beyond commodity oil sales.
- Precision fermentation scale-up:Integration of CRISPR-edited yeast strains with continuous bioreactor processing is collapsing production costs for fermentation-derived GLA, enabling price parity with botanical sources.
Industry Challenges
- Dual-certification timeline compression:Simultaneous FDA cGMP and EU EFSA Novel Food approvals require 18-24 month synchronization, straining smaller suppliers' regulatory affairs capacity and delaying commercial launches.
- Specialized lipid chemist scarcity:Molecular distillation and supercritical CO2 extraction expertise concentrates among retiring technicians in Germany and Switzerland, constraining quality control staffing for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gamma Linolenic Acid Market |
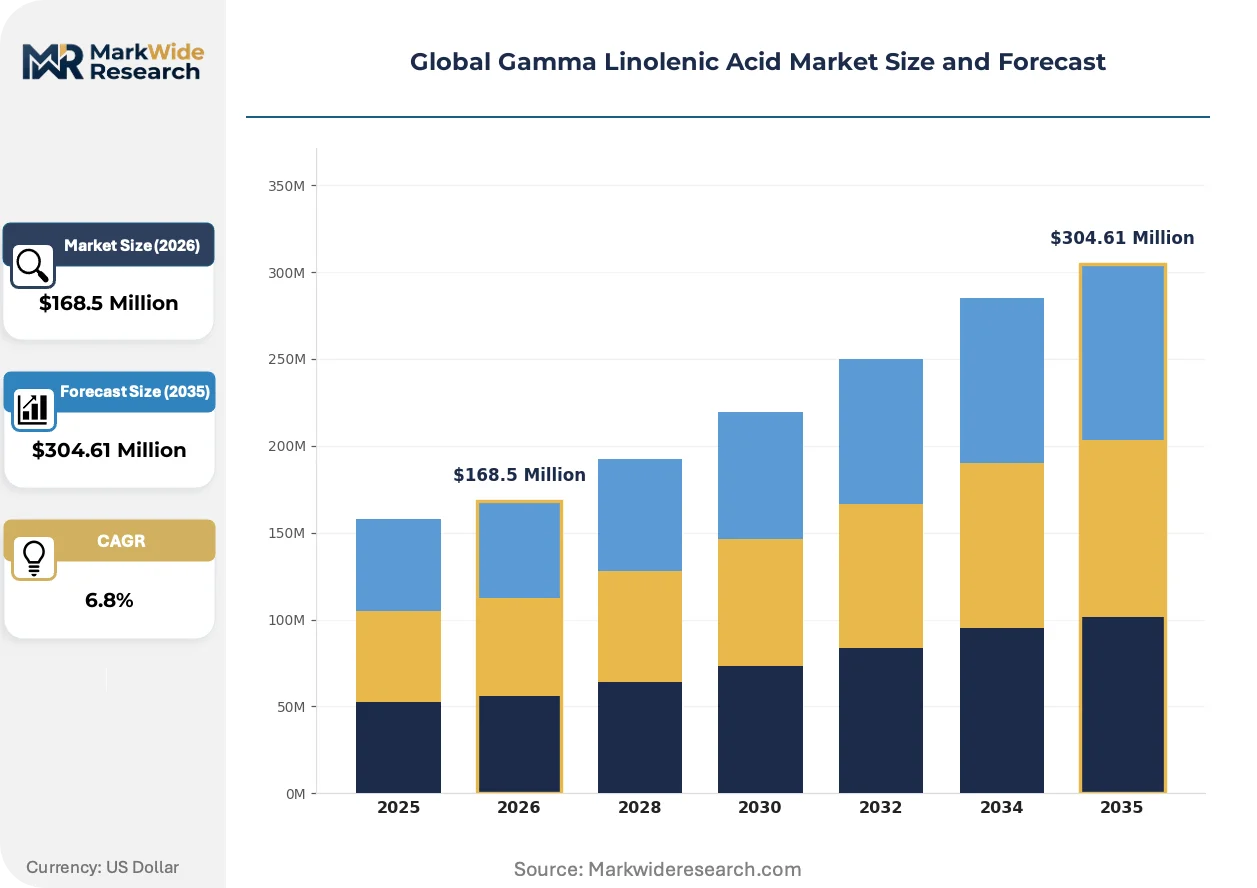
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $304.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable-Based, Marine-Based, Synthetic, Fermentation-Derived Form: Liquid, Capsule, Powder, Softgel, Oil Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Functional Foods, Animal Nutrition End User: Supplement Manufacturers, Personal Care Brands, Pharmaceutical Companies, Food Producers |
| Companies Covered | Croda International Plc, Merck KGaA, DSM-Firmenich, Sanmark Corp, Thermo Fisher Scientific, BASF SE, Bioriginal Food & Science Corp., Connoils LLC, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gamma Linolenic Acid Market Shifts & Advancements
Fermentation technology is collapsing traditional supply hierarchies while regulatory fragmentation across FDA, EFSA, and Japanese frameworks is elevating compliance architecture as a competitive differentiator rather than a cost center.
Precision fermentation using engineered Mortierella alpina and Crypthecodinium cohnii strains is decentralizing GLA production from agricultural geographies to controlled bioreactor facilities. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting microbial-derived GLA at accelerating rates, bypassing organic certification dependencies and pesticide residue testing protocols that burden evening primrose oil supply chains.
EU EFSA Novel Food approval requirements for synthetic and fermentation-derived GLA are tightening fatty acid profile documentation and residual solvent limits. European cosmetic formulators must now submit comprehensive toxicology dossiers for GLA intermediates, with the regulation most acutely affecting mid-sized suppliers lacking in-house regulatory affairs teams who are outsourcing compliance to specialized consultancies.
Long-term supply agreements are replacing spot purchasing for pharmaceutical-grade GLA as procurement teams prioritize batch-to-batch consistency over price arbitrage. German and Japanese nutraceutical manufacturers are locking in three-to-five year contracts with fermentation specialists, a pattern most visible in atopic dermatitis therapeutic formulations where FDA cGMP traceability is non-negotiable.
Global Gamma Linolenic Acid Market Segmentation
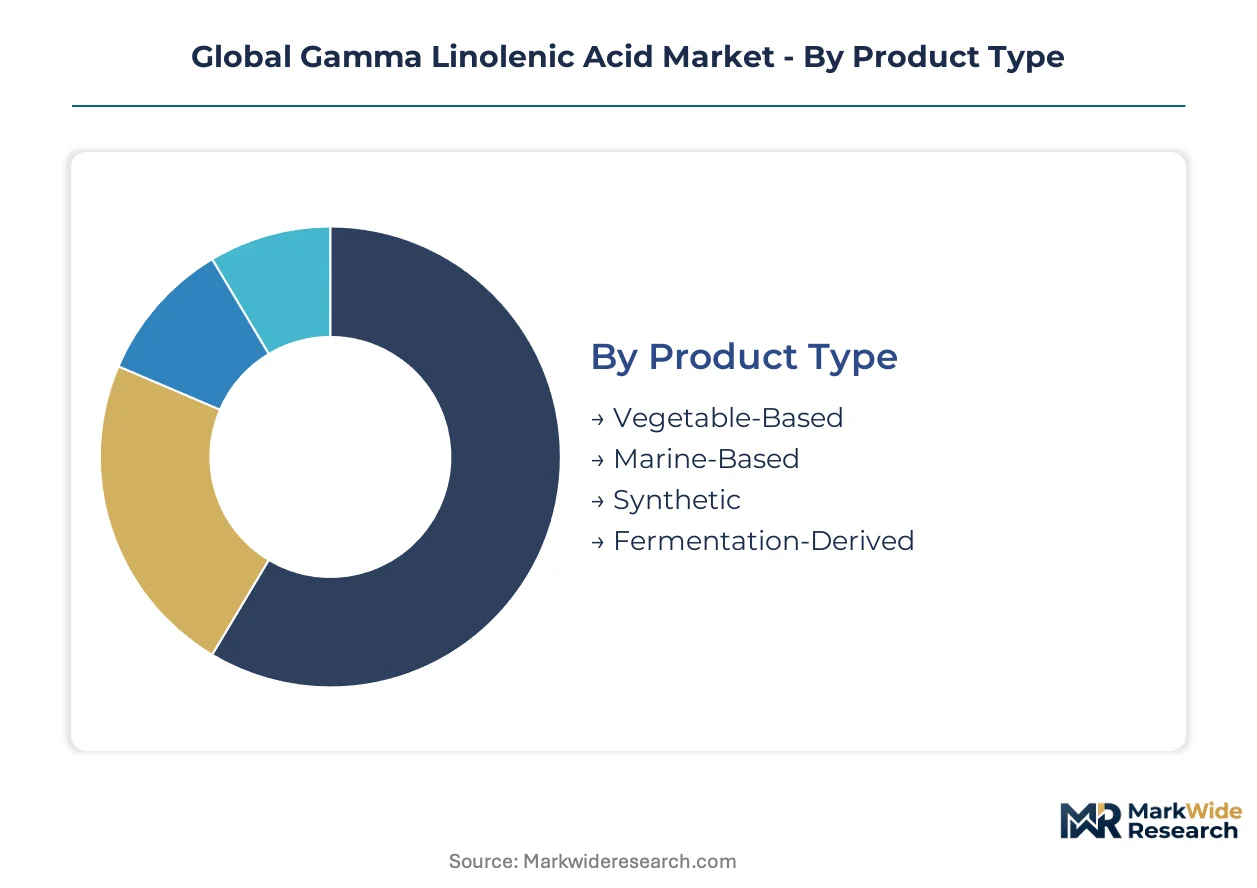
GLA procurement patterns diverge sharply across product origins and formulation formats, with fermentation-derived alternatives displacing botanical sources in pharmaceutical contracts while cosmetic brands prioritize cold-pressed oils for clean-label positioning. Understanding segment boundaries enables suppliers to align purification investments with end-user certification requirements.
Product Type:
Upgrade cycles from evening primrose oil to microbial cell factory platforms are compressing supplier qualification timelines as pharmaceutical manufacturers seek batch-to-batch consistency beyond agricultural volatility.
- Vegetable-Based:Cold-pressed evening primrose and borage seed oils deliver 9-10% GLA purity grades through molecular distillation, dominating organic-certified nutraceutical channels in Germany and Switzerland. Cultivation networks concentrate in China and Argentina, exposing supply to climate volatility and pesticide residue testing burdens under FDA cGMP protocols.
- Fermentation-Derived:Engineered Mortierella alpina and Crypthecodinium cohnii strains produce pharmaceutical-grade GLA in controlled bioreactor facilities, eliminating organic certification dependencies and enabling year-round production consistency. German contract manufacturers are accelerating adoption for atopic dermatitis therapeutics requiring EU EFSA Novel Food dual-certification.
- Marine-Based:Algal extraction platforms remain niche due to omega-3 DHA and EPA co-production economics.
- Synthetic:Petrochemical routes serve cosmetic intermediate applications with REACH-registered supply chains.
Volume placements concentrate in vegetable-based sources; the faster expansion belongs to fermentation-derived platforms.
Form:
Cost tier stratification separates premium softgel pharmaceutical formats from commodity powder bulk ingredients, with liquid oils commanding mid-tier positioning in dermocosmetic channels.
- Softgel:Enteric-coated gelatin capsules dominate pharmaceutical and high-end supplement applications, requiring precise fill weight control and oxidative stability packaging. South Korean and German dermocosmetic brands specify softgel-derived GLA for atopic dermatitis serum formulations commanding premium positioning.
- Oil:Bulk liquid formats serve cosmetic compounders and functional food manufacturers with flexible dosing protocols, though cold-pressed evening primrose oil faces shorter shelf-life constraints versus antioxidant-stabilized alternatives.
- Capsule:Hard-shell gelatin and vegetarian variants target mass-market supplement channels with cost-optimized dosing.
- Powder:Microencapsulated forms enable functional food fortification in bakery and beverage applications.
- Liquid:Dropper bottles and bulk drums serve cosmetic formulation houses requiring custom concentration blending.
Softgel formats capture the highest value per kilogram; powder applications are expanding most quickly in functional food fortification.
Application:
Customer type differentiation separates pharmaceutical procurement teams demanding FDA cGMP traceability from cosmetic formulators prioritizing organic certification narratives.
- Dietary Supplements:Capsule and softgel formats lead absolute consumption volume, with joint health and hormonal balance positioning driving repeat purchase patterns in North American and Japanese markets. Supplement manufacturers increasingly specify fermentation-derived GLA to bypass pesticide residue documentation requirements.
- Cosmetics:GLA-infused serums targeting atopic dermatitis and aging skin conditions command formulation premiums in South Korean and German dermocosmetic channels, with personal care brands emphasizing skin-barrier repair claims backed by prostaglandin E1 precursor science.
- Pharmaceuticals:Anti-inflammatory drug pipelines require prostaglandin E1 precursor applications in rheumatoid arthritis therapeutics, with EU-based contract manufacturers leading volume commitments for dual-certified raw materials.
- Functional Foods:Bakery and beverage fortification remains underpenetrated due to oxidative stability challenges and taste masking requirements.
- Animal Nutrition:Pet dermatology and equine supplements represent emerging demand pockets with specialized dosing protocols.
Pharmaceutical applications deliver the steepest margin expansion; cosmetics is gaining share fastest through premium serum positioning.
End User:
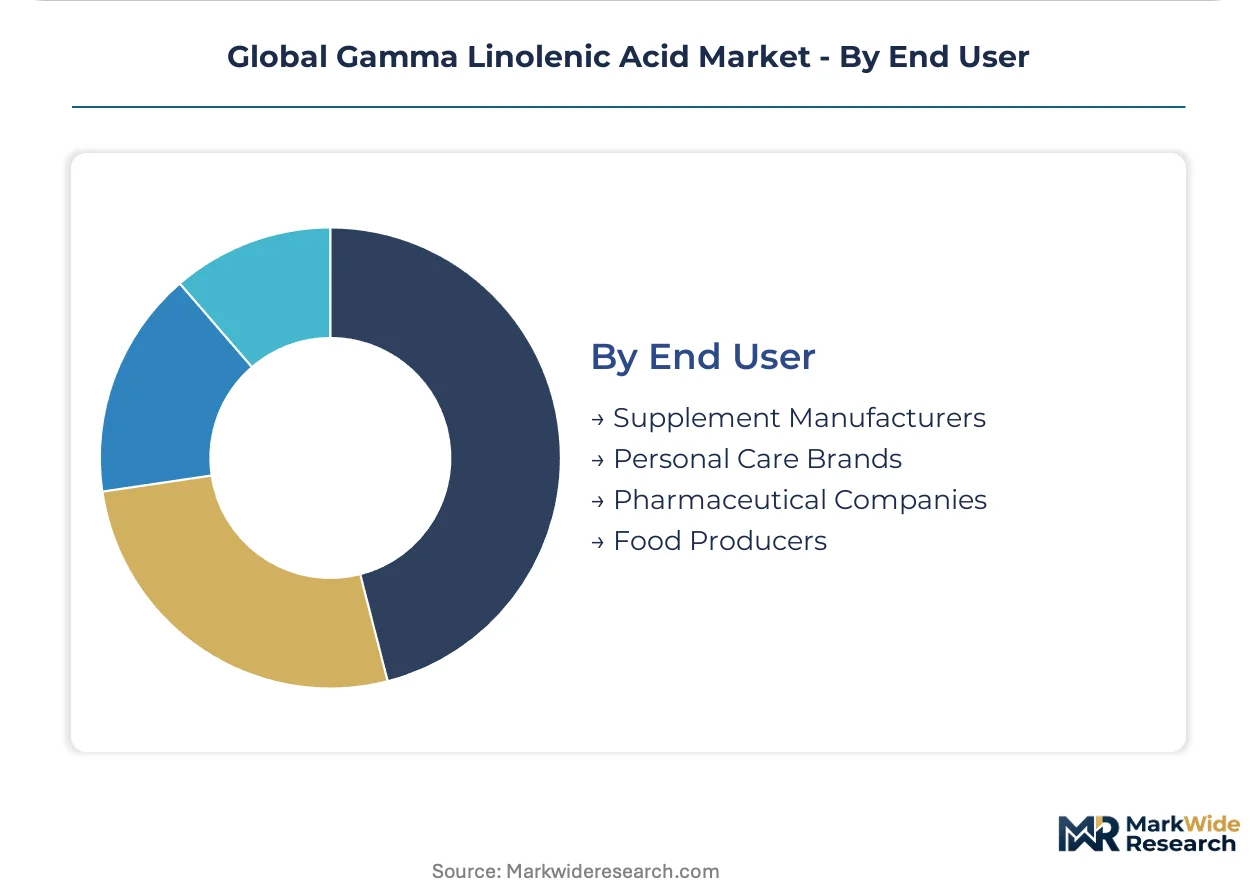
Supply concentration patterns mirror end-user scale requirements, with pharmaceutical companies consolidating procurement around qualified fermentation specialists while personal care brands fragment across botanical extractors.
- Pharmaceutical Companies:Rheumatoid arthritis and atopic dermatitis drug formulators mandate FDA cGMP and EU EFSA Novel Food dual-certification, driving three-to-five year supply agreements with microbial-derived GLA specialists capable of batch-to-batch fatty acid profile consistency.
- Supplement Manufacturers:Contract packagers and branded marketers in Germany and Japan prioritize organic evening primrose oil for clean-label positioning, though fermentation alternatives are penetrating premium lines.
- Personal Care Brands:South Korean and German dermocosmetic houses specify GLA purity grades for serum formulations, with procurement teams balancing organic certification narratives against supply security concerns.
- Food Producers:Functional food manufacturers face formulation challenges with GLA oxidative stability, limiting current penetration to niche bakery and beverage applications.
Pharmaceutical companies anchor the highest volume commitments; personal care brands are diversifying sourcing fastest across botanical and fermentation alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement teams in Germany concentrate the highest volume of GLA demand, driven by contract manufacturing clusters serving EU-wide anti-inflammatory drug pipelines and dermocosmetic export markets.
Germany
Contract manufacturers in Baden-Württemberg and North Rhine-Westphalia dominate pharmaceutical-grade GLA consumption for rheumatoid arthritis therapeutics. EMA oversight and EU EFSA Novel Food dual-certification requirements compress supplier qualification timelines to 18-24 months. The Rhine-Main cluster anchors fermentation-derived GLA adoption, with bioreactor facilities supplying batch-to-batch consistency for atopic dermatitis drug formulations.
United States
FDA cGMP enforcement elevates analytical testing burdens for imported evening primrose oil, driving procurement shifts toward domestic fermentation specialists. The dietary supplements channel concentrates in Utah and California, where contract packagers specify microbial-derived GLA to bypass pesticide residue documentation. Boston-Cambridge pharmaceutical clusters prioritize prostaglandin E1 precursor applications in anti-inflammatory pipelines.
China
Organic evening primrose cultivation networks in Xinjiang and Heilongjiang supply cold-pressed oils to European and Japanese nutraceutical manufacturers. NMPA alignment with international GMP standards is tightening fatty acid profile verification protocols for export-bound batches. The Yangtze River Delta houses specialty oilseed crushing facilities refining 9-10% purity grades for pharmaceutical intermediates.
Japan
MHLW positive list approvals for GLA-containing health claims remain underpenetrated, creating first-mover opportunities for suppliers investing in Japan-specific toxicology dossiers. The Kanto region's functional food manufacturers face formulation challenges with GLA oxidative stability in beverage applications. Osaka-based dermocosmetic brands specify premium GLA purity grades for atopic dermatitis serum formulations commanding 40-60% formulation premiums.
Switzerland
Swissmedic pharmaceutical-grade standards attract fermentation-derived GLA suppliers seeking premium positioning in European rheumatoid arthritis therapeutics. The Basel biotech cluster integrates microbial cell factory platforms into prostaglandin E1 precursor drug development pipelines. Geneva-based specialty chemical distributors anchor REACH-registered synthetic GLA intermediate trade flows serving cosmetic formulators.
Global Gamma Linolenic Acid Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical procurement consolidating around fermentation-derived suppliers while cosmetic brands fragment across botanical extractors. The vendor base organizes into three tiers: integrated chemical conglomerates with global distribution networks, mid-cap fermentation specialists with dual-certification capabilities, and regional oilseed crushers serving organic-certified nutraceutical channels. Strategic moves center on backward integration into specialty oilseed crushing and precision fermentation scale-up using CRISPR-edited microbial strains.
Among integrated chemical and life science conglomerates, DSM-Firmenich, Croda International Plc, and BASF SE exemplify divergent competitive positions. DSM-Firmenich occupies a position within the fermentation-derived tier, leveraging integrated bioreactor capabilities to supply consistent pharmaceutical-grade material. Croda International Plc anchors the specialty lipid processing archetype through backward integration into oilseed crushing and molecular distillation expertise. BASF SE represents the synthetic intermediate pathway, serving cosmetic formulators via REACH-registered supply chains and global distribution infrastructure.
| Leading Market Players |
|---|
| Croda International Plc |
| Merck KGaA |
| DSM-Firmenich |
| Sanmark Corp |
| Thermo Fisher Scientific |
| BASF SE |
| Bioriginal Food & Science Corp. |
| Connoils LLC |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Evening primrose oil futures and organic seed benchmarks cascade through the GLA supply chain into three distinct pricing tiers, with pharmaceutical-grade fermentation-derived material commanding premiums over cold-pressed botanical grades due to batch consistency guarantees and dual-certification compliance costs.
Pricing Analysis
High-volume commodity evening primrose oil trades at thin margins while fermentation-derived pharmaceutical grades capture substantial value premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA cGMP-certified fermentation batches from organic cold-pressed oils and unrefined seed crush intermediates. Cost compression in standard-tier botanical oils is intensifying because pesticide residue testing burdens and climate-driven yield volatility squeeze crusher margins. Supplement manufacturers represent the most price-sensitive buyers, whereas pharmaceutical procurement teams prioritize supply security over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for European pharmaceutical and cosmetic manufacturers, with secondary nodes in Shanghai and Osaka serving Asia-Pacific formulators. Raw material flows concentrate in China, Argentina, and Germany, where organic evening primrose cultivation networks and precision fermentation facilities coexist. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade botanical GLA, as climate volatility in Xinjiang and Heilongjiang threatens seed oil yields. Distribution runs through specialty chemical distributors with REACH-registered synthetic intermediate inventories and direct-to-manufacturer contracts for fermentation-derived material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around dual-certified fermentation specialists, with regulatory timeline compression forcing smaller botanical extractors toward exit or acquisition.
For Market Incumbents: Deepen backward integration into CRISPR-edited yeast strain development and continuous bioreactor processing to collapse production costs and defend margin position against precision fermentation entrants. Secure three-to-five year supply agreements with German and Japanese pharmaceutical manufacturers before regulatory qualification timelines extend further. Priority lever: captive supply of pharmaceutical-grade material with synchronized FDA cGMP and EU EFSA Novel Food dossiers. For New Entrants and Emerging Players: Precision fermentation scale-up using engineered Mortierella alpina strains offers a technology-first wedge into the pharmaceutical contract manufacturing segment, where incumbent botanical suppliers struggle with batch-to-batch consistency. Target Japan's MHLW positive list system for functional food health claims, currently underpenetrated by Western suppliers. Go-to-market angle: Japan-specific toxicology dossiers paired with local distribution partnerships in the Kanto region. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fermentation specialists with existing dual-certification capabilities in Germany and Switzerland, where specialized lipid chemist scarcity constrains new market entrants. Long-term viability over the next decade hinges on microbial cell factory platforms achieving price parity with botanical sources while eliminating agricultural yield dependencies. Signal to watch: CRISPR-edited strain patent filings and continuous bioreactor capacity announcements from European contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-edited Mortierella alpina strains collapse production costs and enable year-round pharmaceutical-grade supply consistency. |
| Dual-Certification Investment | Synchronized FDA cGMP and EU EFSA Novel Food approvals compress supplier qualification timelines to 18-24 months for qualified entrants. |
| Backward Integration into Oilseed Crushing | Captive evening primrose and borage seed processing secures organic-certified supply chains for clean-label cosmetic positioning. |
| Japan-Specific Toxicology Dossiers | MHLW positive list approvals for GLA-containing health claims unlock first-mover advantage in underpenetrated functional food channels. |
| Long-Term Supply Agreements | Three-to-five year contracts with German pharmaceutical manufacturers lock in batch-to-batch consistency requirements and displace spot purchasing. |
Research Methodology
Trade databases, customs records, and EFSA Novel Food submission filings formed the secondary backbone, supplemented by primary interviews with fermentation facility directors, pharmaceutical procurement managers, regulatory affairs specialists at specialty chemical distributors, and cosmetic formulation scientists. Bottom-up volume estimates derived from oilseed crushing capacity and bioreactor utilization rates were cross-validated against top-down pharmaceutical and nutraceutical demand projections.
Bottom-up modeling tracked GLA consumption across product origin tiers, formulation formats, and end-user segments, while top-down analysis anchored total addressable market sizing to anti-inflammatory drug pipeline disclosures and dermocosmetic brand expansion plans. CAGRs were derived from regression analysis of historical procurement patterns and projected fermentation capacity additions across the analysis window. Industry-specific inputs included EMA oversight timelines for rheumatoid arthritis therapeutics and South Korean atopic dermatitis serum formulation premiums.
Several conditions sit outside the modeled scope, including potential algal DHA and EPA substitution acceleration, geopolitical disruption to Argentine evening primrose exports, and breakthroughs in synthetic biology platforms beyond CRISPR-edited microbial strains. Forecasts reflect documented assumptions around regulatory synchronization timelines and fermentation yield improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Germany Food Emulsifiers Market