
 Pulse Protein Market | 2026-2036
Pulse Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Pulse Protein Market Outlook
EU Green Deal legislation is expanding the compliance burden for imported pulse ingredients, forcing suppliers to document carbon intensity and deforestation-free sourcing across their supply chains. Roquette Frères leverages its vertical integration from field to isolate to sustain margin control amid these traceability mandates. Cargill anchors North American supply through its processing footprint and farmer contracting networks. ADM competes on scale, operating multiple pulse fractionation facilities that service both food and nutritional supplement channels.
Pulse protein denotes the concentrated or isolated protein fraction extracted from dried legume seeds through wet or dry fractionation, typically achieving protein contents ranging from 50% to 90% depending on processing intensity. Its primary commercial purpose centers on replacing animal-derived and soy proteins in formulated foods where allergen reduction, clean-label positioning, or carbon footprint claims drive purchasing decisions. Pea protein isolates lead product type volume owing to their functional emulsification and neutral flavor profile, while lentil protein differentiates in premium positioning through superior amino acid completeness. Bakery products application represents the fastest-growing structural segment as manufacturers reformulate for protein fortification without compromising crumb structure or shelf stability.
FDA oversight of plant protein nutrient content claims and USDA BioPreferred program specifications shape product positioning and label compliance in the United States, while EFSA novel food assessments govern new pulse protein introductions across European markets. REACH chemical registration requirements and evolving EU deforestation regulation extend compliance obligations to solvent residues and geographic sourcing documentation. Stakeholders must monitor how tightening protein quality scoring methodologies and emerging carbon border adjustments will reshape procurement priorities and supplier qualification timelines.
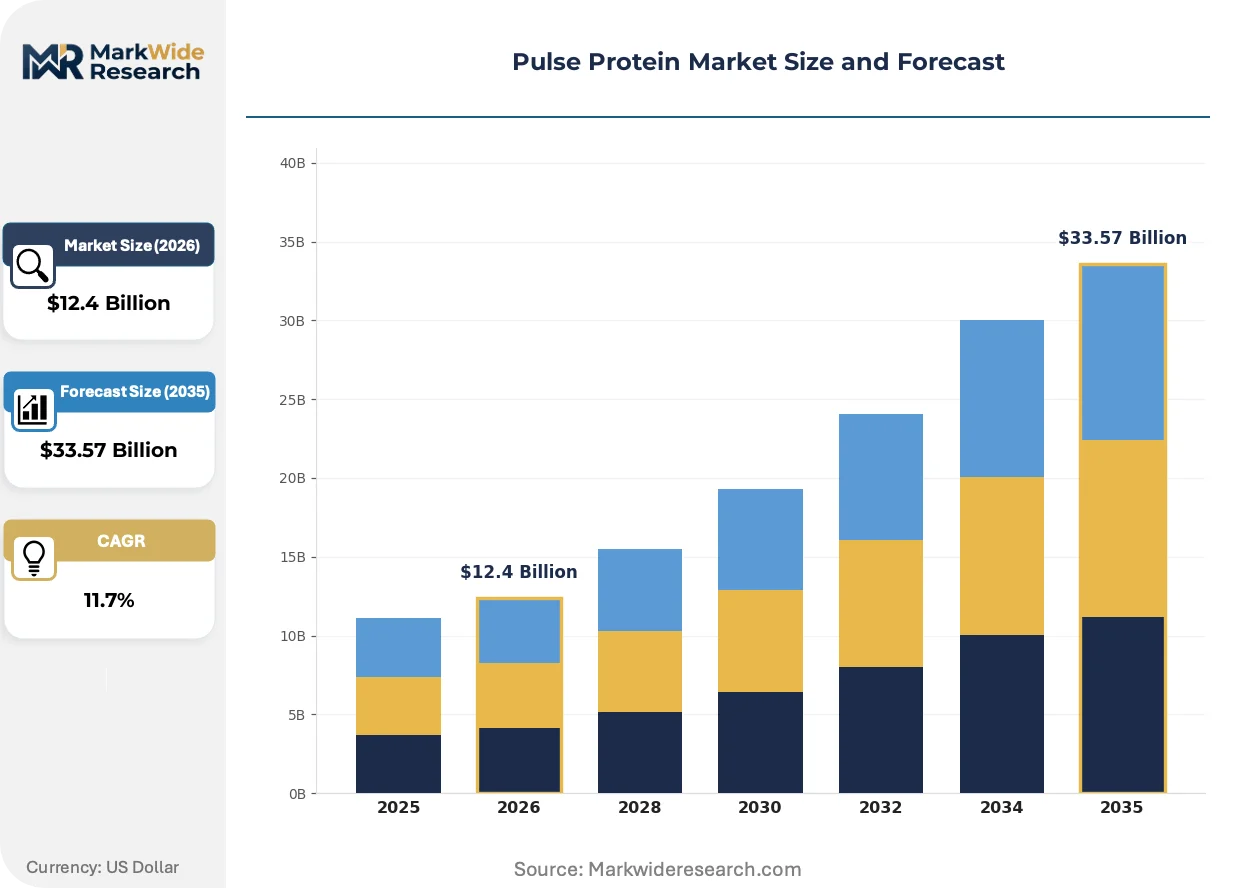
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing pulse protein suppliers to restructure sourcing documentation and fractionation footprints, compressing margins for non-integrated processors while advantaging those with captive field-to-isolate operations.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation traceability for imported pulses is accelerating supplier consolidation toward vertically integrated operators who control farm-level data.
- Sports nutrition reformulation:Clean-label protein fortification in ready-to-mix powders is displacing soy and dairy concentrates across North American and European athletic nutrition channels.
- Fermentation-assisted fractionation:Novel enzymatic pre-treatments are improving protein yield from lentil and fava bean streams, expanding raw material flexibility beyond yellow pea dominance.
Market Restraints
- Input cost volatility:Yellow pea prices fluctuate with Canadian prairie weather patterns and export demand from Asian feed markets, destabilizing isolate cost structures.
- Supply concentration risk:Fractionation capacity clusters in France, Canada, and the Netherlands, creating single-point vulnerability for European and North American food manufacturers.
- Functional limitations:Pulse protein isolates exhibit inferior gelling versus egg and dairy proteins, restricting penetration in high-hydration bakery and confectionery applications.
Strategic Opportunities
- Underpenetrated German bakery sector:Traditional wheat-dominant formulations in artisanal and industrial bread channels present white space for protein fortification without crumb degradation.
- USDA BioPreferred program expansion:Federal procurement preferences for biobased ingredients are opening institutional foodservice channels previously locked by commodity dairy contracts.
- Precision fermentation hybridization:Combining extracted pulse proteins with fermentation-derived flavor masking is converging with clean-label positioning to unlock savory applications.
Industry Challenges
- Specialized protein chemist scarcity:Formulation science expertise at the intersection of plant protein functionality and food matrix stability commands premium compensation and extended recruitment timelines.
- EFSA novel food dossier costs:Lentil and fava protein isolates face multi-year assessment periods and six-figure regulatory investment before European commercialization.
- Legacy dairy equipment incompatibility:Existing spray-drying and extrusion assets require retrofitting for pulse protein's distinct thermal behavior and powder flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulse Protein Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.57 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lentils, Chickpeas, Peas, Beans Application: Food & Beverage, Nutritional Supplements, Animal Feed, Bakery Products End User: Households, Restaurants, Food Manufacturers, Fitness Centers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Roquette Frères, Cargill, Ingredion, AGT Food and Ingredients, ADM, Axiom Foods, The Scoular Company, Emsland Group, PURIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulse Protein Market Strategic Shifts
Fractionation technology and regulatory traceability mandates are rewriting competitive positioning in pulse protein supply chains. Three developments warrant particular attention from procurement and R&D functions.
Air classification combined with electrostatic separation is converging with dry fractionation economics to enable regional processing of lower-volume pulse varieties. Mid-scale food manufacturers in the Netherlands and Denmark are adopting these systems to reduce dependence on imported isolates. The technology is compressing minimum viable scale thresholds and fragmenting supply concentration.
REACH chemical registration requirements for novel extraction solvents are extending compliance timelines for new fractionation entrants. Industrial consequence includes preferential qualification of established processors with existing dossier libraries. European sports nutrition brands are responding by locking multi-year supply contracts with REACH-compliant French and Dutch isolators.
Direct farm contracting is displacing spot-market pulse procurement among major isolate producers. Ingredient buyers now specify carbon intensity and deforestation-free verification as contractual terms. This pattern is most visible in French and Canadian supply chains where processor-farmer partnerships predate regulatory mandates.
Pulse Protein Market Segmentation
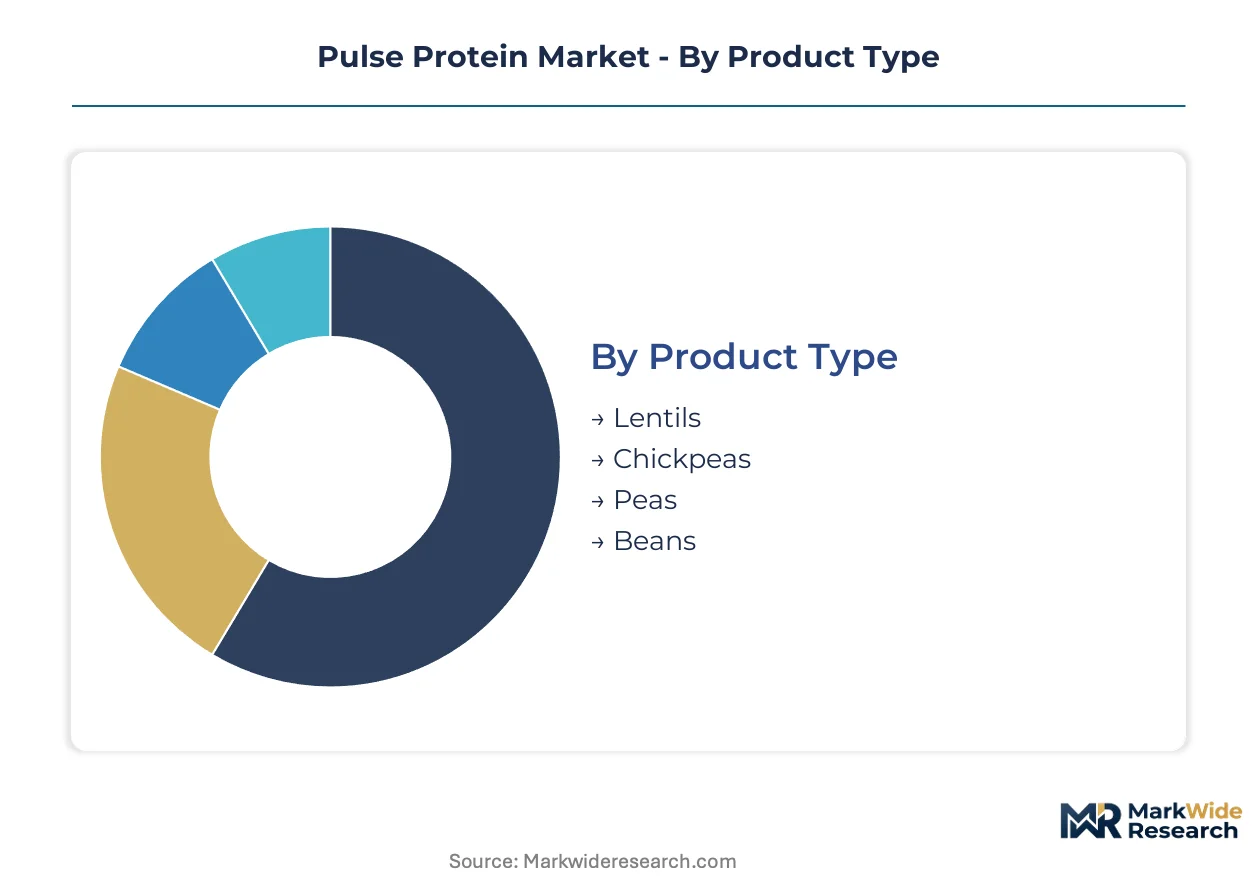
Pulse protein purchasing decisions pivot on functional performance in target matrices, regulatory compliance for label claims, and supply chain traceability documentation. Manufacturers prioritize isolates with proven emulsification stability and neutral flavor profiles for clean-label reformulation.
Product Type:
Formulation scientists select pulse varieties based on amino acid completeness, protein yield from fractionation, and gelling behavior in target food matrices.
- Peas:Yellow pea isolates achieve 80-90% protein concentration through wet fractionation and exhibit superior emulsification stability in high-shear processing. Sports nutrition manufacturers in the United States specify pea protein for ready-to-mix powders due to its neutral flavor and FDA-recognized GRAS status.
- Lentils:Red and green lentil proteins deliver more complete essential amino acid profiles than pea, though fractionation yields remain 15-20% lower. Premium positioning in European sports nutrition and clinical nutrition applications commands price premiums for lentil isolates with documented low-FODMAP certification.
- Chickpeas:Chickpea protein concentrates retain functional starch fractions that improve water-binding in bakery applications without compromising crumb structure.
- Beans:Fava bean protein isolates from French and Dutch processors are gaining traction in savory applications through fermentation-assisted flavor masking technologies.
Pea protein leads on scale; lentil protein leads on momentum.
Application:
End-use selection determines protein specification requirements, from isolate purity levels to microbial testing protocols and shelf-life stability targets.
- Bakery Products:Protein fortification in artisanal and industrial bread channels demands isolates with controlled particle size distribution to prevent gluten network disruption. German and Dutch manufacturers are reformulating wheat-dominant formulations for protein enrichment without volume loss or staling acceleration.
- Nutritional Supplements:Ready-to-mix powders and ready-to-drink beverages require instantized isolates with dispersibility below 30 seconds and minimal chalking. North American athletic nutrition brands are displacing soy and dairy concentrates with pulse-based alternatives for allergen reduction.
- Food & Beverage:Meat analogues and dairy alternatives utilize high-gelling pulse protein concentrates for texture replication in extruded and shear-cell processed formats.
- Animal Feed:Feed-grade pulse protein meals from fractionation byproducts serve aquaculture and pet food channels with lower purity requirements but stringent mycotoxin thresholds.
Bakery applications are climbing the fastest; nutritional supplements retain the largest revenue base.
End User:
Procurement scale and technical sophistication vary dramatically across buyer types, from commodity spot purchasing to multi-year contracted supply with embedded traceability requirements.
- Food Manufacturers:Industrial buyers specify carbon intensity documentation and deforestation-free verification as contractual terms under EU Green Deal compliance mandates. Direct farm contracting with French and Canadian processors is displacing spot-market procurement.
- Restaurants:Foodservice operators in institutional and chain channels prioritize cost-stable supply with USDA BioPreferred certification for federal procurement eligibility.
- Fitness Centers:On-site retail of branded protein supplements drives demand for single-serve packaging and clean-label positioning with minimal ingredient lists.
- Households:Direct-to-consumer purchasing through online retail channels concentrates in organic-certified and non-GMO verified isolates with transparent supply chain storytelling.
Food manufacturers lead on procurement volume; fitness centers lead on brand premiumization.
Distribution Channel:
Channel selection determines margin capture, customer education requirements, and inventory velocity for perishable or temperature-sensitive isolate formats.
- Direct Sales:Processor-to-manufacturer relationships lock multi-year supply contracts with REACH-compliant isolators, securing volume commitments and price stability for European sports nutrition brands.
- Online Retail:E-commerce platforms enable ingredient transparency and subscription purchasing for specialty isolates with organic or regenerative agriculture certification.
- Supermarkets:Mass retail distribution demands standardized packaging formats and competitive unit economics that favor high-volume pea protein concentrates over premium lentil alternatives.
- Health Stores:Specialty retail channels support premium positioning for novel pulse varieties with functional claims around digestive tolerance or amino acid completeness.
Direct sales leads on contract value; online retail leads on customer acquisition velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and protein fractionation engineers concentrate in the Canadian prairies, northern France, and the Dutch processing corridor, anchoring supply-side capabilities for pulse protein manufacturing.
United States
Sports nutrition brands in California and Colorado drive isolate demand for clean-label protein fortification. The USDA BioPreferred program steers federal procurement toward biobased ingredients, expanding institutional foodservice channels. Minneapolis and Chicago house major processor headquarters and fractionation R&D facilities serving North American bakery and beverage manufacturers.
Canada
Yellow pea production in Saskatchewan and Manitoba supplies the dominant raw material stream for global isolate production. Canadian Grain Commission standards and export documentation requirements shape quality protocols for international shipments. Port of Vancouver and Thunder Bay processing clusters handle bulk fractionation for European and Asian markets.
France
Roquette Frères anchors European supply through field-to-isolate vertical integration in the Hauts-de-France region. The EU Green Deal's carbon border adjustment mechanism and deforestation regulation tighten compliance thresholds for imported pulses. Lille and Paris basin facilities specialize in high-purity isolates for sports nutrition and clinical nutrition applications.
Netherlands
Specialized fractionation equipment manufacturers and mid-scale dry fractionation adopters cluster around Eindhoven and Wageningen. REACH chemical registration requirements for novel extraction solvents extend qualification timelines for new market entrants. Dutch food-tech incubators pilot air classification systems for regional pulse protein processing.
Germany
Industrial bakers in Bavaria and North Rhine-Westphalia reformulate wheat-dominant formulations for protein enrichment without volume loss. Germany's national sustainability labeling requirements and supply chain due diligence laws pressure ingredient sourcing transparency. Cologne and Hamburg serve as distribution hubs for Central European food manufacturers.
Pulse Protein Market Competitive Environment
The competitive structure tilts toward integrated agribusiness conglomerates with captive field operations and established fractionation footprints. Mid-scale specialists compete on novel variety development and clean-label certification, while equipment-technology hybrids enable regional processing decentralization. Dominant competitive moves include backward integration into farmer contracting networks and multi-year supply contract locking with REACH-compliant isolators.
Among French integrated processors, Roquette Frères exemplifies the field-to-isolate archetype with upstream control over raw material traceability. Cargill and ADM represent North American scale-driven competitors operating multiple fractionation facilities across food and nutritional supplement channels. AGT Food and Ingredients occupies a position within the Canadian pulse-specialist tier, anchoring prairie-origin supply for international markets.
| Leading Market Players |
|---|
| Roquette Frères |
| Cargill |
| Ingredion |
| AGT Food and Ingredients |
| ADM |
| Axiom Foods |
| The Scoular Company |
| Emsland Group |
| PURIS |
| Others |
Value Chain & Pricing Dynamics
Family-owned French processors with multi-generational farmer relationships anchor premium pricing discipline through captive field contracting, while private-equity-rolled-up North American specialists compete on spot-market agility at thinner margins. This ownership bifurcation shapes how carbon intensity documentation and deforestation-free verification flow through contract structures versus transactional purchasing.
Pricing Analysis
Bundled field-to-isolate contracts with embedded traceability documentation command substantial premiums over unbundled spot-market isolate purchases without farm-level data. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant European isolators from mid-scale dry fractionation adopters and feed-grade byproduct meal suppliers. Pricing pressure stems from Canadian prairie weather volatility destabilizing yellow pea input costs. Food manufacturers with EU Green Deal compliance mandates show lowest price sensitivity, while institutional foodservice operators prioritize cost-stable supply.
Supply Chain Analysis
Ocean freight rates from Vancouver to Rotterdam and overland trucking across the Canadian prairies constitute meaningful delivered cost components for isolate shipments. Supply concentrates in France, Canada, and the Netherlands, with fractionation capacity clustering around Roquette's Hauts-de-France operations, Saskatchewan-Manitoba processing hubs, and the Dutch corridor near Eindhoven. Raw material streams draw from yellow pea, red lentil, and fava bean cultivation zones. Single-source vulnerability threatens European manufacturers dependent on French isolators for REACH-compliant supply. Distribution runs through direct processor-to-manufacturer contracts locking multi-year volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pulse protein market reads as a late-cycle quality story where specification premiums widen as bakery and sports nutrition formulators prioritize amino acid completeness and carbon documentation over commodity pricing. German artisanal bread channels and clinical nutrition applications demonstrate this demand-shift toward premium specifications most acutely.
For Market Incumbents: Deploy backward integration into farmer contracting networks to secure geolocation traceability data ahead of tightening EU Deforestation Regulation enforcement. Incumbents should retrofit legacy spray-drying assets for pulse protein thermal behavior while locking multi-year supply contracts with REACH-compliant isolators to defend against mid-scale dry fractionation entrants eroding regional supply concentration. For New Entrants and Emerging Players: Begin with air classification systems for regional processing of lower-volume pulse varieties in underpenetrated German bakery channels where wheat-dominant formulations present white space for protein fortification. Precision fermentation hybridization partnerships with flavor masking specialists offer a defensible go-to-market angle for savory applications without competing directly on isolate scale. For Investors and Strategic Acquirers: Food and beverage conglomerates with existing plant protein portfolios are the most active acquirer in this space, targeting mid-scale specialists with novel variety development capabilities and clean-label certification infrastructure. The long-term viability window favors processors with demonstrated EFSA novel food dossier completion and captive supply chain control. Watch for carbon border adjustment mechanism implementation timing as the critical inflection indicator for procurement priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Contracting | Roquette's field-to-isolate model secures margin control under EU traceability mandates. |
| EFSA Novel Food Dossier Investment | Lentil and fava protein commercialization in Europe requires six-figure regulatory commitment. |
| Air Classification Technology Adoption | Dutch and Danish mid-scale manufacturers reduce import dependence through regional processing. |
| REACH Compliance Certification | European sports nutrition brands lock supply contracts with compliant French and Dutch isolators. |
| Precision Fermentation Hybridization | Fermentation-derived flavor masking unlocks savory applications for fava bean isolates. |
Study Parameters
Bottom-up bakery and sports nutrition application modeling reconciled against top-down fractionation capacity tracking forms the analytical core of this study. Primary interviews with formulation scientists at North American and European food manufacturers, procurement leads at sports nutrition brands, plant managers at Canadian and French processing facilities, and regulatory affairs specialists navigating EFSA and FDA pathways were validated against secondary sources including EU Green Deal implementation documents, FDA GRAS notifications, Canadian Grain Commission export data, and REACH chemical registration databases.
Historical trendline analysis of isolate pricing and volume trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include pulse variety, application matrix, protein purity tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Industry-specific forecast inputs incorporated Canadian prairie weather pattern correlations and EFSA novel food approval velocity assumptions.
Several conditions sit outside the modeled scope, including geopolitical trade disruption scenarios, breakthrough alternative protein technologies, and accelerated carbon border adjustment mechanism implementation. Forecasts reflect documented assumptions about regulatory enforcement timing and farmer adoption of traceability systems. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Global Soluble Dietary Fibers Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Soy Isoflavones Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
North America Memory Supplements Market